
 Europe Car Wash Market | 2026-2036
Europe Car Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Car Wash Market Insights
Aftermarket service revenue from water reclamation and chemical recycling is rewriting profit allocation across the European car wash value chain. WashTec AG leverages its German engineering base to dominate high-volume tunnel installations across Central Europe. Istobal S.A. anchors Mediterranean markets with specialized corrosion-resistant equipment designed for coastal salinity conditions. Alfred Kärcher SE & Co. KG extends its consumer brand recognition into commercial fleet contracts through modular system architectures.
Europe car wash denotes mechanized or semi-automated vehicle exterior and interior cleaning installations utilizing pressurized water jets, biodegradable surfactants, and conveyor or gantry-based material handling systems, typically operating at pressures between 40 and 150 bar depending on wash stage and vehicle sensitivity. The primary purpose is restoring vehicle surface cleanliness while minimizing water consumption and effluent discharge to comply with municipal environmental standards. Tunnel wash systems capture the largest installed base across the region due to throughput economics at highway-adjacent locations, while touchless wash technology leads growth as ceramic-coated and wrapped vehicles proliferate among premium private owners. Mobile wash applications serving corporate fleets represent the fastest-expanding segment as last-mile delivery operators centralize hygiene protocols under ESG reporting frameworks.
The EU Green Deal and REACH chemical registration requirements are tightening surfactant formulations and wastewater discharge thresholds, compelling operators to invest in closed-loop filtration or risk permit revocation in regulated watersheds. Germany's KBA and France's environmental prefectures enforce divergent technical inspection standards for automated systems, fragmenting equipment certification pathways across borders. Stakeholders must monitor pending CSRD disclosure rules that will mandate Scope 3 water intensity reporting from fleet service providers, reshaping procurement criteria for multi-site wash contracts.
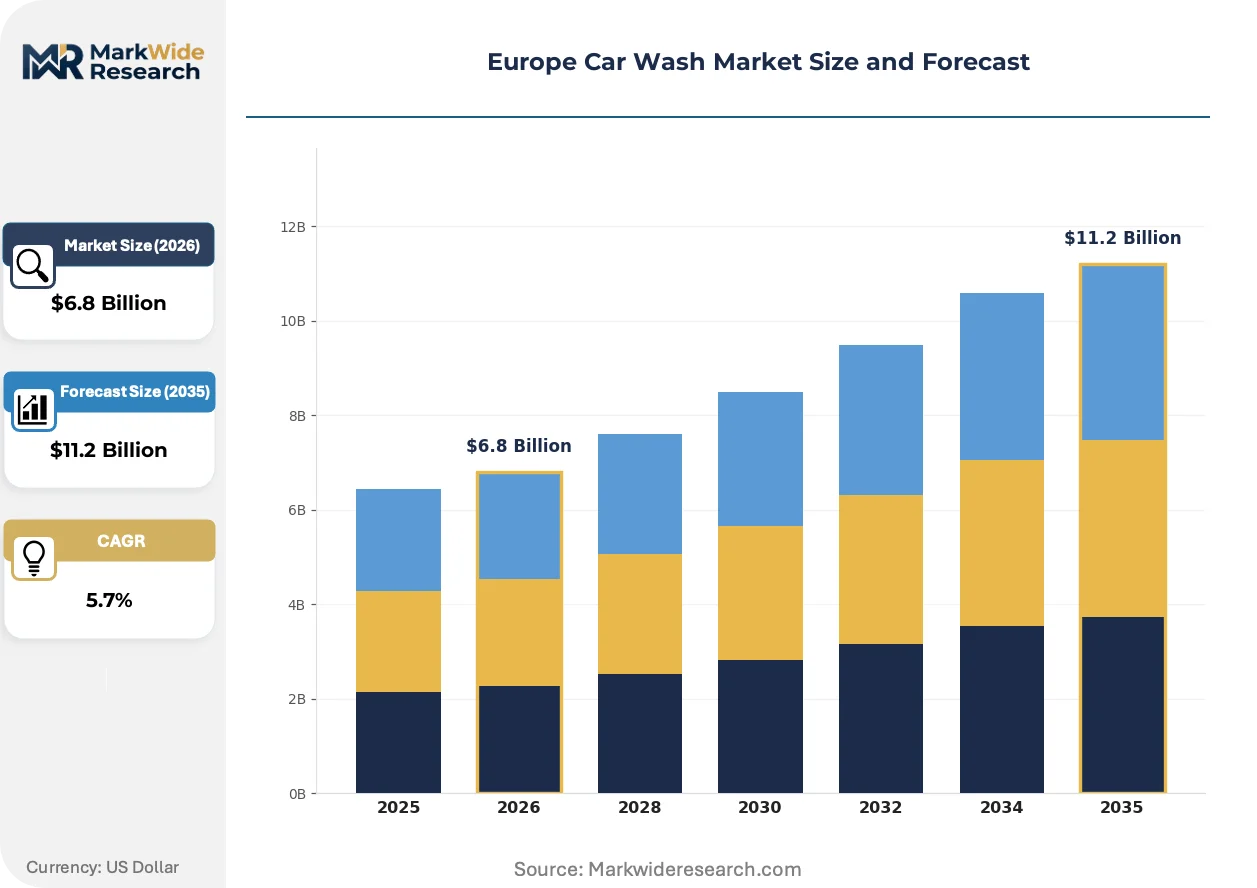
Market Dynamics
The EU Green Deal's water-recovery mandates are forcing a wholesale retrofit cycle across existing tunnel installations, concentrating capital deployment in Germany, France, and the Benelux corridor where municipal discharge thresholds are tightest.
Growth Catalysts
- Fleet electrification hygiene protocols:Last-mile delivery operators across the Netherlands and Belgium now mandate weekly exterior washes to protect battery thermal management systems from road salt accumulation.
- REACH-compliant surfactant innovation:Biodegradable foaming agents certified under ECHA registration pathways are unlocking contract renewals with municipal fleet operators previously blocked by chemical discharge permits.
- High-throughput touchless technology:Ceramic-coated vehicle owners in urban Germany are rejecting brush-based systems, pulling investment toward gantry-based laser-guided wash architectures.
Market Restraints
- Steel and aluminum input volatility:Conveyor system fabricators face margin compression from energy-intensive metal pricing swings tied to EU carbon border adjustment mechanisms.
- Permit fragmentation:France's environmental prefectures enforce divergent technical inspection standards from Germany's KBA, forcing dual certification costs on cross-border equipment suppliers.
- Water scarcity infrastructure gaps:Southern Spain and Italy lack municipal reclaimed water hookups, blocking closed-loop system economics despite regulatory pressure.
Strategic Opportunities
- Poland and Czech Republic fleet penetration:Corporate sustainability reporting under CSRD disclosure rules is extending wash contract centralization into Central European logistics hubs previously served by fragmented hand-wash operators.
- Mobile wash unit deployment:Hydrogen fuel cell-powered mobile rigs are emerging as a channel innovation for port authorities in Rotterdam and Hamburg seeking to decarbonize vessel-to-shore vehicle cleaning.
- EU AI Act compliance automation:Computer vision systems for damage detection pre-wash are creating a regulatory tailwind as operators seek to document condition for insurance-integrated service bundles.
Industry Challenges
- Mechatronics technician scarcity:Automated tunnel maintenance requires PLC programming skills that vocational pipelines in Eastern Europe have not scaled to match installation growth.
- Legacy chemical inventory stranding:Operators holding bulk surfactant stocks face write-downs as REACH substance restriction timelines accelerate reformulation deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Car Wash Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Service, Tunnel Wash, Mobile Wash, Touchless Wash Application: Private Vehicles, Commercial Fleets, Motorcycles, Electric Vehicles Technology: Waterless Cleaning, Automated Systems, High-Pressure Wash, Foam Applicators Customer Type: Individual Owners, Corporate Clients, Fleet Managers, Car Dealerships |
| Companies Covered | WashTec AG, Alfred Kärcher SE & Co. KG, Istobal S.A., Otto Christ AG, Tammermatic Oy, Daifuku Group, Green Steam International Sp. z o.o., GoWashMyCar Ltd., The London Carwash Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Car Wash Market Trends and Innovations
Water reclamation technology is collapsing the traditional separation between capital equipment and recurring service revenue, rewiring how operators monetize installed base across the European car wash value chain.
Closed-loop ceramic membrane filtration is collapsing freshwater intake requirements at high-volume tunnel sites. Fleet operators in Germany's Rhine-Ruhr corridor are adopting these systems ahead of municipal permit renewals. The technology is collapsing the payback period for water infrastructure investment from seven years to under four.
CSRD disclosure rules will mandate Scope 3 water intensity reporting from fleet service providers starting with the 2025 reporting cycle. Multi-site wash contracts are now requiring granular consumption telemetry that legacy meter architectures cannot deliver. Premium logistics operators in France are responding by centralizing procurement with vendors offering ISO 14001-certified environmental management systems.
Subscription-based wash access is displacing per-transaction pricing at highway-adjacent locations. Younger vehicle owners in Belgium and the Netherlands prefer app-managed unlimited plans that bundle interior vacuuming and windshield fluid top-off. This behavioral pivot is most visible among corporate fleet managers seeking to flatten variable cleaning costs under fixed ESG budget lines.
Europe Car Wash Market Segmentation
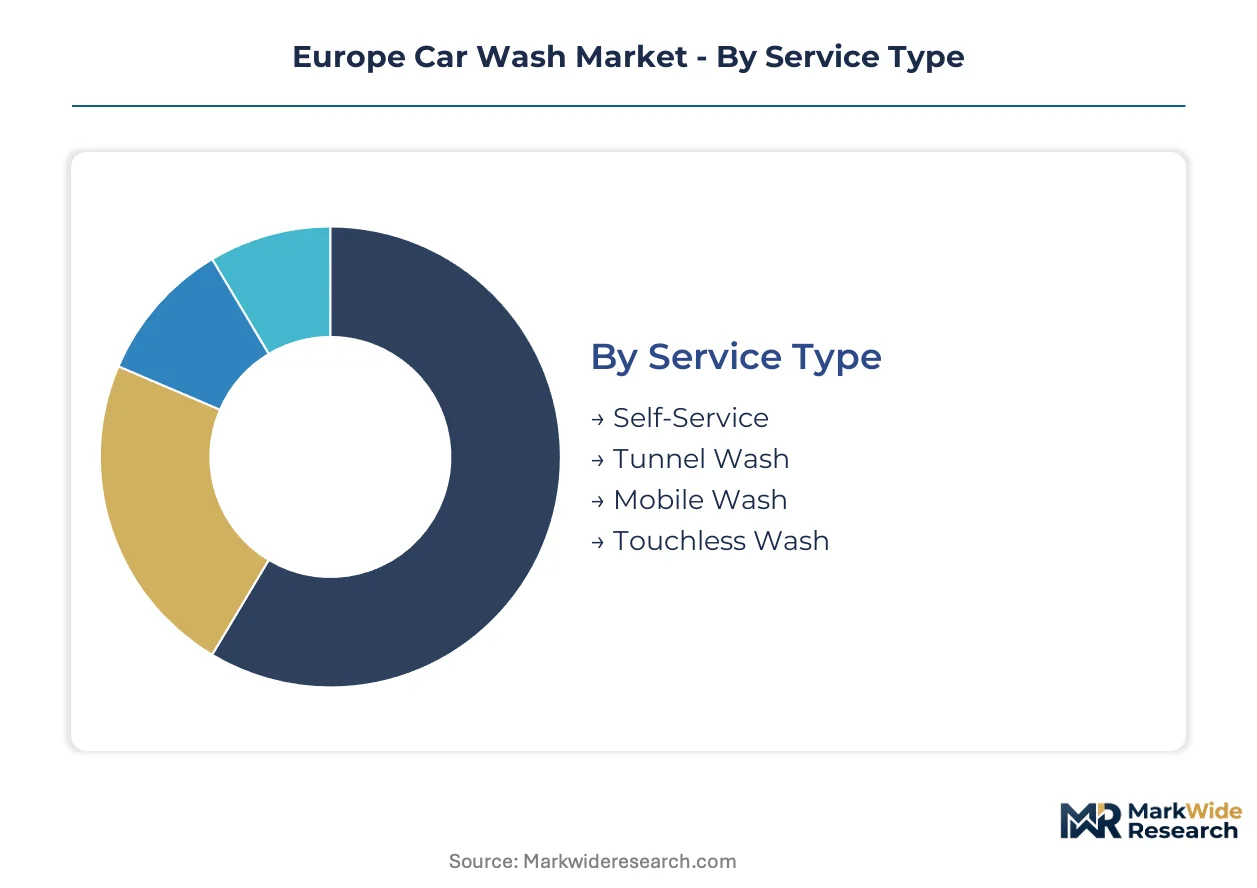
Segmentation in the European car wash market reveals how divergent customer economics and regulatory pressures split capital deployment across service formats. Understanding these fault lines clarifies why tunnel infrastructure dominates highway corridors while mobile formats penetrate dense urban cores.
Service Type:
Mature formats with installed base advantages compete against emerging configurations that bypass real estate constraints.
- Tunnel Wash:Conveyor-based systems process vehicles through sequential wash stages at 40-150 bar pressure ranges. Fleet operators along Germany's Autobahn network and France's A1 corridor favor these installations for throughput economics under corporate sustainability contracts. The format struggles with water-recovery retrofit costs mandated by EU Green Deal timelines.
- Touchless Wash:Gantry-mounted laser-guided architectures eliminate brush contact through precision jet targeting. Ceramic-coated vehicle owners in urban Germany and the Netherlands reject abrasive systems, pulling investment toward this technology despite higher per-wash chemical consumption.
- Self-Service:Coin-operated bay configurations persist in Southern Spain and Italy where labor costs and water scarcity infrastructure gaps block automated alternatives.
- Mobile Wash:Hydrogen fuel cell-powered rigs serve port authorities in Rotterdam and Hamburg seeking to decarbonize vessel-to-shore vehicle cleaning without fixed infrastructure.
Tunnel Wash handles the majority of throughput; Touchless Wash is expanding most quickly on share.
Application:
Vehicle electrification and fleet centralization are reordering demand concentration across use cases.
- Commercial Fleets:Last-mile delivery operators across the Netherlands and Belgium mandate weekly exterior washes to protect battery thermal management systems from road salt accumulation. CSRD disclosure rules are consolidating procurement under multi-site contracts with ISO 14001-certified vendors.
- Electric Vehicles:Wrapped and ceramic-coated EV surfaces require pH-neutral surfactant formulations that brush-based systems compromise. Premium owners in Germany's Rhine-Ruhr corridor drive touchless format adoption.
- Private Vehicles:Individual owners in Belgium and the Netherlands prefer subscription-based app-managed plans bundling vacuuming and fluid top-off.
- Motorcycles:Specialized low-pressure bays serve two-wheeler owners in Mediterranean markets with corrosion-resistant equipment specifications.
Commercial Fleets generate the highest contract value concentration; Electric Vehicles are gaining share fastest among application segments.
Technology:
Water intensity regulations and chemical registration requirements fragment competitive advantage across technical approaches.
- Automated Systems:PLC-controlled conveyor and gantry architectures integrate closed-loop ceramic membrane filtration. Germany's KBA certification requirements and France's divergent environmental prefecture standards force dual compliance pathways on equipment suppliers.
- Waterless Cleaning:Biodegradable surfactant formulations certified under ECHA REACH pathways unlock municipal fleet contracts previously blocked by discharge permits.
- High-Pressure Wash:40-150 bar jet systems remain standard for tunnel stage differentiation but face energy cost pressure from EU carbon border adjustment mechanisms.
- Foam Applicators:Precision dosing systems reduce chemical waste at high-volume sites in the Benelux corridor where municipal discharge thresholds are tightest.
Automated Systems anchor capital deployment; Waterless Cleaning shows the steepest expansion trajectory under tightening discharge rules.
Customer Type:
Procurement centralization under ESG reporting frameworks is collapsing the fragmented hand-wash operator landscape.
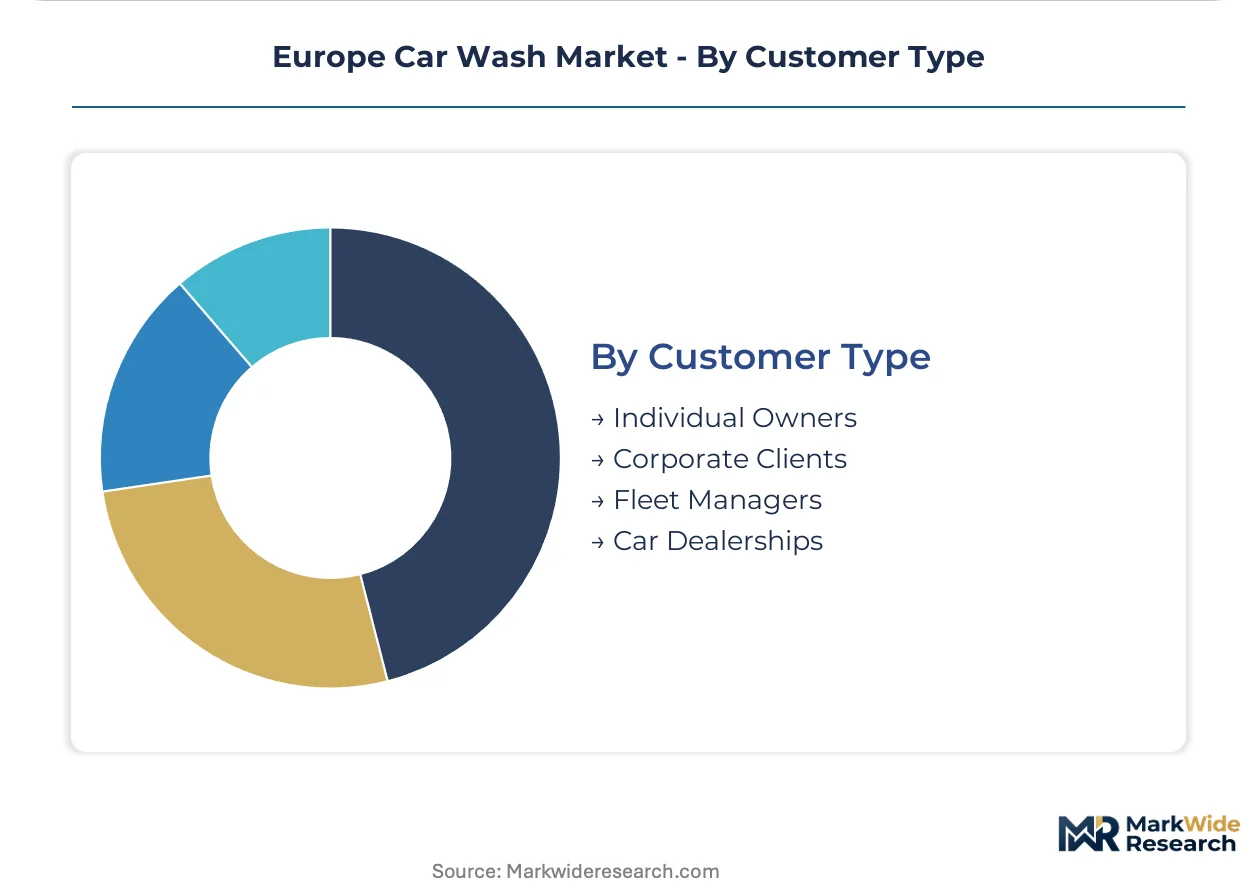
- Fleet Managers:Corporate sustainability reporting under CSRD disclosure rules extends wash contract centralization into Central European logistics hubs. These stakeholders require granular consumption telemetry that legacy meter architectures cannot deliver.
- Corporate Clients:Multi-site operators in France flatten variable cleaning costs under fixed ESG budget lines through subscription-based unlimited wash plans.
- Individual Owners:Younger vehicle owners in Belgium and the Netherlands prefer app-managed access over per-transaction pricing.
- Car Dealerships:Pre-delivery preparation contracts concentrate in Germany's manufacturing belt with damage detection documentation requirements under EU AI Act compliance automation.
Fleet Managers control the largest contract volumes; Corporate Clients are consolidating procurement fastest under disclosure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across the continent. Fleet operators in Germany and the Netherlands absorb premium pricing for certified water-recovery systems, while individual owners in Southern Europe remain tethered to low-cost hand-wash alternatives.
Germany
Fleet centralization along the Rhine-Ruhr corridor drives tunnel wash throughput volumes. KBA certification requirements enforce divergent technical inspection standards that fragment equipment procurement across federal states. WashTec AG anchors high-volume installations in Stuttgart and Munich manufacturing belts.
France
Environmental prefectures impose municipal discharge thresholds that accelerate closed-loop filtration adoption. CSRD disclosure rules reshape procurement criteria for multi-site contracts. Lyon and Marseille logistics hubs concentrate mobile wash deployment for last-mile delivery electrification.
Netherlands
Urban congestion and emission-zone expansion favor compact touchless installations in Amsterdam and Rotterdam corridors. Fleet operators mandate weekly exterior washes to protect battery thermal management systems. Hydrogen fuel cell-powered mobile rigs emerge at Rotterdam port authority facilities.
Belgium
Subscription-based wash access displaces per-transaction pricing at highway-adjacent locations near Brussels and Antwerp. Younger vehicle owners prefer app-managed unlimited plans bundling interior vacuuming. Corporate fleet managers flatten variable cleaning costs under fixed ESG budget lines.
Spain
Water scarcity infrastructure gaps block closed-loop system economics despite EU Green Deal regulatory pressure. Self-service bay configurations persist in Barcelona and Madrid where labor costs and municipal reclaimed water hookups remain inadequate. Southern coastal markets demand corrosion-resistant equipment specifications.
Europe Car Wash Market Competitive Landscape
Engineering-intensive fabricators and service-integrated operators split the market along capital-deployment versus recurring-revenue axes. Consolidation concentrates among German and Spanish equipment specialists with established tunnel installation footprints. Three archetypes dominate: vertically integrated system builders, modular component suppliers, and fleet-service platform operators. Competitive moves center on water-recovery technology licensing and cross-border M&A to secure municipal permit expertise.
Among German engineering-intensive fabricators, WashTec AG and Otto Christ AG exemplify the vertically integrated system builder archetype. Istobal S.A. occupies a position within the corrosion-resistant equipment specialist tier. These named entities anchor industry-level patterns without implying specific strategic actions or market positions beyond their evident geographic and structural characteristics.
| Leading Market Players |
|---|
| WashTec AG |
| Alfred Kärcher SE & Co. KG |
| Istobal S.A. |
| Otto Christ AG |
| Tammermatic Oy |
| Daifuku Group |
| Green Steam International Sp. z o.o. |
| GoWashMyCar Ltd. |
| The London Carwash Co. |
| Others |
Pricing and Supply Chain Analysis
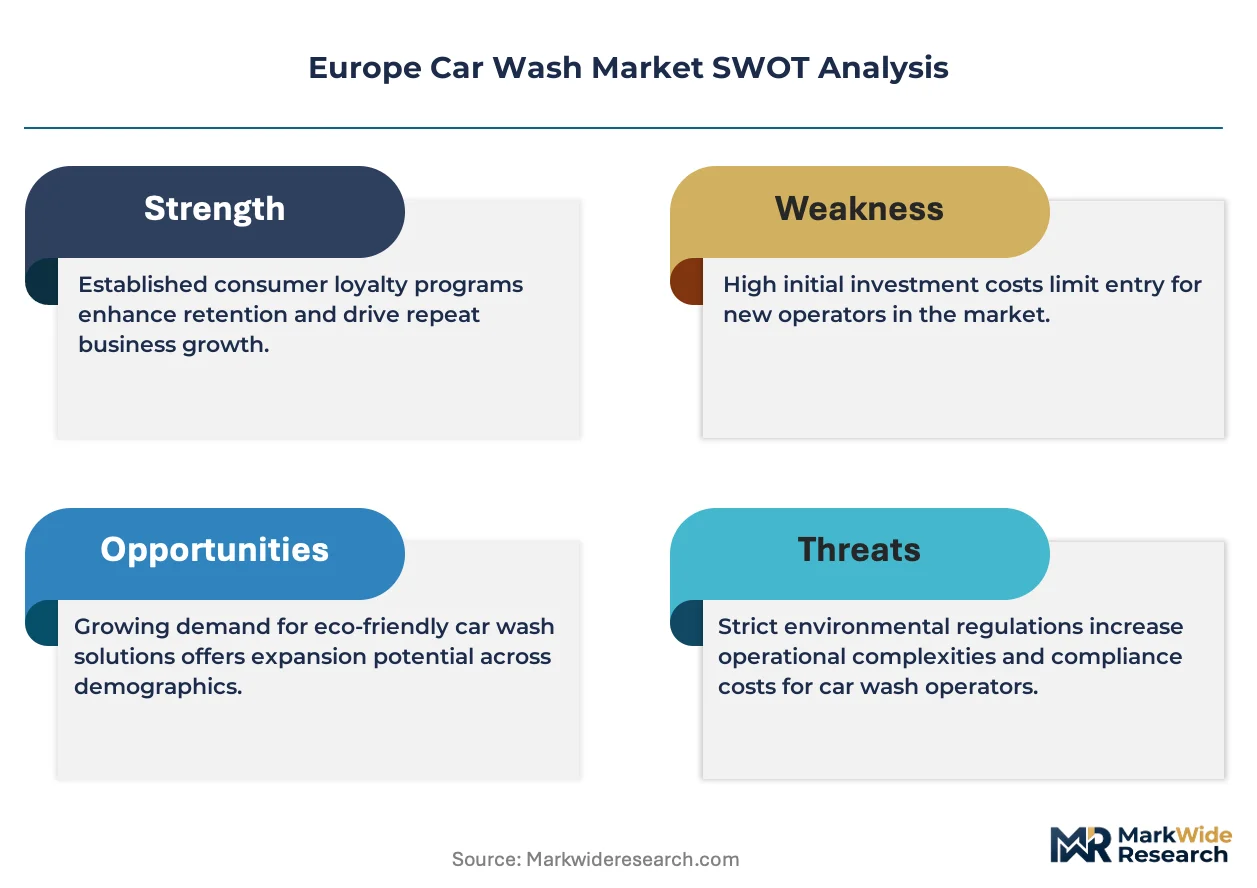
Stuttgart's manufacturing belt concentrates high-volume tunnel system fabrication, concentrating pricing power among German engineering-intensive fabricators serving fleet operators with certified water-recovery mandates. This geographic clustering feeds downstream cost structures across the Rhine-Ruhr corridor and into Benelux logistics hubs where municipal discharge thresholds tighten procurement criteria.
Pricing Analysis
Aftermarket service revenue from water reclamation and chemical recycling drives lifetime value more than initial equipment sales. Three-tier pricing structure across premium certified, standard compliant, and economy non-recovery levels segments buyers by environmental compliance requirements. Pricing pressure stems from steel and aluminum input volatility tied to EU carbon border adjustment mechanisms. Fleet managers demonstrate lowest price sensitivity due to CSRD disclosure mandates, while individual owners in Southern Europe remain tethered to low-cost hand-wash alternatives.
Supply Chain Analysis
Upstream steel and aluminum feedstock draws from German, Italian, and Spanish metalworking clusters. Conveyor system fabricators source PLC controllers from German automation specialists and ceramic membrane filtration components from Dutch water technology suppliers. Single-source vulnerability concentrates in specialized mechatronics technician labor pools. Distribution runs through OEM direct sales for fleet contracts and regional distributor networks for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's car wash market sits in early-cycle expansion as fleet electrification hygiene protocols and CSRD disclosure mandates accelerate automated wash adoption ahead of regulatory deadlines. Water-recovery retrofit requirements and subscription pricing pivots create structural tailwinds for capital deployment.
For Market Incumbents: Build regulatory compliance moats through dual KBA and French environmental prefecture certification pathways to capture cross-border fleet contracts. Deepen backward integration into closed-loop ceramic membrane filtration production to defend margins against steel input volatility. Consolidate municipal permit expertise through targeted acquisitions in the Benelux corridor where discharge thresholds are tightest. For New Entrants and Emerging Players: Central European logistics hubs in Poland and the Czech Republic represent the most penetrable entry point as CSRD rules extend wash contract centralization beyond established German and French markets. Mobile wash unit deployment for port authorities in Rotterdam and Hamburg offers white-space access without fixed infrastructure competition. Partner with hydrogen fuel cell rig suppliers to differentiate on decarbonization credentials. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription-based wash access and water reclamation service contracts generate predictable cash flows under ESG procurement frameworks. Acquisition targets should display ISO 14001-certified environmental management systems with granular consumption telemetry capabilities. Monitor REACH substance restriction timeline acceleration as an inflection signal for chemical inventory stranding risk and reformulation-driven equipment upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Recovery Technology Licensing | EU Green Deal mandates force retrofit cycles across Germany, France, and Benelux tunnel installations. |
| Cross-Border M&A for Permit Expertise | Dual KBA and French prefecture certification requirements fragment equipment procurement pathways. |
| Subscription Platform Development | Belgian and Dutch fleet managers seek fixed ESG budget lines through unlimited wash plans. |
| Hydrogen Fuel Cell Mobile Rig Deployment | Rotterdam and Hamburg port authorities prioritize decarbonized vessel-to-shore vehicle cleaning. |
| Computer Vision Damage Detection Integration | EU AI Act compliance creates regulatory tailwind for insurance-integrated service bundles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers, tunnel system maintenance directors, water reclamation technology specialists, and municipal environmental compliance officers. Secondary validation drew from EU Green Deal implementation documents, ECHA REACH substance registration databases, KBA technical inspection standards, and French environmental prefecture discharge permit records. Bottom-up installation counts and top-down fleet contract value estimates were triangulated to anchor market sizing.
Calibration against historical retrofit cycles and fleet electrification penetration patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service format, vehicle application, technology type, and customer procurement centralization level. CAGRs were derived from equipment replacement timelines and service revenue recurrence rates. Water scarcity infrastructure gaps in Southern Europe and mechatronics technician pipeline constraints in Eastern Europe informed regional growth differentials.
Practitioners should monitor REACH substance restriction acceleration and CSRD disclosure implementation pace for early signals of forecast revision. Cross-checking against customs data on steel and aluminum conveyor system imports and municipal water reclamation permit issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Automatic Tire Changer Market
Automotive Services
Automotive Subscription Services Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
US Quick Lube Equipment Market
Automotive Services
Car Subscription Market
Automotive Services
Automotive Digital Services Market
Automotive Services
Driver's License Market
Automotive Services
US Car Wash Services Market
Automotive Services
Vehicles for Disabled Market