
 Automotive Garage Equipment Market | 2026-2036
Automotive Garage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Garage Equipment Market Intelligence
Modular diagnostic platforms bundled with IoT-Enabled Tools is rebalancing how independent workshops evaluate capital outlays against subscription-like service revenues. Hunter Engineering Company leverages its alignment-system specialization to sustain premium positioning in North American dealership channels. Robert Bosch GmbH anchors European demand through its integrated diagnostic scanner and wheel balancer ecosystems. Launch Tech Co., Ltd. competes aggressively on digital control system features across Asia-Pacific price tiers.
Automotive garage equipment encompasses hydraulic lifts, wheel balancers, tire changers, brake lathes, and diagnostic scanners designed to service passenger and commercial vehicles at capacities typically ranging from 7,000 to 35,000 pounds; these systems employ electro-hydraulic actuation, precision sensor arrays, and embedded software to execute safety-critical maintenance and regulatory compliance tasks. Hydraulic lifts retain the largest installed base due to structural necessity in every service bay, while IoT-Enabled Tools represent the fastest-expanding technology segment as fleet operators demand predictive maintenance integration. Diagnostic scanners command disproportionate margin pools because software licensing and update cycles generate recurring revenue streams that hardware-centric categories cannot replicate.
The EPA enforces refrigerant recovery standards that mandate specific equipment certifications for garage operators handling R-134a and R-1234yf, while the EU F-Gas Regulation progressively restricts fluorinated greenhouse gas use and compels equipment upgrades across member-state service networks. OSHA lift inspection protocols in the United States and CE marking requirements under the EU Machinery Directive establish baseline safety and interoperability standards that shape product development roadmaps. Stakeholders must weigh the pace of electrified-vehicle service requirements against internal combustion equipment refresh cycles when allocating R&D and manufacturing capacity.
Market Dynamics
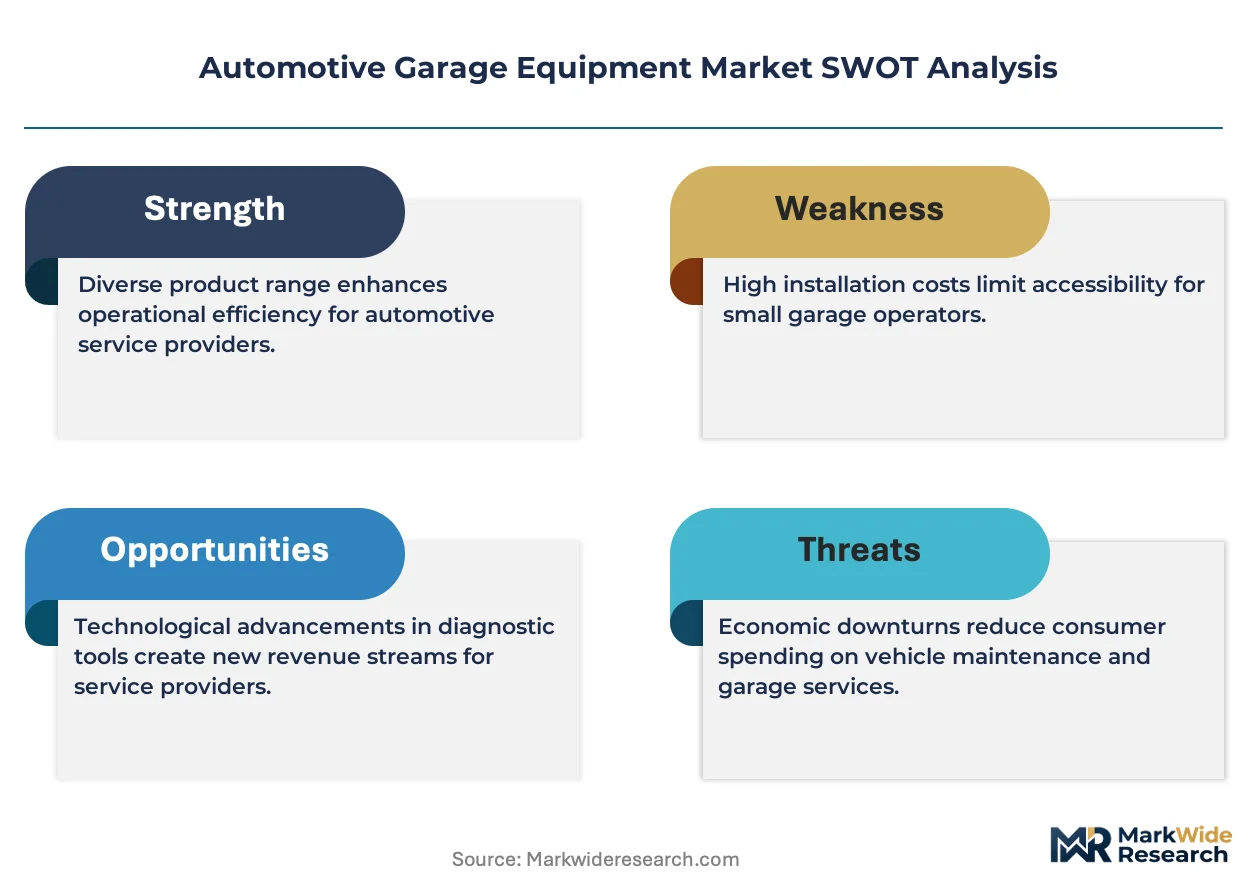
Electrified-vehicle service requirements are compressing refresh cycles for legacy internal combustion equipment while fleet operators demand predictive maintenance integration through IoT-Enabled Tools, forcing manufacturers to split R&D allocation between parallel technology stacks.
Growth Catalysts
- EPA refrigerant recovery mandates:The EPA enforces equipment certifications for garage operators handling R-134a and R-1234yf, compelling systematic upgrades across United States service networks.
- Commercial vehicle uptime tightening:Fleet maintenance providers are expanding tool procurement as downtime penalties from logistics contracts intensify equipment reliability requirements.
- China aftermarket scaling:Service network expansion to match vehicle parc growth is concentrating demand for diagnostic scanners and hydraulic lifts in tier-one Chinese cities.
Market Restraints
- Steel and aluminum input volatility:Hydraulic lift manufacturing depends on commodity metal prices that fluctuate with construction and automotive sector demand cycles.
- EU F-Gas compliance friction:Progressive fluorinated greenhouse gas restrictions force premature equipment retirement before depreciation cycles complete.
- Electronics supply concentration:Precision sensor arrays for wheel balancers and alignment systems source from concentrated semiconductor foundry capacity in East Asia.
Strategic Opportunities
- India aftermarket underpenetration:Organized service networks remain sparse relative to vehicle stock, creating first-mover advantage for diagnostic platform providers.
- Subscription software convergence:Diagnostic scanner ecosystems are bundling predictive analytics with hardware leases, capturing recurring revenue from independent workshops.
- OSHA lift inspection protocols:Mandatory annual certification requirements in the United States sustain replacement demand for aging installed bases.
Industry Challenges
- High-voltage technician certification gaps:Battery electric vehicle service requires specialized training that existing workforce pipelines inadequately supply.
- Legacy diagnostic integration complexity:New IoT-Enabled Tools must interface with 15-20 year old shop management software still prevalent in independent garages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Garage Equipment Market |
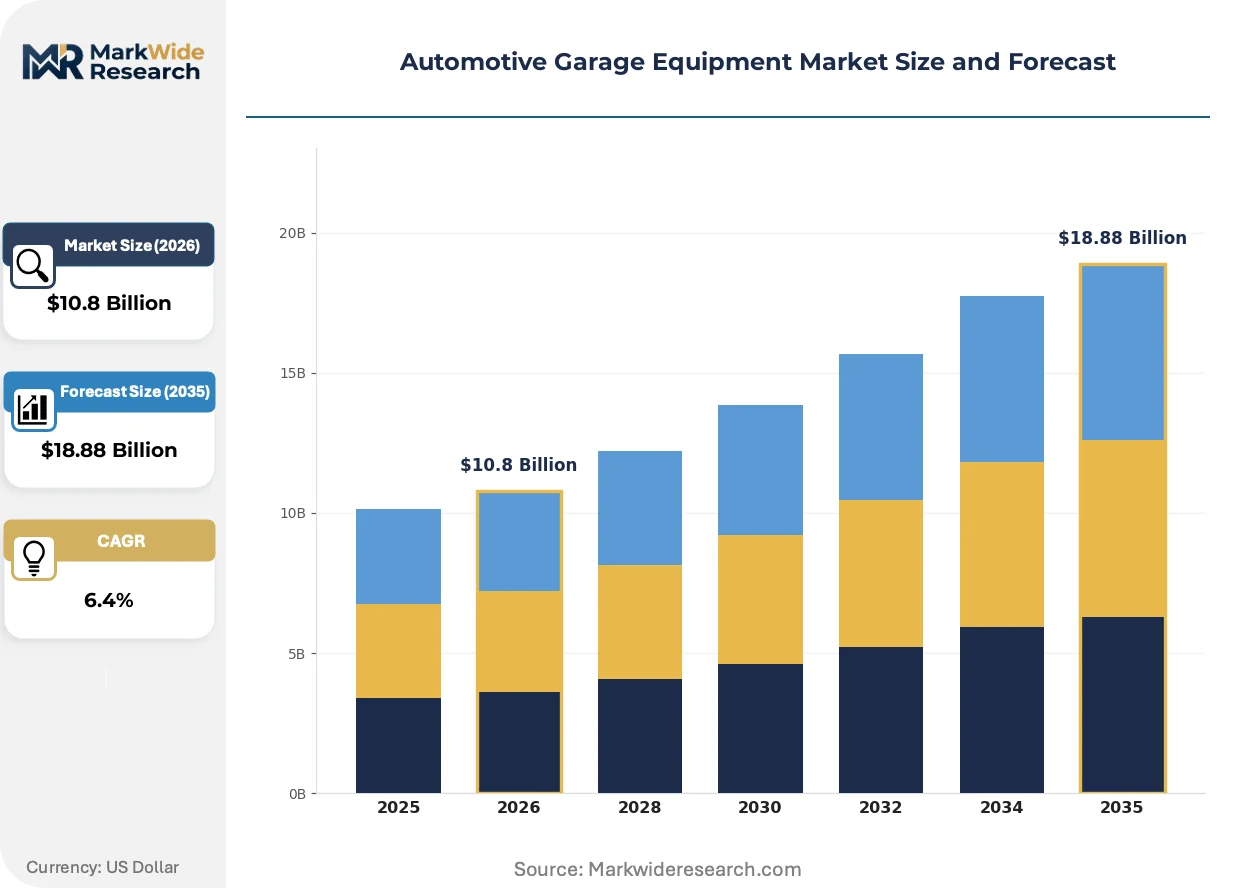
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Lifts, Wheel Balancers, Tire Changers, Brake Lathe, Diagnostic Scanners Technology: Manual Equipment, Semi-Automatic, Fully Automatic, Digital Control Systems, IoT-Enabled Tools Application: Vehicle Repair, Maintenance, Inspection, Tire Services, Engine Diagnostics End User: Independent Workshops, Dealership Service Centers, Fleet Maintenance Providers, Aftermarket Specialists |
| Companies Covered | Hunter Engineering Company, Ravaglioli S.p.A., Robert Bosch GmbH, Atlas Automotive Equipment, Rotary Lift, Snap-on Incorporated, Vehicle Service Group, Launch Tech Co., Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Garage Equipment Market Strategic Shifts & Innovations
Equipment intelligence layers are displacing standalone hardware value propositions as fleet operators and dealership groups prioritize data integration over point-tool functionality.
Automated wheel alignment systems combining machine vision with robotic adjustment arms are automating technician workflows previously requiring 20-30 minutes of manual calibration. High-volume tire retailers and dealership express lanes in the United States and Germany are deploying these systems at replacement rates three times faster than conventional alignment racks. The technology is automating labor cost structures while compressing bay turnover times to under 10 minutes per vehicle.
The EU F-Gas Regulation progressively tightens fluorinated greenhouse gas quotas through 2030, mandating refrigerant recovery equipment upgrades across member-state service networks. Garage operators in Germany, France, and Italy face compliance deadlines that accelerate capital expenditure timelines beyond normal depreciation schedules. Low-GWP refrigerant handling certification is becoming a prerequisite for warranty work on European vehicle brands.
Leasing-based procurement is displacing outright purchase for diagnostic scanners and wheel balancers among independent workshops in Japan and South Korea. Equipment-as-a-service models bundle software updates, calibration, and replacement guarantees into monthly payments that preserve working capital. This restructuring is most visible in Tokyo and Seoul metropolitan clusters where shop consolidation has concentrated buying power among multi-bay operators.
Automotive Garage Equipment Market Segmentation
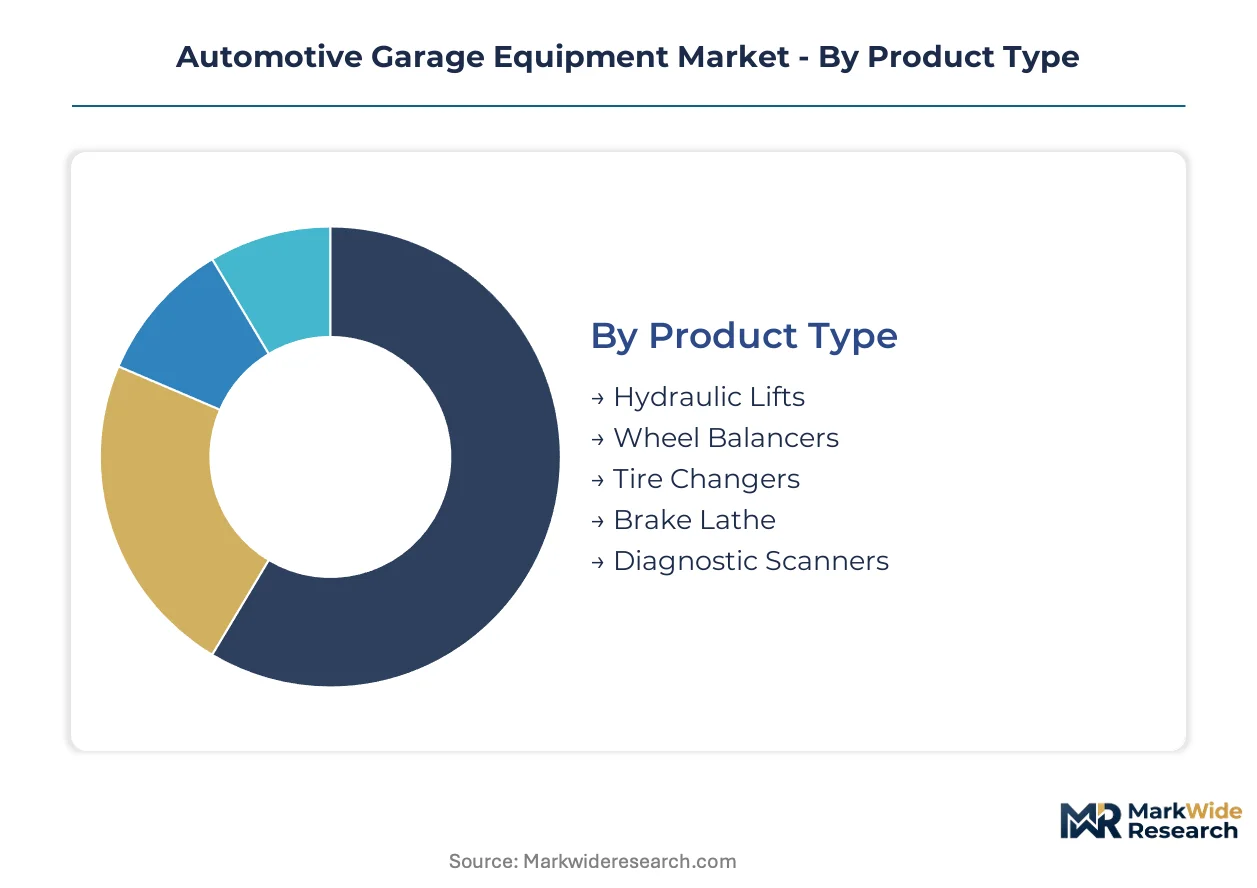
Equipment segmentation in automotive garage systems reveals how capital allocation priorities diverge across service models. Fleet operators, independent workshops, and dealership networks each demand distinct performance tiers, forcing manufacturers to engineer parallel product lines rather than universal platforms.
Product Type:
Replacement cycles vary sharply across equipment categories, with structural necessity driving faster turnover for safety-critical systems than for diagnostic peripherals.
- Hydraulic Lifts:Electro-hydraulic systems rated 7,000 to 35,000 pounds form the structural backbone of every service bay. OSHA inspection mandates in the United States sustain replacement demand as aging installed bases require systematic retirement.
- Diagnostic Scanners:Embedded software platforms with precision sensor arrays command disproportionate margin pools through recurring licensing revenues. Subscription bundling is displacing outright purchase among Tokyo and Seoul metropolitan clusters.
- Wheel Balancers:Precision calibration systems employing laser or sonar measurement arrays.
- Tire Changers:Rim-clamping mechanisms with pneumatic or electric drive systems.
- Brake Lathe:Rotor and drum resurfacing equipment for disc and drum brake maintenance.
Hydraulic lifts sit at the top of the volume ranking, with diagnostic scanners climbing the fastest.
Technology:
Cost tiers separate entry-level mechanical systems from premium connected platforms, with mid-market buyers facing compressed choice sets as vendors consolidate R&D on digital control architectures.
- IoT-Enabled Tools:Predictive maintenance integration through cloud-connected sensor networks is rebalancing fleet procurement criteria. Commercial vehicle operators in Germany and France now specify remote diagnostics compatibility as a contractual requirement.
- Digital Control Systems:Touchscreen interfaces with automated calibration protocols reduce technician training burdens. Launch Tech competes aggressively on feature depth across Asia-Pacific price tiers.
- Manual Equipment:Hand-operated mechanical systems without electronic actuation.
- Semi-Automatic:Hybrid platforms combining mechanical operation with limited electronic assistance.
- Fully Automatic:Robotic adjustment systems with minimal technician intervention.
Manual equipment retains the largest installed base, while IoT-Enabled Tools are expanding most quickly.
Application:
Customer type dictates application intensity, with fleet maintenance providers running inspection protocols at frequencies three to four times higher than retail service channels.
- Vehicle Repair:Collision recovery and mechanical restoration services requiring structural alignment and component replacement. Independent workshops in tier-one Chinese cities are scaling bay capacity to match vehicle parc expansion.
- Maintenance:Scheduled service intervals for fluid replacement, filter changes, and wear-component inspection. EPA refrigerant recovery mandates compel systematic equipment upgrades across United States service networks.
- Inspection:Regulatory compliance verification for safety and emissions standards.
- Tire Services:Mounting, balancing, and rotation operations with high bay turnover requirements.
- Engine Diagnostics:Powertrain fault identification and performance optimization.
Maintenance commands the highest procedure frequency, with engine diagnostics gaining share fastest.
End User:
Procurement patterns diverge across customer types, with consolidated buyers extracting service bundling concessions unavailable to fragmented independent operators.
- Fleet Maintenance Providers:High-volume operators with uptime penalties written into logistics contracts. Equipment reliability specifications tighten as downtime costs escalate in United States and German freight markets.
- Dealership Service Centers:OEM-affiliated facilities with warranty work requirements and brand-standard equipment mandates. Hunter Engineering sustains premium positioning in North American dealership channels through alignment-system specialization.
- Independent Workshops:Small and mid-sized operators with constrained capital budgets and legacy software integration requirements.
- Aftermarket Specialists:Niche service providers focusing on performance modifications or restoration.
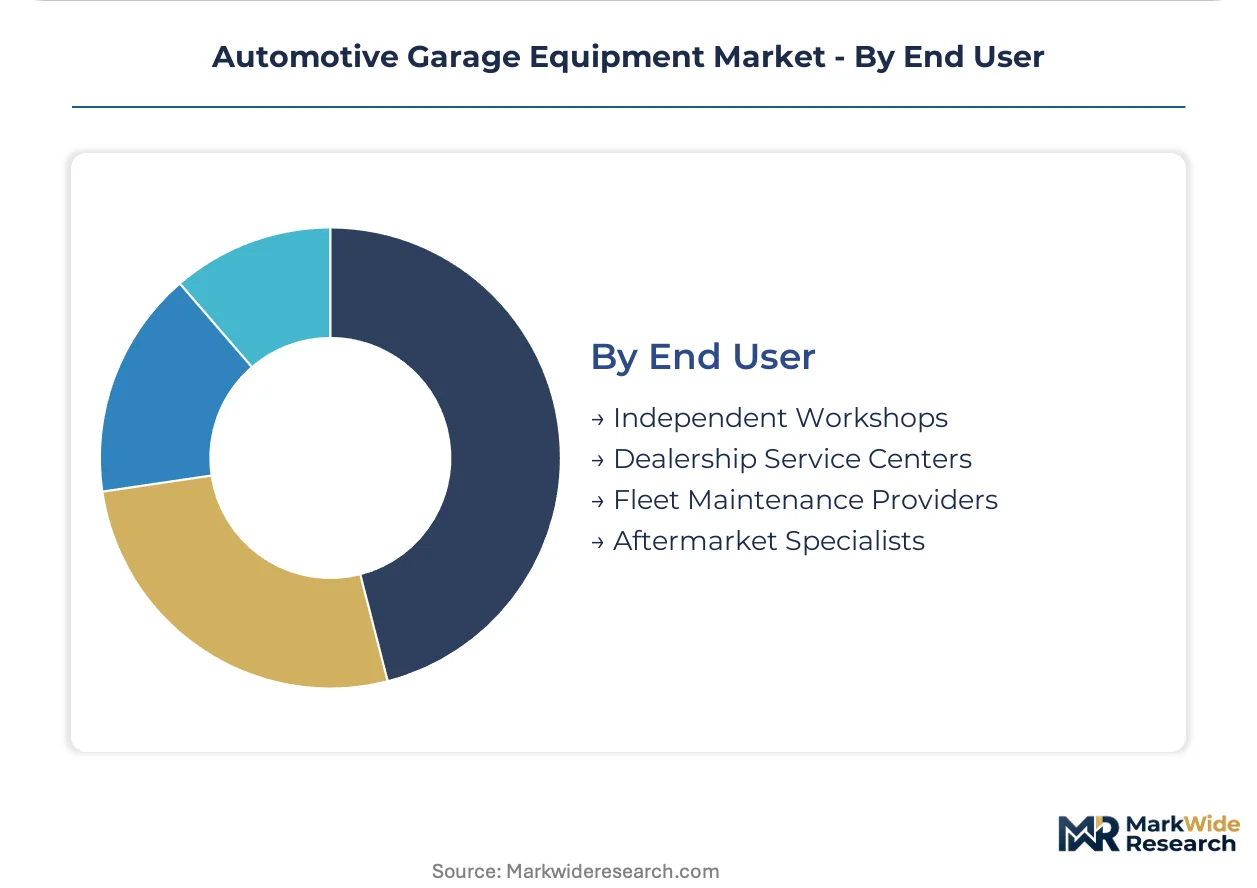
Fleet maintenance providers dominate capital expenditure volume, with dealership service centers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive garage equipment industry traces its modern scaling to post-war industrialization in the United States and Germany, where dealership service networks and independent repair chains first systematized bay equipment standards. Equipment manufacturers subsequently expanded production footprints across East Asia as vehicle assembly concentrated in Japan, South Korea, and China.
United States
Fleet maintenance providers in the Great Lakes and Southeast freight corridors drive capital expenditure volume as logistics uptime penalties tighten. OSHA lift inspection protocols mandate annual certification that sustains replacement demand for aging hydraulic systems. The Detroit-Warren-Ann Arbor automotive cluster anchors equipment procurement through dealership service center networks and heavy-duty commercial vehicle facilities.
Germany
EU F-Gas Regulation compliance deadlines accelerate refrigerant recovery equipment upgrades across independent workshops and OEM-affiliated service centers. The Stuttgart and Munich metropolitan areas concentrate premium diagnostic scanner demand as luxury vehicle parc density supports subscription software bundling. KBA enforcement of low-GWP refrigerant handling certification shapes warranty work access for European vehicle brands.
China
Aftermarket service network expansion in Shanghai, Beijing, and Guangzhou matches passenger vehicle parc growth with concentrated demand for diagnostic scanners and electro-hydraulic lifts. MIIT vehicle emissions enforcement protocols elevate compliance equipment requirements across tier-one city service bays. The Yangtze River Delta manufacturing belt supplies precision sensor arrays for wheel balancers targeting domestic and Asia-Pacific export markets.
Japan
Leasing-based procurement for diagnostic scanners and wheel balancers displaces outright purchase among Tokyo and Osaka metropolitan multi-bay operators. METI industrial standards for connected equipment interoperability shape IoT-Enabled Tools specification requirements. The Nagoya automotive manufacturing corridor generates aftermarket equipment demand through dense supplier park service networks.
India
Organized service network underpenetration relative to vehicle stock creates first-mover positioning for diagnostic platform providers entering Maharashtra and Karnataka. BIS equipment safety certification requirements establish baseline import standards for hydraulic lift and wheel balancer categories. The Delhi-NCR and Chennai industrial clusters concentrate emerging dealership service center construction and fleet maintenance provider facility expansion.
Automotive Garage Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across software-integrated versus hardware-only value capture. The vendor base organizes into three tiers: multinational industrial conglomerates with embedded automotive divisions, specialized garage equipment pure-plays with regional manufacturing footprints, and contract fabricators supplying private-label equipment to distributor networks. Strategic moves concentrate on diagnostic software licensing expansion and IoT platform partnership structures that lock in recurring revenue streams.
Within the specialized equipment tier, Hunter Engineering Company and Launch Tech Co., Ltd. occupy positions reflecting divergent geographic anchoring and technology specialization strategies. Robert Bosch GmbH exemplifies the industrial conglomerate archetype through integrated diagnostic and wheel balancer ecosystem bundling. Ravaglioli S.p.A. and Rotary Lift represent European and North American pure-play fabricators with established dealership channel relationships. Continental AG and Snap-on Incorporated sit within diversified industrial portfolios where automotive service equipment constitutes a segment-level priority rather than core identity.
| Leading Market Players |
|---|
| Hunter Engineering Company |
| Ravaglioli S.p.A. |
| Robert Bosch GmbH |
| Atlas Automotive Equipment |
| Rotary Lift |
| Snap-on Incorporated |
| Vehicle Service Group |
| Launch Tech Co., Ltd. |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Steel and aluminum commodity volatility cascades through hydraulic lift manufacturing, with raw metal costs absorbing 35-45% of finished equipment value before tiered pricing stratifies across fleet procurement contracts, independent workshop spot purchases, and dealership bundled service agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-affiliated dealership mandates from independent workshop procurement and fleet maintenance volume contracts. Certification grade under EU F-Gas Regulation and OSHA lift inspection protocols drives price differentiation between compliant and non-compliant equipment tiers. Cost compression in the economy segment intensifies because contract fabricators compete on metal input sourcing. Fleet maintenance providers exhibit lowest price sensitivity due to uptime penalty structures, while independent workshops in tier-two Chinese cities face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with East Asian semiconductor foundries supplying precision sensor arrays for wheel balancers and alignment systems. Manufacturing draws from China for electro-hydraulic actuation components, Germany for precision engineering subsystems, and the United States for embedded control software. Tariff exposure on steel imports into North American assembly plants creates margin pressure during commodity price spikes. Distribution runs through authorized dealer networks for premium diagnostic scanners and independent distributor channels for standard hydraulic lifts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment manufacturers face a geographic-arbitrage opportunity between EU F-Gas compliance-driven replacement demand and India's underpenetrated organized service networks, where regulatory equipment mandates remain nascent against vehicle parc expansion.
For Market Incumbents: Acquire diagnostic software licensing portfolios to lock in recurring revenue streams against hardware commoditization pressure from Asian contract fabricators. Consolidate R&D allocation between electrified-vehicle service requirements and legacy internal combustion equipment refresh cycles. Channel control through exclusive dealership relationships in North American freight corridors defends premium positioning. For New Entrants and Emerging Players: Direct-to-distributor digital platforms bypass incumbent field sales infrastructure to reach fragmented independent workshops in Maharashtra and Karnataka. India's organized service network underpenetration offers the most penetrable geography for diagnostic platform first-movers. Subscription bundling with predictive analytics software provides differentiation against hardware-only competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where IoT-Enabled Tools vendors lack captive cloud infrastructure to support recurring revenue models. Long-term viability favors specialists with integrated software-hardware ecosystems over pure-play fabricators dependent on metal input pricing. Watch EPA refrigerant recovery mandate enforcement intensity as inflection indicator for compliance equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Software Licensing Expansion | Captures recurring revenue from EPA-mandated scanner update cycles across US service networks. |
| IoT Platform Partnership Structures | Locks fleet operators into predictive maintenance ecosystems through cloud-connected sensor networks. |
| Backward Integration into Precision Sensors | Reduces East Asian foundry dependency for wheel balancer calibration systems. |
| Geographic Manufacturing Footprint Shift | Positions assembly capacity near India's emerging dealership construction clusters in Delhi-NCR. |
| Subscription Bundling with Hardware Leases | Mirrors Tokyo and Seoul procurement patterns for independent workshop cash-flow preservation. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered fleet maintenance procurement directors, independent workshop owners, OEM aftermarket service managers, and hydraulic lift distributor principals. Secondary validation drew from EPA enforcement protocol documents, EU F-Gas Regulation implementation schedules, OSHA lift inspection guidance, and MIIT vehicle emissions standards. Bottom-up equipment shipment tracking and top-down vehicle parc modeling provided cross-verification.
Segment-weighting applied differential growth rates across hydraulic lifts, diagnostic scanners, wheel balancers, and tire changers by technology tier and end-user category. The analytical framework modeled fleet maintenance providers, dealership service centers, and independent workshops separately across the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline mapping, and vehicle electrification pathway assumptions. Forecast inputs incorporated steel and aluminum commodity price banding and semiconductor foundry capacity utilization rates.
The model assumes a particular technology adoption path; alternative pathways for battery electric vehicle service equipment would alter the outlook. Forecasts reflect assumptions about EPA refrigerant recovery enforcement timing and EU F-Gas quota phase-down schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Engineering Services Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Car Rental Business Market
Automotive Services
Mobility Scooters Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
GCC Car Rental Market
Automotive Services
Automotive MRO Market
Automotive Services
Car Washing Service Market
Automotive Services
Online Car-Hailing Service Market
Automotive Services
Automotive Quality Service Market