
 Global Street Sweeper Brushes Market | 2026-2036
Global Street Sweeper Brushes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Street Sweeper Brushes Market Outlook
Germany is reconfiguring supply patterns for street sweeper brush consumables across Central European municipal procurement networks. United Rotary Brush leverages its manufacturing footprint to sustain just-in-time fulfillment contracts with German public works authorities. Keystone anchors its competitive position through specialized steel-wire brush configurations engineered for heavy-debris industrial applications.
Street sweeper brushes are cylindrical or wafer-style rotating implements composed of polypropylene, nylon, steel wire, or natural fiber filaments secured to metal or composite cores, designed to dislodge and convey debris from paved surfaces into collection systems. Polypropylene dominates volume production due to its chemical resistance and cost structure, while steel variants command premium positioning in mining and construction zone applications where abrasive wear rates accelerate replacement cycles. Municipal Facilities represent the largest application segment, though Industrial Sites generate disproportionate margin contribution through specialized large-diameter configurations and shorter replacement intervals.
The EU Green Deal and REACH chemical compliance frameworks in Europe, alongside EPA stormwater runoff regulations in the United States, compel brush manufacturers to certify filament compositions and validate debris capture efficiency. India's BIS mechanical safety standards and China's GB quality benchmarks further fragment certification requirements for exporters. Stakeholders must monitor evolving procurement specifications that integrate circular economy criteria and extended producer responsibility obligations into municipal tender evaluations.
Market Dynamics
EU Green Deal debris recovery mandates are compressing brush replacement cycles across municipal fleets while simultaneously elevating filament performance specifications. This regulatory pressure is hybridizing procurement criteria with circular economy obligations.
Growth Catalysts
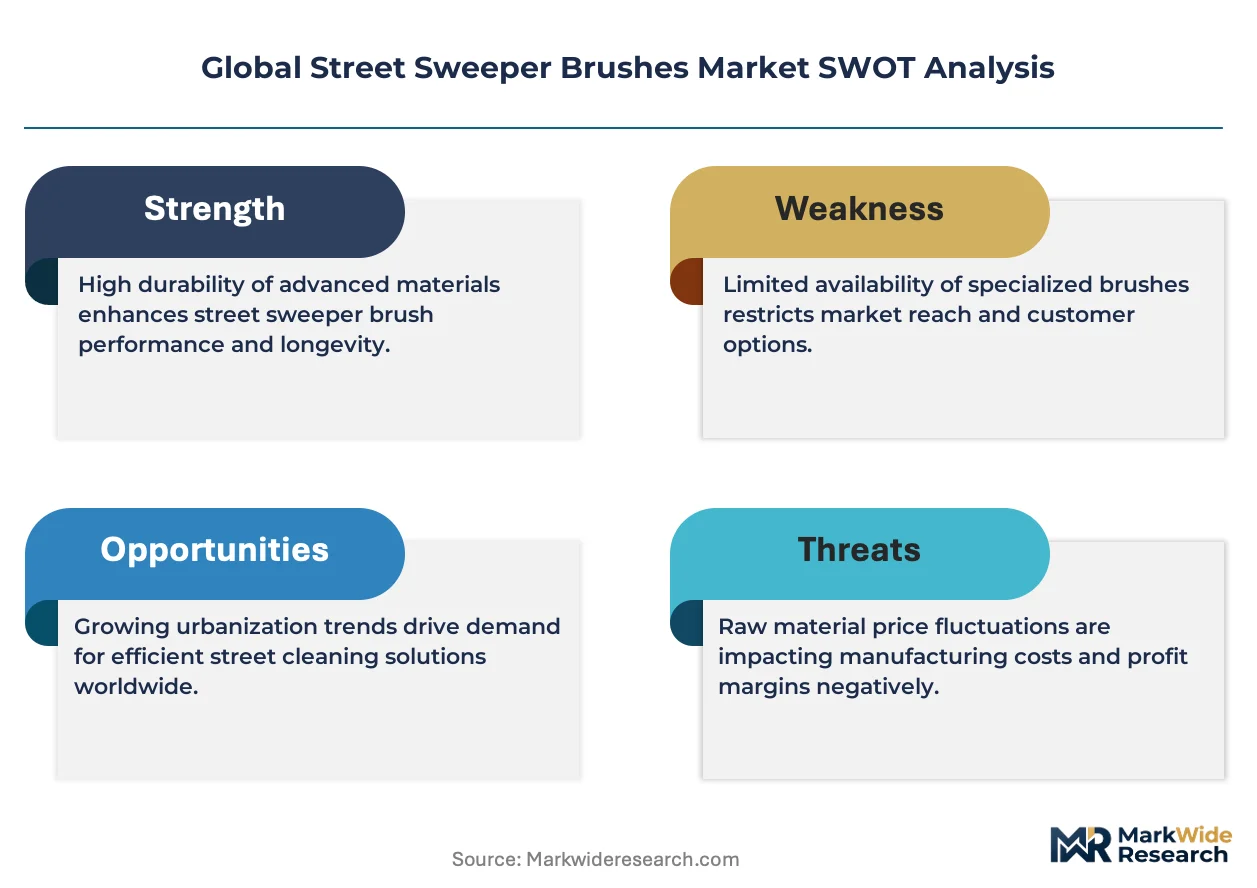
- REACH chemical compliance frameworks:European municipalities now require certified filament compositions that validate debris capture efficiency, creating pull for advanced polypropylene formulations.
- Urban corridor renewal programs:Brazil's federal infrastructure investments and India's smart city initiatives are expanding installed sweeper bases and consumable demand simultaneously.
- Polypropylene abrasion resistance:Enhanced filament formulations are displacing conventional materials in North American procurement contracts through demonstrable lifecycle cost advantages.
Market Restraints
- Steel wire input volatility:Mining-grade brush configurations face margin pressure from ferrous metal price swings and alloy sourcing concentration.
- Technical limitation in high-temperature environments:Standard polypropylene filaments degrade in asphalt plant and foundry proximity applications, restricting addressable market scope.
- REACH certification friction:Extended validation timelines for new filament chemistries delay product commercialization by 12-18 months in European markets.
Strategic Opportunities
- Industrial site specialization:Heavy-debris applications in mining and construction zones command premium positioning through shorter replacement intervals and custom diameter configurations.
- EPA stormwater runoff alignment:US municipal tenders increasingly integrate debris capture efficiency metrics, favoring suppliers with validated performance data.
- Channel convergence with equipment OEMs:Bundled brush-and-sweeper procurement contracts are consolidating vendor relationships and locking in multi-year consumable commitments.
Industry Challenges
- Certification timeline compression:India's BIS mechanical safety standards and China's GB quality benchmarks require parallel testing protocols, fragmenting exporter compliance resources.
- Legacy sweeper compatibility:Municipal fleet heterogeneity forces brush manufacturers to maintain excessive SKU diversity for obsolete mounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Street Sweeper Brushes Market |
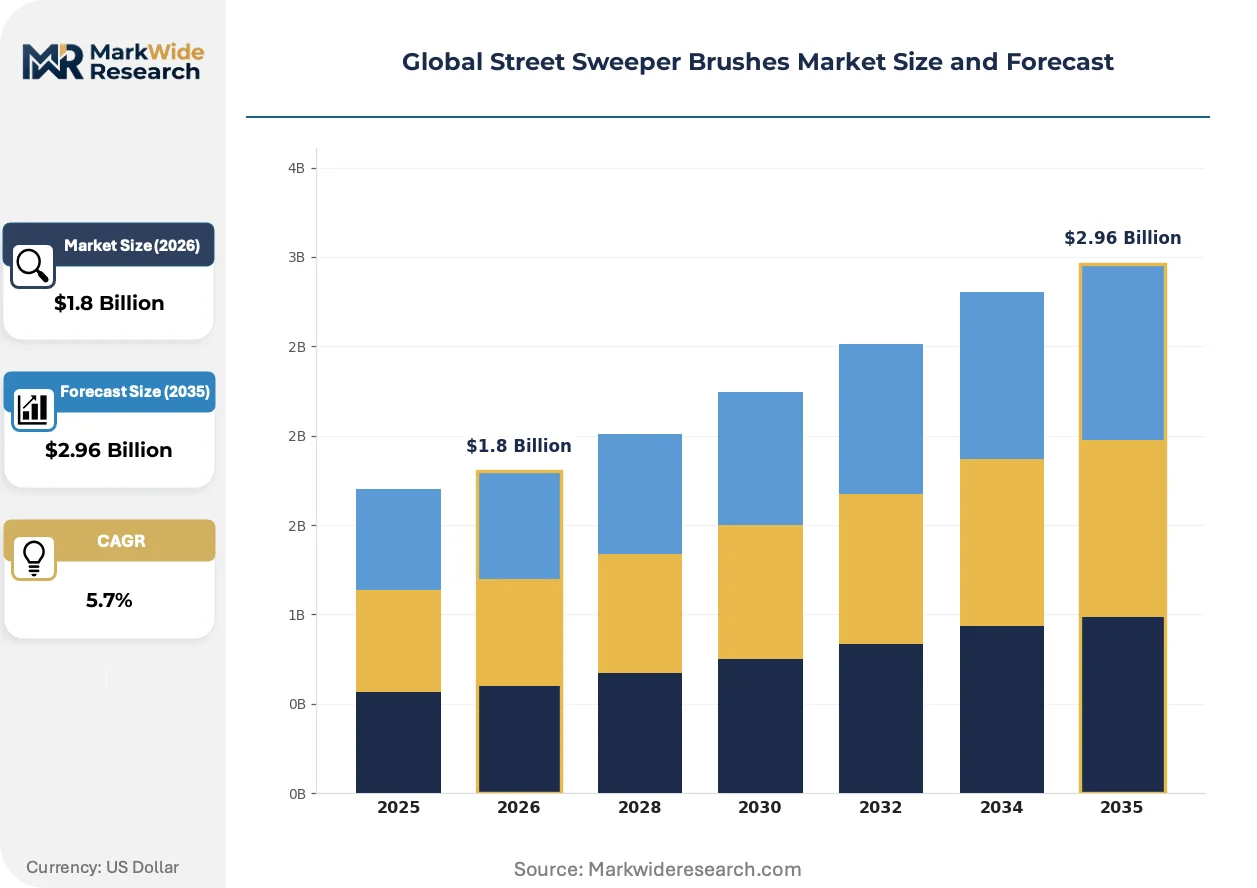
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Nylon, Steel, Natural Fiber Application: Municipal Facilities, Commercial Areas, Industrial Sites, Residential Streets End User: Public Works, Private Contractors, Facility Management, Government Agencies Brush Diameter: Small, Medium, Large, Extra Large |
| Companies Covered | United Rotary Brush, Keystone, Smith Equipment, ODB, Young and Swartz, Liberty Brush Manufacturing, TecSolum, KOTI Group, Osborn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Street Sweeper Brushes Market Strategic Shifts
Material science advances and procurement digitization are converging to reshape competitive positioning. Filament engineering now dominates R&D allocation while municipal buyers demand predictive maintenance integration.
Composite core construction is hybridizing metal and fiber-reinforced polymer substrates to reduce weight without sacrificing rotational stability. German public works authorities are piloting these configurations in high-frequency replacement corridors. The technology is hybridizing traditional wafer-style and cylindrical formats into modular systems that permit field-adaptable configurations.
REACH chemical compliance frameworks are mandating full material disclosure for filament compositions entering European municipal supply chains. Manufacturers must now document polymer sourcing and additive content through supply chain tiers. Industrial site applications face the steepest documentation burdens, driving consolidation toward vertically integrated compounders with captive polymer production.
Municipal procurement platforms are consolidating vendor qualification through centralized digital tendering systems that embed lifecycle cost calculators. German and US public works departments now weight total cost of ownership above unit price in brush selection. Brazil's federal infrastructure programs are adopting similar evaluation frameworks, compressing supplier margins while rewarding performance-validated incumbents.
Global Street Sweeper Brushes Market Segmentation
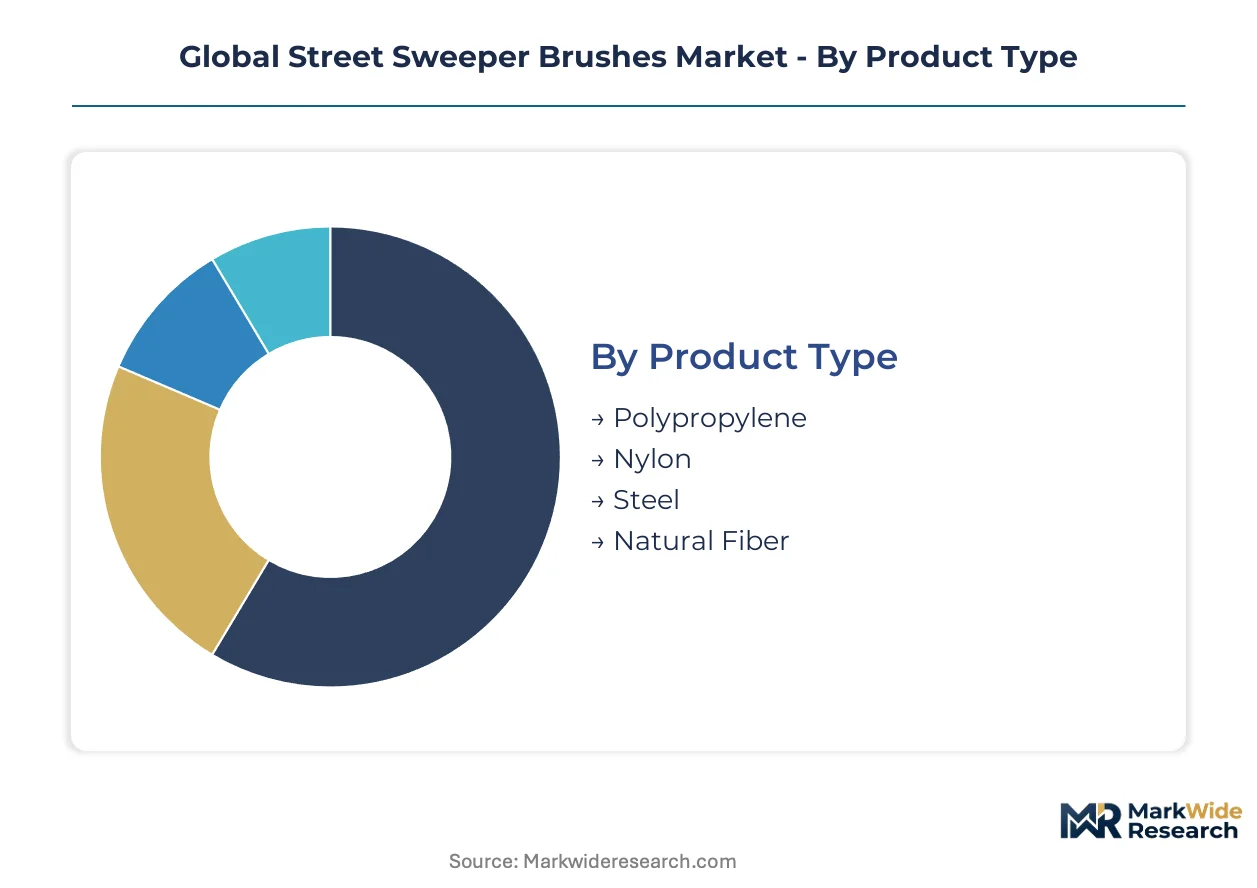
Street sweeper brush procurement varies sharply by duty cycle and debris profile. Segment-specific replacement intervals and filament specifications determine supplier contract structures and inventory planning across municipal and industrial accounts.
Product Type:
Replacement velocity splits dramatically across filament chemistries, with abrasive environments forcing 3-6 month cycles versus 12-18 month intervals for standard municipal duty.
- Polypropylene:Thermoplastic polymer filaments deliver chemical resistance against road salts and petroleum residues at moderate cost. German municipal fleets under EU Green Deal debris recovery mandates are expanding procurement of enhanced abrasion-resistant grades for urban corridor renewal programs.
- Steel:High-tensile wire configurations withstand mining overburden and construction aggregate with accelerated wear tolerance. Mining operations in Australia and Canada generate concentrated demand for heavy-gauge spiral-wound assemblies with 45-60 day replacement schedules.
- Nylon:Polyamide formulations offer superior flexibility in cold-climate applications where polypropylene embrittles.
- Natural Fiber:Biodegradable alternatives serve heritage district and noise-sensitive zone requirements in European historic centers.
Polypropylene dominates installed base. Steel is where expansion concentrates.
Application:
Margin structure inverts across application tiers, with specialized industrial configurations commanding 2-3x unit pricing despite smaller volume.
- Municipal Facilities:Standardized wafer and cylindrical brushes for street and highway maintenance represent the volume anchor. US urban corridor renewal programs and India's smart city initiatives are expanding sweeper fleet deployments and consumable pull-through.
- Industrial Sites:Custom-diameter configurations for mining, quarry, and steel mill environments generate disproportionate margin contribution through engineered filament density and reinforced core construction.
- Commercial Areas:Shopping district and business park specifications prioritize noise reduction and surface finish protection.
- Residential Streets:Light-duty polypropylene configurations serve suburban and gated community fleets with extended replacement intervals.
Municipal Facilities anchor volume throughput. Industrial Sites are climbing the fastest.
End User:
Procurement sophistication diverges sharply between public tender processes and private fleet operator decision frameworks.
- Public Works:Municipal street maintenance departments operate under centralized procurement with lifecycle cost evaluation criteria. German public works authorities now embed circular economy obligations and extended producer responsibility into brush tender specifications.
- Private Contractors:Third-party sweeping service providers prioritize equipment compatibility and rapid fulfillment over unit price optimization.
- Facility Management:Industrial plant and logistics center operators specify brushes for captive sweeper fleets with just-in-time replacement scheduling.
- Government Agencies:Federal and state highway departments maintain separate procurement streams with standardized technical specifications.
Public Works commands the largest addressable spend. Private Contractors are gaining share fastest.
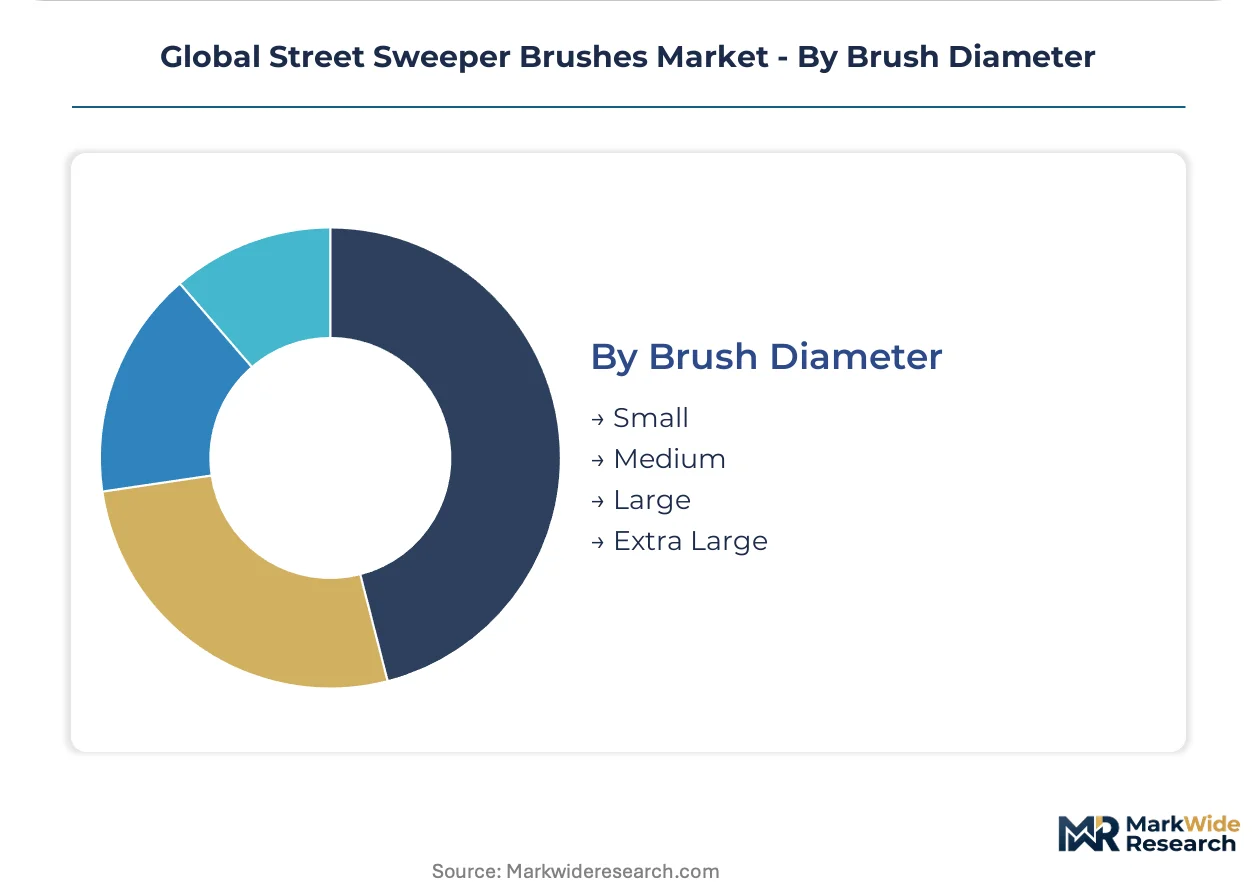
Brush Diameter:
Sweeper OEM mounting system heterogeneity fragments diameter demand across legacy and current-generation equipment bases.
- Medium:22-26 inch configurations serve the broadest installed sweeper base across municipal and commercial applications. Brazilian federal infrastructure investments are expanding medium-diameter fleet penetration for urban corridor programs.
- Large:28-32 inch assemblies address highway-class sweepers with higher debris volume throughput requirements.
- Small:Compact sidewalk and bike lane sweeper specifications.
- Extra Large:Specialized mining and airport runway configurations with custom core engineering.
Medium diameter holds the broadest equipment compatibility. Large diameter is where fleet modernization concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA stormwater runoff regulations in the United States are compressing municipal brush replacement cycles and elevating debris capture efficiency requirements. German public works authorities under EU Green Deal mandates are reconfiguring procurement specifications across Central European networks. Brazil's federal infrastructure investments and India's smart city initiatives are expanding installed sweeper bases and consumable demand simultaneously.
United States
Urban corridor renewal programs in New York, Los Angeles, and Chicago are driving municipal fleet modernization and brush consumable pull-through. EPA stormwater runoff regulations now embed debris capture efficiency metrics into municipal tender evaluations, favoring suppliers with validated performance data. The Southeast corridor from Atlanta to Miami represents a concentration of third-party sweeping contractors prioritizing rapid fulfillment over unit price optimization.
Germany
Municipal street maintenance fleets in Berlin, Munich, and Hamburg are expanding brush replacement schedules amid stricter EU Green Deal debris recovery mandates. REACH chemical compliance frameworks require full material disclosure for filament compositions entering municipal supply chains. The Ruhr industrial cluster is piloting composite core constructions that hybridize metal and fiber-reinforced polymer substrates for high-frequency replacement corridors.
Brazil
Federal infrastructure investments are expanding medium-diameter fleet penetration for urban corridor programs in São Paulo and Rio de Janeiro. Municipal procurement platforms are adopting lifecycle cost evaluation frameworks that weight total cost of ownership above unit price in brush selection. The Minas Gerais mining belt generates concentrated demand for heavy-gauge steel-wire configurations with accelerated replacement intervals.
India
Smart city initiatives in Delhi, Mumbai, and Bangalore are expanding sweeper fleet deployments and consumable demand across municipal accounts. BIS mechanical safety standards require parallel testing protocols that fragment exporter compliance resources and extend validation timelines. The Gujarat industrial corridor is emerging as a fabrication hub for polypropylene filament formulations serving domestic and export markets.
China
GB quality benchmarks and dual carbon goals are elevating filament performance specifications for brushes entering municipal and industrial supply chains. Yangtze River Delta manufacturing clusters are consolidating production of enhanced abrasion-resistant polypropylene grades. The Pearl River Delta is specializing in composite core engineering for export-oriented OEM bundled procurement contracts.
Global Street Sweeper Brushes Market Competitive Environment
Capability concentration sits with specialized filament compounders and custom core engineers; scale advantage sits with multi-regional fabricators serving standardized municipal accounts. The vendor base organizes into three tiers: vertically integrated compounders with captive polymer production, regional specialists in steel-wire or natural fiber configurations, and contract manufacturers serving private label OEM relationships. Consolidation pressure is accelerating through bundled brush-and-sweeper procurement contracts and backward integration by municipal equipment suppliers seeking consumable lock-in.
Among North American fabricators, United Rotary Brush and Keystone occupy distinct positioning archetypes. United Rotary Brush exemplifies the scale-driven tier through its manufacturing footprint and just-in-time fulfillment relationships with German public works authorities. Keystone anchors the specialization vector through engineered configurations for heavy-debris industrial applications. Smith Equipment and Liberty Brush Manufacturing represent the mid-tier regional specialists competing on equipment compatibility breadth and rapid fulfillment velocity. ODB and Young and Swartz sit within the contract manufacturing segment serving private label and OEM bundled procurement channels.
| Leading Market Players |
|---|
| United Rotary Brush |
| Keystone |
| Smith Equipment |
| ODB |
| Young and Swartz |
| Liberty Brush Manufacturing |
| TecSolum |
| KOTI Group |
| Osborn |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp polypropylene freight corridor anchors cost dynamics across European filament supply networks, compressing margins for German brush fabricators while amplifying price differentiation between REACH-certified premium grades and uncertified economy alternatives. This logistics chokepoint simultaneously concentrates procurement power among vertically integrated compounders and forces smaller regional specialists to absorb freight volatility or surrender municipal tender participation.
Pricing Analysis
Geographic price spreads between German municipal tenders and Brazilian federal procurement contracts exceed factor differentials driven by certification burden and logistics cost rather than raw material variance. Three-tier pricing structure across premium REACH-validated, standard abrasion-resistant, and economy polypropylene grades dominates contract structures, with EU Green Deal compliance and filament performance validation serving as the primary differentiation levers. Cost compression in economy tiers is intensifying as Indian export-oriented fabricators scale polypropylene filament production for price-sensitive Southeast Asian markets. Private contractors in the US Southeast corridor exhibit lowest price sensitivity due to rapid fulfillment prioritization, while Indian municipal buyers under smart city budgets demonstrate highest elasticity.
Supply Chain Analysis
Export-control friction around advanced polymer additive formulations constrains technology transfer from German compounders to emerging fabrication hubs, fragmenting global filament engineering capability. Supply concentrates in China for polypropylene resin and composite core substrates, Germany for REACH-certified specialty formulations, and India for volume brush assembly serving domestic and Middle Eastern markets. Raw material dependencies rest on propylene feedstock pricing, steel wire alloy sourcing from Australian and Canadian mining operations, and fiber-reinforced polymer core components from Yangtze River Delta manufacturers. Single-source vulnerability concentrates in European REACH validation laboratories, where extended certification timelines create bottleneck risk for new filament commercialization. Distribution runs through municipal procurement platforms consolidating vendor qualification, OEM bundled brush-and-sweeper contracts, and third-party sweeping service networks prioritizing rapid fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brush replacement cycles compressing under regulatory mandates transform municipal procurement into a service-attach opportunity, with predictive maintenance contracts and just-in-time fulfillment agreements expanding faster than standalone hardware transactions. Recurring revenue layers from multi-year consumable commitments now outpace equipment sale growth across German and US public works accounts.
For Market Incumbents: Pre-empt backward integration threats from sweeper OEMs seeking consumable lock-in by deepening captive polymer production and securing exclusive filament formulation patents. Fortify just-in-time fulfillment infrastructure in high-frequency replacement corridors to defend against emerging regional fabricators in India and China. Prioritize REACH validation laboratory partnerships to compress certification timelines and accelerate product commercialization velocity.
For New Entrants and Emerging Players: India's Gujarat industrial corridor offers underpenetrated white-space for polypropylene filament fabrication serving domestic smart city demand and export markets across Southeast Asia and the Middle East. Target heavy-debris industrial site applications in Brazil's Minas Gerais mining belt with specialized steel-wire configurations, where premium positioning and accelerated replacement intervals offset lower volume scale. Pursue OEM bundled procurement channel entry through private-label manufacturing relationships with municipal equipment suppliers lacking captive brush production.
For Investors and Strategic Acquirers: Regional specialists with established equipment compatibility breadth and rapid fulfillment velocity represent the most defensible acquisition archetype in a consolidating vendor landscape. Long-term viability across the analysis window hinges on circular economy credential integration and extended producer responsibility compliance capability. Monitor EU Green Deal debris recovery mandate expansion into additional member states as the primary inflection signal for accelerated replacement cycle adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Compounding | Captive resin production secures margin control against propylene feedstock volatility and REACH certification friction. |
| Predictive Maintenance Platform Development | IoT-enabled brush wear monitoring locks municipal customers into multi-year service contracts beyond hardware sales. |
| REACH Validation Laboratory Partnership | Parallel testing protocols compress 12-18 month certification timelines to sustain European market access velocity. |
| OEM Bundled Procurement Channel Entry | Private-label manufacturing relationships with sweeper equipment suppliers secure locked-in consumable demand streams. |
| Composite Core Engineering Scale-Up | Hybrid metal-fiber-reinforced polymer substrates reduce weight for high-frequency replacement corridors in German pilot programs. |
Study Parameters
The analysis maps polypropylene, steel-wire, nylon, and natural fiber brush segments, each validated through municipal procurement officers, industrial maintenance directors, sweeper OEM product managers, and filament compounder technical leads. Primary fieldwork combined structured interviews with aftermarket service heads and plant engineers at mining and quarry operations with secondary validation against customs trade data, municipal tender databases, EPA stormwater compliance filings, and EU Green Deal implementation reports. Bottom-up unit economics from replacement cycle frequencies and top-down market sizing from fleet deployment data were triangulated to derive volume and value estimates.
Assumptions held fixed across the projection horizon include prevailing REACH chemical compliance frameworks, EU Green Deal debris recovery mandate scope, and EPA stormwater runoff regulation enforcement intensity. Variables incorporated filament chemistry adoption curves by application segment, urban corridor renewal program deployment schedules, and industrial site sweeper fleet expansion rates. CAGRs were derived from segment-level replacement velocity modeling and procurement platform consolidation trajectories, with polypropylene abrasion resistance improvement curves and steel wire input cost volatility serving as key industry-specific forecast inputs.
Practitioners should monitor regulatory mandate expansion timelines, raw material cost inflections, and OEM backward integration announcements for early signals of forecast revision necessity. Material shifts in EU circular economy obligation scope or REACH certification burden escalation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Vehicle Analytics Market
Automotive Services
Automotive Retail Market
Automotive Services
Automotive Register Market
Automotive Services
Europe Car Wash Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Automotive Digital Services Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Car Wash System Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
North America MRO Distribution Market