
 Emergency Ambulance Vehicle Market | 2026-2036
Emergency Ambulance Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Ambulance Vehicle Market Intelligence
Electrification of commercial vehicle platforms is tilting ambulance architecture toward battery-electric and hybrid drivetrains with integrated power take-off systems for onboard medical equipment. Horton Emergency Vehicles leverages proprietary aluminum body construction to reduce curb weight and extend electric range. REV Group sustains manufacturing scale across multiple North American facilities, enabling rapid fleet fulfillment for large municipal contracts. Demers Ambulances specializes in modular interior configurations that accommodate advanced life support systems without chassis redesign.
An emergency ambulance vehicle is a purpose-built transport unit constructed on a reinforced commercial chassis with a custom patient compartment, medical gas plumbing, electrical inverters, and ISO-compliant mounting hardware for stretchers and monitoring devices. Its primary function is to deliver pre-hospital clinical intervention while relocating patients to definitive care facilities. Road ambulance configurations anchor current revenue due to fleet replacement cycles in mature healthcare systems, while air ambulance segments command premium pricing driven by remote-area access requirements and specialized aeromedical crew training. Telemedicine integration represents the fastest-growing technology dimension as real-time physician consultation during transport reduces time-to-treatment metrics.
The U.S. NHTSA and the European Commission's MDR framework govern ambulance safety standards, crashworthiness testing, and medical device interoperability, directly shaping procurement specifications for public fleet operators. India's CDSCO and BIS certification requirements are emerging as consequential gatekeepers for manufacturers targeting Asia-Pacific expansion through local assembly partnerships. Stakeholders must monitor regulatory divergence between jurisdictions as electrification mandates and data privacy rules for connected vehicle telematics create fragmented compliance obligations.
Market Dynamics
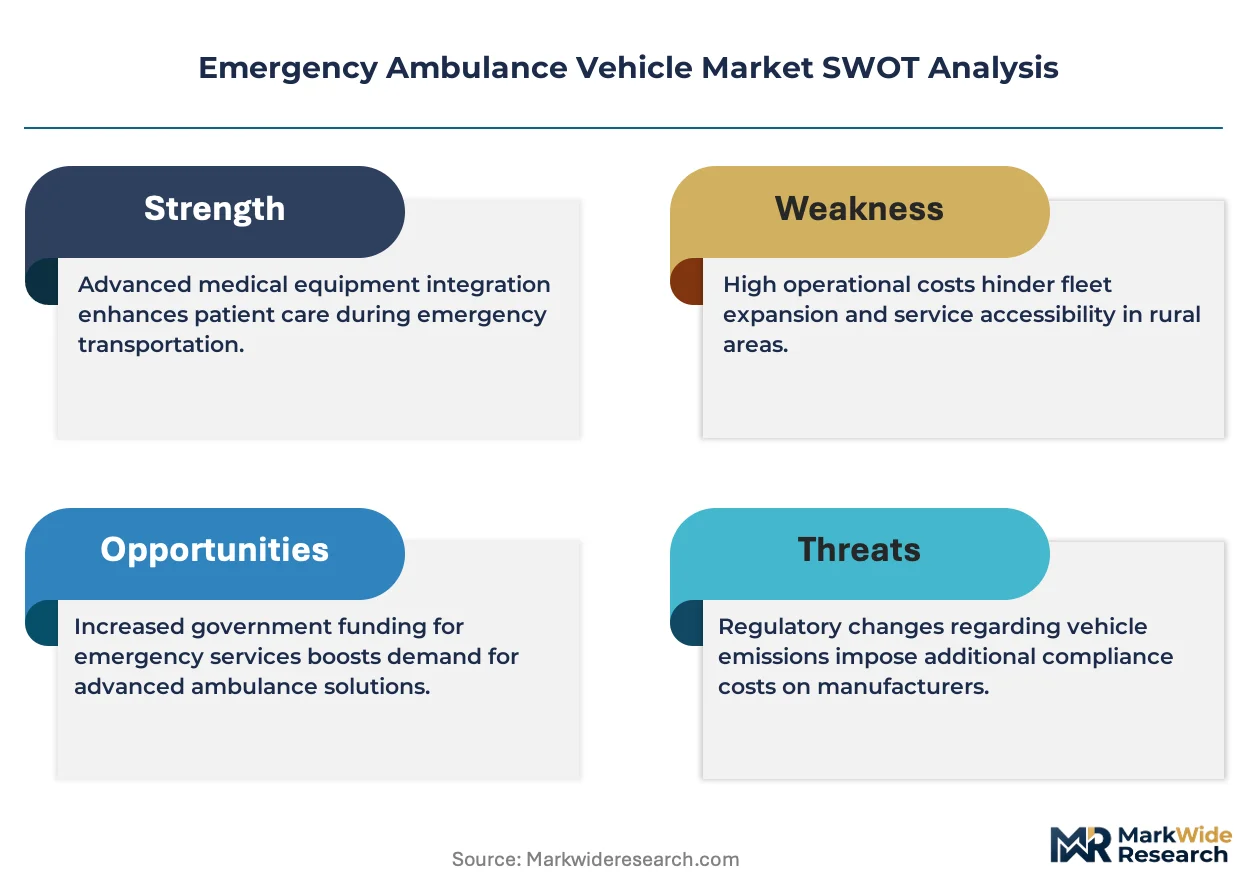
Electrification mandates from the EU Green Deal and California's Advanced Clean Trucks regulation are forcing chassis manufacturers to retool production lines for battery-electric platforms, compressing development cycles for ambulance builders dependent on commercial van supply.
Growth Catalysts
- Aging Demographics:Municipal EMS departments across Germany, Japan, and the United States face surging call volumes from cardiac and stroke events, necessitating fleet expansion and faster response vehicle deployment.
- MDR Framework:The European Commission's Medical Device Regulation mandates ISO-compliant mounting hardware and electrical safety certification, standardizing procurement specifications that favor purpose-built ambulances over retrofit conversions.
- Telemedicine Integration:Real-time physician consultation during transport is digitizing pre-hospital care protocols, creating pull for vehicles with dedicated data infrastructure and satellite connectivity.
Market Restraints
- Lithium Supply Concentration:Battery pack production depends on cathode materials processed in China, exposing electric ambulance programs to raw material price volatility and export restriction risk.
- Chassis Oligopoly:Ford, Mercedes-Benz, and Ram dominate light-commercial van platforms in North America and Europe, limiting ambulance manufacturers' negotiating leverage on drivetrain costs.
- Crashworthiness Standards:NHTSA rollover testing and side-impact requirements add structural mass that compresses electric range, creating technical tension between safety compliance and zero-emission targets.
Strategic Opportunities
- Rural India:CDSCO certification pathways and BIS standards for medical devices are opening local assembly partnerships to address vast underserved territories lacking emergency transport infrastructure.
- Hybrid Architecture:Integrated power take-off systems that run medical equipment independent of engine operation are converging with solar roof panels to extend stationary power duration.
- Subscription Fleet Models:Municipalities in the Netherlands and Denmark are piloting vehicle-as-a-service contracts that bundle maintenance, equipment refresh, and telematics into per-mile pricing.
Industry Challenges
- Electrical System Certification:ISO 17840 compliance for high-voltage safety in patient compartments requires specialized technician training that remains scarce across North American service networks.
- Interoperability Delays:Legacy hospital IT systems resist seamless data handoff from ambulance telemetry, forcing manual transcription that degrades care continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Ambulance Vehicle Market |
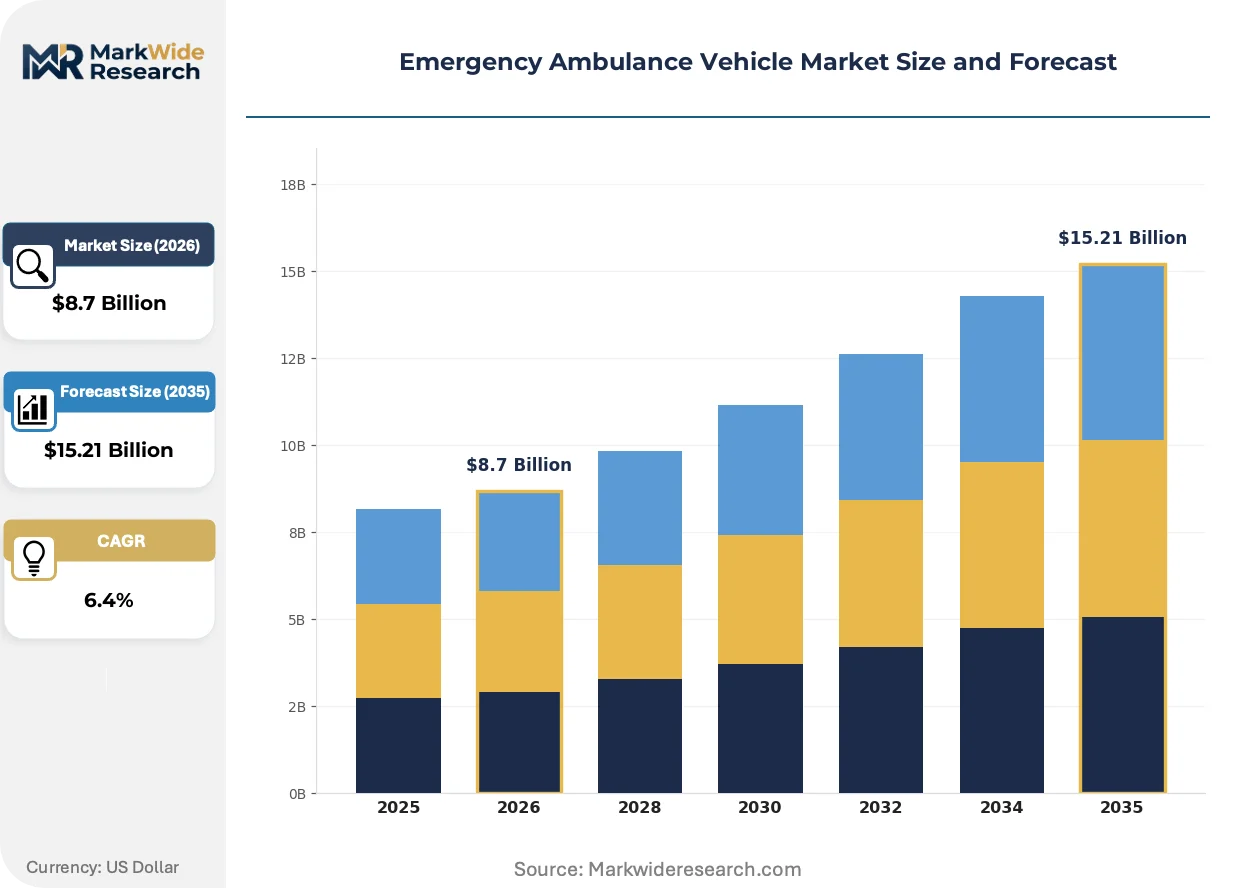
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Road Ambulance, Air Ambulance, Water Ambulance, Mobile ICU Application: Emergency Medical Services, Patient Transport, Disaster Management, Event Medical Support Technology: Telemedicine, GPS Navigation, Vehicle Tracking, Advanced Life Support Systems End User: Government Agencies, Private Operators, Healthcare Providers, Non-Profit Organizations |
| Companies Covered | Horton Emergency Vehicles, Wheeled Coach, REV Group, Braun Industries, Leader Emergency Vehicles, Demers Ambulances, AEV, AmbulanceMed, Medix Specialty Vehicles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Ambulance Vehicle Market Strategic Shifts & Innovations
Connected vehicle architectures and predictive maintenance algorithms are transforming ambulance operations from reactive dispatch to anticipatory healthcare logistics. Three developments are compressing innovation cycles across manufacturing and service delivery.
Telemedicine platforms are digitizing clinical decision-making during transport. Advanced life support crews in urban EMS systems now transmit twelve-lead ECGs and ultrasound imaging to receiving hospitals before arrival. This compression of diagnostic latency is reshaping triage protocols and reducing door-to-balloon times for STEMI patients.
The EU MDR framework and FDA's premarket notification pathway for mobile medical devices are tightening software validation requirements. Ambulance builders must now document cybersecurity controls and electromagnetic compatibility across integrated monitoring systems. European manufacturers face the steepest compliance burden as notified bodies backlog certification reviews.
Consolidated purchasing cooperatives are displacing fragmented municipal procurement across the United States. Regional health authorities in Texas, Florida, and Ohio now issue multi-year fleet contracts with standardized specifications, compressing vendor margins while rewarding scale manufacturing. This concentration is visible most acutely in Sun Belt states where population growth strains existing EMS infrastructure.
Emergency Ambulance Vehicle Market Segmentation
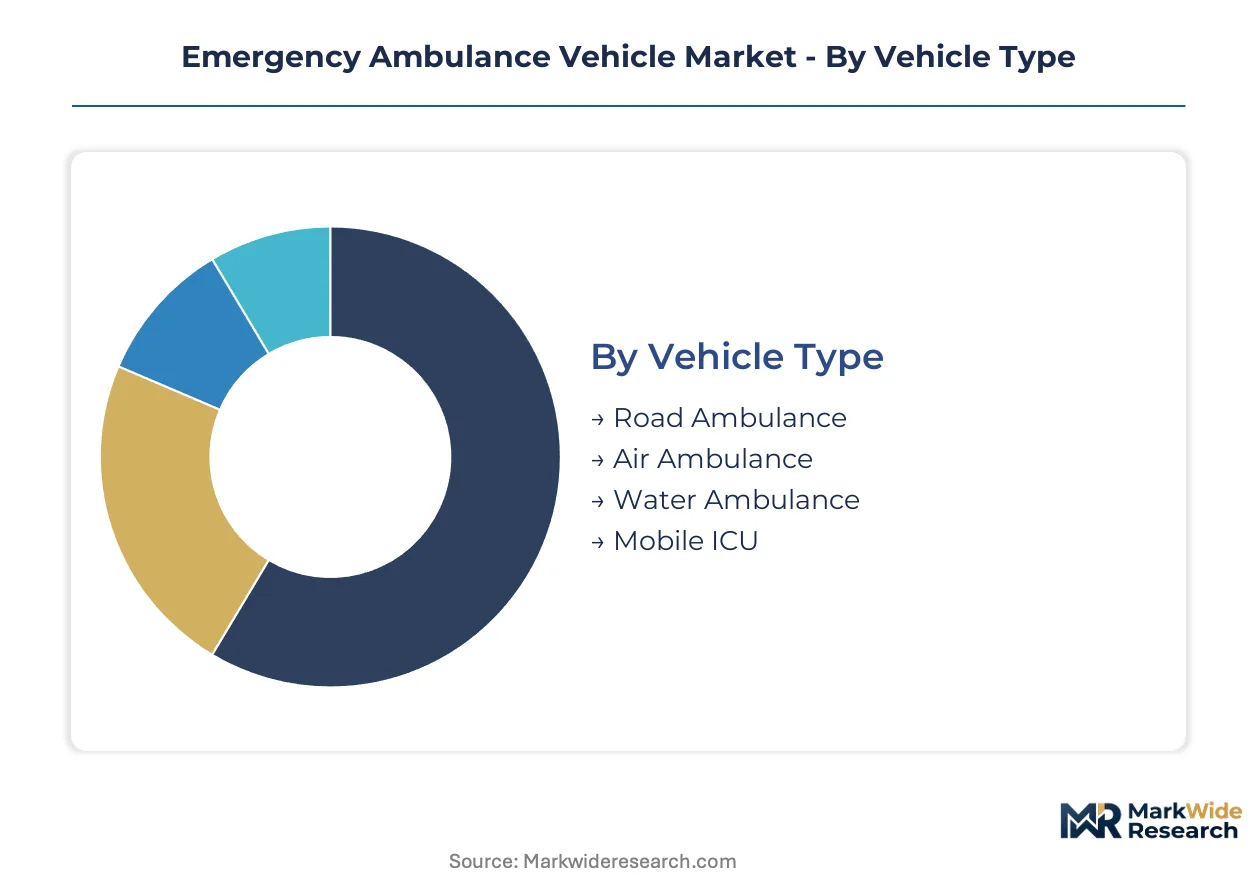
Ambulance procurement patterns diverge sharply across vehicle platforms, clinical applications, and operator business models. Understanding these fault lines reveals where electrification investments concentrate and which technology integrations command premium pricing.
Vehicle Type:
Mature road-based platforms anchor current fleet composition while emerging aerial and aquatic configurations address access gaps.
- Road Ambulance:Purpose-built units on reinforced commercial chassis with custom patient compartments, medical gas plumbing, and ISO-compliant mounting hardware. Municipal EMS departments across Germany, Japan, and the United States drive replacement demand as aging populations strain response capacity.
- Air Ambulance:Rotary-wing and fixed-wing platforms configured for aeromedical evacuation with specialized crew training and remote-area access capabilities. Premium pricing reflects operational complexity and regulatory certification requirements under FAA and EASA frameworks.
- Water Ambulance:Marine vessels equipped for coastal and riverine emergency transport in archipelago nations and flood-prone regions.
- Mobile ICU:High-acuity transport units with ventilator support, dialysis capability, and multi-parameter monitoring for inter-facility transfers.
Road ambulance retains volume leadership; air ambulance holds the steepest expansion curve.
Application:
Cost tiers separate acute emergency response from scheduled patient movement and contingency deployment scenarios.
- Emergency Medical Services:Rapid response units configured for pre-hospital clinical intervention during cardiac, trauma, and stroke events. NHTSA crashworthiness standards and EU MDR certification requirements shape procurement specifications for public fleet operators.
- Patient Transport:Scheduled non-emergency relocation between healthcare facilities, nursing homes, and dialysis centers. Private operators in the Netherlands and Denmark are piloting vehicle-as-a-service contracts that bundle maintenance into per-mile pricing.
- Disaster Management:Mass-casualty configurations deployable during natural disasters, industrial accidents, and public health emergencies.
- Event Medical Support:Temporary on-site coverage for sporting events, concerts, and large public gatherings.
Emergency medical services commands the dominant revenue share; disaster management is climbing the fastest as climate resilience budgets expand.
Technology:
Margin structures favor integrated clinical systems over standalone navigation or tracking functions.
- Telemedicine:Real-time physician consultation platforms transmitting twelve-lead ECGs and ultrasound imaging during transport. Compression of diagnostic latency is reshaping triage protocols and reducing door-to-balloon times for STEMI patients.
- GPS Navigation:Route optimization systems reducing response times in dense urban environments and rural territories lacking landmark clarity.
- Vehicle Tracking:Fleet telematics enabling predictive maintenance and anticipatory healthcare logistics.
- Advanced Life Support Systems:Integrated ventilators, defibrillators, and infusion pumps with ISO-compliant electrical safety certification.
Advanced life support systems retains installed-base dominance; telemedicine is gaining share fastest as hospital IT integration matures.
End User:
Customer type determines financing structures, equipment refresh cycles, and regulatory compliance burdens.
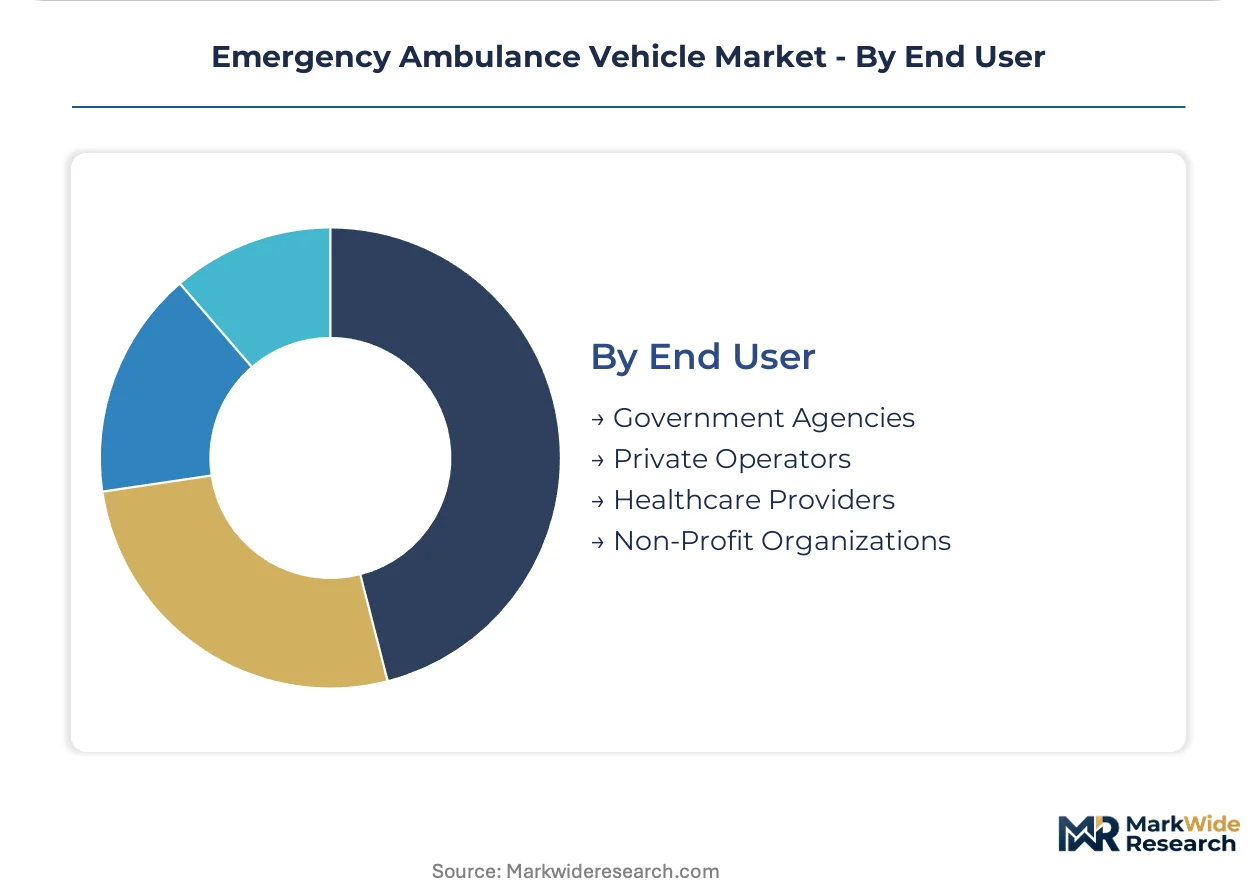
- Government Agencies:Municipal, state, and national EMS departments operating under public procurement rules. Consolidated purchasing cooperatives in Texas, Florida, and Ohio now issue multi-year fleet contracts with standardized specifications.
- Private Operators:For-profit ambulance companies and hospital-affiliated transport services.
- Healthcare Providers:Hospital systems operating captive fleets for inter-facility transfers.
- Non-Profit Organizations:Charitable emergency services and humanitarian relief organizations.
Government agencies account for the largest procurement volume; private operators are expanding most quickly through subscription fleet models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal EMS departments in aging urban centers drive procurement concentration across developed healthcare systems, while emerging economies expand fleet infrastructure to address rural coverage gaps.
United States
Cardiac and stroke call volumes surge across metropolitan EMS networks in Texas, Florida, and Ohio. NHTSA rollover testing and side-impact requirements shape chassis specifications for fleet replacement cycles. Consolidated purchasing cooperatives in Sun Belt states now issue multi-year contracts with standardized vehicle configurations.
Germany
Aging demographics strain municipal response capacity in Berlin, Munich, and Hamburg metropolitan regions. EU MDR framework mandates ISO-compliant mounting hardware and electrical safety certification for all new ambulance deployments. Baden-Württemberg industrial clusters host specialized body fabricators serving Central European export markets.
China
Rural healthcare infrastructure expansion drives demand for basic life support configurations in western provinces. NMPA medical device registration and MIIT commercial vehicle standards govern local assembly partnerships. Yangtze River Delta manufacturing hubs concentrate electric chassis production for municipal fleet electrification programs.
India
Vast underserved territories in Bihar, Uttar Pradesh, and Madhya Pradesh lack emergency transport infrastructure. CDSCO certification pathways and BIS standards for medical devices enable local assembly partnerships. Maharashtra industrial corridors near Pune and Nashik host emerging ambulance body fabrication facilities.
Japan
Super-aging society demographics compress emergency response times in Tokyo, Osaka, and Nagoya conurbations. METI vehicle safety standards and PMDA medical device regulations govern high-acuity mobile ICU specifications. Kanto region manufacturers specialize in compact urban ambulance configurations for dense metropolitan deployment.
Emergency Ambulance Vehicle Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that rewards manufacturing scale and regulatory certification speed. Tier-one chassis suppliers Ford, Mercedes-Benz, and Ram constrain ambulance builders' sourcing leverage through light-commercial van platform oligopoly. Strategic archetypes separate aluminum-body lightweight specialists, multi-facility scale manufacturers, and modular interior configuration experts. Dominant competitive moves include geographic expansion through local assembly partnerships and technology licensing for electrified power take-off integration.
Among North American fabricators, Horton Emergency Vehicles, REV Group, and Demers Ambulances occupy distinct positioning within the competitive spectrum. Horton Emergency Vehicles represents the lightweight construction archetype through proprietary aluminum body methods. REV Group exemplifies multi-facility scale manufacturing with distributed production capacity for rapid fleet fulfillment. Demers Ambulances anchors the modular configuration specialist tier with adaptable interior systems for advanced life support integration.
| Leading Market Players |
|---|
| Horton Emergency Vehicles |
| Wheeled Coach |
| REV Group |
| Braun Industries |
| Leader Emergency Vehicles |
| Demers Ambulances |
| AEV |
| AmbulanceMed |
| Medix Specialty Vehicles |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta manufacturing hubs concentrate electric chassis production for municipal fleet electrification programs, compressing procurement timelines for ambulance builders while amplifying price leverage for integrated powertrain suppliers. Cost-plus contracts with aluminum indexation dominate municipal procurement in Germany and the United States, insulating body fabricators from raw material volatility while passing cathode material exposure to fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates air ambulance configurations from road-based advanced life support units and basic transport vehicles. Price differentiation hinges on ISO 17840 electrical safety certification and NHTSA crashworthiness tier. Cost compression in standard-tier road ambulances is intensifying because consolidated purchasing cooperatives in Texas and Florida extract volume discounts. Private operators in the Netherlands and Denmark show least price sensitivity due to vehicle-as-a-service bundling.
Pricing Analysis
Cost-plus contracts with aluminum indexation dominate municipal procurement in Germany and the United States, insulating body fabricators from raw material volatility while passing cathode material exposure to fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates air ambulance configurations from road-based advanced life support units and basic transport vehicles. Price differentiation hinges on ISO 17840 electrical safety certification and NHTSA crashworthiness tier. Cost compression in standard-tier road ambulances is intensifying because consolidated purchasing cooperatives in Texas and Florida extract volume discounts. Private operators in the Netherlands and Denmark show least price sensitivity due to vehicle-as-a-service bundling.
Supply Chain Analysis
Lithium carbonate and cobalt hydroxide feedstock processing centers on China, South Korea, and the Democratic Republic of Congo, tethering electric ambulance battery costs to concentrated upstream refining. Aluminum sheet and extrusions for lightweight body construction draw from German and Canadian smelters, while commercial van chassis production rests on Ford, Mercedes-Benz, and Ram manufacturing footprints across North America and Europe. Single-source vulnerability in cathode precursor supply exposes fleet electrification timelines to export licensing disruptions. Distribution runs through municipal procurement cooperatives in Sun Belt states and regional health authorities in Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment creates substantial switching costs for municipal fleet operators locked into NHTSA and EU MDR certification pathways.
For Market Incumbents: Pre-empt emerging electric chassis supply constraints by securing long-term offtake agreements with Yangtze River Delta battery manufacturers before cathode material export restrictions tighten. Accelerate ISO 17840 technician training programs across North American service networks to capture maintenance revenue from electrified municipal fleets. Vertical integration into aluminum body fabrication through acquisition of Baden-Württemberg specialized fabricators defends margin position against lightweight construction specialists. For New Entrants and Emerging Players: Build out CDSCO-certified local assembly partnerships in Maharashtra industrial corridors to address India's vast rural coverage gaps in Bihar and Uttar Pradesh. Target hybrid power take-off configurations as the most penetrable technology segment, bridging fleet operator hesitation on full electrification while delivering stationary power advantages. Pursue vehicle-as-a-service subscription models with Dutch and Danish municipalities as the primary go-to-market angle, bundling telematics and equipment refresh into per-mile pricing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular interior configuration specialists with adaptable advanced life support integration capabilities over aluminum-body lightweight pure-plays facing range-compression tradeoffs. Long-term viability over the projection horizon rests on regulatory certification speed and multi-facility manufacturing scale rather than proprietary materials science. Acquisition target archetype: regional body fabricators with established EU MDR notified body relationships and scalable electric platform adaptation. Watch NHTSA electrification mandate signaling as the inflection indicator for chassis supply reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body backlog compression enables faster market access for compliant ambulance builders ahead of retrofit conversion bans. |
| Electric Chassis Supply Agreement | Long-term Ford E-Transit or Mercedes-Benz eSprinter allocation secures production slots before municipal electrification mandates tighten. |
| Telemedicine Platform Integration | Real-time ECG and ultrasound transmission capability differentiates advanced life support configurations in consolidated procurement bids. |
| Local Assembly Partnership in India | CDSCO and BIS certification through Maharashtra facilities unlocks vast rural coverage expansion in underserved northern states. |
| ISO 17840 Technician Training Network | High-voltage safety certification scarcity across North American service networks creates captive aftermarket revenue streams. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal EMS fleet managers, ambulance body fabrication plant directors, hospital biomedical engineers, and GPO contracts administrators. Secondary validation drew from NHTSA safety standard filings, EU MDR notified body certification databases, FDA premarket notification pathways for mobile medical devices, and municipal procurement cooperative contract disclosures. Bottom-up ambulance unit demand estimates triangulated against top-down healthcare infrastructure spending allocations across Germany, the United States, China, and India.
Calibration against historical fleet replacement cycles and electrification mandate implementation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include vehicle platform type, clinical application tier, technology integration level, and end-user procurement structure. CAGRs were derived from logistic diffusion curves for electric platform adoption intersecting with demographic call volume projections. Industry-specific forecast inputs incorporated NMPA medical device registration timelines in China and CDSCO certification pathway durations for local assembly partnerships.
Sensitivities concentrate around cathode material export restrictions, NHTSA rollover standard revisions, and EU MDR notified body processing backlogs. Forecasts embed assumptions on municipal budget continuity and chassis manufacturer electrification roadmaps. Cross-checking against IHS Markit commercial vehicle production data and hospital capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Retail Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Parking Services Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Tow Truck Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Cab Services Market
Automotive Services
Car Wash System Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Brushless Car Wash Machine Market