
 Vehicle Health Monitoring Market | 2026-2036
Vehicle Health Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Health Monitoring Market Intelligence
Silicon carbide is decoupling vehicle health monitoring from legacy silicon-based sensor architectures, cutting thermal losses and enabling higher-frequency signal processing. Robert Bosch leverages captive semiconductor fabrication to control sensor cost curves across European OEM programs. Continental dominates embedded systems integration for powertrain diagnostics. KPIT specializes in AI-based monitoring software stacks for commercial vehicle platforms.
Vehicle health monitoring encompasses onboard sensor networks, telemetry acquisition hardware, and cloud-connected analytics platforms that continuously assess powertrain, brake, battery, and chassis system integrity through CAN bus data streams and wireless transmission protocols. The primary industrial purpose centers on preventing unplanned downtime, extending component life, and ensuring regulatory compliance across fleet operations. Predictive analytics now captures the fastest expansion trajectory as fleet operators demand failure-forecasting capabilities that shift maintenance from scheduled intervals to condition-based triggers. Telematics devices retain the largest installed base but face margin compression as hardware commoditizes. AI-based monitoring and machine learning algorithms concentrate where software differentiation determines contract renewals and platform stickiness.
NHTSA mandates event data recorder standards and cybersecurity management systems for connected vehicles, compelling suppliers to certify monitoring architectures against federal crash-investigation protocols. EPA emissions enforcement and the EU Green Deal's CO2 tracking requirements are expanding data-retention obligations for engine and battery health logs. ISO 26262 functional safety standards and UNECE WP.29 cybersecurity regulations further gate market access for non-compliant hardware. Fleet operators and technology vendors must decide whether to build sovereign data infrastructure or cede platform control to tier-one integrators as regulatory fragmentation deepens.
Market Dynamics
Silicon carbide semiconductor adoption is compressing thermal management costs while NHTSA and EPA mandates force fleet operators into continuous data-logging architectures. Tier-one suppliers now capture platform economics that once flowed to hardware vendors.
Growth Catalysts
- NHTSA Event Data Recorder Mandates:Federal crash-investigation protocols compel commercial fleets to install certified monitoring architectures. This creates installed-base pull-through for predictive analytics subscriptions.
- Silicon Carbide Sensor Migration:Wide-bandgap semiconductors enable higher-frequency signal processing at lower thermal loss. Powertrain diagnostics now capture transient fault signatures invisible to legacy silicon architectures.
- Stuttgart-Munich Engineering Corridor:Germany's automotive R&D concentration accelerates OEM validation cycles. Tier-one suppliers co-locate engineering teams to compress platform development timelines.
Market Restraints
- Telematics Hardware Commoditization:Embedded cellular modules face margin compression as Chinese contract manufacturers scale production. Device vendors lose pricing power to platform aggregators.
- UNECE WP.29 Certification Burden:Cybersecurity management system audits add twelve-to-eighteen month approval timelines. Non-compliant suppliers forfeit access to European OEM programs.
- Cloud Infrastructure Concentration:Fleet data aggregation depends on three hyperscale providers. Operator anxiety over vendor lock-in slows multi-year platform commitments.
Strategic Opportunities
- AI-Based Condition Monitoring:Machine learning failure-forecasting shifts maintenance from interval-based to trigger-based. Software differentiation determines contract renewal rates.
- Commercial Vehicle Electrification:Battery health monitoring for electric powertrains requires new sensor modalities. Cell-level voltage sensing and thermal runaway prediction create greenfield demand.
- EPA Emissions Enforcement Expansion:Enhanced data-retention obligations for engine health logs mandate expanded telemetry deployment. Aftermarket retrofit opportunities emerge in legacy diesel fleets.
Industry Challenges
- ISO 26262 Functional Safety Talent Scarcity:ASIL-D certification expertise concentrates at established tier-one suppliers. Mid-size monitoring vendors struggle to staff safety-critical development teams.
- Legacy Fleet Integration Complexity:Pre-CAN-vehicle architectures lack standardized data buses. Retrofit hardware requires custom signal conditioning for each powertrain variant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Health Monitoring Market |
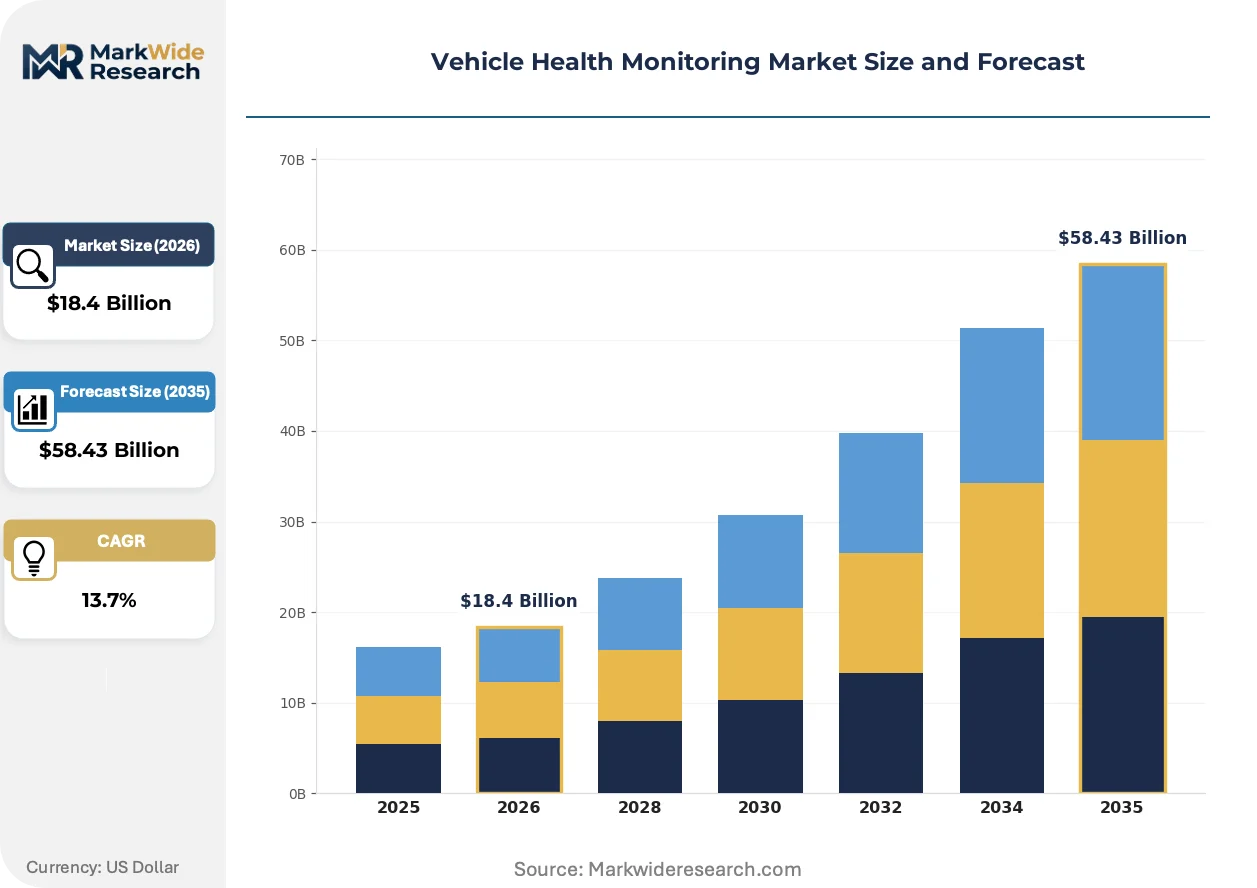
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $58.43 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onboard Diagnostics, Predictive Analytics, Wireless Sensors, Telematics Devices, Embedded Systems Technology: AI-Based Monitoring, Cloud Computing, IoT Integration, Machine Learning Algorithms, Edge Computing Use Case: Fleet Management, Driver Assistance, Maintenance Scheduling, Fuel Efficiency Optimization, Vehicle Safety Enhancement End User: Commercial Fleets, Logistics Companies, Rental Services, Transportation Providers, Delivery Operators |
| Companies Covered | ZF Friedrichshafen, Denso Corporation, Robert Bosch, Vector Informatik, Cummins, Continental, KPIT, OnStar, Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Health Monitoring Market Strategic Shifts & Innovations
Edge computing architectures are relocating inference workloads from cloud data centers to onboard vehicle gateways. This shift compresses latency for safety-critical fault detection while reducing cellular data transmission costs.
Silicon carbide power electronics is expanding into onboard sensor power conditioning and signal amplification circuits. Commercial fleet operators in North American long-haul trucking are retrofitting SiC-based monitoring modules to capture high-frequency bearing vibration signatures. The technology is expanding into applications previously served by silicon IGBT drivers, enabling continuous monitoring at operating temperatures above 150°C.
EU Green Deal CO2 tracking requirements are extending data-retention obligations from engine diagnostics to full vehicle energy flow monitoring. OEMs must now archive battery state-of-health records for eight years post-vehicle registration. European commercial fleet operators are responding by consolidating telematics contracts with suppliers offering EU-hosted data sovereignty guarantees.
Subscription-based predictive maintenance contracts are displacing perpetual-license software sales in commercial vehicle segments. Fleet operators in Germany and the United States now prioritize vendors offering uptime guarantees over hardware ownership. This preference shift concentrates contract value with platform providers capable of absorbing operational risk.
Vehicle Health Monitoring Market Segmentation
Vehicle health monitoring architectures fragment across hardware, software, and service layers that demand distinct procurement strategies. Fleet operators prioritize integration depth over point solutions, compressing vendor margins in commoditized hardware while amplifying value capture in predictive software stacks.
Product Type:
Customization intensity varies sharply across this spectrum, from standardized telematics hardware to deeply embedded powertrain diagnostics requiring OEM-specific calibration.
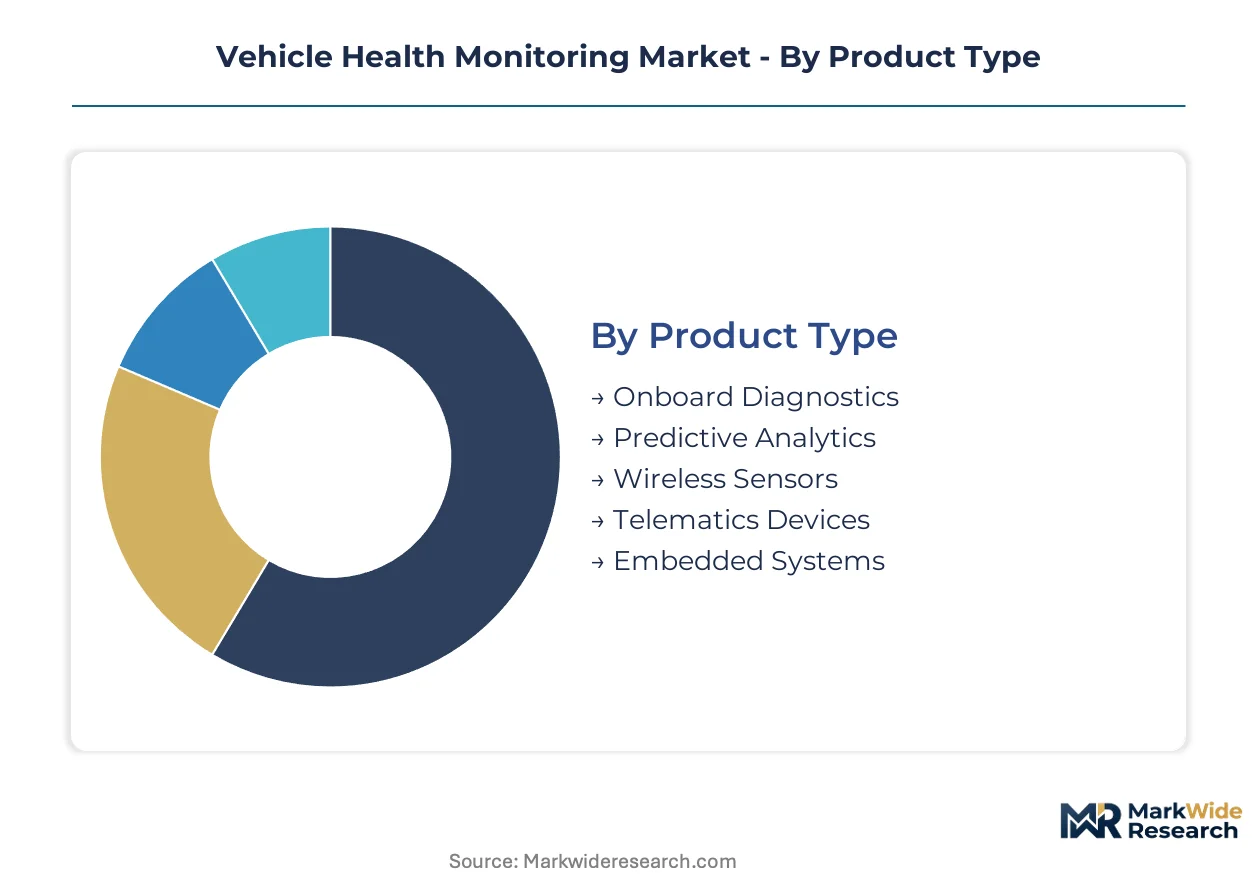
- Predictive Analytics:Cloud-based failure-forecasting platforms process CAN bus telemetry through machine learning models trained on component degradation patterns. Demand concentrates in North American long-haul trucking fleets seeking uptime guarantees from condition-based maintenance triggers. NHTSA data-retention mandates amplify subscription stickiness by locking operators into certified analytics architectures.
- Onboard Diagnostics:OBD-II compliant hardware modules capture standardized powertrain fault codes for regulatory emissions testing and fleet compliance reporting. German commercial operators around Stuttgart prioritize units with EU-hosted data sovereignty to satisfy Green Deal CO2 tracking obligations.
- Wireless Sensors:Battery-powered vibration and temperature monitors transmit via low-power wide-area networks to edge gateways.
- Telematics Devices:Embedded cellular modules face margin compression as contract manufacturers scale production.
- Embedded Systems:ASIL-D certified controllers integrate directly into powertrain ECUs for real-time fault response.
Most installed capacity flows through Telematics Devices. Expansion is steepest in Predictive Analytics.
Technology:
Processing location determines cost structure, with cloud-dependent architectures carrying recurring transmission expenses that edge-native alternatives eliminate.
- AI-Based Monitoring:Deep learning models trained on historical failure data generate component-specific remaining useful life estimates. Logistics operators in the United States prioritize vendors offering uptime-backed service contracts that shift operational risk to platform providers. EPA emissions enforcement expansion mandates AI-driven anomaly detection for engine health log verification.
- Edge Computing:Onboard inference engines process sensor data locally to compress latency for safety-critical brake and steering fault detection. Fleet operators in Germany's Stuttgart-Munich corridor deploy SiC-powered edge gateways to capture high-frequency bearing signatures above 150°C operating temperatures.
- Machine Learning Algorithms:Supervised classification models identify degradation patterns from structured telemetry streams.
- Cloud Computing:Centralized data lakes aggregate multi-vehicle fleets for cross-asset benchmarking.
- IoT Integration:Protocol translation layers harmonize heterogeneous sensor buses into unified data models.
Cloud Computing carries the largest current deployment base. Edge Computing is climbing the fastest as latency requirements tighten.
Use Case:
Application maturity correlates with regulatory enforcement intensity, with emissions-linked use cases commanding premium pricing versus discretionary efficiency tools.
- Fleet Management:Integrated platforms combining telemetry acquisition, route optimization, and maintenance orchestration for multi-asset operations. North American delivery operators consolidate contracts with vendors offering unified uptime guarantees across vehicle classes. NHTSA event data recorder mandates create installed-base pull-through for fleet-wide monitoring subscriptions.
- Vehicle Safety Enhancement:Real-time chassis and brake system monitoring triggers immediate driver alerts and autonomous intervention protocols. German automotive engineering corridors validate safety-critical architectures against ISO 26262 ASIL-D requirements before OEM program adoption.
- Maintenance Scheduling:Condition-based trigger systems replace calendar-interval service planning.
- Fuel Efficiency Optimization:Engine operating parameter recommendations reduce consumption in legacy diesel fleets.
- Driver Assistance:Behavioral scoring from vehicle dynamics data informs coaching programs.
Fleet Management dominates current contract value. Vehicle Safety Enhancement is gaining share fastest from regulatory mandates.
End User:
Procurement sophistication stratifies by fleet scale, with large operators demanding API-accessible data lakes while smaller buyers accept bundled SaaS interfaces.
- Commercial Fleets:Owned-vehicle operators with centralized maintenance facilities and captive technical staff. United States-based long-haul trucking fleets retrofit SiC monitoring modules to capture EPA-mandated engine health telemetry. These operators negotiate direct platform contracts bypassing tier-one integrators.
- Logistics Companies:Third-party operators managing heterogeneous vehicle pools across multiple OEM brands. German logistics providers consolidate telematics contracts with EU-hosted data sovereignty guarantees to satisfy Green Deal eight-year battery record retention rules.
- Transportation Providers:Public transit and intercity bus operators with regulated service continuity obligations.
- Delivery Operators:Last-mile parcel and food delivery fleets with high vehicle turnover.
- Rental Services:Short-term vehicle providers prioritizing damage detection and fuel verification.
Commercial Fleets account for the deepest installed base. Logistics Companies show the steepest expansion trajectory from cross-border fleet consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-Munich engineering corridor anchors European development velocity for vehicle health monitoring platforms. North American commercial fleets drive predictive analytics demand through NHTSA compliance mandates. Asian manufacturing centers scale embedded sensor production for export markets.
United States
Long-haul trucking operators retrofit SiC-based monitoring modules to capture high-frequency bearing vibration signatures. NHTSA event data recorder mandates compel certified architectures for federal crash-investigation protocols. Detroit-Warren automotive clusters validate edge computing gateways for powertrain diagnostics.
Germany
Commercial fleet operators consolidate telematics contracts around EU-hosted data sovereignty guarantees. EU Green Deal eight-year battery record retention rules expand telemetry deployment obligations. Stuttgart engineering corridors compress OEM validation cycles through co-located tier-one supplier teams.
China
Domestic OEMs integrate battery health monitoring for electric powertrain platforms at manufacturing scale. MIIT connected vehicle standards mandate cybersecurity management systems for data-logging architectures. Yangtze River Delta electronics manufacturing clusters supply cellular modules for telematics hardware.
Japan
Automotive semiconductor fabricators supply SiC sensor power conditioning circuits to European OEM programs. METI carbon neutrality targets accelerate fleet electrification and battery monitoring retrofit demand. Nagoya-Toyota industrial corridors specialize in ASIL-D certified embedded controllers.
India
Commercial vehicle manufacturers adopt AI-based monitoring software stacks for domestic logistics platforms. Automotive PLI scheme incentives attract tier-one suppliers to establish embedded systems engineering centers. Tamil Nadu automotive clusters host validation facilities for powertrain diagnostics.
Vehicle Health Monitoring Market Key Industry Players
Strategic partnerships dominate the current landscape as tier-one suppliers capture platform economics from hardware vendors. The vendor base stratifies across three tiers: integrated automotive conglomerates with captive semiconductor fabrication, specialized embedded software developers, and commoditized telematics device manufacturers. Two structural archetypes define competitive positioning: full-stack platform providers bundling hardware-software-service layers, and component specialists supplying certified modules to integrators. M&A activity concentrates on AI-based predictive analytics capabilities, while geographic expansion targets EU-hosted data infrastructure for Green Deal compliance.
Within the integrated tier, Robert Bosch exemplifies captive semiconductor control through in-house SiC sensor production for European OEM programs. Continental occupies a position as embedded systems integration anchor for powertrain diagnostics. KPIT represents the software-specialist archetype, anchoring AI-based monitoring stacks for commercial vehicle platforms.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Denso Corporation |
| Robert Bosch |
| Vector Informatik |
| Cummins |
| Continental |
| KPIT |
| OnStar |
| Visteon Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up telematics hardware specialists have consolidated manufacturing footprints across Shenzhen and Dongguan, compressing component procurement costs while stripping pricing power from device vendors serving North American fleet operators. This ownership pattern feeds directly into subscription-based predictive analytics pricing, where platform providers capture recurring revenue streams that offset hardware margin erosion.
Pricing Analysis
Silicon carbide wafer costs pass through directly to module pricing, with SiC-based monitoring gateways commanding premium positioning over legacy silicon alternatives. Pricing stratifies across ASIL-D certified embedded systems, mid-tier OBD-II compliant hardware, and commoditized cellular telematics devices. Cost compression in telematics modules is intensifying because Yangtze River Delta contract manufacturers scale production of embedded cellular units. Commercial fleets with centralized technical staff exhibit lowest price sensitivity, while small delivery operators with high vehicle turnover remain most price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements from European OEMs mandate qualified suppliers for both SiC power conditioning circuits and ASIL-D certified microcontrollers, forcing tier-one integrators to maintain relationships with Japanese semiconductor fabricators and German automotive electronics specialists. The supply chain draws from Taiwan for foundry capacity, Japan for precision sensor components, and China for cellular module assembly. Single-source vulnerability concentrates in 200mm SiC wafer supply. Distribution runs through tier-one automotive suppliers who bundle monitoring modules into platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle health monitoring functions as a stable compounder, with regulatory mandates from NHTSA and EPA creating durable installed-base expansion that outpaces cyclical automotive production swings.
For Market Incumbents: Lock in platform economics by deepening backward integration into SiC sensor fabrication and securing EU-hosted data infrastructure certifications before Green Deal retention rules harden. Defend against emerging AI-native software vendors by embedding predictive analytics into powertrain ECU firmware, creating switching costs that subscription-only competitors cannot match. For New Entrants and Emerging Players: Begin with battery health monitoring for electric commercial vehicle retrofits, where cell-level voltage sensing and thermal runaway prediction lack established solution providers. Target logistics operators managing heterogeneous fleets across multiple OEM brands, who prioritize vendor-agnostic platforms over captive tier-one offerings. Lead with edge computing architectures that compress latency for safety-critical fault detection. For Investors and Strategic Acquirers: Valuations sit cheapest among telematics hardware vendors facing margin compression, while AI-based predictive analytics specialists command premium multiples. The long-term viability window favors platform providers capable of absorbing operational risk through uptime-backed service contracts. Watch for inflection when EPA emissions enforcement triggers mandatory retrofit demand in legacy diesel fleets.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Sensor Fabrication Investment | Captive semiconductor production insulates Bosch and Continental from wafer supply constraints. |
| EU Data Sovereignty Certification | Green Deal eight-year retention rules lock fleet operators into EU-hosted platform contracts. |
| Predictive Analytics Acquisition | Machine learning failure-forecasting determines contract renewal rates in commercial vehicle segments. |
| Edge Computing Gateway Deployment | Onboard inference engines reduce cellular transmission costs for North American long-haul operators. |
| ASIL-D Functional Safety Certification | ISO 26262 compliance gates access to European OEM powertrain diagnostic programs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, tier-one supplier procurement managers, OEM platform engineers, and aftermarket service heads with secondary validation against NHTSA regulatory filings, EPA enforcement databases, vehicle production statistics from IHS Markit, and SEC disclosures from listed automotive suppliers. Bottom-up segment sizing triangulated against top-down market estimates derived from telematics device shipments and predictive analytics subscription revenues.
Segment-weighting approaches distributed value across hardware, software, and service layers according to procurement patterns observed in commercial fleet operator surveys. The analytical framework modeled technology adoption curves, use case maturity, and end-user scale stratification across the projection horizon. CAGRs were derived from regression analysis of historical telematics penetration rates and regulatory mandate implementation timelines. Forecast inputs incorporated SiC semiconductor cost curves and NHTSA event data recorder compliance deadlines.
Several conditions sit outside the modeled scope, including potential harmonization of UNECE WP.29 cybersecurity standards with divergent national implementations, and breakthrough battery chemistries that might obviate current thermal runaway prediction architectures. Deviation in EPA enforcement intensity or NHTSA mandate delay would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Recycling Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Duster Market