
 Connected Vehicle Market | 2026-2036
Connected Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Vehicle Market Analysis
The gap between embedded automotive hardware and cloud-native software architectures is narrowing as automakers restructure development cycles around over-the-air update pipelines. Continental AG leverages its sensor-to-cloud portfolio to anchor integrated cockpit and telematics systems across European and Asian programs. Robert Bosch GmbH sustains deep manufacturing scale in powertrain control modules while extending software engineering capacity in India and Vietnam. Harman International competes through its dominance in premium audio and connected-car infotainment, occupying a distinct tier above mass-market dashboard suppliers.
A connected vehicle integrates onboard sensors, cellular and short-range wireless modules, edge processors, and cloud backhaul to enable real-time data exchange with infrastructure, other vehicles, and fleet management platforms. Primary commercial purpose centers on predictive maintenance scheduling, collision avoidance, and usage-based insurance underwriting. Vehicle-to-Everything technology leads deployment volumes where latency-critical safety applications command premium module pricing, while telematics services for fleet operators generate recurring revenue streams with higher margin stability than hardware sales. Cloud-based deployment architectures are displacing on-premises alternatives as automakers seek elastic compute for autonomous-driving data lakes.
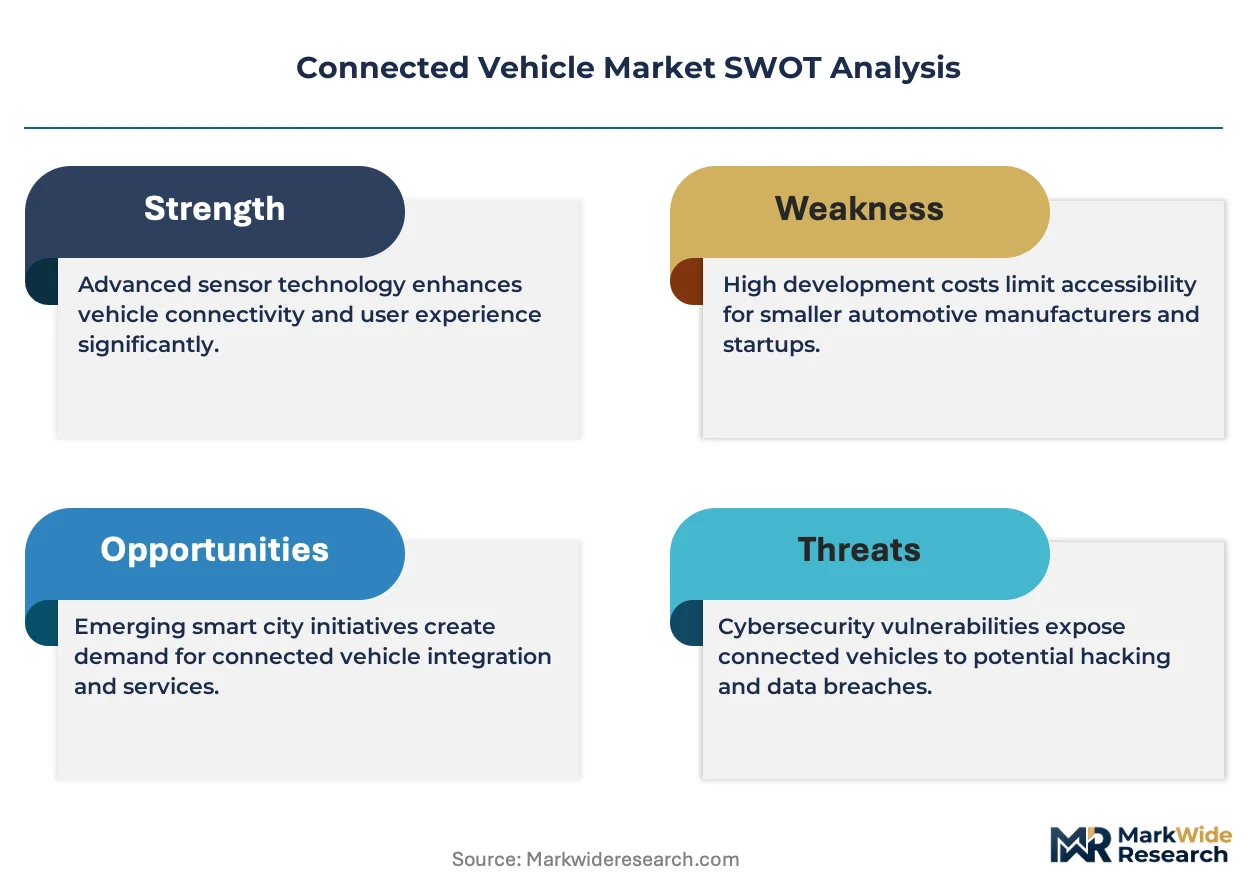
The FCC governs spectrum allocation for dedicated short-range communications in the United States, directly constraining which V2X protocols achieve market viability. ETSI mandates in Europe enforce interoperability standards that shape supplier certification requirements and OEM procurement specifications. The EU AI Act introduces conformity obligations for autonomous-driving algorithms that will filter which software stacks gain type approval. Stakeholders must monitor how cybersecurity regulations evolve across jurisdictions to anticipate where compliance costs will reshape competitive economics.
Market Dynamics
The transition from hardware-centric vehicle architectures to software-defined platforms is compressing development cycles and forcing tier-one suppliers to restructure engineering workforces around continuous integration pipelines rather than discrete model-year releases.
Growth Catalysts
- EU AI Act conformity pathways:The regulation's risk-based classification system for autonomous-driving algorithms is creating certified supplier tiers that OEMs preferentially source from, accelerating consolidation around pre-approved software stacks.
- Fleet telematics monetization:Logistics operators in Germany and the United States are deploying predictive maintenance modules that reduce unplanned downtime through real-time powertrain diagnostics, generating recurring service revenue.
- Edge-to-cloud data pipelines:Cellular V2X module integration is enabling latency-critical collision avoidance applications that command premium hardware pricing compared to basic infotainment connectivity.
Market Restraints
- Semiconductor supply concentration:Advanced driver-assistance system processors depend on Taiwan-based foundry capacity that remains constrained for automotive-grade nodes, creating allocation bottlenecks for European and North American programs.
- FCC spectrum reallocation uncertainty:The regulator's pending decisions on 5.9 GHz band usage for dedicated short-range communications are freezing V2X deployment commitments by risk-averse fleet purchasers.
- Cybersecurity certification costs:ETSI mandatory requirements for vehicle-to-everything encryption are adding engineering overhead that disproportionately burdens mid-volume OEMs lacking dedicated security operations centers.
Strategic Opportunities
- India's automotive software engineering:The country's technical workforce expansion presents captive development center opportunities for European tier-one suppliers seeking cost arbitrage on telematics platform engineering.
- Usage-based insurance integration:Data exchange partnerships between connected vehicle platforms and commercial underwriters in Germany are creating new revenue streams from driving behavior analytics.
- 5G-V2X convergence:The integration of cellular and direct short-range communication protocols is enabling hybrid architectures that satisfy both latency-critical safety and high-bandwidth infotainment requirements.
Industry Challenges
- Embedded software talent scarcity:Automotive-grade functional safety engineering expertise remains concentrated among a limited pool of specialists familiar with ISO 26262 certification requirements.
- Over-the-air validation timelines:Regulatory type approval processes for remote software updates lag behind agile development cycles, forcing OEMs to maintain parallel release tracks for different jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Vehicle Market |
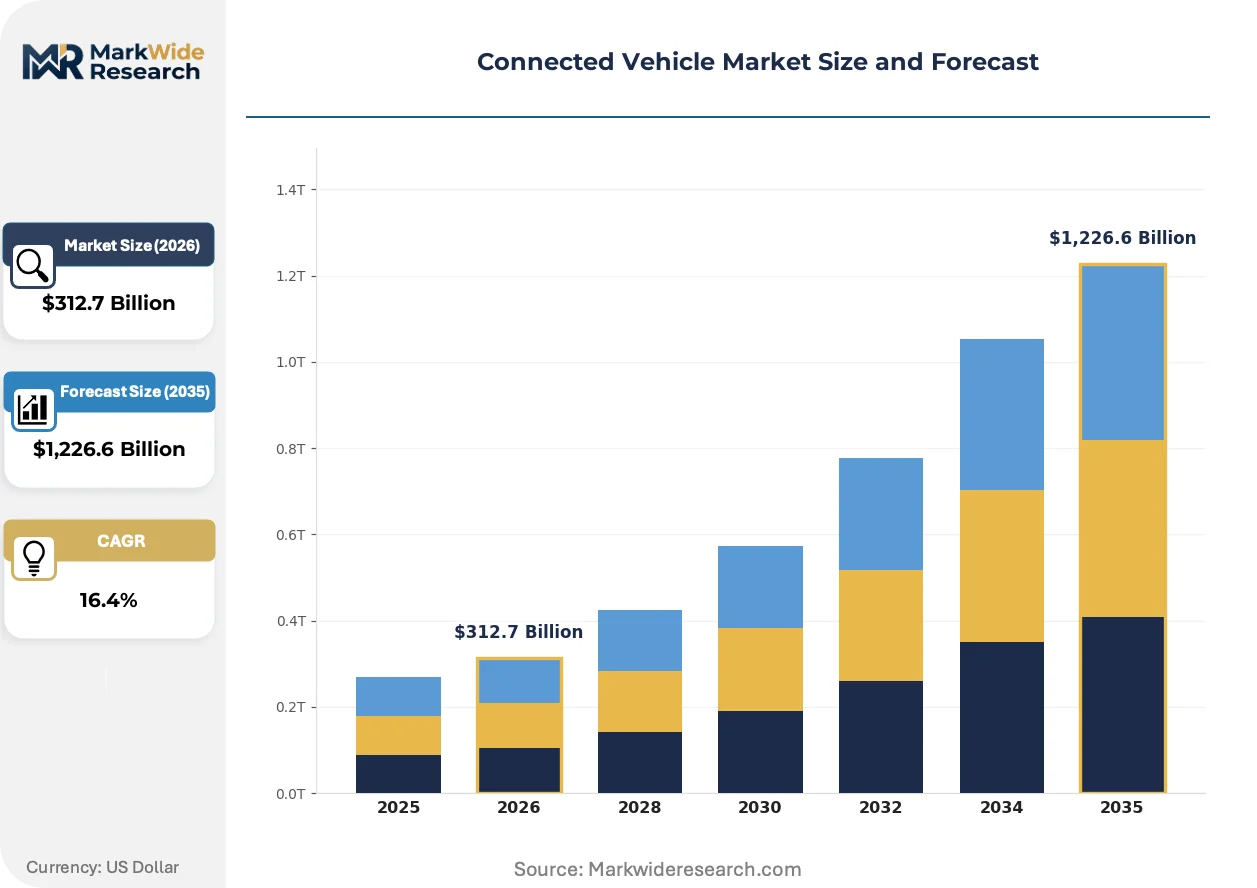
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,226.6 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
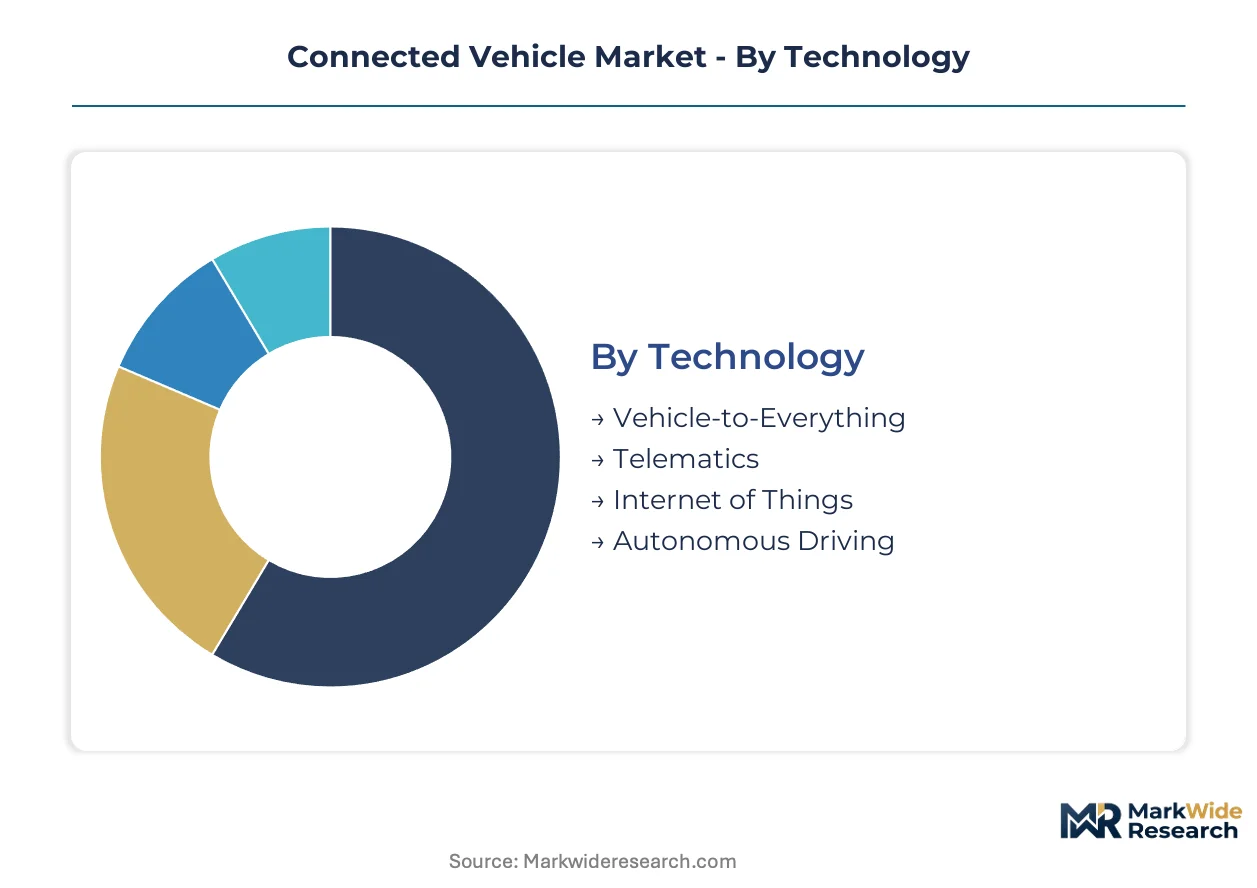
| Segmentation | Technology: Vehicle-to-Everything, Telematics, Internet of Things, Autonomous Driving End User: Fleet Operators, Vehicle Manufacturers, Insurance Companies, Consumers Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Safety & Security, Navigation, Remote Diagnostics, Entertainment |
| Companies Covered | Continental AG, Robert Bosch GmbH, Harman International, AT&T, BMW Group, General Motors, Ford Motor Company, Audi AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Vehicle Market Emerging Trajectories
Software-defined vehicle architectures are collapsing the traditional boundary between electronics hardware and cloud-native development, enabling functionality deployment through remote updates rather than physical module replacement.
Centralized zonal compute platforms are consolidating multiple electronic control units into domain controllers that manage sensor fusion, power distribution, and cabin functions through high-speed Ethernet backbones. Premium OEMs in Germany and the United States are adopting these architectures for 2026 platform launches. The shift is rendering obsolete distributed ECU designs that required physical wiring harness changes for feature upgrades.
The EU AI Act's conformity assessment procedures for autonomous-driving systems are mandating algorithmic transparency documentation that exceeds current automotive software quality standards. European OEM procurement teams now require tier-one suppliers to demonstrate bias testing protocols and human oversight integration. Powertrain control modules with embedded machine learning face extended certification timelines compared to deterministic rule-based alternatives.
Fleet operators are consolidating telematics procurement around integrated platform providers that combine hardware, connectivity, and analytics subscriptions into single-source contracts. This bundling displaces the previous model of separate negotiations for cellular data plans, device hardware, and software licenses. The pattern is most pronounced among North American logistics companies managing mixed-vehicle fleets across state jurisdictions with varying data privacy requirements.
Connected Vehicle Market Segmentation
Connected vehicle architectures fragment across multiple technical and commercial dimensions that determine procurement patterns and margin structures. Technology choices dictate hardware-software integration complexity, while end-user categories separate recurring service revenue from one-time equipment sales. Deployment models and application priorities further stratify supplier relationships and regulatory exposure.
Technology:
Technical differentiation in connected vehicle systems centers on communication protocols, sensor fusion requirements, and the balance between edge processing and cloud dependency.
- Vehicle-to-Everything:Direct short-range communication modules enable latency-critical collision avoidance and traffic signal preemption. German OEMs and tier-one suppliers around Stuttgart prioritize this technology for safety-critical applications where cellular backhaul introduces unacceptable delay. FCC spectrum allocation decisions in the United States directly constrain deployment timelines for fleet operators awaiting regulatory clarity on 5.9 GHz band usage.
- Telematics:Cellular-connected hardware platforms transmit vehicle health data, location, and driver behavior to fleet management dashboards. North American logistics operators scale adoption fastest, driven by fuel cost optimization and insurance premium reduction. Recurring subscription revenue from telematics services delivers margin stability superior to one-time hardware sales.
- Internet of Things:Sensor networks extend connectivity beyond powertrain and chassis to cargo monitoring, trailer tracking, and environmental sensing.
- Autonomous Driving:Multi-sensor fusion systems combining lidar, radar, and camera inputs for conditional automation face extended EU AI Act certification timelines.
Vehicle-to-Everything commands the established base in European safety mandates. The steepest expansion runs through telematics as fleet operators consolidate around integrated platform providers.
End User:
Customer type determines contract structure, pricing power, and the relative importance of hardware durability versus software update frequency.
- Fleet Operators:Commercial vehicle managers procure connected systems through bundled hardware-connectivity-analytics contracts that disaggregate previous separate negotiations. Mixed-fleet logistics companies across Germany and the United States drive standardization demands that pressure mid-volume OEMs lacking dedicated procurement teams.
- Vehicle Manufacturers:OEMs specify embedded modules during platform development, prioritizing supplier scale and type-approval track records over unit cost minimization. Development center concentration around Munich and Stuttgart creates geographic clustering in European sourcing decisions.
- Insurance Companies:Commercial underwriters in Germany leverage driving behavior analytics from connected platforms to refine usage-based premium calculations.
- Consumers:Individual purchasers prioritize infotainment integration and smartphone mirroring over predictive maintenance or safety-critical V2X functionality.
Fleet operators dominate current procurement volume. Vehicle manufacturers anchor long-term platform roadmaps that constrain supplier switching.
Deployment:
Infrastructure architecture choices separate elastic compute scalability from data sovereignty and latency constraints.
- Cloud-Based:Elastic compute resources support autonomous-driving data lakes and over-the-air update pipelines that compress development cycles. Automakers restructure engineering workforces around continuous integration rather than discrete model-year releases as cloud-native architectures displace on-premises alternatives.
- On-Premises:Dedicated server installations persist where data residency requirements or air-gapped security protocols override scalability considerations.
- Hybrid:Architectures partition latency-critical safety functions to edge modules while offloading analytics and infotainment to cloud backhaul.
- Edge Computing:In-vehicle processors handle sensor fusion and immediate decision-making without network dependency.
Cloud-based deployment captures the majority of new platform investment. Edge computing gains share fastest where cellular coverage inconsistency threatens safety-critical function availability.
Application:
Functional use cases determine sensor specifications, regulatory certification pathways, and the balance between mandatory and discretionary spending.
- Safety & Security:Collision avoidance, emergency calling, and stolen vehicle tracking face mandatory homologation requirements that filter supplier eligibility. ETSI cybersecurity mandates add engineering overhead that disproportionately burdens mid-volume OEMs lacking dedicated security operations centers.
- Navigation:Real-time traffic integration and predictive routing leverage cloud connectivity for map updates and congestion data.
- Remote Diagnostics:Powertrain health monitoring enables predictive maintenance scheduling that reduces unplanned downtime for commercial fleets.
- Entertainment:Premium audio and streaming integration commands distinct supplier tiers above mass-market dashboard providers.
Safety and security applications command regulatory-mandated deployment. Entertainment functions expand most quickly as consumer expectations for smartphone-equivalent cabin experience intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports connected vehicle modules and software stacks to North American and Asian OEMs through established automotive supplier corridors. The trade flow concentrates development expertise in Stuttgart and Munich while assembly programs scale across multiple continents.
United States
Fleet telematics procurement by logistics operators drives module demand across Texas and California distribution corridors. FCC spectrum allocation decisions for the 5.9 GHz band constrain V2X deployment timelines for commercial vehicle manufacturers. Detroit-based engineering centers coordinate tier-one supplier qualification for integrated cockpit systems.
Germany
OEMs around Stuttgart and Munich anchor European demand for vehicle-to-everything safety modules and autonomous-driving software stacks. EU AI Act conformity pathways filter supplier eligibility through algorithmic transparency requirements. Baden-Württemberg hosts concentrated development activity between OEM technical centers and tier-one electronics suppliers.
China
Domestic EV manufacturers scale connected platform deployment across Yangtze River Delta and Pearl River Delta production bases. MIIT cybersecurity standards for intelligent connected vehicles mandate data localization and encryption protocols. Shanghai-based engineering operations coordinate software-defined vehicle architectures for export programs.
India
European tier-one suppliers establish captive development centers in Bangalore and Pune for telematics platform engineering cost arbitrage. PLI scheme incentives for automotive electronics manufacturing attract module assembly investments. Karnataka and Maharashtra concentrate technical workforce expansion for embedded software talent pipelines.
Japan
Denso Corporation and domestic OEMs anchor demand for sensor fusion modules and edge computing platforms in Aichi Prefecture. METI standardization efforts for connected vehicle cybersecurity shape procurement specifications for export programs. Nagoya-Tokyo industrial corridors coordinate tier-one supplier certification for Asian market deployment.
Connected Vehicle Market Vendor Landscape
On the supply side, the industry is tiered between diversified automotive electronics conglomerates, specialized infotainment providers, and telecommunications infrastructure operators. The structure concentrates around three strategic archetypes: sensor-to-cloud integrators, premium cockpit experience specialists, and connectivity service platforms. Dominant competitive moves include portfolio diversification into software-defined vehicle architectures and strategic partnerships between tier-one suppliers and cloud infrastructure providers.
Within the diversified electronics tier, Continental AG and Robert Bosch GmbH exemplify scale-driven suppliers with integrated manufacturing and software engineering capabilities. Harman International occupies a distinct position representing premium-tier infotainment specialization above mass-market dashboard providers. AT&T anchors the telecommunications vector as a connectivity platform operator serving fleet and consumer segments through cellular infrastructure integration.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Harman International |
| AT&T |
| BMW Group |
| General Motors |
| Ford Motor Company |
| Audi AG |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Taiwan-based foundry concentration for automotive-grade semiconductor nodes feeds directly into margin compression for European and North American module suppliers lacking captive silicon sourcing. Tier-one electronics suppliers pass through wafer allocation premiums to OEM procurement teams, concentrating pricing power upstream while fleet telematics providers absorb downstream cost pressure.
Pricing Analysis
Next-generation cellular V2X modules command substantial premiums over legacy 4G telematics hardware, while prior-generation DSRC units face accelerated depreciation. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 functional safety certification grade and volume scale commitments. Cost compression in mid-volume OEM programs is intensifying because ETSI cybersecurity certification overhead disproportionately burdens suppliers lacking dedicated security operations centers. Fleet operators demonstrate highest price sensitivity due to hardware-connectivity-analytics bundling demands, while premium German OEMs prioritize supplier track records over unit cost minimization.
Supply Chain Analysis
Automotive-grade silicon feedstock draws from Taiwan, South Korea, and Japan for advanced driver-assistance system processors. Module assembly hinges on China, Mexico, and Germany for printed circuit board fabrication, sensor packaging, and final system integration. Single-source vulnerability concentrates in Taiwan-based foundry capacity for 7nm and 5nm automotive nodes. Distribution runs through tier-one supplier direct sales to OEM platform engineering teams, with aftermarket telematics channels serving fragmented fleet operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected vehicle market constitutes a high-growth disruption as EU AI Act conformity pathways filter supplier eligibility and compress development cycles around over-the-air update architectures.
For Market Incumbents: Insulate embedded software margins by acquiring ISO 26262-certified engineering teams in India and Vietnam before talent scarcity intensifies. Deepen backward integration into edge processor design to offset Taiwan foundry allocation risk. Consolidate around pre-approved software stacks as EU AI Act risk-based classifications create certified supplier tiers that OEMs preferentially source from. For New Entrants and Emerging Players: India's underpenetrated captive development center market offers white-space expansion for telematics platform engineering serving European tier-one suppliers. Target usage-based insurance data exchange partnerships with German commercial underwriters as the most penetrable revenue stream. Pursue direct cloud infrastructure partnerships with automakers restructuring around continuous integration pipelines rather than discrete model-year releases. For Investors and Strategic Acquirers: Capital is best deployed toward sensor-to-cloud integrators with demonstrated EU AI Act conformity track records and established OEM platform engineering relationships. Long-term viability favors suppliers combining hardware manufacturing scale with software-defined vehicle architecture investments. Watch FCC 5.9 GHz spectrum allocation decisions as the critical inflection indicator for V2X deployment commitment timelines across North American fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables functionality deployment through over-the-air updates rather than physical module replacement cycles. |
| 5G-V2X Module Integration | Supports hybrid architectures satisfying latency-critical safety and high-bandwidth infotainment requirements simultaneously. |
| EU AI Act Conformity Certification | Creates algorithmic transparency documentation barriers that filter tier-one supplier eligibility for autonomous-driving programs. |
| Captive Development Center Expansion | Captures cost arbitrage on telematics engineering through Bangalore and Pune technical workforce pipelines. |
| Cloud Infrastructure Partnership | Supplies elastic compute for autonomous-driving data lakes displacing on-premises deployment alternatives. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, fleet telematics operators, and cloud infrastructure architects converged on the working assumptions. Primary interviews combined with secondary validation against vehicle production databases, IHS Markit registration data, FCC spectrum filings, and ETSI standardization documents. Bottom-up module shipment analysis and top-down OEM platform content triangulation anchored volume estimates.
Demand-supply-balance framing modeled connected vehicle architecture adoption across the analysis window through vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segment-level shipment trajectories weighted by module pricing tiers. Forecast inputs incorporated EU AI Act implementation timelines and FCC spectrum reallocation uncertainty scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese EV manufacturers on software-defined architectures or hyperscaler cloud providers on automotive edge computing would shift outcomes. Material shifts in Taiwan semiconductor foundry capacity allocation or EU AI Act enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Self-Driving Shuttle Market