
 Airbag Repair Service Market | 2026-2036
Airbag Repair Service Market Size, Share, and Industry Trends Forecast 2026-2036
Airbag Repair Service Market Insights
The EU Green Deal is expanding requirements for component reuse and waste reduction across automotive aftermarkets. Safety Restore leverages proprietary reset technology to anchor its position in inflation module refurbishment. MyAirbags competes through direct-to-consumer channels that bypass traditional dealership markups. Airbag Team specializes in module-only repairs that reduce material waste compared with full-system replacement.
Airbag repair service encompasses the diagnostic, refurbishment, and recertification of deployed or fault-triggered supplemental restraint systems, including pyrotechnic inflator replacement, crash sensor recalibration, and seatbelt pretensioner restoration to original equipment performance thresholds. Inflation module repair commands the deepest margin pools due to proprietary reset protocols and limited technician certification, while diagnostic testing represents the fastest-growing entry point as telematics-enabled remote fault detection expands. Independent repair shops absorb the majority of off-warranty volume, though fleet services are consolidating demand through centralized procurement of mobile repair contracts.
NHTSA in the United States enforces strict recall compliance timelines that sustain replacement demand even where repair is technically feasible, while the EU's CE marking and MDR frameworks impose traceability requirements on refurbished safety components. Japan's METI coordinates domestic standards for pyrotechnic handling that limit cross-border service arbitrage. Stakeholders must monitor diverging national post-repair certification rules that will determine whether centralized refurbishment hubs or localized micro-factories capture scale economies.
Market Dynamics
Extended vehicle lifecycles across developed economies are pressuring owners to maintain aging supplemental restraint systems rather than absorb total replacement costs. The EU Green Deal's circular economy mandates now explicitly favor component refurbishment over disposal, redirecting service flows toward certified repair networks.
Growth Catalysts
- EU Green Deal circular economy mandates:Waste reduction targets for automotive components now require documented reuse protocols, creating legal preference for refurbishment over replacement.
- Telematics-enabled remote diagnostics:Connected vehicle platforms transmit fault codes directly to service providers, compressing detection-to-repair timelines and expanding addressable incident volume.
- Germany's TÜV inspection regime:Biennial safety certification requirements sustain specialized repair demand in Europe's highest-density passenger vehicle market.
Market Restraints
- Pyrotechnic material cost volatility:Sodium azide and nitroguanidine prices fluctuate with chemical feedstock markets, squeezing margin on inflator replacement services.
- NHTSA recall compliance timelines:Strict replacement mandates for recalled components override technical repair feasibility in the US market, diverting volume from refurbishment channels.
- Cross-border service arbitrage limits:Japan's METI pyrotechnic handling standards prevent foreign technicians from servicing domestic vehicles, fragmenting scale economies.
Strategic Opportunities
- Fleet service centralization:Commercial vehicle operators are consolidating mobile repair contracts through single-source procurement, bypassing fragmented dealer networks.
- CE marking traceability requirements:MDR frameworks for refurbished safety components create first-mover advantage for providers with documented quality systems.
- Module-only repair protocols:Seatbelt pretensioner and crash sensor recalibration services address warranty-expired vehicles without full-system replacement overhead.
Industry Challenges
- Technician certification scarcity:Pyrotechnic handling licenses require specialized training programs that few vocational institutions currently offer.
- Post-repair certification fragmentation:Divergent national approval rules for refurbished airbag systems complicate hub-and-spoke service models.
- Legacy sensor integration complexity:Pre-2010 vehicle architectures lack standardized diagnostic ports, requiring manual recalibration procedures that extend service times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airbag Repair Service Market |
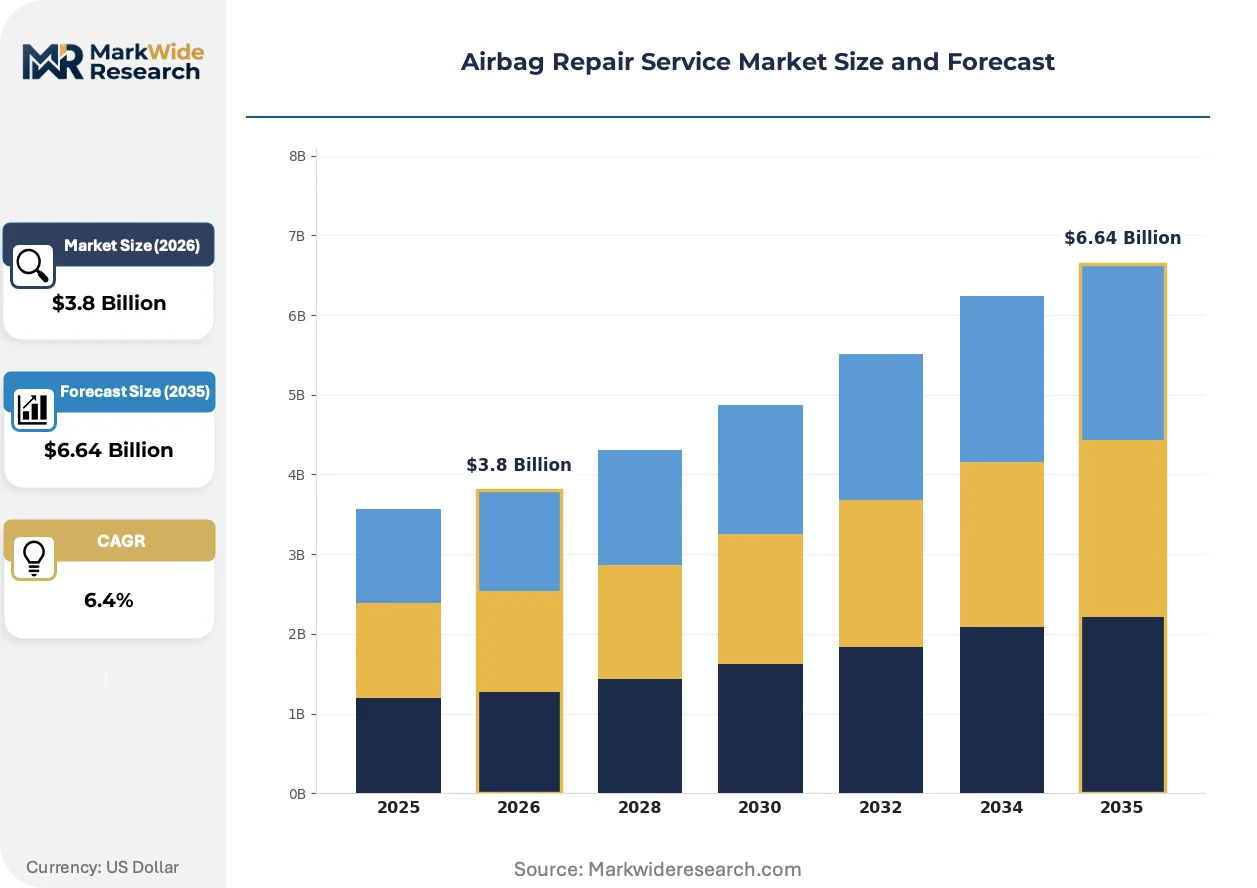
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inflation Module Repair, Sensor Calibration, Wiring Harness Repair, Diagnostic Testing End User: Automotive OEMs, Independent Repair Shops, Insurance Companies, Fleet Services Vehicle Type: Passenger Cars, Commercial Trucks, Motorcycles, SUVs Repair Model: On-Site Repair, Off-Site Service, Mobile Repair, Warranty Service |
| Companies Covered | Airbag Service, Accurate Care Automotive, Safety Restore, CrashData, WhoCanFixMyCar, Airbagbank, AirbagTeam, Airbag Repair Centre, MyAirbags, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airbag Repair Service Market Trends and Innovations
Diagnostic automation and refurbishment protocols are compressing service delivery timelines while regulatory traceability requirements reshape competitive positioning around certification depth rather than geographic coverage alone.
Remote fault detection platforms are converging with cloud-based calibration databases to enable technician dispatch before vehicle arrival at service bays. Independent repair shops adopt these systems fastest where dealer network density is lowest. The technology is converging with predictive maintenance algorithms that flag inflator degradation patterns before deployment failure.
EU MDR traceability mandates now require serialized component histories for all refurbished safety devices entering member state markets. Manufacturers must maintain auditable records linking original equipment specifications to post-repair performance thresholds. German KBA type-approval processes are tightening documentation requirements fastest, advantaging incumbent specialists with existing quality management systems.
Fleet managers now unbundle after-sales service contracts from vehicle procurement agreements, awarding repair volumes through competitive tender rather than captive dealer relationships. Commercial operators in high-mileage segments prioritize turnaround speed over brand affiliation. This pattern concentrates procurement power most visibly in Germany's dense logistics corridor stretching from Rhine-Ruhr to Bavaria.
Airbag Repair Service Market Segmentation
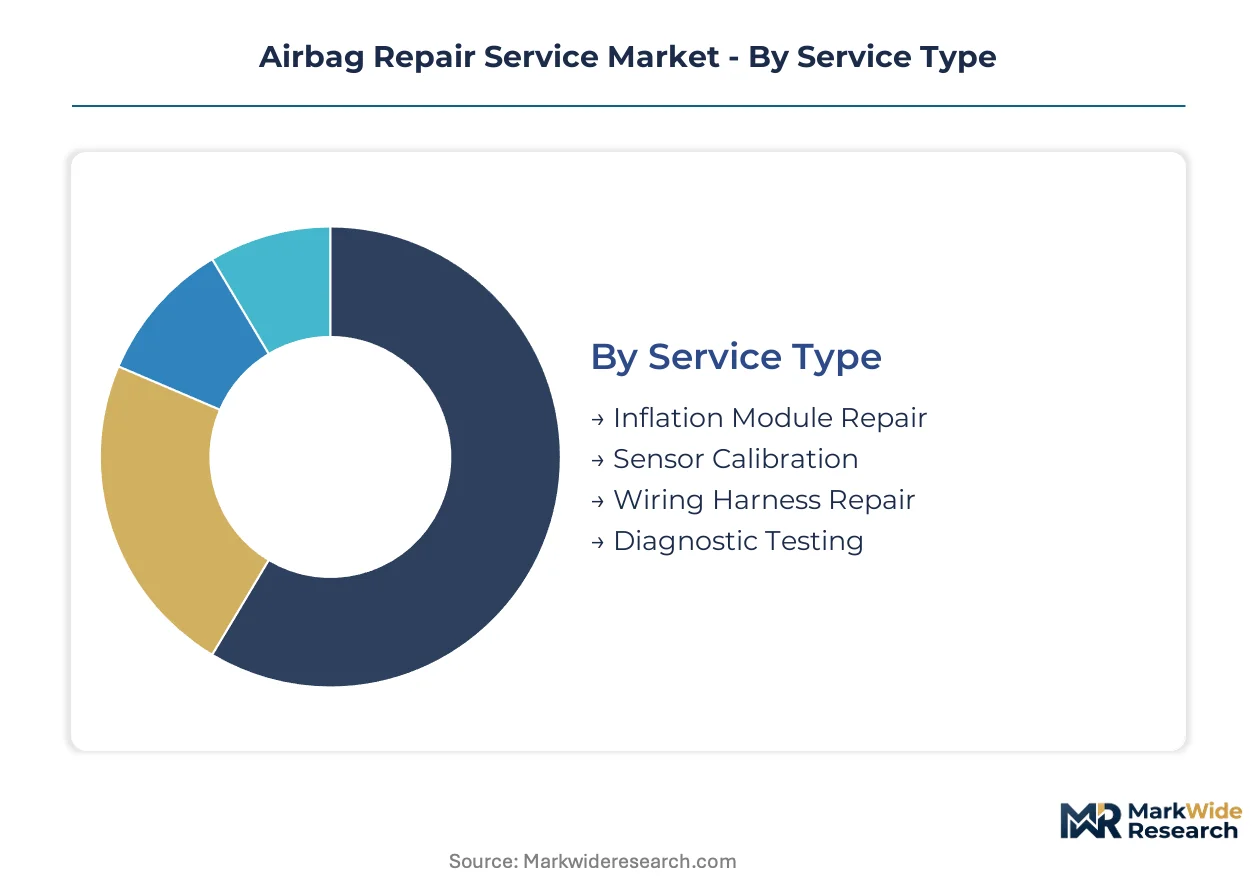
Segmentation in the airbag repair service market reveals how specialized capabilities concentrate around high-margin refurbishment protocols and divergent certification requirements across service delivery models. Understanding these divisions exposes where proprietary technology creates defendable positions versus commoditized competition.
Service Type:
Supply concentrates in diagnostic and refurbishment workflows where proprietary reset technology limits technician pool expansion.
- Inflation Module Repair:Pyrotechnic inflator replacement and gas generator refurbishment require specialized handling licenses and controlled-environment facilities. Demand clusters in Germany's TÜV-regulated inspection corridors where documented reuse protocols satisfy EU Green Deal mandates.
- Diagnostic Testing:Remote fault code interpretation through telematics platforms compresses detection-to-repair timelines. Fleet operators in high-mileage logistics corridors adopt these services fastest where vehicle downtime carries penalty costs.
- Sensor Calibration:Crash sensor recalibration restores original deployment thresholds without full-system replacement.
- Wiring Harness Repair:Electrical pathway restoration addresses corrosion and collision damage in aging vehicle populations.
Today's leader: Inflation Module Repair. Tomorrow's challenger: Diagnostic Testing.
End User:
Cost tier separation between captive OEM networks and independent channels determines margin capture and volume access.
- Fleet Services:Centralized procurement of mobile repair contracts consolidates previously fragmented demand. Commercial vehicle operators unbundle after-sales agreements from vehicle purchase contracts, awarding volumes through competitive tender rather than dealer affiliation.
- Independent Repair Shops:Off-warranty volume absorption depends on diagnostic equipment investment and technician certification depth. These operators adopt cloud-based calibration databases fastest where dealer network density is lowest.
- Automotive OEMs:Warranty-period service maintains brand-controlled customer relationships.
- Insurance Companies:Claims cost containment drives repair-over-replacement authorization protocols.
Fleet Services command procurement leverage today; Independent Repair Shops are climbing the fastest as vehicle age profiles extend.
Vehicle Type:
Application complexity varies dramatically across passenger protection requirements and commercial duty cycles.
- Passenger Cars:Dense sensor arrays and multi-stage deployment systems create intricate refurbishment protocols. Extended vehicle lifecycles across developed economies pressure owners toward module-only repairs rather than total replacement costs.
- Commercial Trucks:High-utilization duty cycles accelerate supplemental restraint system wear. Fleet managers prioritize turnaround speed over brand affiliation, concentrating procurement power in logistics-dense corridors.
- SUVs:Rollover protection systems add curtain and side-impact complexity.
- Motorcycles:Limited airbag adoption restricts addressable repair volume.
Passenger Cars anchor current revenue; Commercial Trucks represent the steepest expansion trajectory as fleet centralization accelerates.
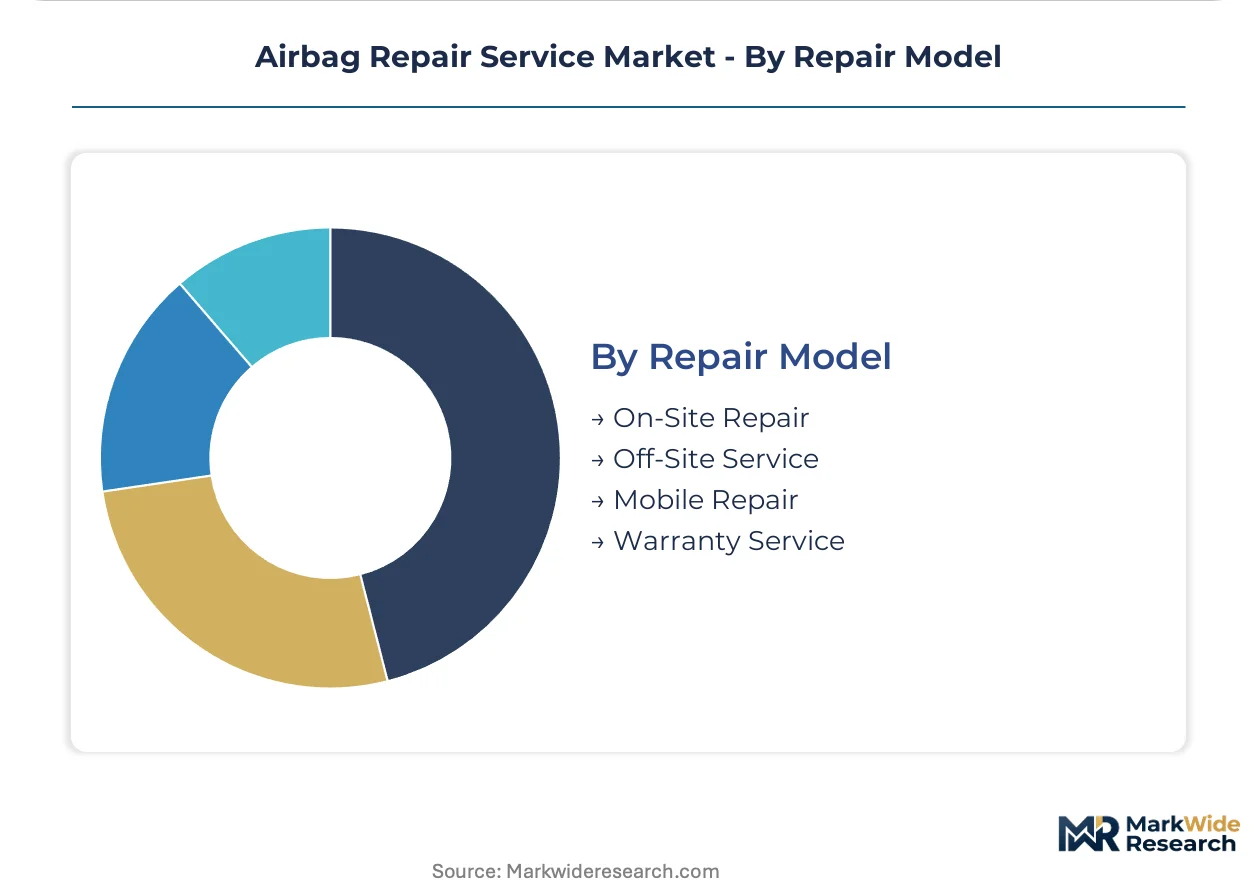
Repair Model:
Geography of service delivery—fixed facility versus mobile—shapes capital intensity and technician utilization economics.
- Mobile Repair:Technician dispatch to vehicle location eliminates transport downtime and bay congestion. Germany's dense logistics corridor from Rhine-Ruhr to Bavaria demonstrates concentrated adoption where fleet density justifies route optimization.
- Off-Site Service:Centralized refurbishment hubs exploit scale economies in pyrotechnic handling and quality documentation. EU MDR traceability mandates favor providers with auditable serialized component histories.
- On-Site Repair:Fixed-location service maintains traditional dealer and independent shop workflows.
- Warranty Service:OEM-captive protocols restrict refurbishment options in favor of replacement.
Off-Site Service dominates margin capture today; Mobile Repair is gaining share fastest as fleet procurement patterns shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified pyrotechnic technicians cluster in Germany's automotive corridors, where TÜV inspection density sustains specialized repair networks. Japan's METI-licensed specialists concentrate in Nagoya and Osaka manufacturing zones. United States-based technicians face NHTSA replacement mandates that limit refurbishment scope.
Germany
TÜV-certified workshops in Bavaria and North Rhine-Westphalia handle the densest passenger car inspection volumes in Europe. The EU Green Deal's circular economy mandates explicitly prioritize documented component reuse over disposal, redirecting service flows toward KBA-registered refurbishment hubs. Stuttgart's automotive cluster hosts concentrated inflation module reset operations serving Rhine-Ruhr logistics fleets.
United States
Independent repair shops in Texas and California absorb the majority of off-warranty supplemental restraint system volume. NHTSA recall compliance timelines enforce strict replacement protocols for defective components, diverting technical repair feasibility toward non-recall incidents. Detroit's legacy manufacturing base sustains specialized sensor calibration networks for pre-2010 vehicle architectures.
Japan
METI-licensed technicians in Nagoya and Osaka face restricted cross-border service arbitrage due to domestic pyrotechnic handling standards. The country's centralized type-approval system favors localized micro-factories over hub-and-spoke refurbishment models. Toyota City maintains captive technician training programs tied to domestic OEM warranty networks.
United Kingdom
Post-Brexit divergence from EU MDR traceability requirements creates parallel certification pathways for refurbished safety components. Independent garages in the Midlands and Greater London adopt cloud-based diagnostic platforms fastest where dealer network density thins. Birmingham's automotive aftermarket cluster specializes in wiring harness restoration for aging fleet vehicles.
China
MIIT-coordinated standards for supplemental restraint systems are tightening documentation requirements for independent repair channels. Yangtze River Delta manufacturing zones concentrate domestic airbag module production, limiting refurbishment demand to warranty-expired import vehicles. Shanghai's commercial fleet operators pilot centralized mobile repair contracts bypassing traditional dealership structures.
Airbag Repair Service Market Competitive Landscape
Capital-heavy refurbishment hubs compete with asset-light diagnostic platforms for technician deployment and customer acquisition. The market fragments across three tiers: OEM-captive warranty networks, certified independent specialists, and unlicensed regional operators. Two strategic archetypes dominate—proprietary reset technology holders and direct-to-consumer channel builders. Competitive moves concentrate on technician certification scale and telematics integration partnerships.
Within the proprietary technology tier, Safety Restore and MyAirbags exemplify divergent channel strategies. Safety Restore anchors position through controlled-environment refurbishment protocols. MyAirbags occupies the direct-to-consumer vector, bypassing traditional dealership markups through mail-in service models. AirbagTeam sits within the module-only repair specialization, reducing material waste compared with full-system replacement protocols.
| Leading Market Players |
|---|
| Airbag Service |
| Accurate Care Automotive |
| Safety Restore |
| CrashData |
| WhoCanFixMyCar |
| Airbagbank |
| AirbagTeam |
| Airbag Repair Centre |
| MyAirbags |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists across Germany's TÜV-certified workshop networks have consolidated diagnostic equipment procurement, compressing input costs while preserving premium pricing power for inflation module reset protocols. This ownership pattern concentrates refurbishment capacity in controlled-environment facilities that extract margin through proprietary technician certification rather than geographic coverage.
Pricing Analysis
Bundled full-system replacement services command substantial premiums over unbundled module-only repairs, with fleet operators negotiating volume discounts that independent shops cannot match. Price differentiation hinges on TÜV certification tier and pyrotechnic handling license depth, with KBA-registered hubs capturing margin pools unavailable to unlicensed competitors. Cost compression in diagnostic testing intensifies as cloud-based calibration platforms democratize fault code interpretation. Insurance companies exhibit highest price sensitivity, authorizing repair-over-replacement only where documentation satisfies claims protocols.
Supply Chain Analysis
Pyrotechnic chemical supply rests on German specialty chemical producers, Chinese sodium azide processors, and Japanese nitroguanidine refiners for gas generator inputs. Refurbishment workflows draw from serialized inflator cores, controlled-environment chamber equipment, and telematics diagnostic hardware. Single-source vulnerability concentrates in METI-licensed pyrotechnic handling certification programs that limit technician pool expansion. Distribution runs through KBA-registered refurbishment hubs serving TÜV inspection corridors, with mobile repair units bypassing fixed facility overhead in fleet-dense logistics zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airbag repair service represents a late-cycle quality story as extended vehicle lifecycles force owners toward documented refurbishment protocols that satisfy EU Green Deal reuse mandates rather than absorb total replacement costs.
For Market Incumbents: Acquire proprietary reset technology portfolios to consolidate technician certification scale against emerging cloud-based diagnostic platforms. Secure controlled-environment facility capacity in Rhine-Ruhr logistics corridors before fleet procurement centralization accelerates. METI licensing restrictions in Japan create captive domestic markets where first-mover certification depth defends margin pools. For New Entrants and Emerging Players: Capture diagnostic testing volume through telematics integration partnerships where dealer network density thins fastest. Independent repair shops in Texas and California present the most penetrable entry points for remote fault detection platforms. Direct-to-consumer mail-in models bypass traditional dealership markups and extract margin from price-sensitive passenger car owners. For Investors and Strategic Acquirers: Valuations sit cheapest among unlicensed regional operators facing EU MDR traceability compliance costs that favor scaled incumbents with existing quality management systems. Long-term viability hinges on regulatory certification depth rather than geographic coverage alone. Watch NHTSA recall compliance timeline relaxations as the signal for refurbishment volume inflection in the US market.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Scale-Up | EU MDR traceability mandates favor providers with auditable pyrotechnic handling programs. |
| Telematics Platform Integration | Remote fault detection compresses detection-to-repair timelines for fleet operators. |
| Mobile Repair Network Expansion | Germany's dense logistics corridor demonstrates concentrated adoption where fleet density justifies route optimization. |
| Proprietary Reset Technology Acquisition | Controlled-environment refurbishment protocols anchor defendable margin positions. |
| KBA-Registered Hub Consolidation | Centralized refurbishment captures scale economies in pyrotechnic handling and quality documentation. |
Research Methodology
Multiple input streams — structured interviews with TÜV-certified workshop operators, fleet procurement managers, and pyrotechnic handling instructors, alongside regulatory filing analysis and vehicle registration databases — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from KBA type-approval records, EU MDR compliance documentation, NHTSA recall databases, and METI licensing registries.
Historical volume trajectories were cross-referenced against expert panel inputs covering service type segmentation, repair model geography, and end-user procurement patterns across the projection horizon. CAGRs were derived from modeled interactions between extended vehicle lifecycle trends, circular economy mandate enforcement intensity, and telematics adoption curves. Forecast inputs incorporated technician certification pipeline constraints and pyrotechnic material cost volatility assumptions.
Regulatory timeline shifts, pyrotechnic feedstock price spikes, and cross-border service arbitrage liberalization are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about EU Green Deal implementation pacing and fleet procurement centralization velocity. A small set of named triggers — NHTSA recall protocol modifications, METI licensing reciprocity agreements, and CE marking MDR enforcement intensity — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automatic Tire Changer Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Tow Truck Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
GCC Car Rental Market