
 Variable Refrigerant Flow (VRF) System Market | 2026-2036
Variable Refrigerant Flow (VRF) System Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Refrigerant Flow (VRF) System Market Intelligence
ISO 5149 certification for refrigerating systems and heat pumps is rotating the competitive landscape by filtering out suppliers lacking third-party thermal performance validation. Daikin Industries leverages captive compressor manufacturing to sustain margin control across multi-zone installations. Mitsubishi Electric anchors premium positioning through proprietary two-pipe heat recovery architectures. Johnson Controls competes on building automation integration, extending its Metasys platform into native VRF supervisory layers.
A Variable Refrigerant Flow system modulates refrigerant volume to multiple indoor evaporator coils from a single outdoor condensing unit, typically operating with R-410A or lower-GWP alternatives at part-load efficiencies exceeding conventional chiller-loop designs by fifteen to thirty percent. Heat pump configurations dominate unit shipments in temperate climates, while heat recovery variants command superior margins by enabling simultaneous heating and cooling across building zones. Inverter compressor technology leads the technology dimension, with magnetic bearing scroll systems representing the fastest-growing sub-category in data center applications where acoustic restrictions apply.
EPA SNAP program rules on hydrofluorocarbon phase-down and the EU F-Gas Regulation are forcing refrigerant transitions toward R-32 and HFO blends, reshaping product development cycles and service technician certification requirements. Japan's METI Top Runner program and China's GB energy efficiency standards for multi-connected air conditioners create divergent compliance burdens for manufacturers serving multiple export destinations. Stakeholders must monitor refrigerant patent expirations and regional service infrastructure buildout as determinants of which technology platforms achieve scalable deployment.
Market Dynamics
Inverter-driven compressor technology is compressing fixed-speed alternatives across Southeast Asian commercial construction, while municipal energy code tightening accelerates specification of heat recovery VRF configurations.
Growth Catalysts
- Heat Recovery Configurations:Municipal energy codes in Vietnam, Thailand, and Indonesia now mandate simultaneous heating and cooling capabilities in mixed-use developments, driving specification of proprietary two-pipe architectures.
- ISO 5149 Certification:Third-party thermal performance validation is filtering supplier pools, creating competitive advantage for manufacturers with captive compressor manufacturing and certified testing infrastructure.
- Inverter Compressor Adoption:Magnetic bearing scroll systems are penetrating data center applications where acoustic restrictions apply, displacing conventional chiller-loop designs in noise-sensitive installations.
Market Restraints
- Refrigerant Transition Costs:EPA SNAP program rules on hydrofluorocarbon phase-down and EU F-Gas Regulation are forcing R-410A to R-32 and HFO blend transitions, extending product development cycles and requiring service technician recertification.
- Divergent Compliance Burdens:Japan's METI Top Runner program and China's GB energy efficiency standards for multi-connected air conditioners create conflicting certification requirements for manufacturers serving multiple export destinations.
- Patent Infrastructure Dependency:Scalable deployment of lower-GWP alternatives depends on refrigerant patent expirations and regional service infrastructure buildout timelines that lag hardware availability.
Strategic Opportunities
- Building Automation Integration:Native VRF supervisory layers compatible with established building management platforms offer white space for controls specialists extending into HVAC system orchestration.
- Urban Hospitality Concentration:Vietnam's resort corridor developments and Indonesia's Jakarta mixed-use towers present underpenetrated specification channels for premium heat recovery configurations.
- Acoustic-Sensitive Sub-Segments:Magnetic bearing scroll technology convergence with precision cooling requirements creates entry points in data center and healthcare laboratory applications.
Industry Challenges
- Technician Certification Compression:Refrigerant transitions toward R-32 and HFO blends require simultaneous retraining of installation and service workforces across multiple national certification frameworks.
- Legacy System Integration Friction:Existing building automation protocols and proprietary two-pipe architectures create interoperability complexity when retrofitting heat recovery capabilities into operational structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Refrigerant Flow (VRF) System Market |
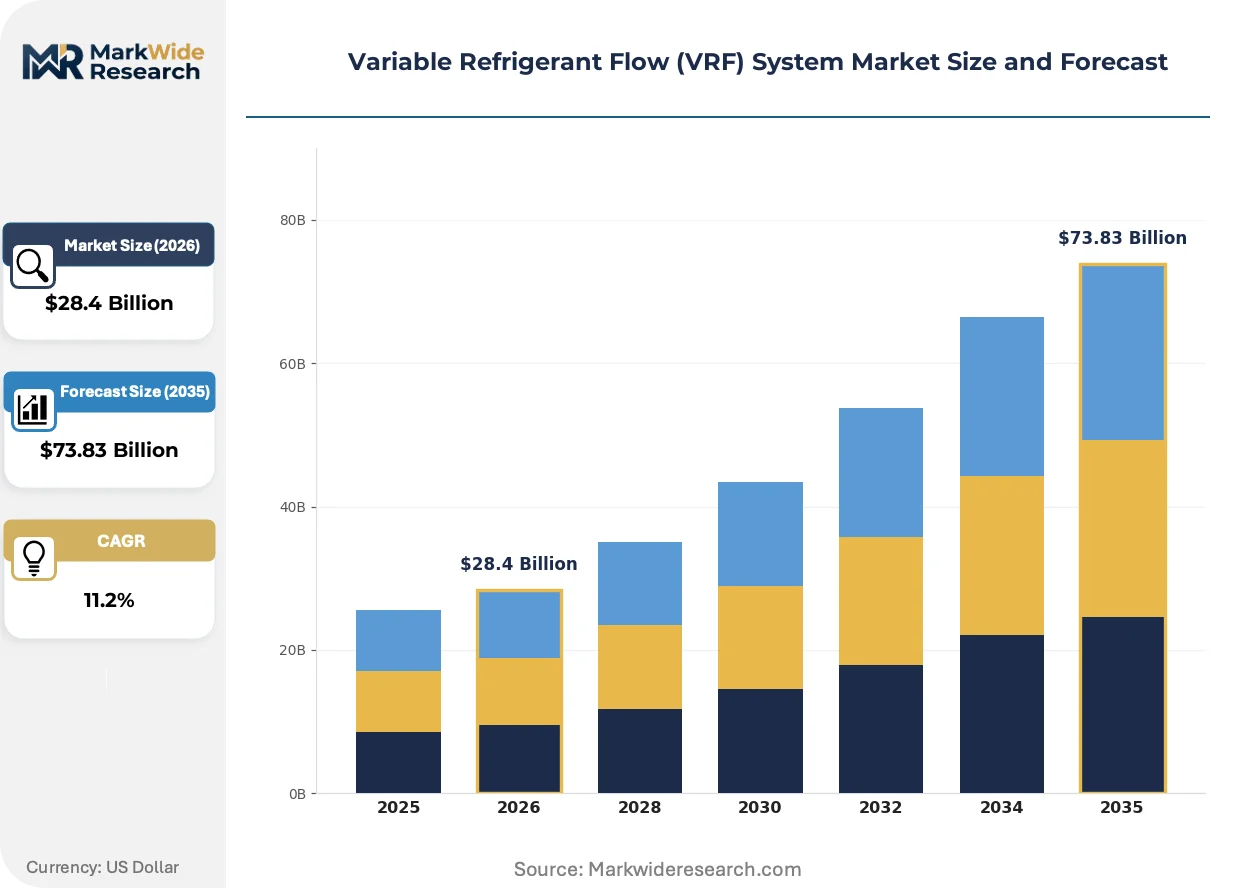
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $73.83 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Recovery, Heat Pump, Cooling Only, Energy Recovery Technology: Inverter, Magnetic Bearing, Scroll Compressors, Digital Scroll, Centrifugal Application: Commercial Buildings, Data Centers, Educational Facilities, Hospitality Venues End User: Real Estate Developers, Facility Management Providers, Government Offices, Corporate Campuses |
| Companies Covered | Johnson Controls, LG Electronics, Daikin Industries, Fujitsu General, Midea Group, Mitsubishi Electric, Panasonic Corporation, Toshiba Corporation, Carrier Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Refrigerant Flow (VRF) System Market Strategic Shifts & Innovations
Refrigerant chemistry transitions and compressor architecture evolution are restructuring competitive positioning, while procurement patterns shift toward integrated building system specifications.
Magnetic bearing scroll compressor technology is decomposing conventional acoustic mitigation strategies in precision cooling applications. Data center operators in Singapore and Frankfurt are specifying these systems to meet strict noise ordinances without secondary sound attenuation infrastructure. The technology is decomposing the historical trade-off between part-load efficiency and installation footprint that constrained chiller-loop alternatives.
EU F-Gas Regulation phase-down schedules are accelerating R-32 and HFO blend adoption across European commercial construction. Manufacturers serving this market face compressed product development cycles to maintain compliance with declining GWP thresholds. Heat pump configurations dominate new specifications in temperate climate zones, while heat recovery variants face reformulation delays as suppliers validate alternative refrigerant charge optimization.
Urban hospitality developers in Bangkok and Ho Chi Minh City are consolidating HVAC procurement under single-source building automation contracts. This behavior compresses traditional equipment-bid separation, favoring manufacturers with captive controls integration capabilities. The pattern is most visible in mixed-use towers where simultaneous heating and cooling loads create complex zone management requirements.
Variable Refrigerant Flow (VRF) System Market Segmentation
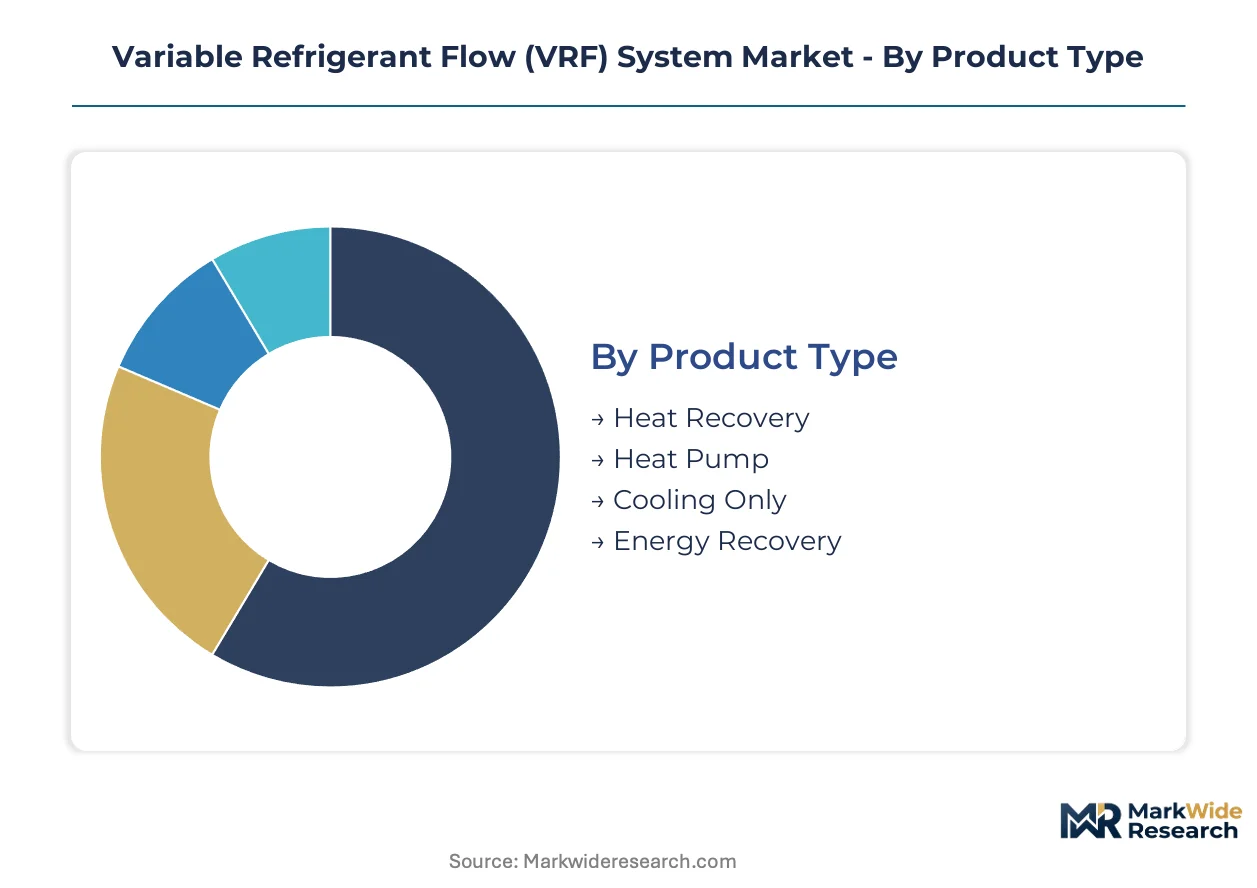
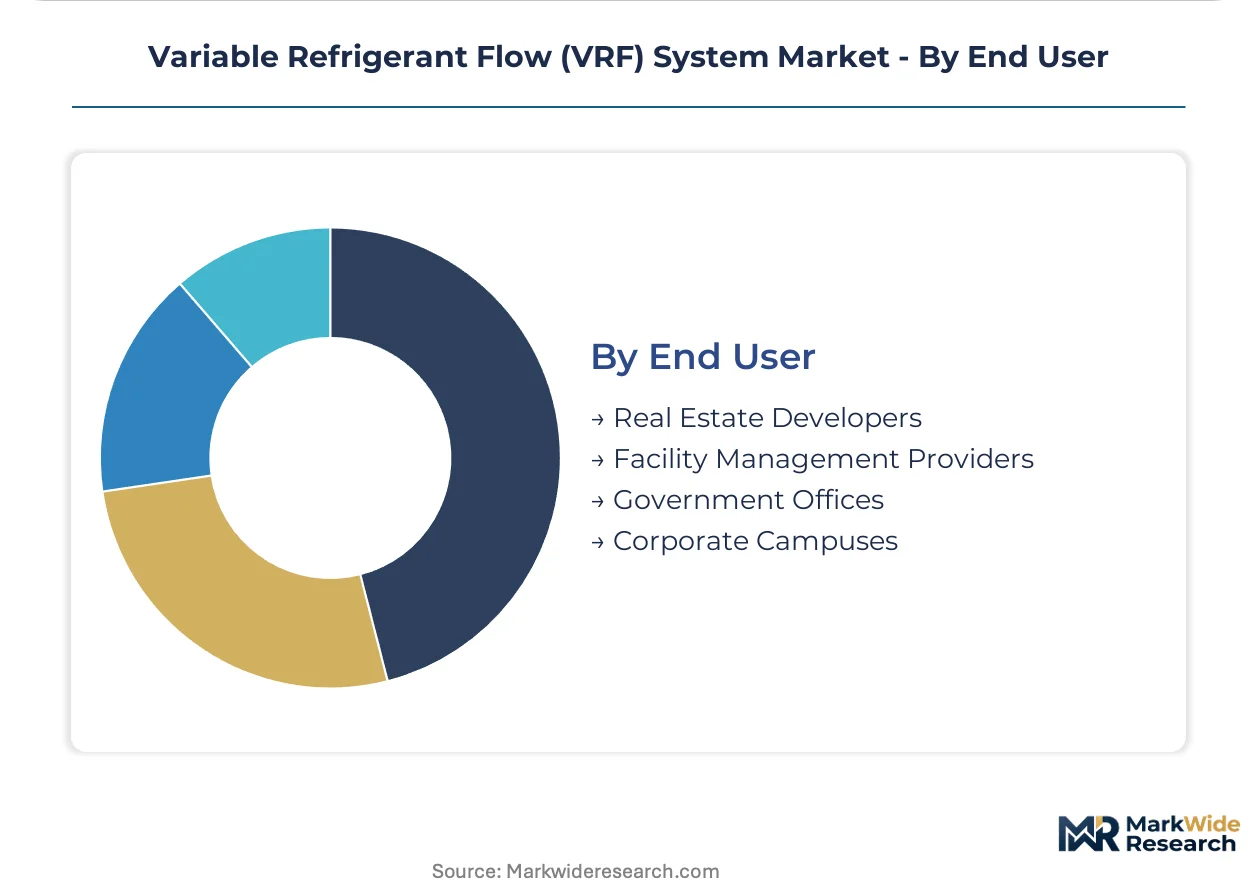
VRF system procurement decisions diverge sharply across installation contexts. Heat recovery configurations command premium positioning in mixed-use towers, while cooling-only units face displacement pressure from heat pump alternatives in temperate climate zones.
Product Type:
Substitution pressure intensifies against cooling-only configurations as building energy codes mandate year-round thermal management capabilities.
- Heat Recovery:Enables simultaneous heating and cooling across building zones through proprietary two-pipe architectures. Demand concentrates in Bangkok and Ho Chi Minh City mixed-use developments where municipal codes now require load-balancing capabilities.
- Heat Pump:Reversible refrigeration cycle delivers heating or cooling to individual zones without simultaneous operation. Unit shipments dominate in Vietnam's resort corridor developments and Indonesia's hospitality sector where seasonal load patterns predominate.
- Cooling Only:Single-mode operation suited to legacy retrofit installations in tropical climates.
- Energy Recovery:Ventilation-integrated heat exchange for high-occupancy commercial spaces.
Heat pump configurations anchor the volume base while heat recovery gains share at the steepest rate.
Technology:
Cost tier stratification separates magnetic bearing scroll systems at the premium extreme from digital scroll alternatives serving price-sensitive commercial bids.
- Inverter:Variable-speed compressor modulation matches refrigerant flow to real-time thermal loads. Deployment concentrates across Southeast Asian commercial construction where part-load efficiency requirements exceed fifteen percent above conventional chiller-loop designs.
- Magnetic Bearing:Oil-free operation eliminates acoustic transmission for precision cooling applications. Singapore and Frankfurt data center operators specify these systems to satisfy strict noise ordinances without secondary attenuation infrastructure.
- Scroll Compressors:Fixed-volume ratio compression for standard commercial installations.
- Digital Scroll:Capacity modulation through periodic unloading cycles.
- Centrifugal:Large-tonnage applications in centralized district cooling networks.
Inverter systems dominate shipment volumes while magnetic bearing technology climbs the fastest among emerging specifications.
Application:
Customer type differentiation separates specification authority between developer-led new construction and owner-operator retrofit decisions.
- Commercial Buildings:Mixed-use towers and office complexes requiring multi-zone climate control. Procurement in Jakarta and Bangkok increasingly consolidates under single-source building automation contracts that compress traditional equipment-bid separation.
- Data Centers:Precision cooling with acoustic and redundancy constraints. Singapore operators lead specification of magnetic bearing scroll configurations to meet strict noise ordinances.
- Educational Facilities:Seasonal occupancy patterns favoring heat pump configurations.
- Hospitality Venues:Vietnam's resort corridor developments and Indonesia's urban hotels present concentrated demand for premium heat recovery systems.
Commercial buildings generate the dominant specification volume while data center applications show the steepest technology upgrade trajectory.
End User:
Supply concentration varies with procurement scale, as real estate developers consolidate multi-tower orders while facility management providers fragment across service territories.
- Real Estate Developers:Control specification authority in new construction through design-build contracts. Bangkok and Ho Chi Minh City developers increasingly bundle HVAC procurement with native building automation platforms.
- Facility Management Providers:Influence replacement cycles and retrofit specifications in operational buildings. Service infrastructure limitations constrain rapid refrigerant transition deployment across Southeast Asian markets.
- Government Offices:Public procurement subject to energy efficiency mandates.
- Corporate Campuses:Owner-occupied facilities with centralized sustainability targets.
Real estate developers anchor the specification volume base while facility management providers gain procurement influence fastest through operational building retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down schedules and Japan's METI Top Runner program are accelerating refrigerant transitions and efficiency mandates across major markets. Municipal energy codes in Southeast Asia are tightening specifications for commercial developments. Divergent national standards create compliance complexity for multi-destination manufacturers.
China
GB energy efficiency standards for multi-connected air conditioners mandate escalating performance thresholds for new installations. The country's national standardization administration enforces testing protocols that filter supplier participation. Yangtze River Delta manufacturing clusters around Shanghai concentrate inverter compressor production capacity serving domestic and export markets.
Japan
METI Top Runner program establishes efficiency benchmarks that exceed international baselines by substantial margins. The program forces continuous product iteration cycles among domestic manufacturers. Osaka-based engineering centers develop proprietary two-pipe heat recovery architectures for premium export specifications.
United States
EPA SNAP program rules on hydrofluorocarbon phase-down restrict refrigerant options for commercial HVAC replacements. State-level building energy codes in California and New York accelerate heat recovery system specifications. Texas data center corridors drive magnetic bearing scroll compressor demand for acoustic-sensitive precision cooling.
Germany
EU F-Gas Regulation mandates declining GWP thresholds that compress product development timelines for R-410A successors. REACH compliance adds chemical registration burdens for HFO blend formulations. Frankfurt data center operators specify low-noise VRF configurations to satisfy strict municipal noise ordinances without secondary attenuation.
Vietnam
Municipal energy codes in Ho Chi Minh City now mandate simultaneous heating and cooling capabilities for mixed-use tower developments. The country's construction ministry issues technical standards that favor certified equipment suppliers. Resort corridor developments along the central coast concentrate heat pump specifications for seasonal hospitality occupancy patterns.
Variable Refrigerant Flow (VRF) System Market Key Industry Players
Listed leaders compete with private specialists across technology certification and captive manufacturing dimensions. The supplier base consolidates around inverter compressor architectures while fragmenting across refrigerant transition readiness. Three archetypes dominate: integrated manufacturers with captive component production, controls specialists extending into system orchestration, and regional fabricators competing on installation service density. Competitive moves concentrate on building automation platform integration and magnetic bearing scroll technology licensing.
Within the integrated manufacturing tier, Daikin Industries and Mitsubishi Electric occupy positions defined by proprietary architectural control. Johnson Controls exemplifies the controls-integration archetype, extending building management platforms into native VRF supervisory layers. These three companies anchor the competitive structure by representing distinct strategic vectors: captive compressor production, premium heat recovery engineering, and automation-native system design.
| Leading Market Players |
|---|
| Johnson Controls |
| LG Electronics |
| Daikin Industries |
| Fujitsu General |
| Midea Group |
| Mitsubishi Electric |
| Panasonic Corporation |
| Toshiba Corporation |
| Carrier Global Corporation |
| Others |
Cost & Logistics Intelligence
ISO 5149 certification gates supplier qualification and price differentiation simultaneously, filtering uncertified manufacturers from premium bids while creating tiered margin structures between validated and non-validated equipment tiers. Municipal energy code tightening in Vietnam, Thailand, and Indonesia compresses price elasticity for heat recovery configurations as code compliance becomes non-negotiable.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with ISO 5149-validated systems commanding substantial premiums over uncertified alternatives in Southeast Asian commercial bids. Price differentiation separates magnetic bearing scroll configurations for data center applications from standard inverter systems serving hospitality developments. Cost compression in cooling-only segments is intensifying because heat pump alternatives displace single-mode equipment under tightening energy codes. Real estate developers show least price sensitivity when bundling HVAC procurement with building automation platforms, while facility management providers in retrofit cycles remain most cost-conscious.
Supply Chain Analysis
Strategic stockpiling of refrigerant inventories dominates over just-in-time preferences as R-410A phase-down schedules create supply uncertainty ahead of R-32 and HFO blend transitions. Manufacturing concentrates in China, Japan, and South Korea, with Yangtze River Delta clusters anchoring inverter compressor production and Osaka-based engineering centers developing proprietary heat recovery architectures. Component dependencies include rare-earth magnets for compressor motors, copper tubing for refrigerant lines, and semiconductor chips for inverter controls. Single-source vulnerability in magnetic bearing technology licensing creates concentration risk. Distribution runs through manufacturer-direct specification channels for large commercial projects and authorized dealer networks for smaller installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction cycle recovery across Southeast Asian urban centers drives specification volume normalization, with hospitality and mixed-use development pipelines justifying capacity positioning ahead of municipal code enforcement waves.
For Market Incumbents: Compound captive compressor manufacturing advantages through backward integration into refrigerant charge optimization systems, defending against emerging controls specialists extending into native VRF supervisory layers. Deepen certification infrastructure investments to maintain ISO 5149 validation moats as third-party thermal performance requirements expand across Indonesian and Vietnamese municipal codes. Prioritize magnetic bearing scroll technology licensing to capture data center specification share in Singapore and Frankfurt corridors. For New Entrants and Emerging Players: Aftermarket service infrastructure gaps in R-32 and HFO blend technician certification present white-space entry points for training and maintenance specialists. Target Vietnam's resort corridor developments and Indonesia's Jakarta mixed-use towers where procurement consolidation under single-source automation contracts has not yet fully matured. Pursue acoustic-sensitive healthcare laboratory applications as a beachhead segment where magnetic bearing technology penetration remains incomplete. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down milestones reshape the acquisition landscape toward suppliers with validated lower-GWP refrigerant platforms and established service network density. Five-to-ten year viability favors manufacturers with captive compressor production and certified testing infrastructure over pure-play controls integrators. Monitor refrigerant patent expiration schedules and regional technician certification buildout rates as inflection indicators for scalable deployment timelines. Revision becomes warranted when compliance cost burdens cross thresholds that trigger specification preference shifts toward alternative HVAC architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | Validates R-32 and HFO blend architectures ahead of EPA SNAP and EU F-Gas enforcement deadlines. |
| Magnetic Bearing Technology Licensing | Unlocks data center and healthcare laboratory specifications in Singapore and Frankfurt noise-restricted zones. |
| Building Automation Integration | Captures procurement consolidation trends in Bangkok and Ho Chi Minh City mixed-use tower developments. |
| Technician Certification Infrastructure | Enables scalable R-32 and HFO blend deployment across Southeast Asian service territories. |
| Captive Compressor Manufacturing Expansion | Sustains margin control and ISO 5149 validation compliance in multi-zone installation bids. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with HVAC specification engineers, building automation integrators, refrigerant supply specialists, and facility management procurement directors; and secondary validation through customs trade databases, SEC equipment manufacturer filings, EPA SNAP program rulemakings, and EU F-Gas Regulation implementation notices. Bottom-up triangulation across installation project databases and top-down reconciliation against national energy efficiency standard enforcement records anchored volume estimates.
Across the analysis window, the forecasting framework modeled product type segmentation between heat recovery, heat pump, cooling-only, and energy recovery configurations; technology tiers spanning inverter, magnetic bearing, scroll, digital scroll, and centrifugal compressor architectures; and application contexts including commercial buildings, data centers, educational facilities, and hospitality venues. CAGRs derived from regression analysis of historical shipment patterns against municipal code adoption curves and refrigerant transition timelines. Industry-specific inputs included METI Top Runner efficiency benchmark trajectories and GB standard testing protocol thresholds.
Forecasts assume regulatory continuity in EPA SNAP, EU F-Gas, and Japan METI regimes; material policy shifts would require re-modeling deployment timelines. Refrigerant chemistry transitions, technician certification bottlenecks, and building automation protocol fragmentation represent specific risk factors that could revise outlooks. Revision becomes warranted when compliance cost differentials between R-410A and lower-GWP alternatives cross thresholds that accelerate or delay specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Blowers Market
HVAC Equipment
China HVAC Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
US Residential Furnace Market