
 Japan HVAC Market | 2026-2036
Japan HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Japan HVAC Market Insights
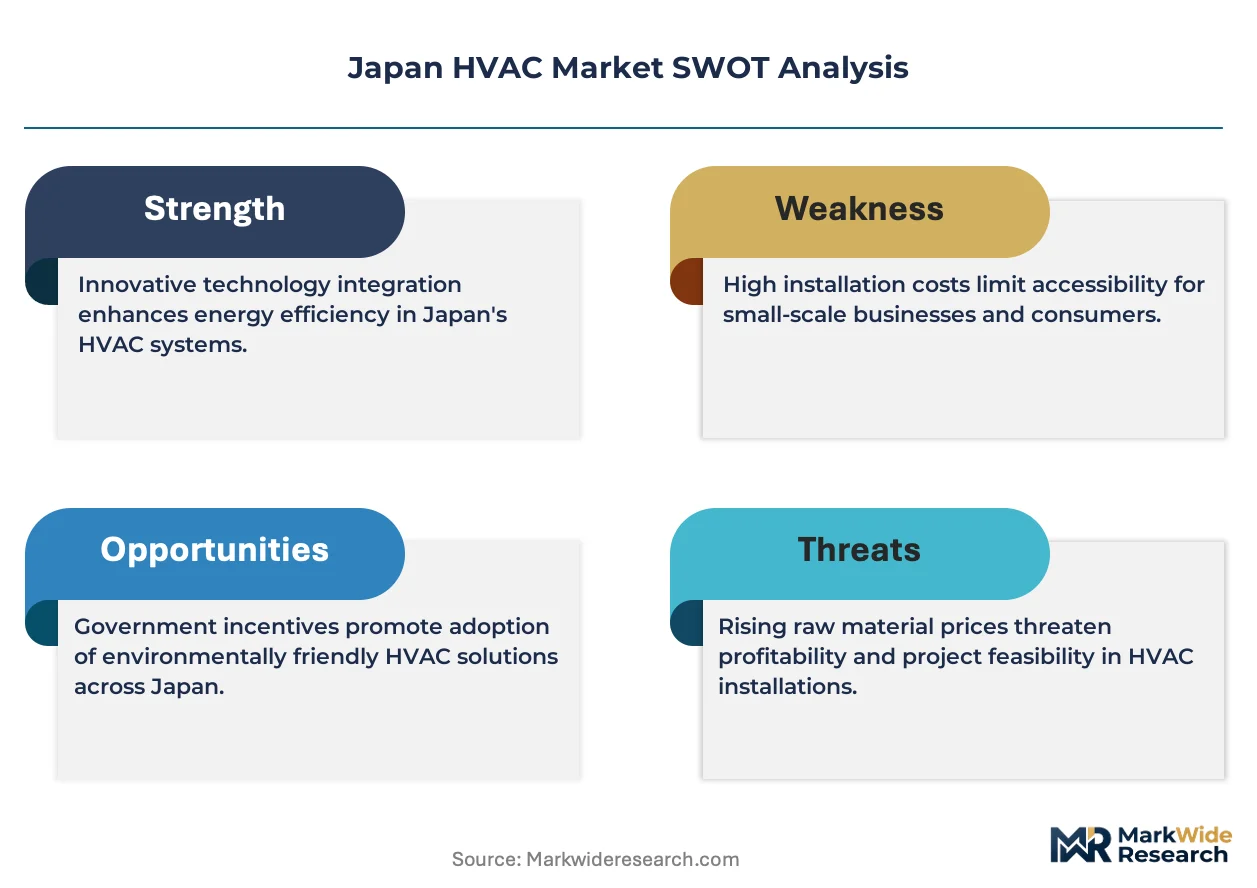
Performance-based maintenance contracts is rebalancing how Japanese HVAC suppliers monetize installed equipment. Daikin Industries leverages its nationwide service network to anchor long-term aftermarket revenue. Mitsubishi Electric differentiates through predictive diagnostics platforms that sustain premium pricing. Panasonic Holdings competes by bundling energy management software with hardware sales.
Heating, ventilation, and air conditioning systems regulate indoor thermal conditions through refrigeration cycles, air distribution networks, and heat exchange mechanisms operating between 15°C and 30°C setpoints for human comfort and process control. Split systems dominate residential replacement flows where R32 refrigerant migration drives unit turnover. VRF technology leads commercial retrofit segments with zoning flexibility that captures margin pools in mid-rise buildings. Heat pumps expand fastest among technology categories as building electrification targets reshape specification standards.
METI enforces Top Runner efficiency standards that mandate progressive performance gains across residential and commercial equipment categories. JIS standards govern installation quality and refrigerant handling protocols that shape contractor certification requirements. PMDA oversight extends to specialized cleanroom HVAC in pharmaceutical manufacturing facilities. Stakeholders must monitor refrigerant phase-down schedules and building energy codes to align product portfolios with compliance timelines.
Market Dynamics
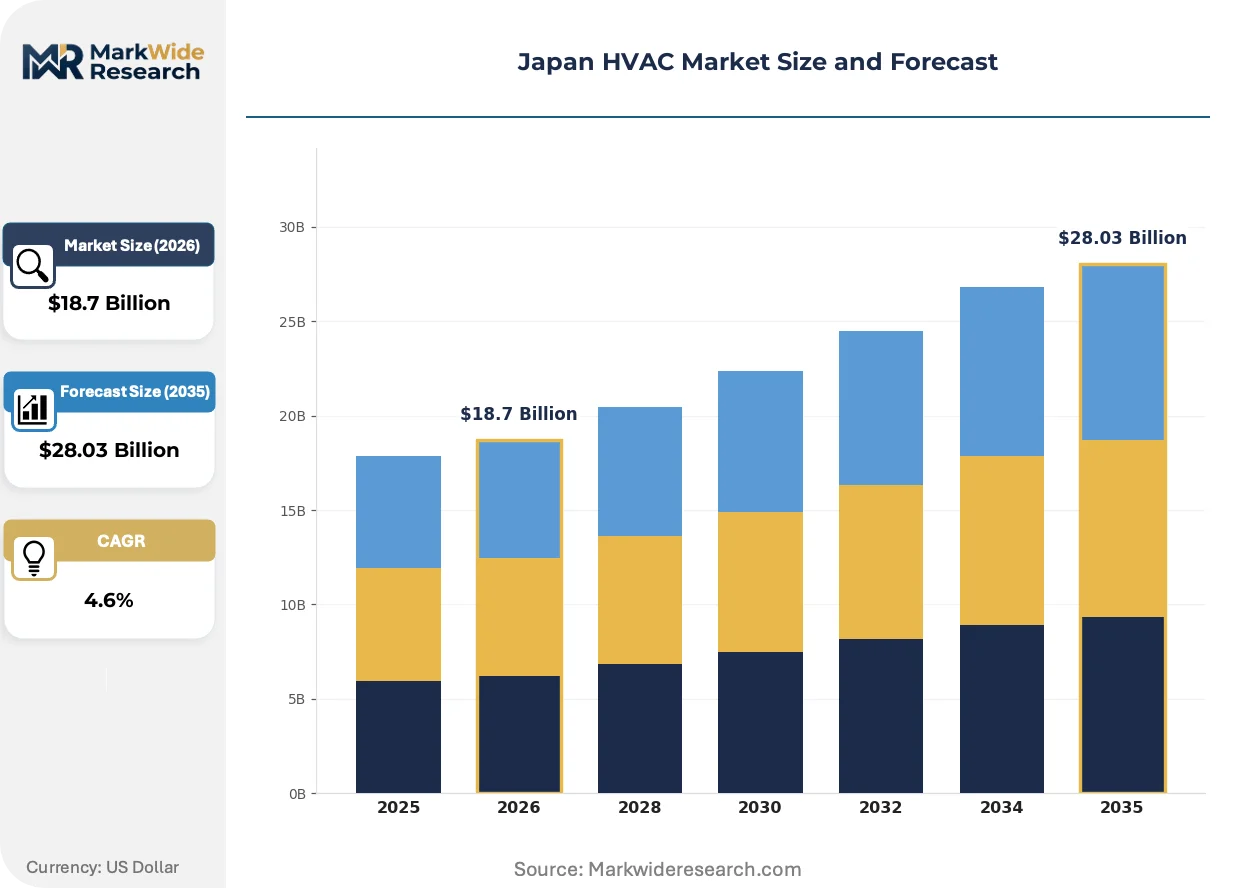
Japan's HVAC sector is undergoing a forced equipment turnover cycle as METI's refrigerant phase-down rules and Top Runner efficiency mandates compress replacement timelines across residential and commercial installed bases.
Growth Catalysts
- Commercial Retrofit Surge:Aging office stock in Greater Tokyo requires climate control upgrades as building electrification targets reshape specification standards.
- Heat Pump Adoption:Building decarbonization policies favor electric heating solutions over fossil fuel systems in new construction and renovation projects.
- VRF Technology Penetration:Variable refrigerant flow systems capture margin pools in mid-rise commercial buildings seeking zoning flexibility without ductwork reconstruction.
Market Restraints
- Copper and Aluminum Volatility:Raw material price swings for heat exchanger metals compress equipment margins and destabilize contractor quoting.
- Specialized Contractor Concentration:Certified installation capacity clusters in major metropolitan areas, creating service bottlenecks for rural equipment deployment.
- Natural Gas Infrastructure Lock-in:Existing piped heating networks in northern prefectures slow heat pump displacement despite efficiency advantages.
Strategic Opportunities
- Hokkaido Electrification Gap:Cold-climate heat pump deployment lags national averages, creating white space for low-ambient temperature equipment variants.
- Performance Contracting Models:Energy-as-a-service structures allow suppliers to capture lifetime value through guaranteed savings arrangements.
- Cleanroom HVAC Expansion:Pharmaceutical manufacturing investments in Osaka and Kanagawa prefectures drive demand for specialized contamination control systems.
Industry Challenges
- Refrigerant Handling Certification:R32 and next-generation fluid protocols require retraining of field technicians to maintain compliance with JIS handling standards.
- Legacy Control Integration:Smart building management systems must interface with decades-old pneumatic and analog infrastructure in Tokyo's commercial core.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan HVAC Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Ducted Systems, Chillers, Heat Pumps End User: Residential, Commercial, Industrial, Government Technology: VRF, Inverter, Hydronic, Radiant Installation Type: New, Retrofit, Replacement, Maintenance |
| Companies Covered | Daikin Industries, Ltd., Mitsubishi Electric Corporation, Panasonic Holdings Corporation, Fujitsu General Limited, Hitachi Ltd., Johnson Controls International plc, Toshiba Corporation, Taikisha Global Ltd., Mayekawa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan HVAC Market Trends and Innovations
Equipment intelligence and service model reinvention are restructuring how Japanese HVAC suppliers capture value beyond hardware transactions.
AI-driven predictive maintenance is decentralizing service dispatch decisions across commercial building portfolios. Property managers in Osaka and Nagoya are deploying sensor networks that trigger technician deployment before occupant complaints occur. This shift compresses response times while reducing truck-roll frequency for routine inspections.
METI's refrigerant phase-down schedule is accelerating R32 migration across residential split system replacements. Equipment manufacturers must redesign compressor architectures and safety protocols to accommodate mildly flammable working fluids. The transition imposes inventory complexity on distributors serving mixed-generation installed bases.
Building operators are unbundling maintenance from equipment procurement, favoring multi-year performance guarantees over standard warranty terms. Facility management firms in Greater Tokyo negotiate uptime commitments with service penalties. This procurement evolution pressures manufacturers to build captive service capabilities or cede aftermarket revenue to third-party contractors.
Japan HVAC Market Segmentation
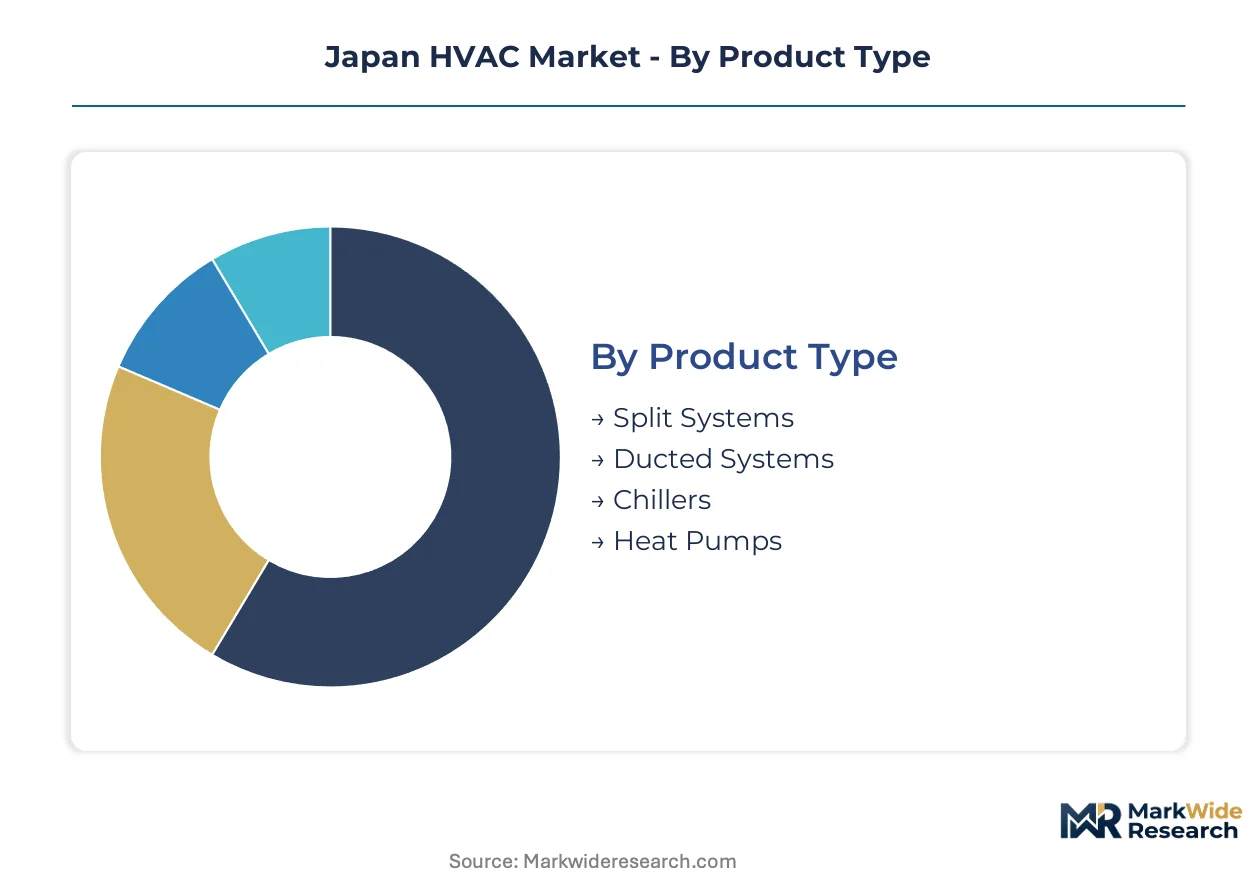
Japan's HVAC market segments reflect distinct upgrade cycles across aging building stock and refrigerant transition timelines. Equipment categories, end-use applications, and installation modes each command separate margin pools and compliance requirements.
Product Type:
Equipment replacement cycles vary sharply by product architecture and refrigerant compatibility constraints.
- Split Systems:Wall-mounted and multi-split configurations dominate residential replacement flows. R32 refrigerant migration drives accelerated turnover in Greater Tokyo's dense housing stock as METI phase-down rules compress equipment lifecycles.
- Heat Pumps:Air-source and water-source electric heating systems capture building electrification mandates. Cold-climate variants for Hokkaido command premium positioning as natural gas infrastructure faces displacement pressure.
- Ducted Systems:Central air distribution networks serve large-format commercial footprints requiring uniform conditioning.
- Chillers:Water-cooled and air-cooled centralized cooling plants anchor district-scale installations in Osaka and Nagoya commercial cores.
Volume placements concentrate in Split Systems; the faster expansion belongs to Heat Pumps.
End User:
Customer archetypes separate by procurement sophistication and performance guarantee requirements.
- Commercial:Office buildings, retail chains, and hospitality operators negotiate multi-year service contracts with uptime commitments. Property management firms in Greater Tokyo prioritize predictive maintenance platforms over standard warranty terms.
- Residential:Single-family and multi-family housing units drive seasonal replacement demand. Homeowners in Kanagawa and Saitama prefectures respond to utility rebate programs for high-efficiency equipment upgrades.
- Industrial:Manufacturing facilities require process-critical climate control with specialized contamination protocols.
- Government:Municipal buildings and public infrastructure projects follow mandated procurement schedules with domestic content preferences.
Commercial segment claims the dominant revenue share; residential replacement cycles provide the steadiest demand baseline.
Technology:
Control architectures differentiate margin capture through energy performance guarantees.
- VRF:Variable refrigerant flow systems modulate capacity across multiple zones without ductwork reconstruction. Mid-rise commercial buildings in Nagoya and Fukuoka specify VRF for retrofit flexibility that avoids structural disruption.
- Inverter:Variable-speed compressor drives optimize part-load efficiency across residential and light commercial applications. METI Top Runner standards favor inverter architectures for their superior seasonal performance coefficients.
- Hydronic:Water-based distribution networks integrate with existing boiler infrastructure in northern prefectures.
- Radiant:Floor and ceiling panel systems serve premium residential and healthcare applications requiring draft-free conditioning.
VRF technology commands the highest installed value per square meter; inverter penetration is climbing the fastest across replacement volumes.
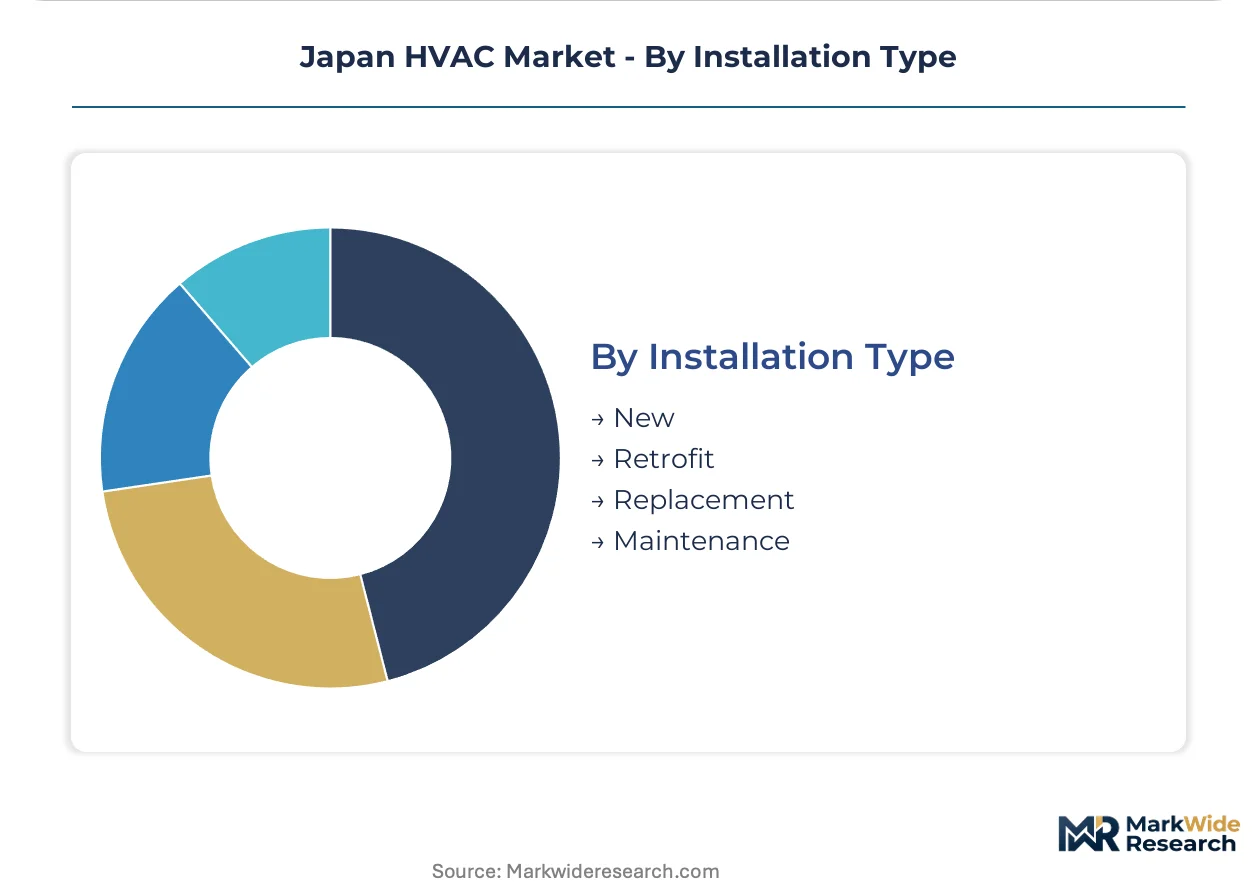
Installation Type:
Project origination shapes contractor capacity allocation and equipment margin structures.
- Replacement:End-of-life equipment swaps dominate residential activity as refrigerant regulations force premature retirements. Certified technicians in metropolitan areas face capacity constraints during peak summer seasons.
- Retrofit:Existing building climate upgrades capture commercial electrification incentives. Aging office stock in Tokyo's central business district requires phased equipment replacement without full occupancy disruption.
- New:Greenfield construction projects specify integrated building systems with smart management interfaces.
- Maintenance:Performance-based service contracts extend equipment lifecycles while generating recurring revenue streams for captive service networks.
Replacement installations generate the highest annual unit volumes; retrofit projects are gaining share fastest as building decarbonization targets reshape capital planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's HVAC production concentrates in Osaka-Kobe and Nagoya industrial corridors, while consumption clusters in Greater Tokyo's dense commercial and residential stock. Domestic manufacturing serves replacement demand cycles accelerated by METI efficiency mandates. Regional performance varies sharply across climate zones and building age profiles.
Kanto/Tokyo
Greater Tokyo's aging office stock drives commercial retrofit demand as building electrification targets compress replacement timelines. METI Top Runner standards force premature equipment retirements across Chiyoda and Minato ward commercial towers. Property managers in Shibuya and Shinjuku submarkets negotiate performance-based maintenance contracts with uptime guarantees.
Kansai/Osaka
Osaka's manufacturing heritage anchors HVAC production clusters in neighboring Hyogo prefecture. The Kansai region's humid subtropical climate sustains year-round cooling demand across residential and commercial segments. Pharmaceutical manufacturing investments in Osaka prefecture expand cleanroom HVAC requirements under PMDA oversight protocols.
Chubu/Nagoya
Nagoya's automotive and aerospace industrial base generates process-critical climate control demand with specialized contamination protocols. Heavy manufacturing facilities in Aichi prefecture require precision temperature control for production lines. Regional contractors face capacity constraints during summer peak seasons as METI refrigerant rules accelerate replacement volumes.
Hokkaido
Cold-climate heat pump deployment lags national averages due to natural gas infrastructure lock-in across northern prefectures. Sapporo's district heating networks resist electrification despite efficiency disadvantages. Low-ambient temperature equipment variants command premium positioning as building decarbonization policies extend northward.
Kyushu
Fukuoka's semiconductor manufacturing investments drive cleanroom HVAC specification demand with particulate control requirements. The region's subtropical climate sustains cooling-centric equipment profiles with minimal heating load. Industrial parks in Kumamoto and Nagasaki prefectures attract pharmaceutical facilities requiring specialized contamination control systems.
Japan HVAC Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning, while mid-scale specialists occupy retrofit and maintenance segments. The vendor base stratifies across captive service networks, component suppliers, and regional installation contractors. Three archetypes dominate: integrated manufacturers with nationwide service infrastructure, technology-focused system developers, and energy management platform bundlers. Competitive moves center on predictive diagnostics deployment and multi-year performance contracting structures.
Among Japan-based integrated manufacturers, Daikin Industries, Ltd., Mitsubishi Electric Corporation, and Panasonic Holdings Corporation occupy positions exemplifying distinct strategic archetypes. Daikin Industries, Ltd. represents the captive service network model with aftermarket revenue anchoring long-term relationships. Mitsubishi Electric Corporation exemplifies technology-driven differentiation through diagnostic platforms. Panasonic Holdings Corporation sits within the energy management bundling tier, combining software with hardware positioning.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Mitsubishi Electric Corporation |
| Panasonic Holdings Corporation |
| Fujitsu General Limited |
| Hitachi Ltd. |
| Johnson Controls International plc |
| Toshiba Corporation |
| Taikisha Global Ltd. |
| Mayekawa |
| Others |
Pricing and Supply Chain Analysis
METI's refrigerant phase-down mandates are forcing equipment redesigns that compress supplier margins and concentrate procurement power among certified contractors in Greater Tokyo. Manufacturers must absorb R32 transition costs while competing for replacement volumes against aging installed bases.
Pricing Analysis
Margin tightening in the residential split-system tier reflects copper and aluminum volatility for heat exchanger components. Three-tier pricing structure across premium inverter, standard fixed-speed, and economy non-certified levels separates Daikin's service-bundled positioning from unbranded imports. Price differentiation hinges on JIS certification status and captive installation network coverage. Commercial buyers in Osaka and Nagoya exhibit lowest price sensitivity due to uptime guarantee requirements, while rural residential replacement demand shows highest elasticity to utility rebate timing.
Supply Chain Analysis
Regional distribution centers in Osaka-Kobe and Nagoya industrial corridors anchor hub-and-spoke patterns serving Kanto consumption clusters. Manufacturing concentrates in Japan, China, and South Korea for compressor assemblies and electronic control modules. Raw material dependencies span Chilean copper, Australian aluminum, and Chinese rare earth elements for permanent magnet motors. Single-source vulnerability sits with specialized refrigerant handling equipment from limited JIS-certified fabricators. Distribution runs through manufacturer-direct channels for large commercial projects and wholesale distributors for residential replacement flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's HVAC market functions as a cost-of-compliance story where METI Top Runner standards and refrigerant handling certifications erect barrier-to-entry moats favoring incumbents with established technician training infrastructure.
For Market Incumbents: Deploy predictive maintenance platforms to anchor multi-year service contracts before third-party contractors capture aftermarket revenue. Deepen backward integration into refrigerant recovery and reclamation services to control compliance costs. Defend against emerging energy-management software bundlers by integrating building automation interfaces.
For New Entrants and Emerging Players: Begin with Hokkaido's low-ambient heat pump segment where natural gas infrastructure lock-in creates underpenetrated white space. Target pharmaceutical cleanroom HVAC in Osaka and Kanagawa prefectures where PMDA oversight requirements favor specialized contamination control expertise. Pursue direct contractor certification partnerships rather than distributor relationships to bypass established channel gatekeepers.
For Investors and Strategic Acquirers: Re-rating potential sits with regional installation networks possessing JIS refrigerant handling credentials given METI's technician retraining mandates. Long-term viability favors service-capable manufacturers over pure equipment vendors as performance contracting displaces transactional hardware sales. Monitor R32 inventory write-down announcements as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Service Network Expansion | Daikin's nationwide technician corps captures recurring revenue from METI-mandated equipment turnover. |
| Predictive Diagnostics Platform Deployment | Mitsubishi Electric's sensor networks compress response times before occupant complaints trigger dispatch. |
| Energy Management Software Bundling | Panasonic's building automation integration differentiates hardware sales through guaranteed savings structures. |
| Cold-Climate Heat Pump Development | Low-ambient variants for Hokkaido address electrification gaps where district heating networks resist displacement. |
| Cleanroom HVAC Specialization | Taikisha's pharmaceutical contamination control systems capture Osaka and Kanagawa manufacturing investments. |
Research Methodology
Independent corroboration across equipment manufacturer sales directors, JIS-certified installation contractors, and commercial property management firms underwrites the qualitative findings. Primary fieldwork encompassed maintenance directors at Tokyo office towers, procurement leads at Osaka pharmaceutical facilities, and regional distribution managers in Nagoya. Secondary validation drew from METI efficiency standard filings, customs trade data for copper and aluminum imports, and building energy code disclosures from prefectural governments. Bottom-up unit placement estimates triangulated against top-down construction permit flows and replacement cycle assumptions.
Rate-of-change decomposition across product type, end-user segment, technology architecture, and installation mode structured the analytical framework. Segmentation modeling incorporated equipment replacement timelines, refrigerant transition schedules, and regional climate load profiles throughout the forecast period. CAGRs derived from historical placement volumes adjusted for METI regulatory acceleration effects and building electrification policy trajectories. Forecast inputs included commercial retrofit pipeline data from Greater Tokyo property managers and residential utility rebate program allocations from Kanagawa and Saitama prefectures.
Underlying measurement precision varies by segment; commercial replacement flows carry tighter precision than emerging heat pump penetration estimates in northern prefectures. Forecasts reflect documented assumptions regarding refrigerant phase-down adherence and contractor certification capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Global Air Conditioner Market