
 China HVAC Market | 2026-2036
China HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
China HVAC Market Insights
Variable refrigerant flow integration with IoT-enabled diagnostics is reconfiguring how building climate systems are engineered and serviced in China. Gree Electric Appliances leverages captive compressor manufacturing to sustain cost leadership in domestic VRF deployments. Midea Group anchors its position through backward integration into inverter controller production. Daikin Industries competes on premium commercial specifications, differentiating via specialized large-tonnage chiller engineering for industrial facilities.
Heating, ventilation, and air conditioning encompasses electromechanical systems that regulate indoor temperature, humidity, and air purity through vapor-compression refrigeration cycles, heat exchange networks, and forced-air distribution ducting rated by cooling capacity in tons or kilowatts; these systems serve commercial, industrial, and residential enclosures where thermal comfort and contaminant control protect occupant health and equipment performance. Air conditioners dominate installed base value across China's coastal megacities where replacement cycles compress amid efficiency mandates. Smart HVAC Solutions represent the fastest-expanding technology segment as building operators prioritize remote diagnostics and demand-responsive load management. Heat Pumps capture margin concentration in northern provinces where coal-to-electricity heating conversions expand addressable volume.
MIIT enforces GB standards for seasonal energy efficiency ratios while MEE monitors refrigerant phase-down schedules under China's Kigali Amendment commitments, tightening compliance costs for manufacturers still dependent on high-GWP working fluids. NMPA-aligned product safety certifications and provincial-level green building codes in Jiangsu and Zhejiang further filter market access, favoring suppliers with in-house testing laboratories. Stakeholders must monitor how municipal carbon intensity targets in Shanghai and Shenzhen reshape procurement specifications for new commercial construction.
Market Dynamics
GB energy efficiency standards and dual carbon mandates are compressing replacement cycles across China's eastern coastal provinces, forcing equipment upgrades ahead of natural end-of-life.
Growth Catalysts
- Data center cooling demand:Eastern provinces including Jiangsu and Zhejiang are accelerating hyperscale facility construction, pulling precision cooling equipment into deployment pipelines.
- MIIT efficiency mandates:Seasonal energy efficiency ratio requirements are phasing out legacy fixed-speed units, creating mandatory upgrade volume in commercial building stock.
- Coal-to-electricity heating conversion:Northern provinces are expanding heat pump installations as primary heating infrastructure, displacing distributed coal combustion.
Market Restraints
- Copper and rare-earth magnet volatility:Inverter compressor production faces input cost instability from concentrated upstream supply.
- High-GWP refrigerant lock-in:Manufacturers dependent on R410A and R22 face MEE phase-down compliance costs under Kigali Amendment schedules.
- Technical labor scarcity:VRF system commissioning requires certified refrigeration technicians, with training pipeline gaps in tier-three cities.
Strategic Opportunities
- Western province penetration:Sichuan and Chongqing building stock remains underpenetrated by smart HVAC systems relative to Yangtze River Delta saturation.
- IoT-enabled predictive maintenance:Cloud-connected diagnostics platforms are opening recurring revenue streams separate from equipment sales.
- Industrial process cooling:Semiconductor fabrication and battery manufacturing facilities require specialized chiller engineering with tighter temperature tolerances.
Industry Challenges
- Certification timeline compression:NMPA-aligned product safety testing and provincial green building code approvals are extending time-to-market for new equipment launches.
- Legacy building retrofit complexity:Existing ducting infrastructure in Shanghai and Shenzhen commercial towers limits VRF compatibility without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China HVAC Market |
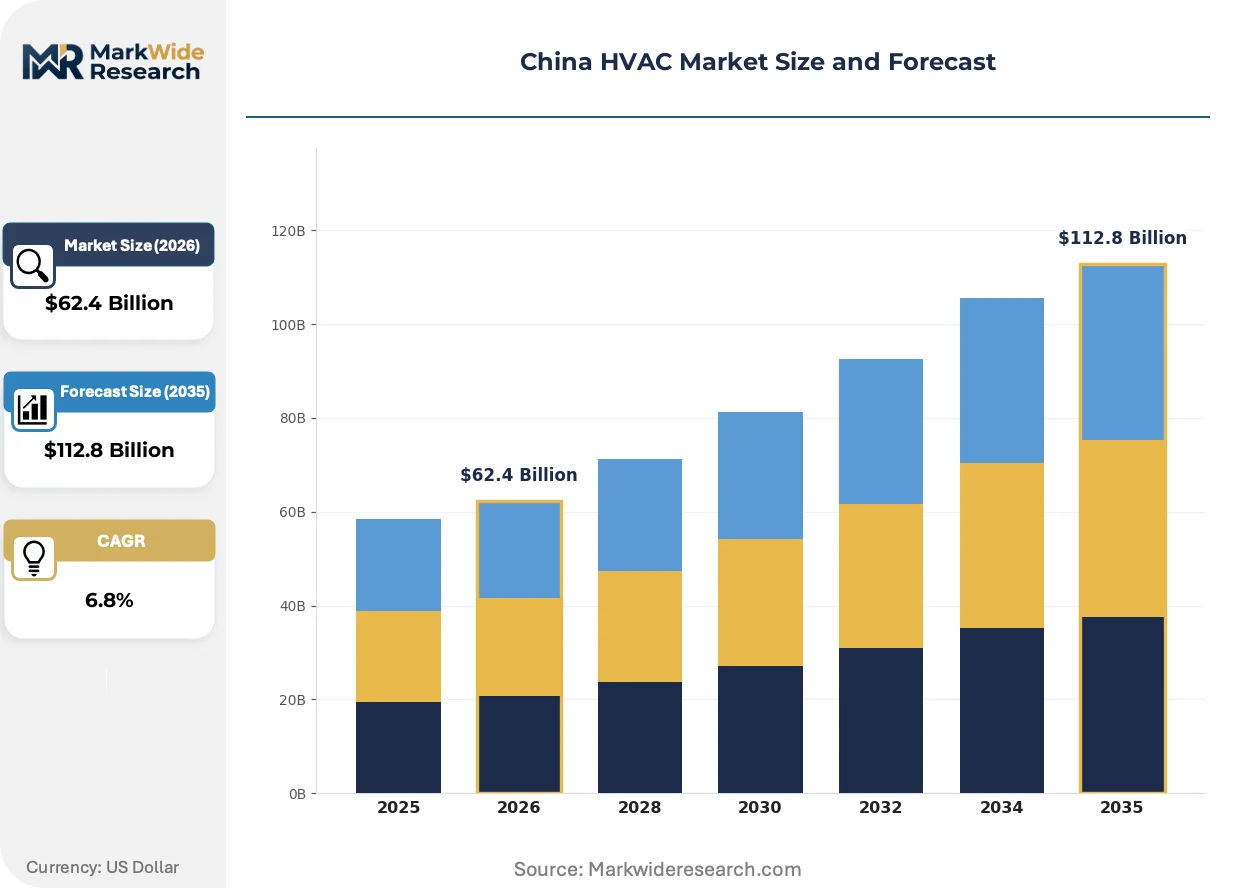
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Air Conditioners, Heat Pumps, Ventilation Fans End User: Residential Sector, Commercial Offices, Industrial Facilities, Retail Spaces Technology: VRF Systems, Centralized Systems, Window Units, Smart HVAC Solutions Application: Cooling, Heating, Air Quality Control, Humidity Control |
| Companies Covered | Haier Smart Home, Chigo Air Conditioning, Daikin Industries, Panasonic Corporation, Aux Air Conditioning, Gree Electric Appliances, Carrier Global, LG Electronics, Midea Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China HVAC Market Trends and Innovations
Digital twin architectures and refrigerant chemistry transitions are reconfiguring how climate systems are engineered, sold, and serviced across China's building stock.
Digital twin software for HVAC asset management is virtualizing how facility operators monitor chiller performance and predict component failure. Property management groups in Guangdong and Beijing are deploying these platforms across multi-building portfolios. The technology is compressing traditional preventive maintenance schedules into condition-based interventions.
MEE enforcement of Kigali Amendment refrigerant phase-downs is accelerating R32 and R290 adoption in new equipment platforms. Manufacturers must retool compressor designs and safety systems for mild-flammability working fluids. Northern province heat pump deployments face the tightest compliance timelines given heating-season refrigerant charge volumes.
Building operators in the Yangtze River Delta are unbundling equipment procurement from long-term service contracts, separating capital expenditure from operational vendor relationships. Traditional turnkey vendors are responding with standalone monitoring subscriptions and performance-guarantee pricing. This pattern is most pronounced in Shanghai commercial real estate where asset-light operating models dominate.
China HVAC Market Segmentation
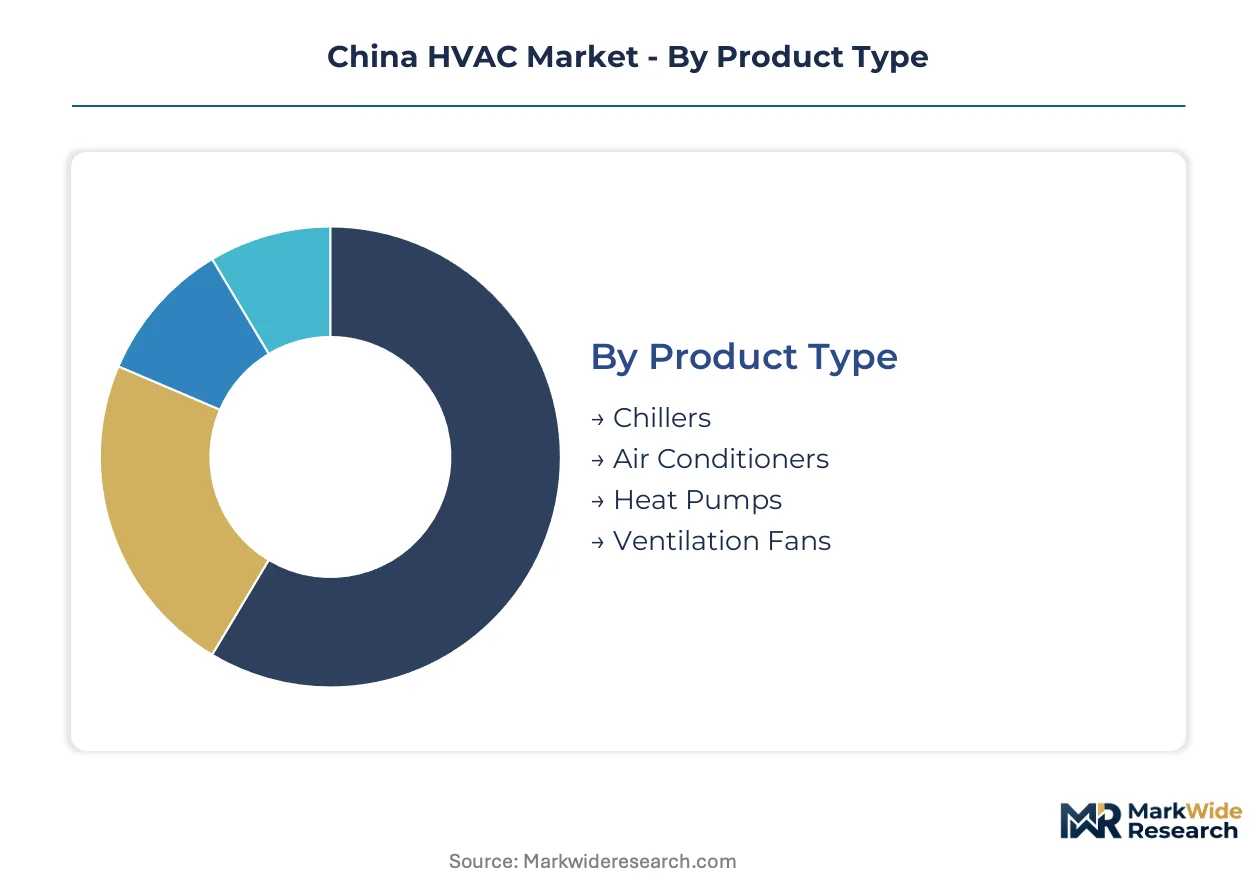
Equipment complexity and maintenance frequency vary sharply across HVAC categories in China. Service contract attach rates and spare parts revenue potential differ by segment, reshaping how manufacturers structure their go-to-market economics.
Product Type:
After-sales-service intensity climbs with system scale and refrigerant charge volume, driving divergent margin structures across equipment categories.
- Chillers:Large-tonnage centrifugal and screw compressors serving commercial complexes require specialized technician crews for tube maintenance and refrigerant management. Demand concentrates in Shanghai and Shenzhen data center clusters where precision cooling uptime guarantees command premium service pricing.
- Air Conditioners:Split-system and packaged units dominate residential replacement cycles across eastern coastal provinces. Fixed-speed inventory faces accelerated obsolescence under MIIT seasonal efficiency mandates, compressing upgrade timelines in Jiangsu and Zhejiang housing stock.
- Heat Pumps:Air-source and ground-source configurations are displacing coal-fired heating in northern provinces under coal-to-electricity conversion programs.
- Ventilation Fans:Heat recovery ventilators and exhaust systems integrate with airtight building envelopes in green-certified commercial towers.
Air Conditioners hold the largest share; momentum sits with Heat Pumps.
End User:
Procurement authority and specification complexity separate fragmented residential demand from concentrated commercial decision-making.
- Residential Sector:Individual households purchase through retail channels with price sensitivity shaping tier-two and tier-three city penetration. Northern province heating conversions are expanding addressable volume beyond traditional cooling demand.
- Commercial Offices:Property management groups in Beijing and Guangdong specify VRF and centralized systems with embedded IoT diagnostics. Asset-light operating models are unbundling equipment procurement from long-term service contracts.
- Industrial Facilities:Semiconductor fabrication and battery manufacturing require specialized chiller engineering with tighter temperature tolerances.
- Retail Spaces:Shopping mall operators prioritize rapid installation and zonal climate control across heterogeneous tenant footprints.
Commercial Offices command the highest service contract values; Industrial Facilities are climbing fastest on process cooling requirements.
Technology:
Control system sophistication and connectivity infrastructure determine upgrade path compatibility with existing building automation networks.
- VRF Systems:Variable refrigerant flow platforms enable individualized zone control with heat recovery between spaces. Eastern province commercial retrofits favor these for minimal ducting modification.
- Centralized Systems:Chiller plants and air handling units serve large floorplates with uniform load profiles. Legacy installations in Shanghai commercial towers face refrigerant phase-down compliance costs.
- Window Units:Compact self-contained systems persist in rental housing and budget hospitality segments.
- Smart HVAC Solutions:Cloud-connected diagnostics and demand-responsive load management are expanding most quickly as building operators prioritize remote monitoring capabilities.
Centralized Systems retain installed base dominance; Smart HVAC Solutions are gaining share fastest on predictive maintenance revenue models.
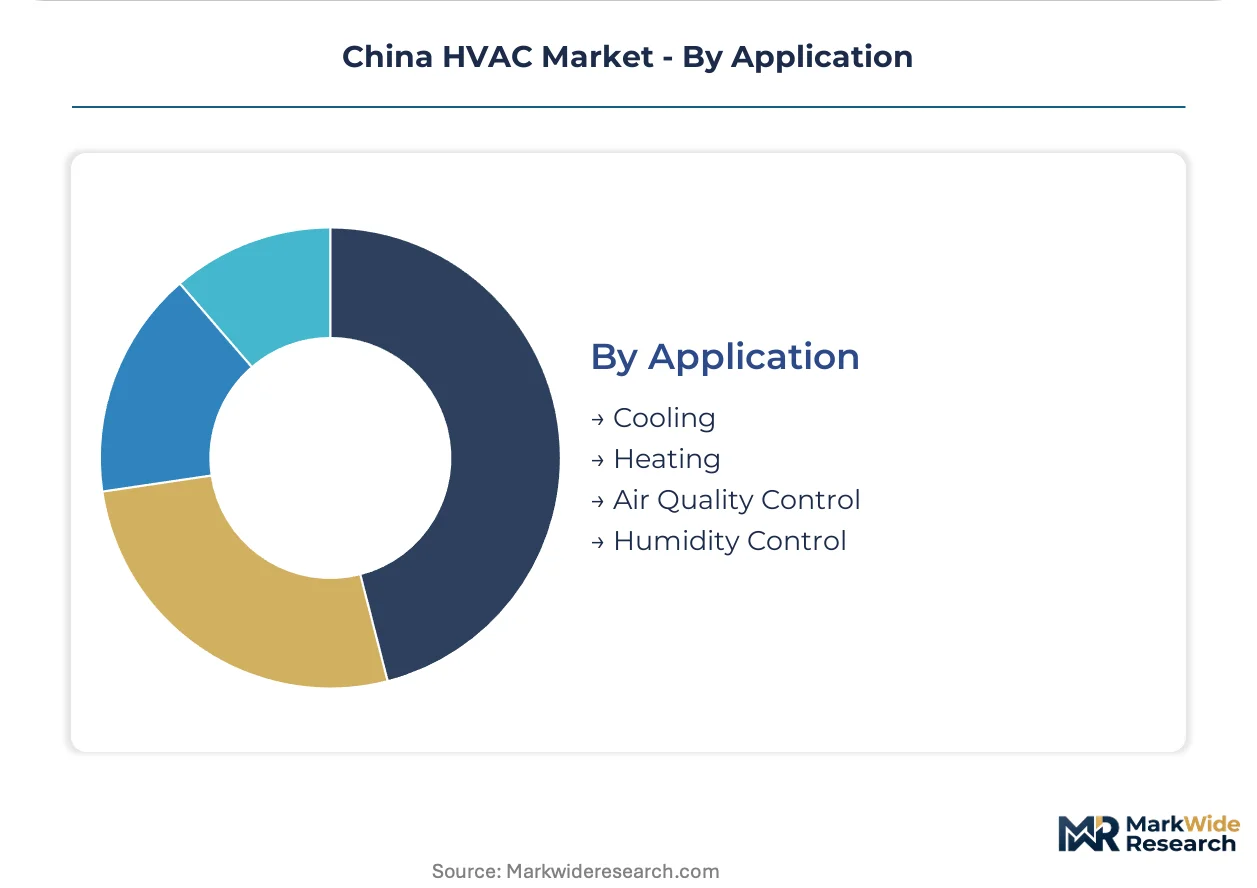
Application:
Climate function determines equipment sizing methodology and seasonal utilization patterns across China's heating-cooling transition zones.
- Cooling:Vapor-compression refrigeration cycles dominate southern province demand with peak load stress during Yangtze River Delta summer humidity.
- Heating:Heat pump and electric resistance configurations are displacing distributed coal combustion in northern provinces under environmental enforcement.
- Air Quality Control:Filtration and pressurization systems serve healthcare and cleanroom applications with HEPA specification requirements.
- Humidity Control:Desiccant and mechanical dehumidification protects electronics manufacturing and archival storage in coastal high-humidity zones.
Cooling retains volume leadership; Heating is expanding most quickly on coal-to-electricity infrastructure replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Property developers and facility managers in eastern coastal provinces drive specification intensity, while northern provinces pull heat pump volume through coal-to-electricity conversion mandates. Provincial carbon intensity targets reshape procurement timelines across urban clusters.
Yangtze River Delta
Shanghai and Jiangsu data center construction accelerates precision cooling deployments. MIIT seasonal efficiency mandates phase out fixed-speed inventory in commercial towers. Zhejiang manufacturing corridors concentrate VRF system integration with IoT diagnostics.
Pearl River Delta
Guangdong commercial real estate unbundles equipment procurement from service contracts. MEE refrigerant phase-down enforcement tightens compliance timelines for legacy chiller plants. Shenzhen green building codes filter market access toward suppliers with in-house testing laboratories.
Beijing-Tianjin-Hebei
Coal-to-electricity heating conversions expand air-source heat pump installations across northern municipalities. GB energy efficiency standards compress replacement cycles in aging residential stock. Tianjin industrial zones pull specialized chiller engineering for semiconductor fabrication facilities.
Sichuan-Chongqing
Western province building stock remains underpenetrated by smart HVAC systems relative to coastal saturation. Provincial green building codes in Chongqing reshape new commercial construction specifications. Chengdu electronics manufacturing clusters generate process cooling demand with tighter temperature tolerances.
Shandong Peninsula
Qingdao and Jinan commercial retrofits favor VRF platforms for minimal ducting modification. SAMR product safety certifications extend time-to-market for equipment launches targeting northern markets. Local HVAC distributors build technician training pipelines to address VRF commissioning scarcity.
China HVAC Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Consolidation concentrates among captive manufacturers with backward integration into compressor and controller production. Three archetypes dominate: integrated appliance conglomerates with captive component supply, premium-tier foreign specialists with large-tonnage engineering capabilities, and regional fabricators serving price-sensitive replacement cycles. Competitive moves center on IoT platform development and provincial certification laboratory investments.
Among integrated appliance conglomerates, Gree Electric Appliances and Midea Group occupy positions defined by captive manufacturing depth. Daikin Industries anchors the premium-tier specialist archetype with large-tonnage chiller engineering concentration. Haier Smart Home exemplifies the smart platform vector through cloud-connected diagnostics integration. Carrier Global and LG Electronics sit within the foreign multinational tier competing on commercial specification differentiation. Panasonic Corporation represents the precision electronics origin archetype applying semiconductor-grade control systems to climate equipment. Aux Air Conditioning and Chigo Air Conditioning occupy regional fabricator positions serving replacement demand in tier-two and tier-three cities.
| Leading Market Players |
|---|
| Haier Smart Home |
| Chigo Air Conditioning |
| Daikin Industries |
| Panasonic Corporation |
| Aux Air Conditioning |
| Gree Electric Appliances |
| Carrier Global |
| LG Electronics |
| Midea Group |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shandong compressor manufacturing is compressing margins across China's HVAC equipment tiers, forcing suppliers into longer-term contract structures while buyers exploit utilization transparency to extract price concessions.
Pricing Analysis
Cost-plus contracts indexed to Shanghai copper futures dominate commercial equipment procurement, with annual renegotiation clauses protecting buyers against raw material spikes. Price differentiation separates NMPA-certified premium units from standard-efficiency inventory facing MIIT obsolescence deadlines. Cost compression in fixed-speed residential units is intensifying as eastern province distributors liquidate non-compliant stock. Tier-two city households exhibit highest price sensitivity, while data center operators prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian component sources is reshaping sourcing strategies for inverter controller assemblies. Manufacturing concentrates in Guangdong, Jiangsu, and Zhejiang provinces, drawing from Chilean copper concentrate and Australian rare-earth magnet feedstock. Single-source vulnerability sits with Malaysian semiconductor packaging for IoT-enabled diagnostic modules. Distribution runs through provincial HVAC wholesale networks with direct-to-contractor platforms gaining share in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's HVAC sector is approaching a platform-economics inflection as building operators unbundle equipment from service relationships, creating interoperability requirements that favor ecosystem orchestrators over standalone manufacturers.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance subscriptions into new equipment sales before third-party IoT platforms capture diagnostic data ownership. Prioritize captive inverter controller production to defend margin position against Midea and Gree backward integration. Accelerate provincial certification laboratory investments to compress NMPA approval timelines as compliance windows tighten.
For New Entrants and Emerging Players: Pursue white-space penetration in Sichuan-Chongqing smart HVAC retrofit markets where coastal saturation has not yet replicated. Target western province commercial offices with standalone monitoring subscriptions that bypass incumbent equipment lock-in. Position through cloud-native diagnostics platforms rather than hardware-first approaches.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IoT-enabled service providers with multi-building portfolio contracts in Shanghai and Shenzhen. Long-term viability favors acquisition targets with in-house refrigerant testing capabilities and Kigali Amendment-ready equipment platforms. Monitor municipal carbon intensity target acceleration as the signal for procurement specification inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Cloud-connected diagnostics capture recurring revenue from Shanghai commercial portfolios. |
| Backward Integration into Controllers | In-house inverter production defends margin against Gree and Midea captive supply advantages. |
| Provincial Certification Laboratory Investment | NMPA-aligned testing capacity compresses time-to-market for GB efficiency-compliant launches. |
| Western Province Distribution Expansion | Sichuan-Chongqing penetration captures underexploited smart HVAC retrofit demand. |
| Refrigerant Chemistry Transition | R32 and R290 platform readiness positions for MEE phase-down enforcement acceleration. |
Research Methodology
The analysis maps chiller, VRF, air conditioner, and heat pump sub-sectors, each validated through equipment procurement managers, facility maintenance directors, HVAC contractor networks, and MIIT regulatory affairs specialists. Primary fieldwork combined structured interviews with secondary triangulation against GB standard filings, provincial green building code databases, customs trade records for compressor imports, and SAMR product certification registries. Bottom-up equipment shipment estimates and top-down construction spend allocations were reconciled across segmentation dimensions.
Forecast assumptions held fixed the current GB energy efficiency tier structure and Kigali Amendment phase-down schedule while varying data center construction pipelines and coal-to-electricity conversion rates across northern provinces. CAGRs were derived from logistic diffusion models fitted to replacement cycle compression patterns. Segmentation modeling incorporated product type, end-user sector, technology architecture, and application function with regional carbon intensity targets as a China-specific demand modifier.
Sensitivities concentrate around MIIT mandate acceleration, copper price volatility, and municipal procurement specification shifts. Forecasts reflect documented assumptions on equipment lifespans and efficiency upgrade elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Global Tubular Heating Elements Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
North America Air Conditioning Equipment Market