
 Japan Commercial HVAC Market | 2026-2036
Japan Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Commercial HVAC Market Insights
METI's Top Runner Program is recalibrating procurement standards across Japan's commercial building stock. Daikin Industries leverages its captive compressor manufacturing to anchor premium VRF system supply chains. Mitsubishi Electric sustains technology leadership through in-house semiconductor-inverter integration. Fujitsu General competes on compact ductless platforms tailored to Japan's dense urban retrofit market.
Japan Commercial HVAC encompasses climate control systems engineered for non-residential buildings, typically operating between 2.5 kW and 500 kW cooling capacity using refrigerant cycles, air distribution networks, and building automation interfaces. Chillers occupy the largest installed base across legacy office towers, while heat pumps represent the fastest-expanding technology segment as building operators retrofit away from fossil-fuel heating. Application demand concentrates in healthcare facilities and educational institutions where indoor air quality standards drive equipment replacement cycles.
METI enforces efficiency benchmarks through the Top Runner Program, while JIS standards govern equipment safety and performance testing protocols. PMDA oversight intersects where HVAC systems serve pharmaceutical manufacturing cleanrooms. Stakeholders must monitor refrigerant phase-down schedules and grid-interactive building codes to align product roadmaps with compliance timelines.
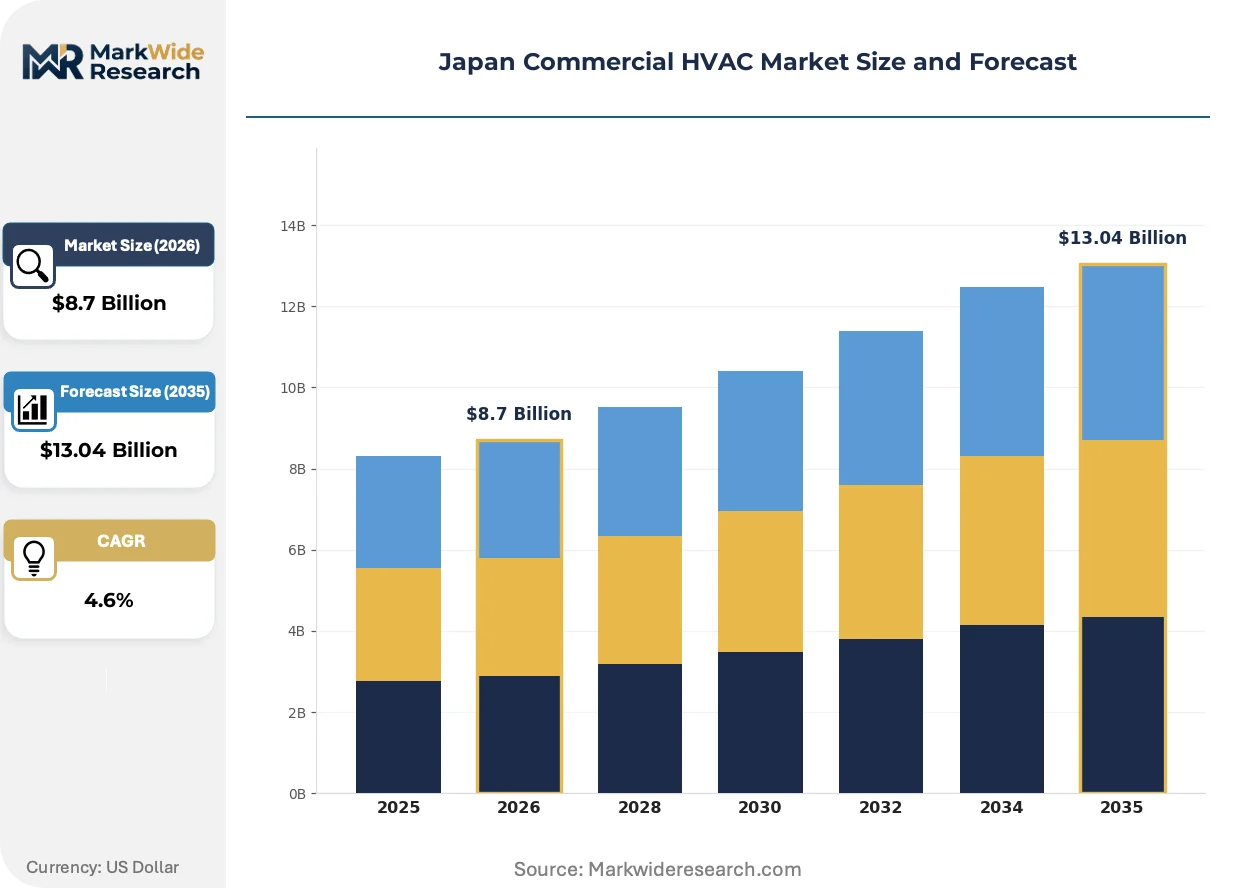
Market Dynamics
Japan's commercial HVAC sector is pivoting decisively around refrigerant phase-down mandates and heat pump technology substitution, with METI's Top Runner Program compressing replacement cycles across the installed base.
Growth Catalysts
- Building Energy Codes:METI's Top Runner Program mandates progressive efficiency improvements, forcing equipment turnover in aging office towers and hospitals.
- Healthcare Infrastructure:Surgical suites and pharmaceutical cleanrooms under PMDA oversight require precision climate control, driving premium system installations.
- Urban Redevelopment:Tokyo, Osaka, and Fukuoka commercial zones are densifying, concentrating demand for compact, high-capacity VRF and ductless platforms.
Market Restraints
- Refrigerant Supply Concentration:Japan relies on imported HFC alternatives and natural refrigerant precursors, exposing distributors to volatile feedstock costs from Chinese chemical processors.
- Skilled Installer Shortage:The pipeline of certified refrigeration technicians is thinning as vocational enrollment drops, extending project timelines for complex heat pump retrofits.
- Grid Capacity Constraints:Electrification of heating loads is straining regional utilities in Hokkaido and Tohoku, where winter peak demand already tests infrastructure limits.
Strategic Opportunities
- Pharmaceutical Manufacturing:Biosimilar production expansion under PMDA guidelines is creating demand for ultra-stable cleanroom HVAC with redundant compressor arrays.
- Building Automation Convergence:Integration of HVAC controls with BEMS and demand-response platforms is opening service revenue streams for system integrators.
- Regional Hospital Modernization:Prefectural governments in Shikoku and Kyushu are consolidating medical facilities, requiring centralized plant HVAC with heat recovery.
Industry Challenges
- Certification Bottlenecks:JIS standards revision cycles lag refrigerant technology shifts, delaying product approvals for low-GWP equipment.
- Legacy System Interoperability:Proprietary control protocols from 1990s-era installations resist integration with modern IoT-enabled management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Commercial HVAC Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Heat Pumps, Air Handling Units, Rooftop Units Technology: Variable Refrigerant Flow, Centralized Systems, Ductless Systems, Geothermal Application: Office Buildings, Retail Spaces, Educational Institutions, Healthcare Facilities End User: Property Management, Facility Management, Construction Companies, Hospitality |
| Companies Covered | Daikin Industries, Ltd., Mitsubishi Electric Corporation, Carrier Corporation, Panasonic Corporation, Hitachi Ltd., Johnson Controls International PLC, Fujitsu General, Toshiba Carrier Corporation, Midea Group Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Commercial HVAC Market Trends and Innovations
Refrigerant chemistry, semiconductor-inverter integration, and service model restructuring are converging to redefine equipment value propositions and vendor-customer relationships across Japan's commercial building stock.
CO2 transcritical heat pump technology is integrating into mid-scale commercial applications, leveraging its superior performance in cold climates where traditional HFC systems lose capacity. Regional supermarket chains and district heating operators in Hokkaido are piloting these systems for combined space conditioning and hot water generation. The technology is integrating building thermal storage with grid demand-response programs, creating new revenue stacking opportunities for facility operators.
METI's 2024 refrigerant phase-down schedule is accelerating equipment replacement decisions, compressing the economic life of R-410A systems and redirecting capital toward R-32 and CO2 platforms. Equipment financiers are recalibrating lease terms to reflect stranded asset risk in legacy refrigerant categories. Pharmaceutical and semiconductor cleanroom operators face the steepest compliance timelines, driving premium pricing for certified low-GWP installations.
Performance-based service contracts are displacing traditional preventive maintenance agreements, with building operators paying for guaranteed uptime and energy outcomes rather than scheduled technician visits. Equipment manufacturers are absorbing operational risk through remote monitoring infrastructure and predictive analytics platforms. This shift is most visible in Tokyo's Class A office towers, where REITs prioritize opex predictability over capex minimization in vendor selection criteria.
Japan Commercial HVAC Market Segmentation
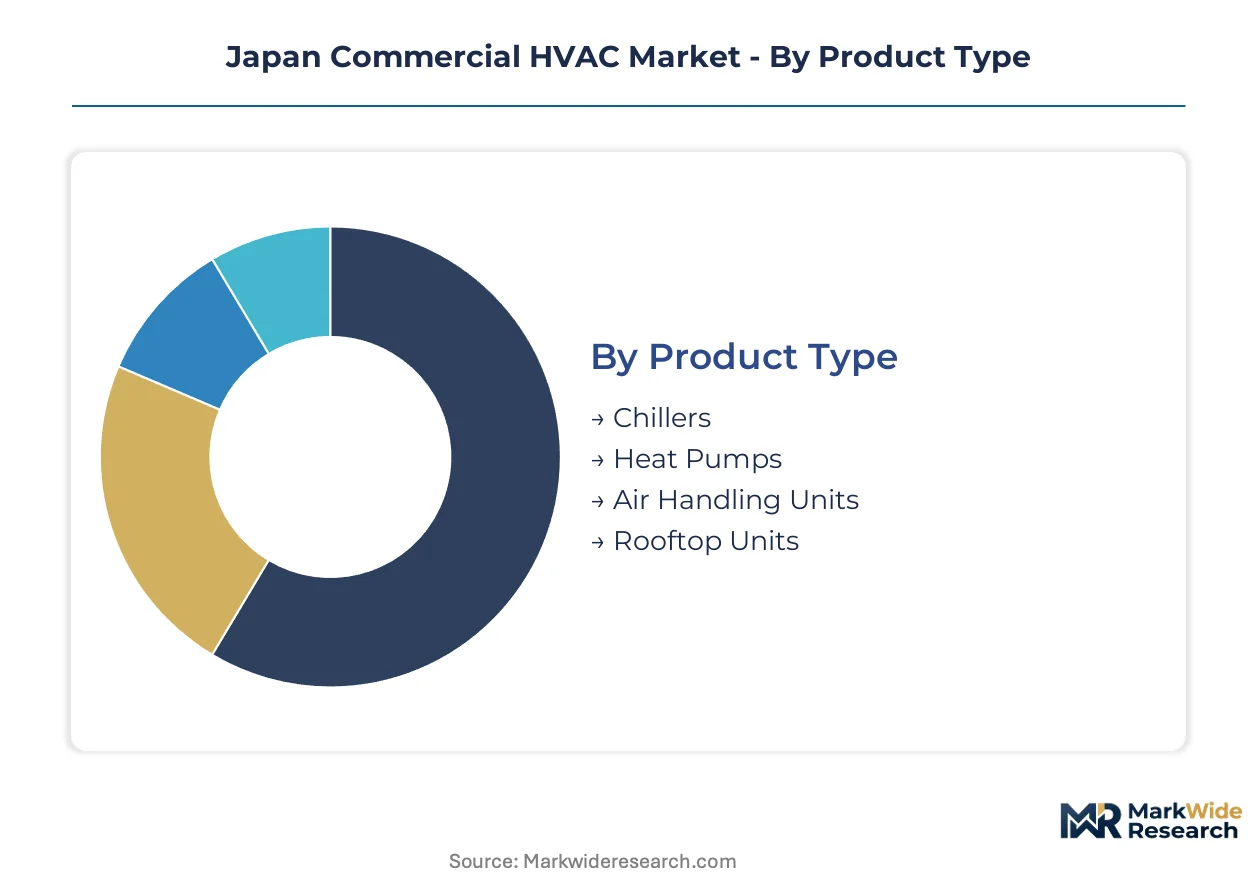
Segmentation in Japan's commercial HVAC market reveals how equipment specifications diverge across building vintages and regulatory pressure points. Understanding these divides helps vendors calibrate R&D investment and service infrastructure to where replacement cycles are compressing fastest.
Product Type:
Standalone packaged systems dominate new construction, while embedded central plant equipment anchors retrofit decisions in Tokyo and Osaka's aging office towers.
- Chillers:Large-capacity centrifugal and screw compressor systems serving centralized chilled water networks. Demand concentrates in legacy financial district towers where METI efficiency mandates are forcing equipment turnover ahead of depreciation schedules.
- Heat Pumps:Refrigerant-cycle systems providing reversible heating and cooling through air-source, water-source, or ground-source exchange. Hospital operators in Kansai and Kyushu are prioritizing these for surgical suite climate control as fossil-fuel heating faces phase-out pressure.
- Air Handling Units:Modular fan-coil assemblies integrating filtration, humidification, and thermal exchange.
- Rooftop Units:Self-contained packaged systems combining compressors, coils, and air distribution in weatherized enclosures.
Chillers lead volumes today; heat pumps are gaining share fastest.
Technology:
Cost tiers separate premium inverter-driven platforms from standard fixed-speed equipment, with margin compression most severe in mid-market ductless categories.
- Variable Refrigerant Flow:Inverter-driven refrigerant distribution systems enabling zoned temperature control across multiple indoor units. Retail chains in Fukuoka's commercial redevelopment zones are specifying these for flexible tenant fit-out configurations.
- Centralized Systems:Chiller-based plants with distributed air handling through duct networks. District cooling operators in Tokyo's Otemachi and Marunouchi districts rely on these for base-load thermal management.
- Ductless Systems:Split and multi-split configurations eliminating ductwork through direct refrigerant lines.
- Geothermal:Ground-coupled heat pumps leveraging stable subsurface temperatures for efficiency gains.
Centralized systems anchor installed value; Variable Refrigerant Flow is climbing the fastest.
Application:
Volume concentrates in sectors where indoor air quality standards intersect with high occupancy density and strict regulatory oversight.
- Office Buildings:Climate control for speculative and owner-occupied commercial towers. Class A properties in central Tokyo are driving premium equipment specifications as REITs prioritize energy performance certifications.
- Healthcare Facilities:Precision environmental control for patient care, surgical suites, and pharmaceutical storage. PMDA oversight of cleanroom operations is mandating redundant compressor arrays and continuous monitoring systems.
- Retail Spaces:Comfort conditioning for shopping centers, convenience stores, and specialty retail.
- Educational Institutions:Ventilation and thermal management for schools and universities.
Office buildings dominate current shipments; healthcare facilities show the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with facility management companies driving performance-based contracting and construction companies favoring lowest-first-cost specifications.
- Property Management:Asset-level oversight of HVAC systems for institutional real estate owners. Operators in Osaka's Umeda district are consolidating vendor relationships around guaranteed uptime contracts with remote monitoring provisions.
- Facility Management:Third-party service providers assuming operational responsibility for building systems. These stakeholders are pushing outcome-based agreements where payment ties to measured energy and availability performance.
- Construction Companies:General contractors and mechanical subcontractors installing equipment in new builds.
- Hospitality:Hotel operators and resort developers specifying guest room and common area climate control.
Property management directs the largest procurement volumes; facility management is expanding its share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's commercial HVAC industry traces its modern foundations to post-war industrialization in the Kanto region, where compressor manufacturing and precision electronics converged to establish the country's dominance in climate control technology.
Kanto/Tokyo
Tokyo's commercial building stock drives replacement demand for high-efficiency heat pumps in aging Marunouchi and Otemachi financial towers. METI's Top Runner Program mandates equipment turnover ahead of standard depreciation cycles. REITs in central Tokyo are consolidating vendor relationships around performance-based service contracts with remote monitoring provisions.
Kansai/Osaka
Osaka's Umeda district healthcare clusters require precision climate control for surgical suites and pharmaceutical cleanrooms under PMDA oversight. The prefectural government is consolidating medical facilities, driving centralized plant HVAC specifications. Urban redevelopment in central Osaka is concentrating demand for compact VRF systems in mixed-use towers.
Chubu/Nagoya
Nagoya's automotive and aerospace manufacturing bases require specialized cleanroom HVAC for precision assembly operations. Industrial facility operators face compressed replacement cycles as refrigerant phase-down schedules accelerate. The region's semiconductor fabrication plants are driving premium specifications for redundant compressor arrays.
Kyushu
Fukuoka's commercial redevelopment zones are densifying with retail and hospitality developments specifying flexible ductless platforms. Prefectural hospital modernization programs are creating demand for heat recovery systems in consolidated medical campuses. The region's pharmaceutical manufacturing expansion under PMDA guidelines requires ultra-stable cleanroom environmental controls.
Hokkaido
Cold-climate performance requirements in Sapporo and regional cities are accelerating CO2 transcritical heat pump adoption for combined space conditioning and hot water. Regional supermarket chains are piloting these systems for district heating integration. Grid capacity constraints during winter peak demand are testing infrastructure limits as electrification of heating loads advances.
Japan Commercial HVAC Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and captive component supply. The vendor base organizes into three tiers: integrated compressor-inverter manufacturers, system assemblers sourcing key components, and regional installation-service specialists. Strategic archetypes include captive supply chain operators, semiconductor-inverter integrators, and compact platform specialists. Dominant competitive moves center on backward integration into compressor manufacturing and convergence with building automation platforms.
Within the integrated tier, Daikin Industries, Ltd. and Mitsubishi Electric Corporation represent archetypes of captive supply chain control, while Fujitsu General occupies a position emphasizing compact platform configurations. These three Japanese manufacturers anchor the competitive structure through differentiated approaches to component integration and urban retrofit specialization.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Mitsubishi Electric Corporation |
| Carrier Corporation |
| Panasonic Corporation |
| Hitachi Ltd. |
| Johnson Controls International PLC |
| Fujitsu General |
| Toshiba Carrier Corporation |
| Midea Group Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Tokyo REITs and Osaka healthcare consortiums concentrate procurement volumes, anchoring a project-based pricing model where long-term service bundling commands premium positioning over equipment-only transactions. METI efficiency mandates compress replacement cycles, forcing vendors to recalibrate lifecycle cost presentations against first-cost minimization pressures from construction contractors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service depth. JIS-compliant systems with PMDA cleanroom certification capture the premium tier, while uncertified fixed-speed equipment serves price-sensitive retail fit-outs. Cost compression in the standard tier intensifies because Chinese compressor imports erode margin buffers. Construction contractors exhibit the highest price sensitivity; facility management companies prioritize opex predictability over capex minimization.
Supply Chain Analysis
JIS certification and PMDA qualification requirements gate market access, filtering component suppliers through rigorous testing protocols. Compressor manufacturing concentrates in Japan and China; inverter semiconductors source from South Korea and Taiwan. Copper tubing and aluminum coil stock draw from regional Japanese metal processors. Single-source vulnerability in refrigerant precursors from Chinese chemical plants exposes distributors to feedstock volatility. Distribution runs through authorized dealer networks with mandatory technician certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
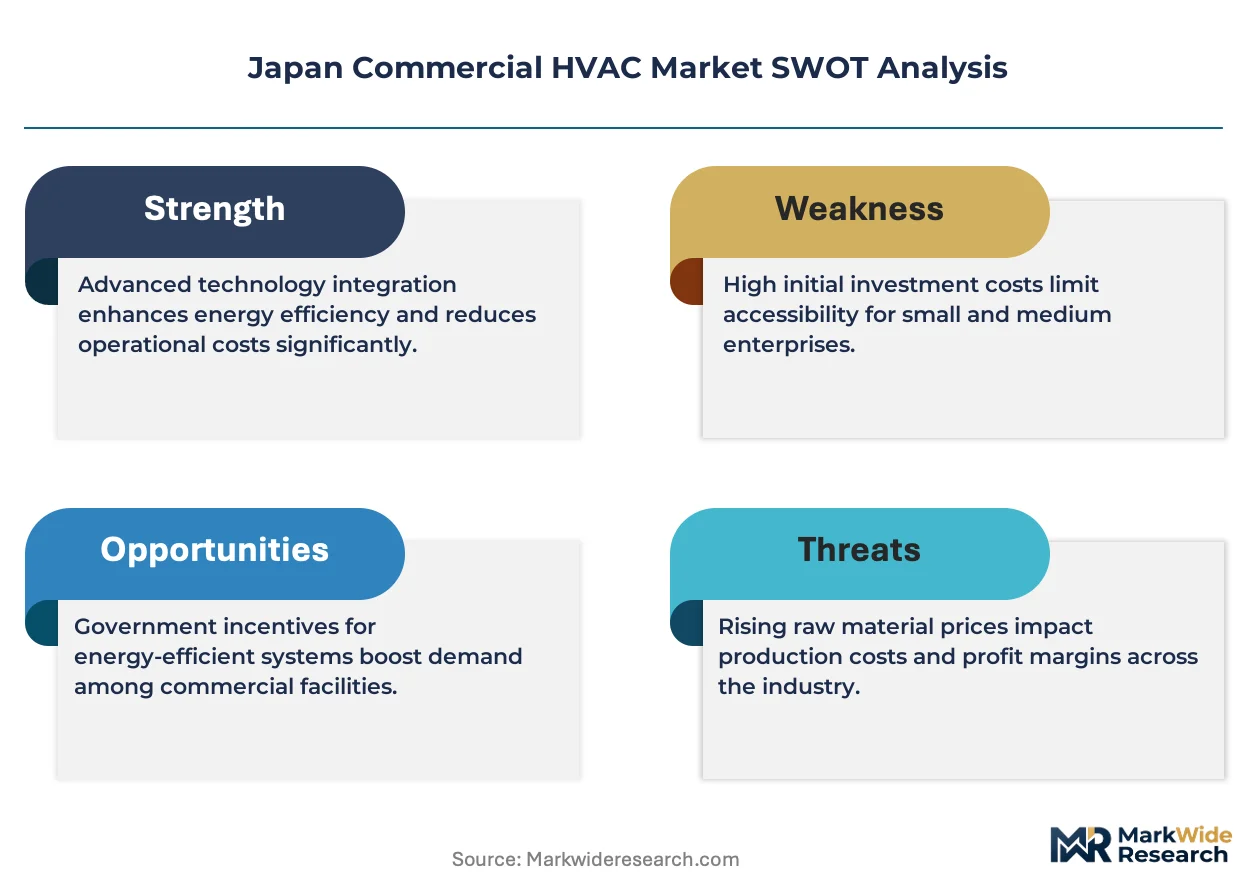
Analyst Recommendations
Japan's commercial HVAC sector represents a late-cycle quality story where METI's Top Runner Program redirects demand toward premium heat pump specifications with embedded IoT diagnostics. Building operators now prioritize guaranteed performance outcomes over lowest-first-cost procurement.
For Market Incumbents: Extend service contract penetration into Class A office towers by absorbing operational risk through remote monitoring infrastructure. Consolidate backward integration into inverter semiconductor production to defend margin position against Korean component suppliers. Daikin and Mitsubishi Electric should deepen captive supply control over low-GWP refrigerant distribution channels before phase-down deadlines compress replacement demand. For New Entrants and Emerging Players: Regional hospital modernization programs in Shikoku and Kyushu present an underserved buyer archetype with concentrated procurement authority and limited incumbent relationships. Compact CO2 transcritical platforms for Hokkaido's cold climate applications offer a penetrable technology segment with fewer established specialists. A go-to-market angle through prefectural government framework agreements bypasses Tokyo-centric dealer network barriers. For Investors and Strategic Acquirers: Building automation integrators are the most active acquirer in this space, seeking HVAC controls expertise to complete BEMS platform offerings. The five-to-ten-year viability window favors targets with certified cleanroom installation capabilities and recurring service revenue above forty percent of total sales. Acquisition candidates should demonstrate JIS certification breadth across multiple refrigerant platforms. The signal to watch is METI's refrigerant phase-down enforcement intensity accelerating equipment replacement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply control insulates margin pressure from Chinese component volatility. |
| Performance-Based Service Contract Expansion | REITs in Tokyo prioritize opex predictability over traditional preventive maintenance agreements. |
| CO2 Transcritical Platform Development | Cold-climate superiority in Hokkaido opens supermarket and district heating applications. |
| Building Automation Convergence | BEMS integration creates recurring software revenue streams beyond equipment sales. |
| Prefectural Hospital Framework Positioning | Consolidated medical facility procurement in Kyushu reduces customer acquisition costs. |
Research Methodology
Direct dialogue with HVAC equipment manufacturers, facility management executives, refrigeration technician training programs, and prefectural hospital procurement officers grounded qualitative insights. Secondary validation drew from METI efficiency program filings, JIS standards documentation, PMDA cleanroom guidelines, and Japanese construction industry association reports. Bottom-up equipment shipment analysis triangulated against top-down building stock replacement modeling.
Market size and growth trajectories across the projection horizon reflect segmented modeling by product type, technology tier, application vertical, and end-user procurement sophistication. The analytical framework incorporated heat pump adoption curves, refrigerant phase-down compliance timelines, and urban redevelopment pipeline data. CAGRs were derived from equipment replacement cycle compression under METI mandates and healthcare infrastructure investment patterns.
Inputs from METI regulatory filings and prefectural government budget disclosures were available through the study window; gaps in real-time dealer inventory data introduce uncertainty bands around quarterly shipment estimates. Forecasts reflect assumptions about technician certification pipeline recovery and grid capacity expansion in Hokkaido. A model refresh is warranted upon material change in METI's Top Runner Program enforcement intensity or refrigerant import tariff adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
North America Ceiling Cassette Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Tubular Heater Market