
 Global Large-Scale Natural Refrigerant Heat Pump Market | 2026-2036
Global Large-Scale Natural Refrigerant Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Large-Scale Natural Refrigerant Heat Pump Market Outlook
Aftermarket service revenue is rewriting how suppliers capture lifetime value in this sector. Johnson Controls leverages its building automation footprint to lock in long-term maintenance contracts across North American installations. GEA Group Aktiengesellschaft anchors its position through specialized ammonia compressor engineering that sustains premium pricing in European food processing. Mitsubishi Electric Corporation dominates Asian project development by controlling local distributor networks for large-capacity scroll and screw configurations.
Large-scale natural refrigerant heat pumps transfer thermal energy using ammonia, carbon dioxide, or hydrocarbon working fluids in capacities exceeding 500 kW, typically achieving coefficient of performance ratings between three and five depending on source temperature and sink requirements. These systems serve district heating networks, industrial process heat, and commercial climate control where synthetic refrigerant restrictions have eliminated conventional alternatives. The Carnot Cycle technology segment leads installed capacity due to its maturity in high-lift applications, while absorption systems are gaining traction in waste-heat recovery scenarios where steam or exhaust drives the refrigeration cycle. Deployment patterns favor centralized configurations for district heating retrofits because single-plant economies reduce balance-of-system costs, though decentralized units are penetrating commercial building portfolios where modular scaling matches variable load profiles.
The EU F-Gas Regulation mandates an 80 percent reduction in hydrofluorocarbon consumption by 2030, directly compelling heating infrastructure replacement across member states. EPA SNAP program restrictions in the United States parallel this trajectory by delisting high-global-warming-potential alternatives for new commercial equipment. Japan's METI has codified natural refrigerant deployment targets in its latest strategic energy plan, tightening product certification pathways. Stakeholders must monitor how national building codes synchronize with refrigerant phase-down timelines to anticipate procurement cycle acceleration or delay.
Market Dynamics
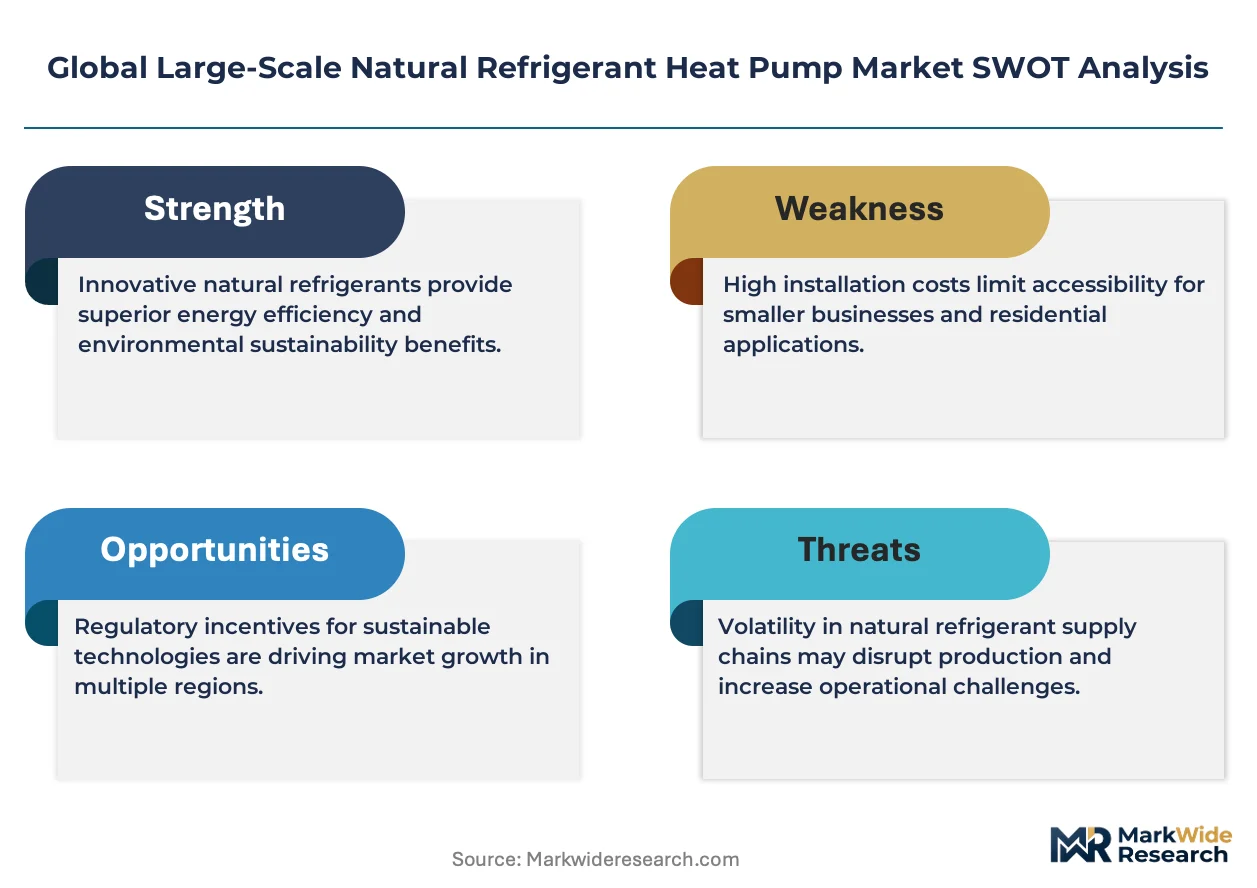
The EU F-Gas Regulation's 80 percent hydrofluorocarbon phase-down by 2030 is forcing district heating operators across Northern Europe to replace synthetic refrigerant infrastructure with ammonia and carbon dioxide systems. This regulatory compression is redrawing supplier relationships and procurement timelines.
Growth Catalysts
- EU F-Gas Regulation:The mandated refrigerant phase-down compels municipal heating plant retrofits in Germany, Denmark, and Sweden. District network operators face compliance deadlines that compress replacement cycles.
- Industrial Process Heat Recovery:Food processing facilities in the Netherlands and Belgium deploy absorption heat pumps to capture waste steam. Carnot Cycle systems achieve coefficient of performance ratings above four in these applications.
- Carbon Dioxide Transcritical Systems:Japanese commercial building portfolios adopt large-capacity CO2 configurations for simultaneous heating and cooling. METI certification pathways accelerate domestic deployment.
Market Restraints
- Specialized Compressor Supply Concentration:European ammonia compressor manufacturing clusters in Germany and Denmark. Limited qualified suppliers extend lead times for projects above 2 MW capacity.
- Copper and Steel Input Volatility:Heat exchanger fabrication depends on copper tube and stainless steel plate availability. Commodity price swings compress equipment margins for mid-scale manufacturers.
- Ammonia Safety Code Friction:Local fire and building codes in France and Italy impose site-specific requirements that delay permitting. Regulatory inconsistency across EU member states fragments project execution.
Strategic Opportunities
- Underpenetrated US District Heating:EPA SNAP program restrictions on high-GWP refrigerants create first-mover openings in Minneapolis, Boston, and Seattle municipal networks. Federal IRA incentives offset capital intensity for early adopters.
- Data Center Thermal Integration:Hyperscale facilities in Ireland and Finland seek heat pump coupling with liquid cooling infrastructure. Waste heat export to district networks generates dual revenue streams.
- Green Hydrogen Electrolyzer Coupling:Danish and Norwegian projects integrate heat pumps with electrolysis waste heat. This convergence reduces hydrogen production energy intensity by 8-12 percent.
Industry Challenges
- Ammonia Refrigeration Technician Scarcity:Certified installation and maintenance specialists concentrate in Northern Europe. North American and Asian markets face 18-24 month training pipelines.
- Legacy Control System Integration:Municipal heating plants in Eastern Europe operate 1980s-era SCADA infrastructure. Retrofit compatibility demands custom engineering that extends commissioning timelines.
- ASME and PED Certification Parallel Tracks:Equipment serving transatlantic projects requires dual pressure vessel certification. Documentation burden adds 4-6 months to delivery schedules.
Report Scope
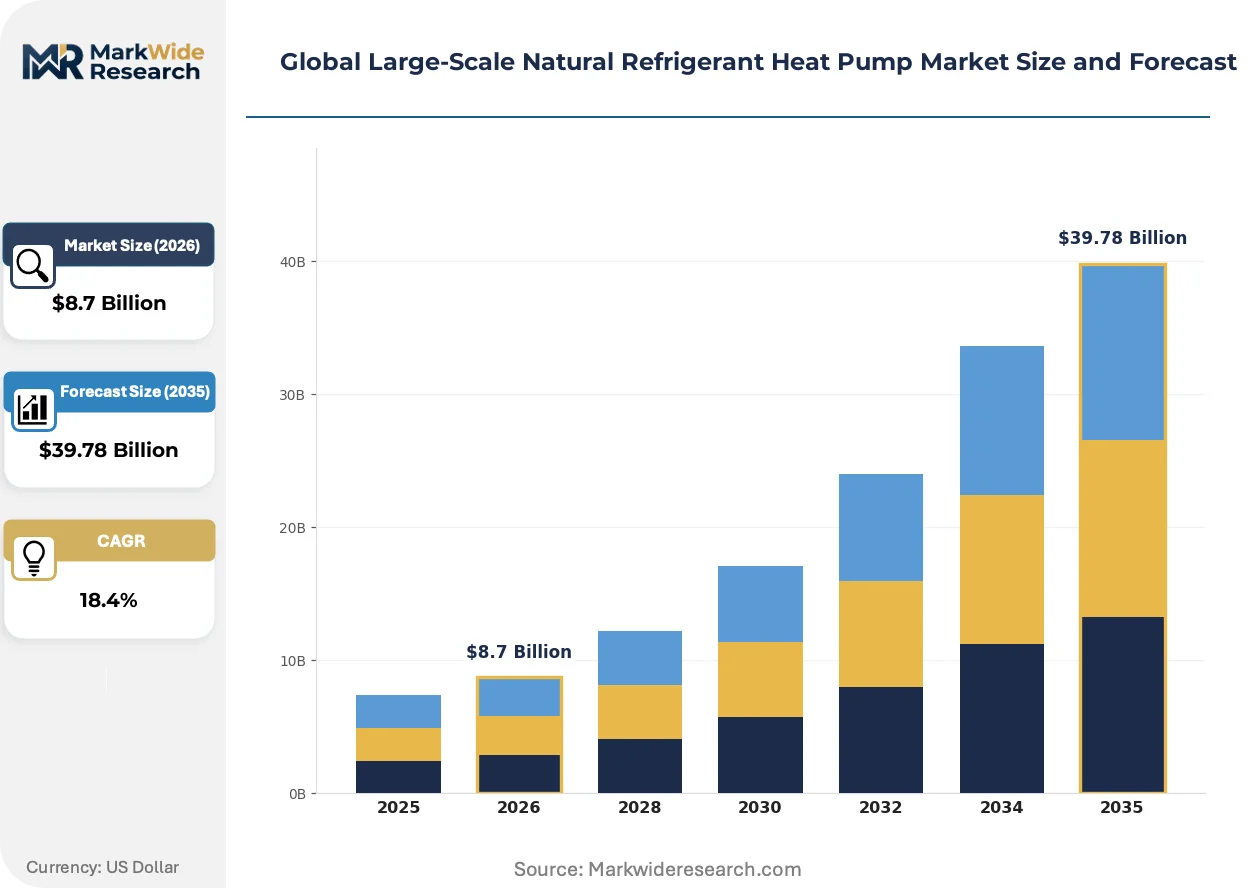
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Large-Scale Natural Refrigerant Heat Pump Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Carnot Cycle, Absorption, Steam-Driven, Natural Gas End User: Industrial Facilities, Commercial Buildings, Agricultural Sector, Cold Storage Deployment: On-Premise, Off-Grid, Centralized, Decentralized Heat Source: Geothermal, Solar Thermal, Ambient Air, Ground Source |
| Companies Covered | Johnson Controls, GEA Group Aktiengesellschaft, Mitsubishi Electric Corporation, Panasonic Holdings Corporation, Siemens Energy, Thermax Limited, Star Refrigeration, Mayekawa Manufacturing Co., Clade Engineering Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Large-Scale Natural Refrigerant Heat Pump Market Strategic Shifts
Digital twin architecture is virtualizing how heat pump systems are commissioned, operated, and maintained across district heating networks. This shift compresses fault detection cycles and enables predictive service interventions.
Digital twin platforms replicate thermal performance and mechanical stress across ammonia compressor arrays and heat exchanger banks in real time. District heating operators in Copenhagen and Hamburg deploy these systems to optimize part-load efficiency. The technology is virtualizing traditional scheduled maintenance contracts into continuous performance guarantees.
The EU F-Gas Regulation's 2024 tightening of quota allocation rules accelerates refrigerant cost escalation for synthetic alternatives. Equipment purchasers in Poland and the Czech Republic now face five-year total cost of ownership parity between natural and synthetic refrigerant systems. Food processing installations above 1 MW capacity are responding by specifying ammonia in 90 percent of new tenders.
Energy service companies unbundle heat pump hardware from thermal output contracts in Swedish and Finnish municipal markets. District heating authorities purchase guaranteed temperature delivery rather than capital equipment. This procurement compression transfers operational risk to vendors and locks in 15-20 year service relationships.
Global Large-Scale Natural Refrigerant Heat Pump Market Segmentation
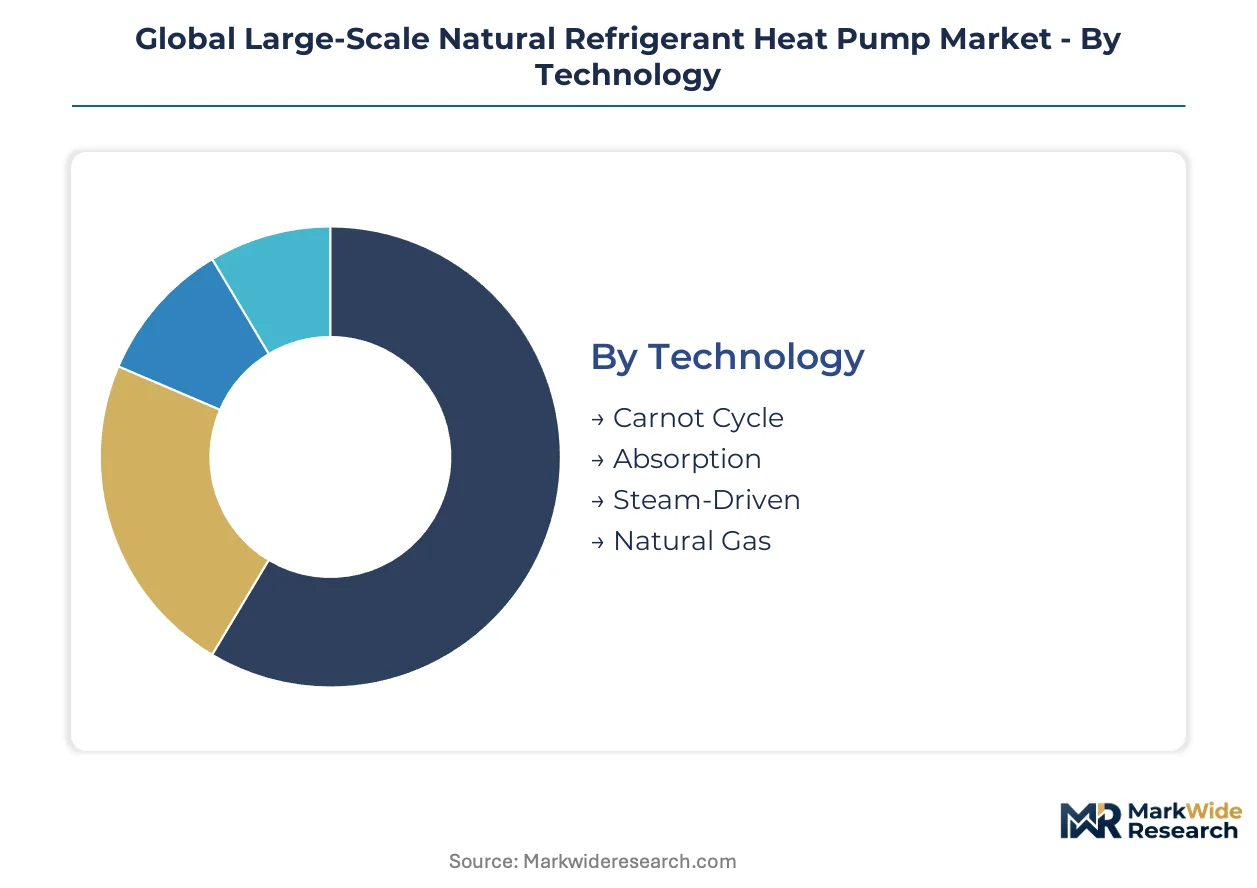
Segmentation in this market reveals how technology choices, deployment architectures, and heat source configurations align with regulatory pressures and site-specific thermal demands. Distinct procurement patterns emerge across district heating authorities, industrial processors, and commercial developers.
Technology:
The use-case spectrum spans established mechanical compression to thermally activated systems, each matching different temperature lifts and waste heat availability.
- Carnot Cycle:Mechanical vapor compression systems using ammonia or CO2 refrigerants achieve coefficient of performance ratings between three and five. District heating networks in Denmark and Germany specify these configurations for high-lift applications where source temperatures fall below 10°C.
- Absorption:Lithium bromide or ammonia-water systems utilize waste steam or exhaust heat to drive the refrigeration cycle. Food processing facilities in the Netherlands deploy these units to recover thermal energy from sterilization processes.
- Steam-Driven:Direct thermal activation using medium-pressure steam bypasses electrical compression entirely. Industrial clusters with captive cogeneration capacity favor this architecture for process heat delivery above 80°C.
- Natural Gas:Gas-engine-driven compressors provide mechanical work while capturing engine jacket heat for combined thermal output. Remote facilities lacking grid capacity specify these units in Norwegian district heating extensions.
The dominant share belongs to Carnot Cycle systems, while Absorption technology is closing the gap fastest.
End User:
Cost tier differentiation separates capital-intensive municipal infrastructure from modular commercial installations with shorter payback horizons.
- Industrial Facilities:Chemical processors and food manufacturers require heat delivery above 100°C for pasteurization and reaction processes. German pharmaceutical plants specify ammonia systems to comply with EU F-Gas Regulation phase-down timelines.
- Commercial Buildings:Office complexes and retail centers prioritize simultaneous heating and cooling functionality. Japanese METI-certified CO2 transcritical systems dominate this segment in urban mixed-use developments.
- Agricultural Sector:Greenhouse operators and livestock facilities demand consistent low-grade heat for climate control. Danish agricultural cooperatives cluster decentralized ammonia units across regional heating collectives.
- Cold Storage:Refrigeration warehouses seek heat recovery from cooling cycles for space heating and defrost functions. Swedish logistics parks integrate these systems with district network connections for excess heat export.
Industrial Facilities command the largest installed base, though Commercial Buildings are expanding most quickly.
Deployment:
Volume concentration favors centralized architectures where single-plant economies reduce balance-of-system costs for district heating retrofits.
- On-Premise:Dedicated systems serving single facilities with tailored capacity and control integration. Finnish paper mills deploy these configurations for process steam generation adjacent to production lines.
- Off-Grid:Standalone installations in remote locations without electrical infrastructure connection. Norwegian fishing processing villages specify gas-driven units in coastal areas beyond transmission network reach.
- Centralized:Single large-capacity plants feeding extensive distribution networks. Hamburg and Copenhagen municipal authorities anchor district heating with 10+ MW ammonia facilities.
- Decentralized:Modular units distributed across multiple sites with aggregated thermal output. German residential quarters deploy these systems to reduce primary network investment in low-density areas.
Centralized deployment retains the dominant position, while Decentralized configurations are gaining share fastest.
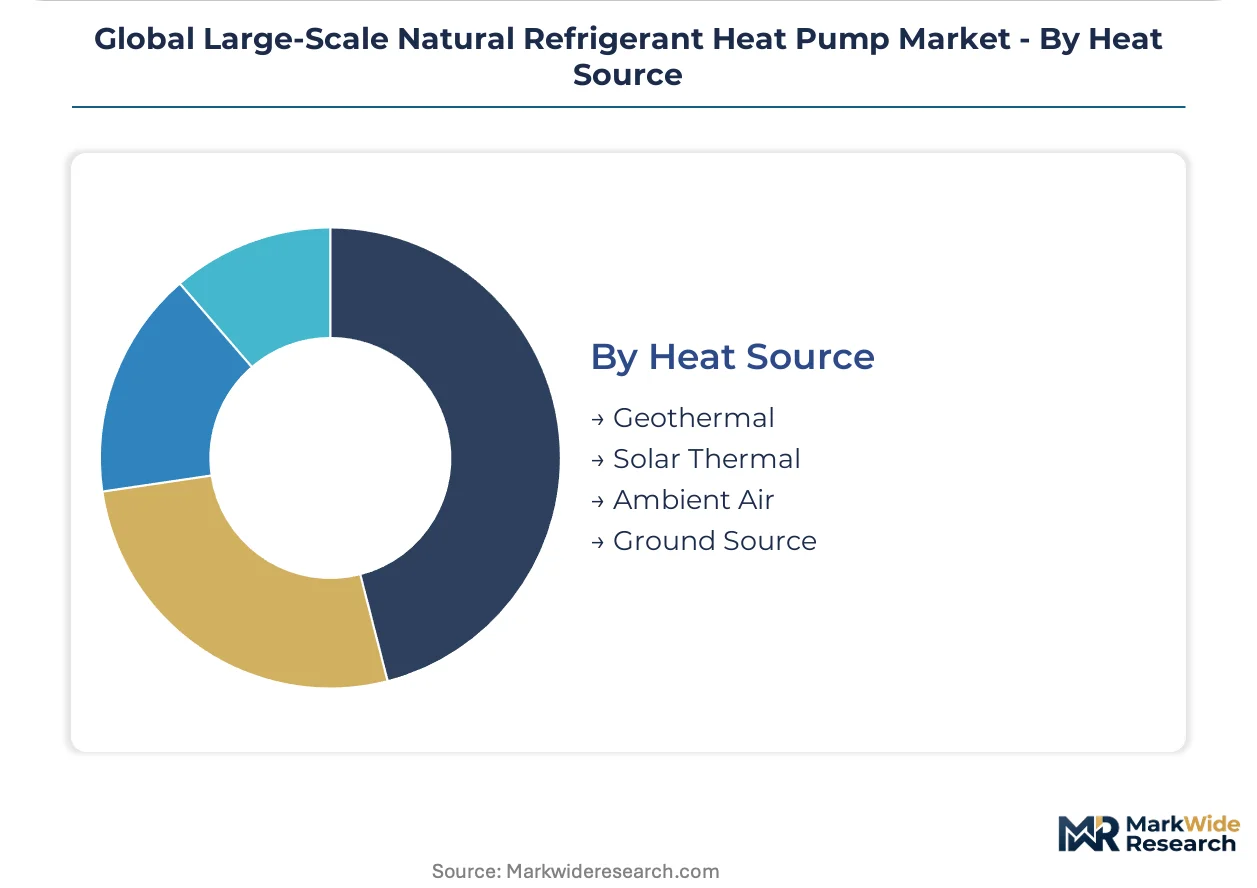
Heat Source:
Geographic availability of low-grade thermal energy dictates system specification and seasonal performance variation.
- Geothermal:Deep aquifer or hot dry rock extraction provides stable year-round source temperatures. Icelandic district heating networks leverage this resource with ammonia heat pumps for temperature amplification.
- Solar Thermal:Large-scale collector arrays feed seasonal storage for winter heat pump operation. Danish solar district heating plants combine these sources with heat pumps to extend delivery capacity.
- Ambient Air:Atmospheric heat extraction using finned coil evaporators in variable conditions. Swedish commercial buildings specify these systems where ground access is restricted by urban density.
- Ground Source:Borehole heat exchangers or horizontal collectors exploit stable subsurface temperatures. German residential developments favor this approach for its consistent seasonal coefficient of performance.
Geothermal sources anchor the largest capacity share, though Ambient Air systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across markets. Municipal buyers in Northern Europe absorb premium equipment costs through long-term energy service contracts. Commercial developers in Japan and North America demand rapid payback periods that compress acceptable capital expenditure thresholds.
Germany
District heating networks in Hamburg and Berlin drive ammonia system deployment at 10+ MW scale. The EU F-Gas Regulation's 2030 phase-down deadline accelerates municipal procurement cycles. Manufacturing clusters in Bavaria and North Rhine-Westphalia supply specialized compressors that extend lead times for cross-border projects.
United States
EPA SNAP program restrictions on high-GWP refrigerants create first-mover openings in Minneapolis, Boston, and Seattle municipal networks. Federal IRA incentives offset capital intensity for early district heating adopters. The Pacific Northwest and Northeast corridor concentrate project development where building codes align with refrigerant transition timelines.
Denmark
Copenhagen's district heating authority anchors centralized ammonia facilities feeding extensive distribution networks. National building codes synchronize with EU F-Gas Regulation enforcement. Agricultural cooperatives in Jutland cluster decentralized units across regional heating collectives.
Japan
METI-certified CO2 transcritical systems dominate urban mixed-use developments in Tokyo and Osaka. The Ministry of Economy, Trade and Industry codified natural refrigerant deployment targets in its latest strategic energy plan. Commercial building portfolios adopt large-capacity configurations for simultaneous heating and cooling functionality.
Sweden
Energy service companies unbundle hardware from thermal output contracts in Stockholm and Malmö municipal markets. District heating authorities purchase guaranteed temperature delivery rather than capital equipment. Logistics parks in Gothenburg integrate heat recovery systems with district network connections for excess heat export.
Global Large-Scale Natural Refrigerant Heat Pump Market Competitive Environment
Capability concentration sits with engineering-intensive specialists; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: premium-positioned technology originators, mid-scale regional fabricators, and building automation integrators seeking thermal hardware adjacencies. Two competitive vectors dominate: long-term service contract capture that transfers operational risk from buyers to vendors, and vertical integration into compressor manufacturing that secures supply chain control for high-capacity projects.
Within the diversified industrial tier, Johnson Controls exemplifies building automation leverage into maintenance contract lock-in. GEA Group Aktiengesellschaft occupies a position among German engineering specialists focused on ammonia compressor systems. Mitsubishi Electric Corporation anchors the Asian project development vector through distributor network control for large-capacity configurations.
| Leading Market Players |
|---|
| Johnson Controls |
| GEA Group Aktiengesellschaft |
| Mitsubishi Electric Corporation |
| Panasonic Holdings Corporation |
| Siemens Energy |
| Thermax Limited |
| Star Refrigeration |
| Mayekawa Manufacturing Co. |
| Clade Engineering Systems Ltd. |
| Others |
Value Chain & Pricing Dynamics
Bavarian and North Rhine-Westphalian manufacturing clusters anchor European compressor supply, concentrating pricing power among German engineering specialists who command premium positioning for ammonia systems above 2 MW capacity. This geographic concentration transfers downstream into extended lead times and tiered equipment quotations that differentiate municipal district heating authorities from commercial developers.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture more than initial hardware sales, with energy service companies in Sweden and Finland unbundling thermal output guarantees from capital equipment procurement. Three-tier pricing structure across premium engineering-grade, standard industrial, and economy modular levels separates buyers by certification complexity and service bundling. Pricing pressure stems from copper and steel input volatility compressing margins for mid-scale heat exchanger fabricators. Municipal buyers in Northern Europe show lowest price sensitivity through long-term energy service contracts, while North American commercial developers demand rapid payback periods that compress acceptable capital expenditure thresholds.
Supply Chain Analysis
Copper tube and stainless steel plate feedstock availability constrains heat exchanger fabrication capacity across Germany, Denmark, and Japan. Component sourcing draws from specialized ammonia compressor manufacturing clusters in Northern Europe and scroll/screw configuration assembly lines in Japan. Single-source vulnerability concentrates in qualified suppliers for projects exceeding 2 MW capacity, extending delivery schedules when demand surges. Distribution runs through direct vendor relationships with district heating authorities and industrial EPC contractors rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where maintenance contract expansion outpaces hardware revenue growth, particularly as energy service companies assume operational risk through guaranteed thermal output agreements.
For Market Incumbents: Build switching-cost moats through SCADA integration and predictive maintenance platforms that virtualize traditional scheduled service contracts. Deepen backward integration into compressor manufacturing to secure supply chain control for high-capacity ammonia projects. Address certified technician scarcity by funding apprenticeship pipelines in North America and Asia. Leverage building automation footprints to lock in 15-20 year service relationships before competitors establish comparable digital twin capabilities. For New Entrants and Emerging Players: Establish a beachhead in US district heating retrofits where EPA SNAP program restrictions create first-mover openings in Minneapolis, Boston, and Seattle municipal networks. Target data center thermal integration in Ireland and Finland where hyperscale facilities seek heat pump coupling with liquid cooling infrastructure. Pursue green hydrogen electrolyzer coupling projects in Denmark and Norway as convergence applications reduce customer acquisition costs through shared engineering requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because EU F-Gas Regulation enforcement and parallel EPA restrictions eliminate synthetic refrigerant alternatives regardless of equipment economics. Acquisition targets should cluster around ammonia compressor engineering specialists with captive certification pathways and established municipal relationships. Monitor permitting velocity in France and Italy as an inflection indicator—regulatory harmonization or continued friction will determine whether project execution scales efficiently or fragments across member-state code variations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Virtualizes commissioning and predictive maintenance, compressing fault detection cycles for Copenhagen and Hamburg operators. |
| Ammonia Compressor Backward Integration | Secures supply chain control for high-capacity projects above 2 MW where qualified European suppliers concentrate. |
| Energy Service Contract Unbundling | Transfers operational risk to vendors through guaranteed temperature delivery rather than capital equipment sales. |
| North American Technician Apprenticeship Investment | Addresses 18-24 month training pipelines that constrain installation and maintenance capacity expansion. |
| ASME-PED Dual Certification Streamlining | Reduces 4-6 month documentation burden for transatlantic projects serving both US and EU regulatory frameworks. |
Study Parameters
A standing panel of district heating authority procurement directors, ammonia compressor engineering specialists, industrial process heat managers, and energy service company executives provided ongoing calibration across the study period. This primary fieldwork combined with secondary validation from EU F-Gas Regulation implementation reports, EPA SNAP program delisting announcements, METI strategic energy plan documentation, and customs trade data for copper and steel inputs. Bottom-up project pipeline enumeration triangulated against top-down regulatory mandate sizing to establish market boundaries.
Scenario bracketing around refrigerant phase-down velocity, commodity input volatility bands, and permitting timeline variations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, deployment architecture, heat source configuration, and end-user sector with regional regulatory cluster overlays. CAGRs derived from equipment replacement cycle compression analysis and energy service contract penetration curves, with specific inputs from district heating network retrofit pipelines and industrial waste heat recovery project development databases.
Stress conditions across copper price volatility, ammonia safety code harmonization failure, and certified technician training pipeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and municipal procurement acceleration timelines. Cross-checking against IEA district heating deployment benchmarks and national building code synchronization indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Industrial Electric Boiler Market