
 Canada Outdoor Air Source Heat Pump Market | 2026-2036
Canada Outdoor Air Source Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Outdoor Air Source Heat Pump Market Insights
The capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is unwinding competitive stability in the Canada outdoor air source heat pump landscape. Carrier leverages captive compressor technology and cold-climate R&D infrastructure to sustain premium positioning across Ontario and Quebec. Daikin Industries Ltd. anchors its Canadian presence through localized distribution networks and residential ductless specialization. Mitsubishi Electric Corporation differentiates via hyper-heating inverter performance at sub-zero temperatures, a capability that commands specification in Atlantic Canada.
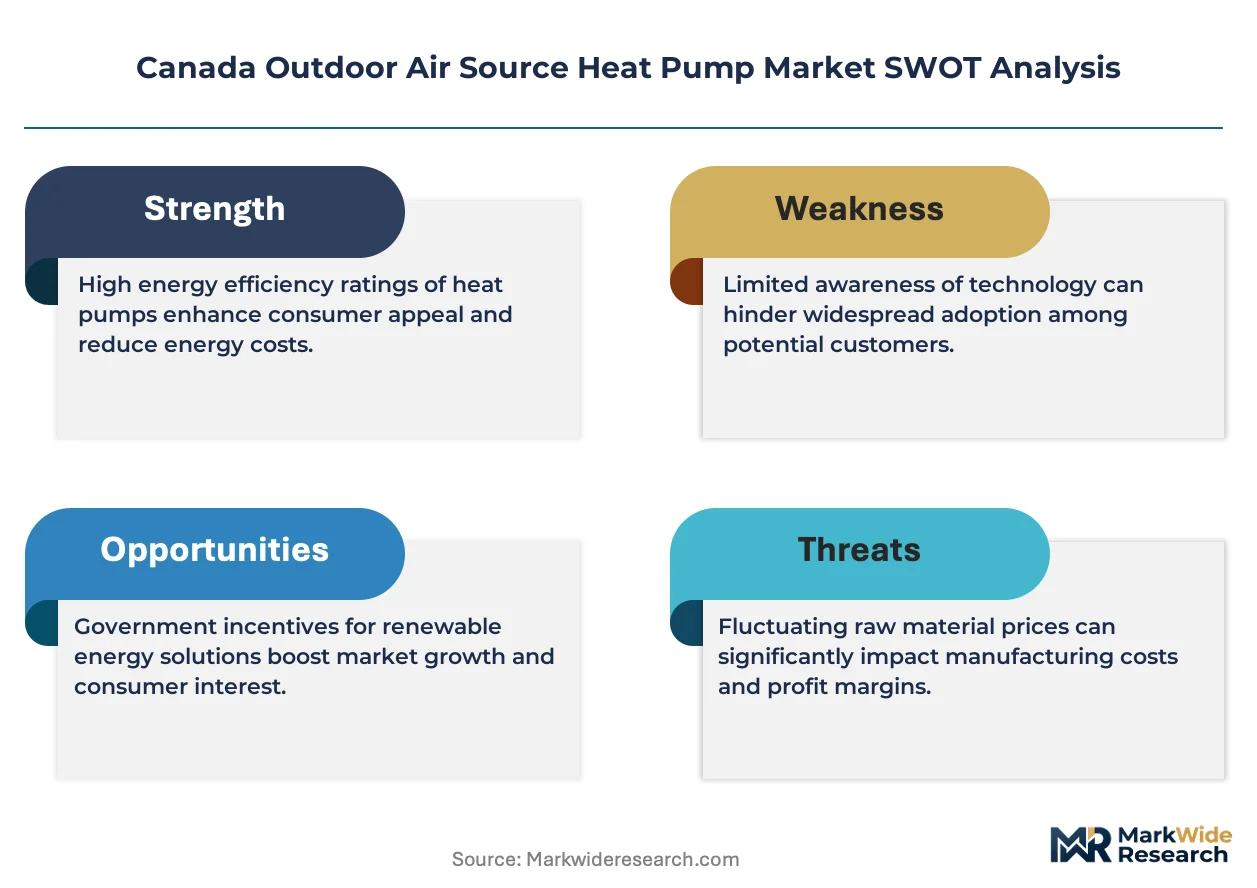
Canada outdoor air source heat pumps are electrically driven vapor-compression systems that extract thermal energy from ambient air for space heating, typically operating with coefficient of performance ratings between two and four at minus fifteen degrees Celsius. These systems serve residential and commercial buildings seeking to displace natural gas combustion for primary heating duty. Ductless mini-splits occupy the dominant volume position in residential retrofits where existing hydronic or forced-air distribution proves incompatible with heat pump integration. Multi-zone systems represent the fastest-expanding product category as builders specify whole-home electrification in new construction across British Columbia and Quebec. Energy Star and AHRI Certified efficiency tiers concentrate margin pools, with cold-climate HSPF thresholds above ten commanding price premiums in Prairie provinces.
Health Canada and PMRA influence refrigerant transition timelines through environmental fate assessments, while Natural Resources Canada administers equipment efficiency verification under the EnerGuide program. Provincial regulators in Quebec and British Columbia enforce building code amendments that effectively mandate heat-ready construction or full electrification in new residential builds. Stakeholders must monitor the interplay between federal carbon pricing escalation and provincial utility rate structures, as this dynamic determines payback periods and retrofit economics across Canada's climatically disparate regions.
Market Dynamics
Federal carbon pricing escalation combined with Natural Resources Canada's Greener Homes Grant is compressing payback periods for residential electrification across climatically disparate provinces. This dual policy architecture is reshaping procurement criteria and cold-climate performance specifications simultaneously.
Growth Catalysts
- Ontario Building Code amendments:New residential construction mandates in the Greater Toronto Area are accelerating heat-ready specifications. Builders now pre-wire for full electrification as standard practice.
- British Columbia CleanBC incentives:Provincial utility rate structures and electrification rebates are pulling forward replacement cycles for aging natural gas furnaces in the Vancouver metropolitan corridor.
- Cold-climate inverter R&D:Hyper-heating performance at sub-zero temperatures is expanding addressable market coverage into Atlantic Canada and Prairie provinces previously deemed unsuitable for air-source deployment.
Market Restraints
- Copper and rare earth input volatility:Compressor motor laminations and refrigerant line sets face commodity price swings that compress assembly-dependent margins.
- Atlantic Canada contractor scarcity:Certified installer density remains insufficient to match demand acceleration in Newfoundland and Labrador.
- Legacy hydronic distribution incompatibility:Existing radiant floor systems in Quebec and Ontario create technical friction for ductless mini-split retrofits.
Strategic Opportunities
- Manitoba and Saskatchewan underpenetration:Prairie provinces with lower electricity rates present whitespace for cold-climate HSPF-above-ten product categories.
- Multi-zone new construction specification:Whole-home electrification in British Columbia and Quebec builder channels represents the fastest-expanding product category.
- Natural Resources Canada EnerGuide tier advancement:Federal efficiency verification programs are creating certification-driven preference shifts toward AHRI Certified cold-climate tiers.
Industry Challenges
- Refrigerant handling certification gaps:Provincial HVAC trades face training pipeline constraints for A2L and lower-GWP refrigerant transition timelines mandated by Health Canada and PMRA environmental fate assessments.
- Utility interconnection backlogs:Distribution system capacity upgrades in Ontario and British Columbia are delaying project completions despite equipment availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Outdoor Air Source Heat Pump Market |
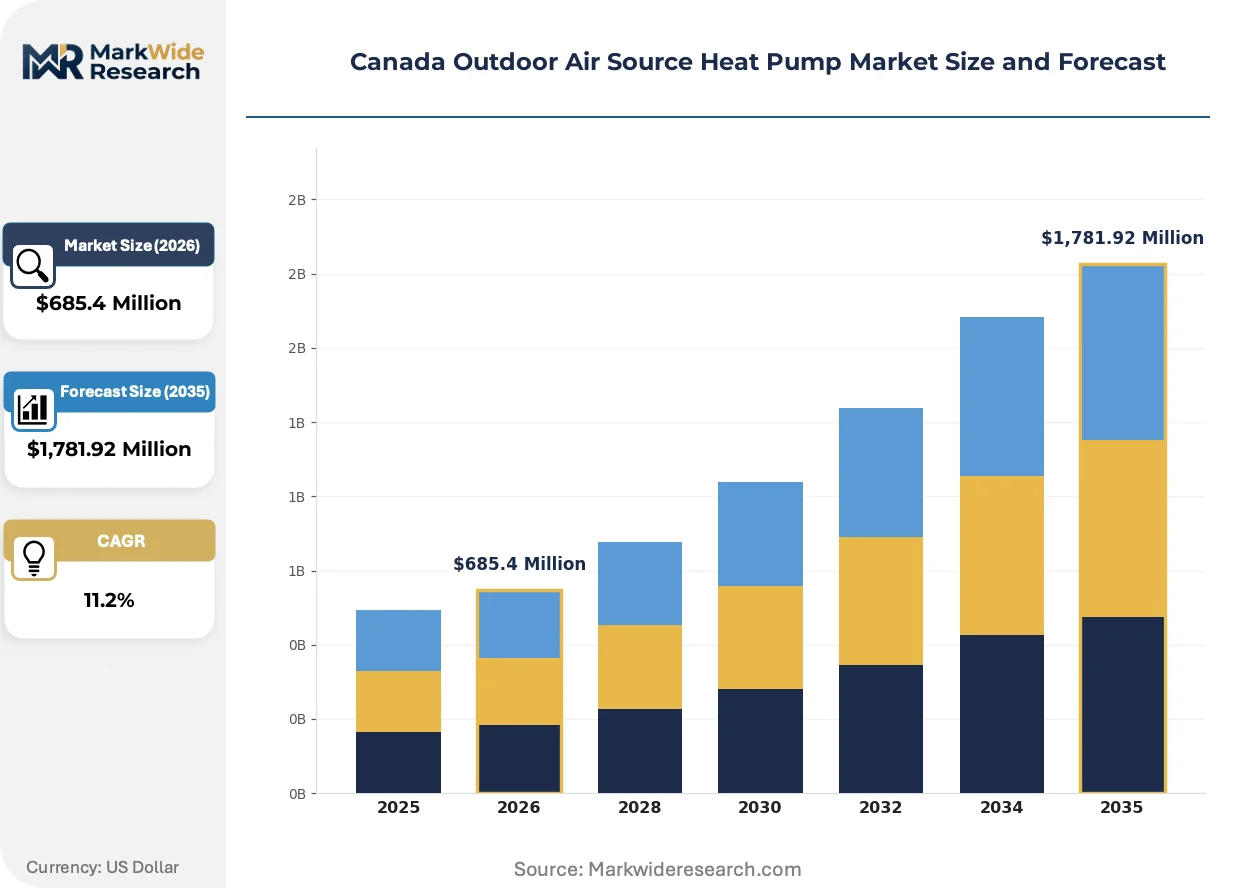
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,781.92 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Zone Systems, Multi-Zone Systems, Ductless Mini-Splits, Ducted Systems End User: Residential, Commercial, Industrial, Government Installation Type: Retrofit, New Construction, Modular, Integrated Energy Efficiency Rating: SEER, HSPF, Energy Star, AHRI Certified |
| Companies Covered | Carrier, Daikin Industries Ltd., Ingersoll-Rand Plc (Trane), Robert Bosch GmbH, Danfoss, Mitsubishi Electric Corporation, Panasonic Holdings Corporation, LG Electronics, Inc., Rheem Manufacturing Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Outdoor Air Source Heat Pump Market Trends and Innovations
Cold-climate performance standards and refrigerant chemistry transitions are fragmenting product architectures across Canada's provincial regulatory patchwork. Equipment manufacturers must now engineer for multiple efficiency verification regimes simultaneously.
Variable-speed compressor modulation is fragmenting the traditional single-stage residential market. Atlantic Canada homeowners facing volatile heating degree-day patterns are specifying hyper-heating inverter systems that maintain capacity at minus twenty-five degrees Celsius. This performance tier is compressing specification windows for conventional cold-climate units in coastal British Columbia and Quebec.
Health Canada and PMRA environmental fate assessments are accelerating refrigerant transition timelines beyond baseline Montreal Protocol schedules. A2L mildly flammable formulations are displacing R-410A in new equipment platforms. The Prairie provinces, with their extended heating seasons and higher charge sizes, face the most complex field conversion logistics.
Residential retrofit buyers are consolidating purchase decisions around EnerGuide label tiers rather than contractor recommendations alone. Ontario and British Columbia homeowners now self-direct specification toward cold-climate HSPF thresholds above ten. This certification-driven preference shift is compressing margin pools for standard-efficiency inventory in distributor channels.
Canada Outdoor Air Source Heat Pump Market Segmentation
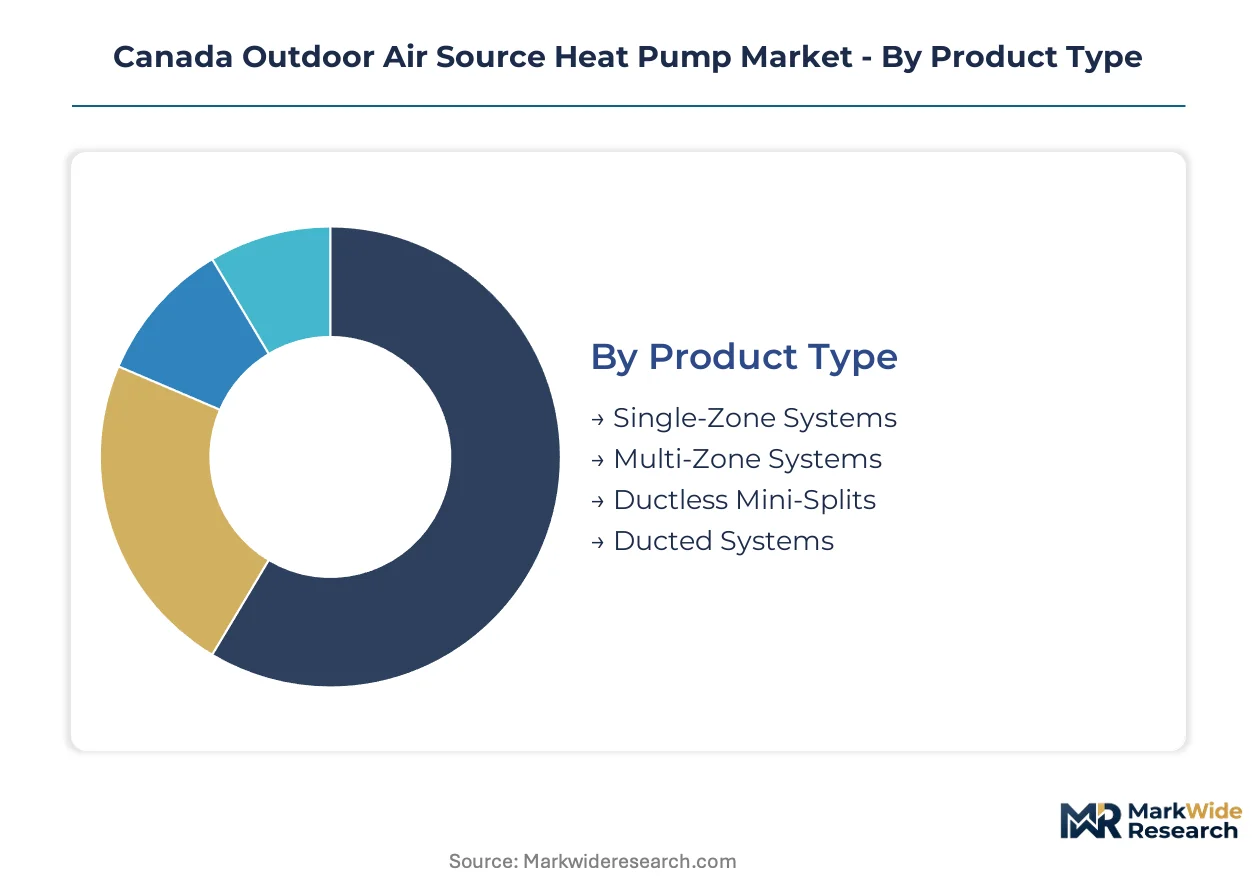
Product architecture in the Canada outdoor air source heat pump market fragments across efficiency tiers and distribution compatibility requirements. Each segment commands distinct channel relationships and margin structures that reshape procurement patterns across provincial incentive programs.
Product Type:
Distributor inventory concentrates on systems aligned with British Columbia and Quebec building code trajectories, where electrification mandates accelerate specification velocity.
- Ductless Mini-Splits:Wall-mounted and ceiling-cassette configurations deliver zoned heating without ductwork retrofit. Residential retrofits in Ontario and British Columbia drive volume where existing hydronic distribution blocks ducted alternatives. Natural Resources Canada EnerGuide tier advancement pulls specification toward cold-climate HSPF-above-ten variants.
- Multi-Zone Systems:Single outdoor units connect multiple indoor heads for whole-home electrification. New construction channels in Vancouver and Montreal metropolitan corridors specify these for builder-grade compliance with provincial heat-ready mandates. AHRI Certified efficiency verification separates premium from standard inventory in distributor warehouses.
- Single-Zone Systems:Compact units serve additions and secondary heating loads where full-system replacement is uneconomical.
- Ducted Systems:Central forced-air replacements dominate Prairie province retrofits with existing furnace infrastructure.
Ductless mini-splits dominate installed base. Multi-zone systems are where expansion concentrates.
End User:
Customer-type segmentation tracks building code stringency and incentive eligibility across Natural Resources Canada and provincial programs.
- Residential:Single-family and multi-family dwellings seeking Greener Homes Grant eligibility. Retrofit demand concentrates in Greater Toronto Area and Vancouver corridors where carbon pricing escalation compresses payback periods. Homeowners self-direct specification toward Energy Star and AHRI Certified tiers.
- Commercial:Retail, office, and hospitality buildings under CleanBC and provincial electrification mandates. British Columbia and Quebec commercial rate structures favor heat pump displacement of natural gas boilers in buildings under 50,000 square feet.
- Industrial:Light manufacturing and warehouse facilities with process heating loads.
- Government:Federal and provincial building retrofits under carbon-neutral procurement directives.
Residential channels absorb the highest unit volumes. Commercial applications are climbing the fastest as building code amendments tighten.
Installation Type:
Project delivery mode determines contractor certification requirements and utility interconnection sequencing.
- Retrofit:Replacement of aging fossil fuel systems in existing buildings. Ontario and British Columbia dominate where Greener Homes Grant stacking with provincial rebates accelerates decision timelines. Legacy hydronic distribution in Quebec creates technical friction for ductless integration.
- New Construction:Pre-wired electrification in residential builds across British Columbia and Quebec code jurisdictions. Builders specify heat-ready infrastructure as standard practice to avoid future retrofit costs.
- Modular:Prefabricated mechanical penthouses for multi-unit residential.
- Integrated:Factory-integrated HVAC packages in off-site construction.
Retrofit channels command current revenue concentration. New construction is gaining share fastest as provincial mandates harden.
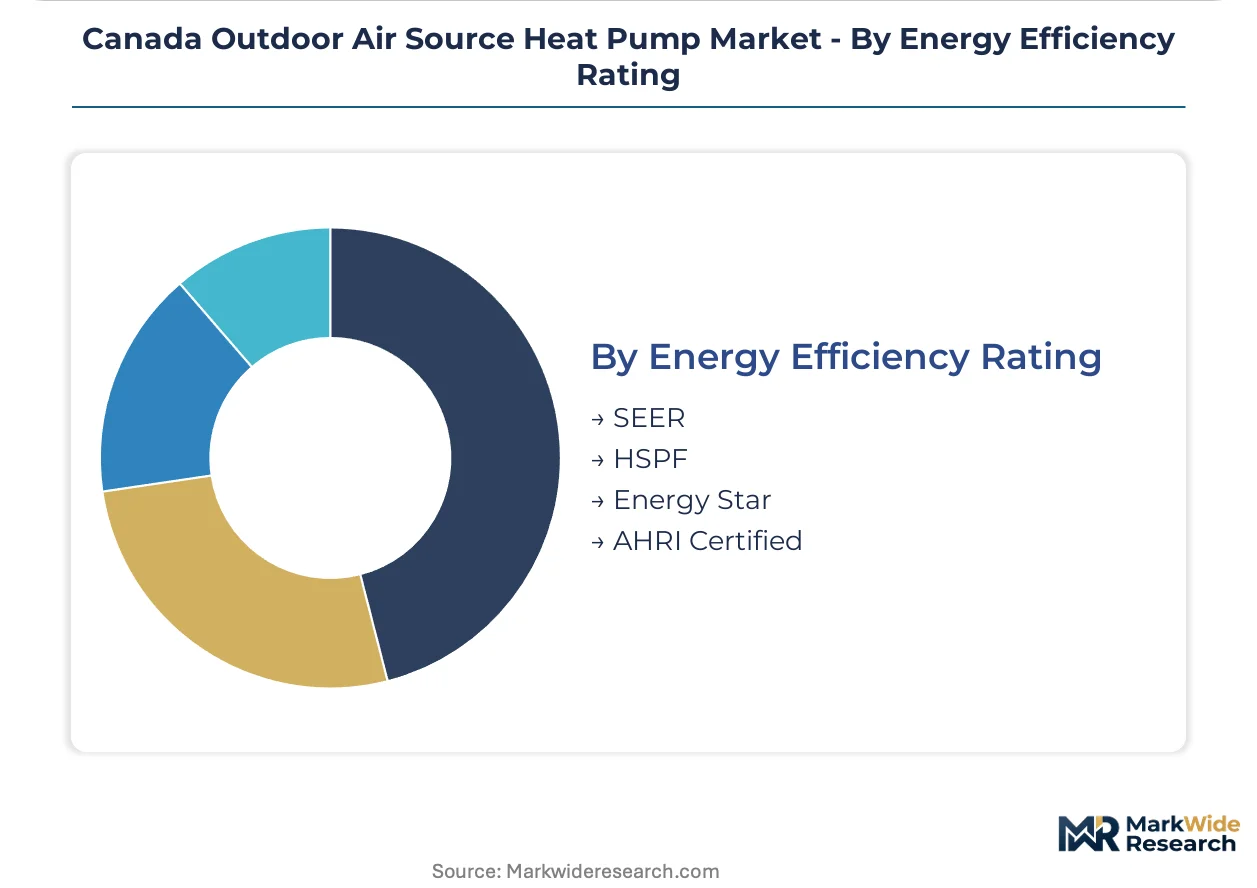
Energy Efficiency Rating:
Certification tier stratifies pricing and channel access across Natural Resources Canada verification programs.
- Cold-Climate HSPF:Heating Seasonal Performance Factor ratings above ten for sub-zero operation. Prairie province demand centers on this tier where extended heating seasons amplify operating cost differentials. Health Canada refrigerant transition timelines compress product development windows for this category.
- Energy Star:Federal efficiency verification required for Greener Homes Grant eligibility. Ontario and British Columbia distributors prioritize stocking this tier to maintain incentive program access.
- SEER:Seasonal Energy Efficiency Ratio for cooling-dominated applications.
- AHRI Certified:Independent performance verification for commercial specification.
Cold-climate HSPF dominates premium positioning. Energy Star certification is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's outdoor air source heat pump trade flows remain domestically oriented, with limited import dependence on compressor technology and inverter components from Japan and South Korea. Provincial regulatory divergence creates distinct sub-national markets rather than a unified national landscape.
Ontario
Greater Toronto Area builders are pre-wiring new residential construction for full electrification under amended building codes. Natural Resources Canada's Greener Homes Grant stacks with provincial incentives to compress retrofit payback periods. Ottawa and Hamilton corridor distributors report inventory concentration on Energy Star-certified cold-climate tiers.
British Columbia
CleanBC electrification rebates and favorable utility rate structures accelerate natural gas furnace replacement cycles in Vancouver metropolitan corridor. Vancouver and Victoria municipal heat-ready mandates pull specification toward multi-zone systems for new construction. Provincial building code amendments effectively mandate pre-wired electrification infrastructure.
Quebec
Montreal metropolitan corridor builders specify whole-home electrification as standard practice to avoid future retrofit costs. Existing hydronic radiant floor distribution in older housing stock creates technical friction for ductless mini-split integration. Quebec provincial regulators enforce building code amendments that align with federal carbon pricing trajectories.
Alberta
Calgary and Edmonton residential markets show emerging traction for cold-climate HSPF-above-ten products as carbon pricing escalation reshapes operating economics. Prairie province electricity rate structures favor extended heating season deployment. Distributor channels prioritize AHRI Certified inventory to maintain specification access in commercial segments.
Atlantic Canada
Newfoundland and Labrador face certified installer density constraints that limit demand acceleration despite hyper-heating inverter availability. Halifax and Moncton corridors specify sub-zero capacity maintenance at minus twenty-five degrees Celsius. Atlantic Canada contractor scarcity represents the primary bottleneck to market expansion.
Canada Outdoor Air Source Heat Pump Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive compressor technology and cold-climate R&D infrastructure. Assembly-dependent competitors face margin compression from copper and rare earth input volatility. Two strategic archetypes dominate: vertically integrated global HVAC conglomerates with proprietary inverter platforms, and regional distributors leveraging localized service networks. Competitive moves center on provincial certification stacking and utility partnership formation.
Within the integrated manufacturer tier, Carrier and Daikin Industries Ltd. exemplify archetypes anchored by captive technology control. Mitsubishi Electric Corporation occupies a position representing hyper-heating specialization for sub-zero climates. These three entities anchor competitive positioning across Ontario, Quebec, and British Columbia specification channels where cold-climate performance thresholds determine procurement outcomes.
| Leading Market Players |
|---|
| Carrier |
| Daikin Industries Ltd. |
| Ingersoll-Rand Plc (Trane) |
| Robert Bosch GmbH |
| Danfoss |
| Mitsubishi Electric Corporation |
| Panasonic Holdings Corporation |
| LG Electronics, Inc. |
| Rheem Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between integrated compressor manufacturers and Ontario distributor networks lock in supply access while anchoring price visibility for cold-climate HSPF-above-ten inventory. These contracts insulate premium product tiers from copper and rare earth volatility that compresses assembly-dependent margins.
Pricing Analysis
Residential retrofit buyers anchor three-tier pricing stratification across premium cold-climate HSPF, standard Energy Star, and economy SEER tiers. Price differentiation rests on AHRI certification grade and after-sales service bundling. Cost compression in standard-efficiency tiers intensifies because distributor inventory stacking favors certified variants. Commercial specification channels exhibit least price sensitivity due to building code compliance mandates.
Supply Chain Analysis
Strategic stockpile preferences dominate among Canadian distributors buffering against compressor lead time variability from Japan and South Korea. Manufacturing concentration in these countries feeds inverter component dependencies. Single-source vulnerability in rare earth motor laminations poses structural risk. Distribution runs through provincial HVAC wholesaler networks with localized service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between cold-climate heat pump platforms and utility demand-response systems is creating platform-economics inflection, rewarding ecosystem orchestrators over point-product vendors.
For Market Incumbents: Fortify captive compressor technology control through backward integration into rare earth motor lamination supply. Expand cold-climate R&D infrastructure in Quebec to preempt regulatory efficiency tier advancement. Channel control through certified installer network density defends against emerging regional distributors. For New Entrants and Emerging Players: Contractor certification gaps in Newfoundland and Labrador represent service-layer underinvestment by integrated manufacturers. Prairie province whitespace for HSPF-above-ten products offers penetrable geography. Partnership with provincial utility demand-response programs provides differentiated go-to-market positioning. For Investors and Strategic Acquirers: Regional distributors with localized service networks and AHRI Certified inventory access present acquisition target archetype with consolidation upside. Long-term viability hinges on federal carbon pricing trajectory and provincial building code stringency alignment. Watch Natural Resources Canada refrigerant transition timeline acceleration as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Climate R&D Expansion | Carrier and Daikin anchor premium positioning through sub-zero performance validation. |
| Certified Installer Network Buildout | Atlantic Canada contractor density constraints create first-mover advantage for training investment. |
| Utility Partnership Formation | CleanBC and Ontario utility rate structures favor demand-response-integrated product specification. |
| Backward Integration into Components | Captive compressor technology insulates margins from copper and rare earth price volatility. |
| Multi-Zone New Construction Specification | Vancouver and Montreal builder channels drive fastest-expanding product category adoption. |
Research Methodology
Operator-level perspectives from HVAC contractor network heads, provincial distributor inventory managers, Natural Resources Canada program administrators, and building code compliance officers anchored the qualitative base. Secondary validation drew from Natural Resources Canada EnerGuide databases, provincial utility rebate program disclosures, AHRI certification registries, and Health Canada environmental fate assessment filings. Bottom-up installation volume estimates and top-down equipment shipment data were triangulated.
Sensitivity analysis across the projection horizon tested variable-speed compressor adoption rates, federal carbon pricing escalation trajectories, and provincial building code amendment timing. Segmentation dimensions modeled include product architecture, end-user category, installation type, and energy efficiency certification tier. CAGRs were derived from equipment shipment trend extrapolation and incentive program budget allocation patterns.
Forecasts assume regulatory continuity in federal Greener Homes Grant administration and provincial CleanBC incentive structures; material policy shifts would require re-modeling. Commodity price volatility in copper and rare earth inputs, alongside Health Canada refrigerant transition timeline acceleration, represent specific revision triggers. Revision becomes warranted when utility interconnection backlog duration crosses six-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market