
 Global Variable Refrigerant Flow (VRF) Market | 2026-2036
Global Variable Refrigerant Flow (VRF) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Variable Refrigerant Flow (VRF) Market Foresight
Certified HVAC technician shortages across major installation markets is redrawing competitive dynamics for equipment suppliers. Daikin leverages its captive training academy network to secure qualified installer pipelines in priority markets. Mitsubishi Electric anchors its position through deep backward integration into inverter compressor manufacturing. Carrier competes by dominating specification-grade projects across North American hospitality and healthcare verticals.
Variable Refrigerant Flow systems modulate refrigerant volume to multiple indoor evaporator units from a single outdoor condensing unit, operating with capacities from 6 to 48 tons and utilizing inverter-driven scroll or rotary compressors to match real-time thermal loads. Heat recovery configurations command premium positioning by enabling simultaneous heating and cooling across building zones, while heat pump variants dominate volume in temperate climate installations. Electronic expansion valve technology sustains margin pools through precision superheat control and diagnostic integration.
EPA SNAP program restrictions on high-GWP refrigerants, EU F-Gas Regulation phase-down schedules, and Japan's METI energy efficiency standards collectively force refrigerant chemistry transitions and compressor redesign cycles. China's GB energy efficiency standards and India's BIS cooling performance ratings further fragment certification requirements across manufacturing footprints. Stakeholders must monitor refrigerant patent cliffs and regional service infrastructure readiness before committing to next-generation platform investments.
Market Dynamics
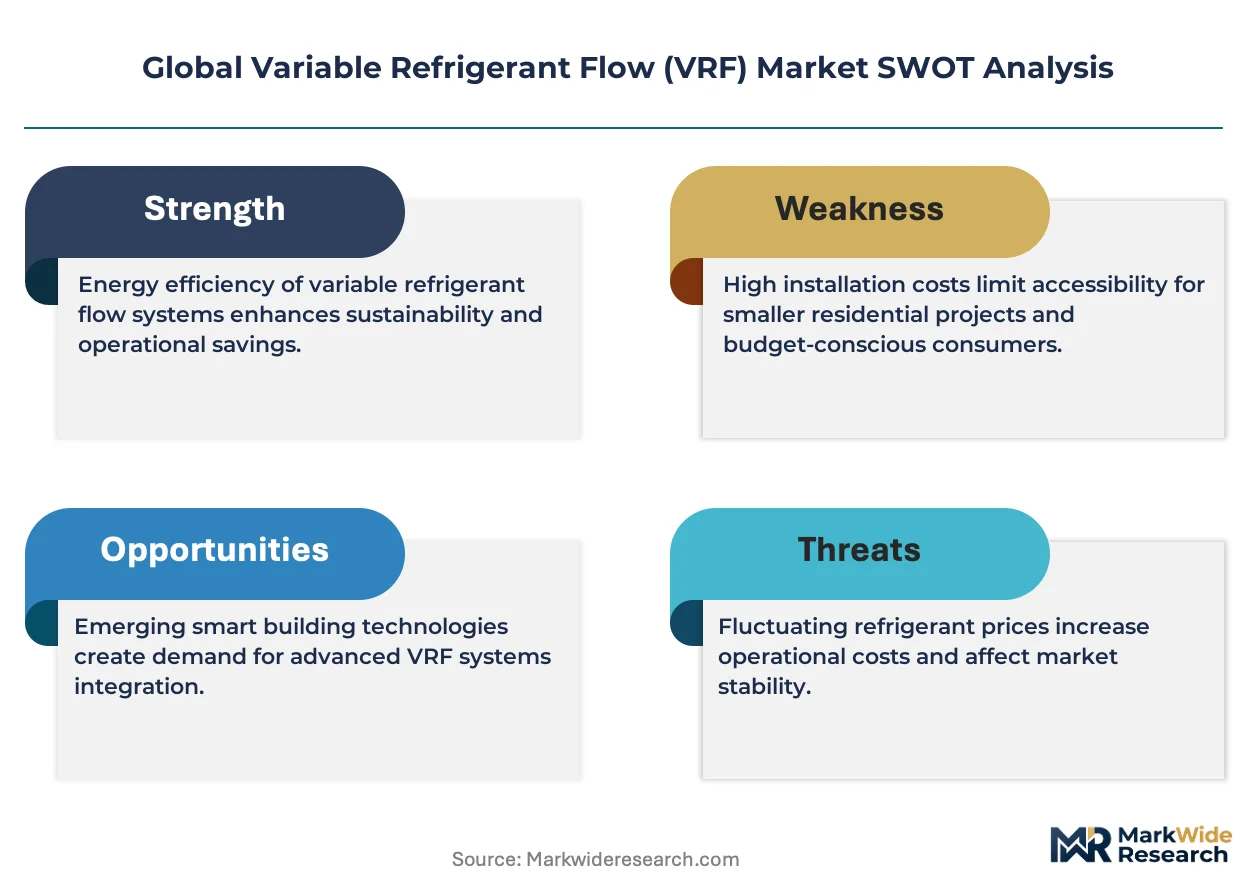
The refrigerant chemistry transition forced by the EU F-Gas Regulation and parallel EPA SNAP restrictions is compressing product development cycles while fragmenting regional certification requirements across manufacturing footprints.
Growth Catalysts
- Heat Recovery Configurations:Simultaneous heating and cooling capabilities unlock premium positioning in mixed-use commercial developments across Southeast Asia's tightening building energy codes.
- China's Tier-One Urban Retrofit Mandates:Replacement demand concentrates in Shanghai, Beijing, and Shenzhen where existing HVAC infrastructure ages out under mandatory efficiency upgrades.
- Electronic Expansion Valve Integration:Precision superheat control enables diagnostic-linked service revenue streams that sustain margin pools beyond equipment sales.
Market Restraints
- Copper and Rare Earth Input Volatility:Inverter compressor manufacturing depends on concentrated rare earth processing in China, exposing cost structures to supply disruptions and export quota shifts.
- Refrigerant Patent Cliffs:Next-generation low-GWP chemistries face intellectual property thickets that delay platform standardization and inflate licensing costs for second-tier manufacturers.
- Certified Installer Scarcity:The gap between VRF system complexity and qualified HVAC technician supply constrains deployment velocity in North American and European priority markets.
Strategic Opportunities
- India's BIS Cooling Performance Ratings:New mandatory efficiency disclosure rules create first-mover advantage for suppliers with pre-certified product portfolios in a historically underpenetrated market.
- Healthcare and Data Center Verticals:Precise zonal temperature control requirements in pharmaceutical manufacturing and server farms drive specification-grade procurement with extended service attach rates.
- Refrigerant-as-a-Service Models:Leased refrigerant and predictive maintenance bundles address customer capital constraints while locking in long-term supplier relationships through embedded IoT diagnostics.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Japan's METI energy efficiency standards, China's GB codes, and India's BIS ratings operate on non-harmonized testing protocols that duplicate validation costs.
- Legacy Building Integration Complexity:Retrofit installations in existing commercial structures require structural modifications and electrical upgrades that extend project timelines and erode contractor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Variable Refrigerant Flow (VRF) Market |
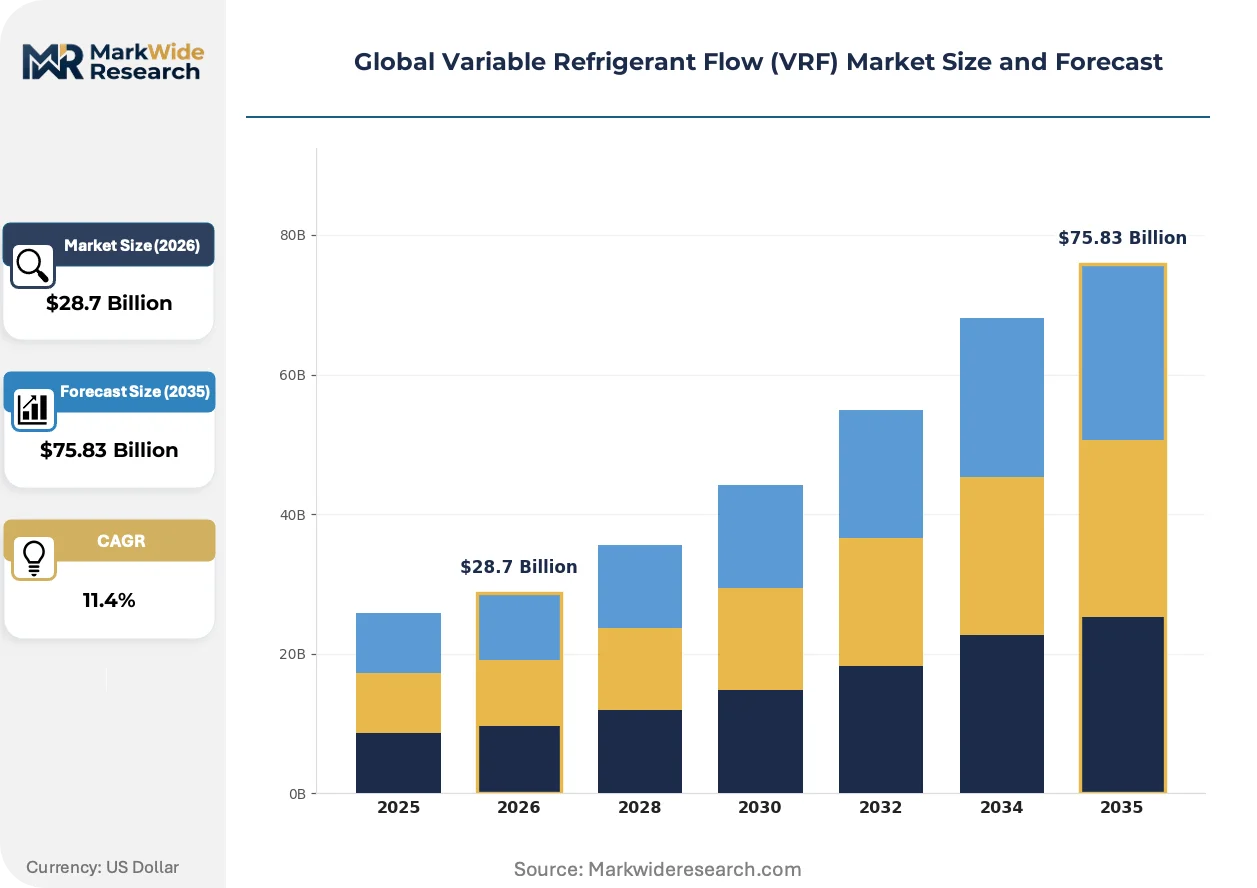
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Heat Recovery, Heat Pump, Cooling Only, Dual Cool Technology: Inverter, Scroll Compressor, Microchannel, Electronic Expansion Valve Application: Commercial Complexes, Data Centers, Educational Institutions, Hospitality Centers End User: Office Facilities, Retail Enterprises, Leisure Facilities, Government Buildings |
| Companies Covered | Midea, Johnson Controls, Daikin, Gree, LG Electronics, Mitsubishi Electric, Carrier, Samsung Electronics, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Variable Refrigerant Flow (VRF) Market Shifts & Advancements
Refrigerant technology trajectories and procurement model evolution are compressing traditional equipment sales cycles while opening service-based revenue architectures. The intersection of regulatory phase-downs and digital diagnostics is redefining competitive differentiation.
Low-GWP refrigerant blends are fragmenting platform standardization as manufacturers pursue divergent chemistry pathways to meet EU F-Gas and EPA SNAP requirements. Commercial developers in Germany and France face accelerated replacement timelines as HFC availability contracts. The technology is fragmenting vendor interoperability and inflating service infrastructure investments across incompatible refrigerant families.
Japan's METI energy efficiency standards are forcing compressor redesign cycles that prioritize part-load performance over peak capacity ratings. Equipment suppliers must retest entire product portfolios under new seasonal efficiency metrics. Heat pump variants targeting temperate climate installations face the steepest compliance cost increases as testing protocols expand to capture real-world operating conditions.
Building owners are unbundling equipment procurement from long-term service contracts, reversing the traditional bundled-sale model. Third-party facility management firms in Singapore and Dubai now specify open-protocol systems that enable multi-vendor maintenance competition. This shift concentrates purchasing power among large real estate investment trusts while pressuring OEM margins on initial equipment sales.
Global Variable Refrigerant Flow (VRF) Market Segmentation
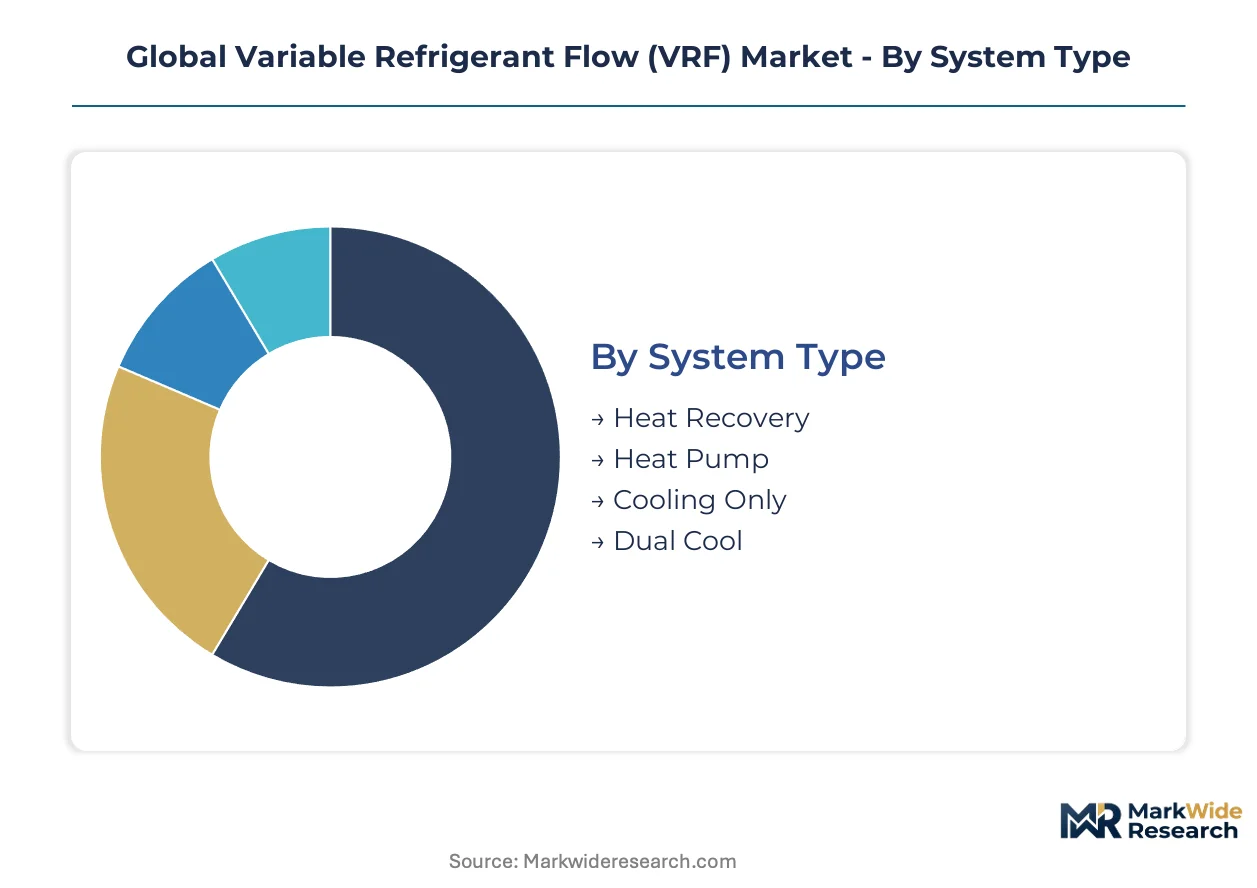
VRF system configurations fragment procurement channels across specification-grade projects, volume-driven retail, and service-integrated retrofit contracts. Technology and application segments align with distinct customer risk appetites and regulatory compliance burdens.
System Type:
Heat recovery and heat pump configurations dominate specification channels for mixed-use developments, while cooling-only variants flow through distributor networks serving price-sensitive replacement demand.
- Heat Recovery:Simultaneous heating and cooling across building zones requires three-pipe refrigerant architecture and sophisticated control systems. Demand concentrates in Singapore and Dubai commercial towers where building energy codes mandate zonal efficiency. Premium positioning sustains margins through extended service attach rates.
- Heat Pump:Reversible refrigeration cycle delivers both heating and cooling through simplified two-pipe infrastructure. China's tier-one cities drive replacement volume as GB energy efficiency standards force aging system retirements. Temperate climate installations favor this configuration for operational simplicity.
- Cooling Only:Single-mode operation suits tropical markets with minimal heating requirements. Southeast Asian retail and hospitality sectors specify these systems for lower capital outlay.
- Dual Cool:Hybrid architecture combines VRF with dedicated outdoor air systems for specialized ventilation loads. Pharmaceutical manufacturing and healthcare facilities in Germany and Japan require this configuration for contamination control.
By volume, heat pump configurations lead. By growth pace, heat recovery systems are expanding most quickly.
Technology:
Component technology tiers separate premium specification-grade procurement from standard commercial installations, with inverter and electronic expansion valve systems commanding higher initial margins.
- Inverter:Variable-frequency drive modulates compressor speed to match thermal loads rather than cycling on-off. Japan's METI seasonal efficiency standards favor this technology for part-load performance optimization. Mitsubishi Electric's captive compressor manufacturing secures supply chain control.
- Electronic Expansion Valve:Precision superheat control enables real-time diagnostic feedback and predictive maintenance integration. Data center operators in Northern Virginia and Frankfurt specify this technology for uptime-critical applications. IoT-enabled service bundles extend revenue streams beyond equipment sale.
- Scroll Compressor:Orbiting scroll design delivers reliable compression for mid-capacity commercial applications. Standard office and retail installations specify this proven technology.
- Microchannel:Flat tube aluminum construction reduces refrigerant charge and coil weight. Weight-constrained high-rise retrofits in Manhattan and London favor this compact heat exchanger technology.
Inverter technology holds volume leadership. Electronic expansion valve integration is gaining share fastest through service-contract bundling.
Application:
End-use verticals concentrate demand in distinct geographic clusters, with specification intensity varying by operational criticality and regulatory exposure.
- Commercial Complexes:Mixed-use developments across Shanghai, Beijing, and Shenzhen retrofit under mandatory efficiency mandates. Heat recovery configurations dominate new construction.
- Data Centers:Precise zonal temperature control protects server infrastructure. Northern Virginia, Frankfurt, and Singapore host concentrated procurement with 24/7 operational requirements.
- Educational Institutions:Seasonal occupancy patterns favor heat pump flexibility. Public sector procurement in Japan and South Korea emphasizes lifecycle cost over initial capital.
- Hospitality Centers:Guest comfort requirements drive simultaneous heating and cooling demand. Dubai and Bangkok luxury developments specify premium heat recovery systems.
Commercial complexes lead by installed base. Data center applications are climbing the fastest on digital infrastructure expansion.
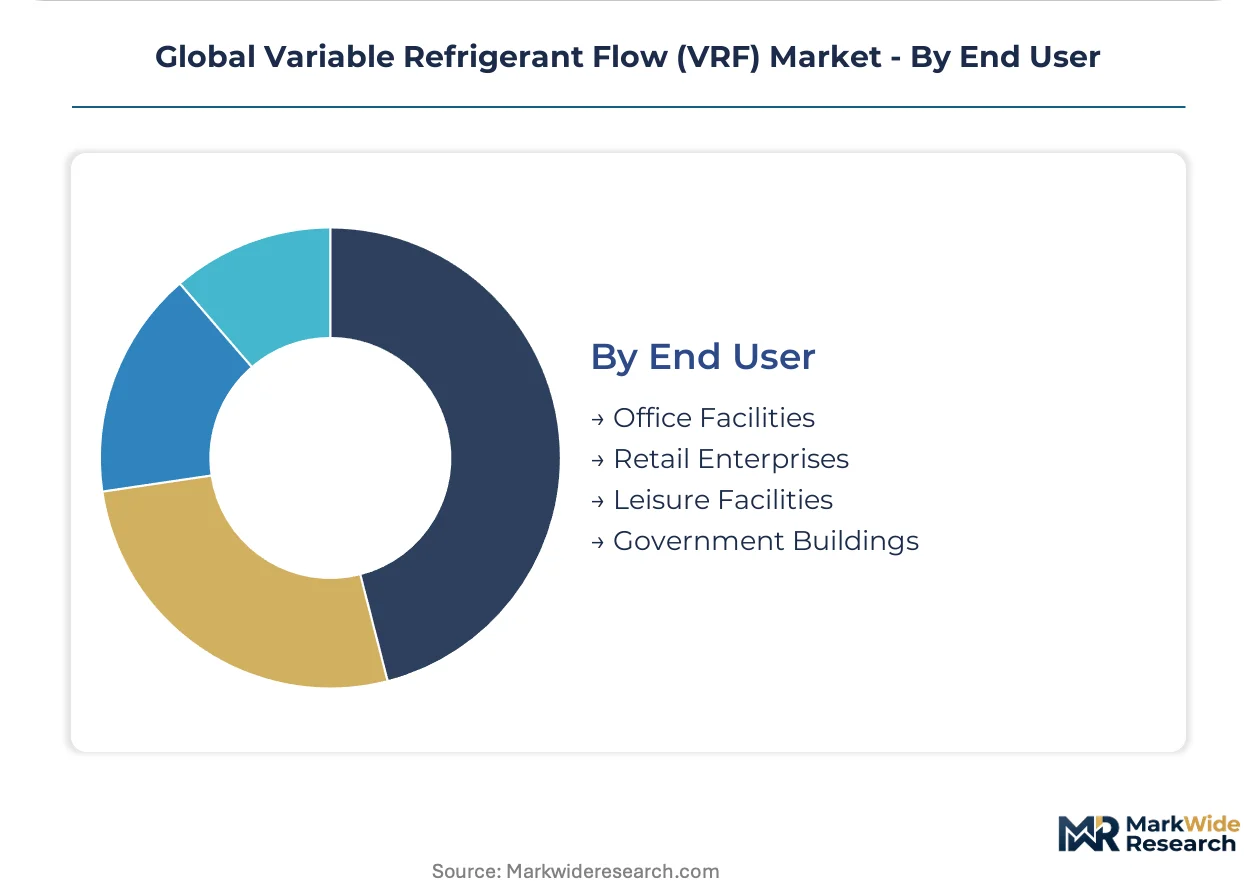
End User:
Customer type determines procurement channel access and service contract structure, with facility scale dictating specification influence.
- Office Facilities:Corporate real estate portfolios in London and New York standardize on open-protocol systems for multi-vendor maintenance competition. Third-party facility managers concentrate purchasing power.
- Retail Enterprises:Franchise networks and big-box operators prioritize capital efficiency and rapid deployment. Volume procurement through distributor channels dominates.
- Leisure Facilities:Gyms, cinemas, and entertainment venues require rapid load response for occupancy fluctuations. Southeast Asian markets show concentrated demand.
- Government Buildings:Public procurement mandates energy efficiency certifications and domestic content requirements. India's Central Public Works Department and Japan's government building standards create compliance-driven demand.
Office facilities represent the largest installed base. Government building retrofits are expanding most quickly on fiscal stimulus and efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT energy efficiency standards anchor the dominant geography, with GB code revisions forcing replacement cycles across tier-one urban clusters. The EU F-Gas Regulation and EPA SNAP restrictions in the United States create parallel compliance pressures that fragment regional product portfolios.
China
Shanghai, Beijing, and Shenzhen retrofit mandates concentrate replacement demand as aging HVAC infrastructure ages out under mandatory efficiency upgrades. MIIT's seasonal performance metrics force compressor redesigns prioritizing part-load operation. Yangtze River Delta manufacturing clusters supply inverter components to domestic and export markets.
United States
Data center operators in Northern Virginia and hospitality developers across Florida drive specification-grade procurement with 24/7 uptime requirements. EPA SNAP program restrictions on high-GWP refrigerants compress product development timelines. Southwest commercial construction clusters favor heat pump configurations for temperate climate operation.
Germany
Commercial developers in Frankfurt and Munich face accelerated replacement timelines as EU F-Gas Regulation phase-downs contract HFC availability. REACH compliance requirements add certification layers for refrigerant handling infrastructure. Bavarian industrial zones host concentrated heat recovery installations in mixed-use pharmaceutical facilities.
Japan
METI energy efficiency standards force seasonal efficiency testing protocols that favor inverter technology for part-load optimization. Kanto region building retrofits emphasize lifecycle cost over initial capital outlay. Osaka-based manufacturing maintains captive compressor production for supply chain control.
India
BIS cooling performance ratings create first-mover advantage for pre-certified suppliers entering this historically underpenetrated market. Delhi-NCR government building retrofits expand on fiscal stimulus and efficiency mandates. Maharashtra commercial complexes adopt heat pump systems as urban energy codes tighten.
Global Variable Refrigerant Flow (VRF) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive manufacturing and training infrastructure separating premium positioning from price-driven volume plays. The structure rewards backward integration into compressor production and installer certification networks. Three archetypes dominate: full-stack integrated manufacturers with captive component supply, specification-grade project specialists targeting healthcare and data center verticals, and volume-oriented fabricants serving retail and distributor channels. Competitive moves concentrate on training academy expansion to secure qualified installer pipelines and refrigerant platform transitions to meet EU F-Gas and EPA SNAP compliance deadlines.
Among Asia-Pacific integrated manufacturers, Daikin, Midea, and Mitsubishi Electric exemplify distinct strategic positions. Daikin occupies a position emphasizing captive training infrastructure deployment. Midea represents scale-driven volume fabrication with broad distributor channel penetration. Mitsubishi Electric anchors the premium tier through in-house compressor manufacturing control. These three demonstrate how geographic origin and structural integration choices map to divergent competitive vectors within the same regulatory environment.
| Leading Market Players |
|---|
| Midea |
| Johnson Controls |
| Daikin |
| Gree |
| LG Electronics |
| Mitsubishi Electric |
| Carrier |
| Samsung Electronics |
| Hitachi |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day compressor lead times from Yangtze River Delta manufacturing clusters concentrate pricing power among inverter suppliers with captive production. This inventory band forces project contractors to absorb cost volatility or extend bid validity windows, tightening margins on fixed-price commercial installations across North American and European procurement channels.
Pricing Analysis
Price spreads between German and Indian project quotes reach three-to-one multiples for equivalent heat recovery tonnage, reflecting certification burden differentials under EU F-Gas versus BIS efficiency regimes. Three-tier pricing structure across specification-grade, standard commercial, and distributor-channel economy levels separates projects with METI seasonal efficiency compliance from basic cooling-only replacements. Pricing pressure stems from rare earth export quota volatility feeding into inverter compressor cost structures. Retail franchise networks exhibit highest price sensitivity, while data center operators prioritize uptime guarantees over capital outlay.
Supply Chain Analysis
Strategic stockpiling of copper tube and rare earth magnets characterizes procurement behavior among Japanese and Korean OEMs, contrasting with just-in-time refrigerant inventory management prevalent in European distributor networks. Manufacturing gravity centers on China, Japan, and South Korea for compressor and inverter component supply. Raw material dependencies span copper concentrate, neodymium-dysprosium rare earth blends, and aluminum microchannel coil stock. Single-source vulnerability concentrates in Chinese rare earth processing infrastructure. Distribution runs through authorized dealer networks for specification-grade projects and open wholesale channels for replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent VRF suppliers face substitution pressure from magnetic-bearing chiller technology in data center and healthcare precision-cooling applications, requiring defensive positioning around service-integrated revenue architectures.
For Market Incumbents: Fortify captive installer training academy networks to secure qualified technician pipelines against certified HVAC labor scarcity in North American and European priority markets. Deepen backward integration into electronic expansion valve and inverter compressor manufacturing to insulate margin structures from rare earth supply disruption. Prioritize refrigerant platform transitions ahead of EU F-Gas phase-down deadlines to avoid stranded inventory positions. For New Entrants and Emerging Players: India's BIS cooling performance rating fast-track offers regulatory arbitrage for pre-certified product portfolios entering a historically underpenetrated market with concentrated government building retrofit demand. Target Maharashtra commercial complex heat pump specifications where urban energy code tightening outpaces incumbent certification refresh cycles. Pursue third-party facility management partnership channels in Singapore and Dubai open-protocol procurement environments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized HVAC divisions lacking scale in inverter compressor technology or refrigerant service infrastructure. Long-term viability hinges on supplier positioning within low-GWP refrigerant patent estates and IoT-enabled predictive maintenance platform deployment. Monitor EU F-Gas quota auction price trajectories as inflection indicator for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Training Academy Network Expansion | Secures qualified installer pipelines against certified technician scarcity constraining deployment velocity. |
| Refrigerant-as-a-Service Model Launch | Locks in long-term customer relationships through embedded IoT diagnostics and leased chemistry bundles. |
| Inverter Compressor Manufacturing Scale-Up | Captures supply chain control and insulates margin structures from rare earth export quota volatility. |
| Open-Protocol System Certification | Enables multi-vendor maintenance competition preferred by third-party facility management procurement. |
| Low-GWP Refrigerant Platform Transition | Ensures EU F-Gas and EPA SNAP compliance ahead of phasedown deadlines contracting HFC availability. |
Research Methodology
A spread of perspectives from HVAC contractor operations managers, commercial real estate development executives, refrigerant supply specialists, and inverter component procurement leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, EPA SNAP regulatory filings, EU F-Gas quota registry disclosures, and MIIT seasonal efficiency certification databases. Bottom-up project pipeline tracking across Shanghai, Frankfurt, and Northern Virginia development clusters triangulated against top-down equipment shipment analysis.
Segmentation dimensions modeled span system type configuration, compressor technology tier, electronic expansion valve integration level, end-use vertical application, and customer facility scale across the projection horizon. CAGRs derive from unit shipment trajectories by configuration, applied to average selling price bands adjusted for refrigerant chemistry transition cost pass-through. Forecast inputs incorporate GB energy efficiency standard revision timelines, METI seasonal performance testing protocol changes, and BIS cooling performance rating implementation schedules.
Underlying assumptions cover refrigerant patent cliff resolution timelines and rare earth supply quota stability, with deviation risk concentrated in multi-jurisdiction certification harmonization delays and installer training throughput bottlenecks. Revision becomes warranted when EU F-Gas auction price volatility crosses thresholds triggering accelerated commercial replacement pull-forward demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Compressor Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Industrial Boiler Market