
 Qatar Residential Construction Market | 2026-2036
Qatar Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Residential Construction Market Outlook
Buyer concentration among luxury homebuyers and institutional investors is decoupling from traditional first-time buyer segments as Qatar's population shifts toward high-income expatriates. Galfar Al Misnad Engineering & Contracting leverages its vertically integrated project delivery to dominate premium residential developments in Doha. Hamad Bin Khalid Contracting sustains market presence through specialized infrastructure tie-ins that anchor large-scale community builds. Porr Construction Qatar differentiates via European-engineered modular systems that reduce on-site labor dependency.
Qatar residential construction encompasses the planning, design, and assembly of dwellings using reinforced concrete frames, structural steel systems, and high-performance glazing specified for desert thermal conditions, serving housing needs across income tiers. Concrete and steel remain the dominant building materials, though green building methods are gaining share as GSAS certification becomes a threshold requirement for government-linked projects. Single-family homes retain the largest project type share, while luxury condominiums capture disproportionate margin pools in West Bay and the Pearl.
Qatar's Ministry of Municipality and Environment enforces building permits and zoning compliance, while the Qatar General Organization for Standard and Metrology mandates material testing protocols that align with Gulf standardization requirements. The Global Sustainability Assessment System operates as the de facto green building regulator, restricting market access for developers who fail to meet minimum energy performance thresholds. Stakeholders must monitor how evolving cooling-load regulations and water-efficiency standards reshape material procurement and construction method selection.
Market Dynamics
Qatar's residential construction sector is undergoing structural compression as GSAS certification mandates from the Global Sustainability Assessment System force simultaneous upgrades to thermal envelope specifications and cooling-load calculations across all government-linked developments.
Growth Catalysts
- GSAS Certification Mandates:Government-linked projects now require minimum energy performance thresholds, redirecting procurement toward high-performance glazing and insulated concrete systems.
- Expatriate Professional Inflows:Doha and Lusail absorb sustained demand for multi-family units from high-income foreign workers and their families.
- Desert Thermal Engineering:Advanced HVAC-integrated building envelopes reduce operational cooling loads, attracting institutional capital to premium developments.
Market Restraints
- Steel and Cement Input Volatility:Regional supply concentration in Saudi and UAE producers exposes Qatar developers to freight cost swings and import duty fluctuations.
- Specialized Labor Scarcity:GSAS-accredited project managers and thermal performance engineers remain concentrated in Doha, constraining rollout speed to secondary districts.
- Water-Efficiency Compliance Friction:Qatar General Organization for Standard and Metrology testing protocols extend material approval timelines by 15-20 percent for non-standard specifications.
Strategic Opportunities
- Lusail Smart City Expansion:The northern district offers undeveloped parcels for integrated community builds with district cooling infrastructure already committed.
- Modular Construction Convergence:European-engineered prefabrication systems are merging with local concrete supply chains to compress on-site labor requirements.
- Ministry of Municipality Incentives:Expedited permitting for GSAS Gold-rated projects reduces approval cycles, rewarding early green building adopters.
Industry Challenges
- GSAS Auditor Certification Bottlenecks:The limited pool of accredited assessors creates project scheduling conflicts and delays certificate issuance.
- Legacy Concrete Supply Integration:Established ready-mix networks require capital-intensive retrofitting to deliver low-carbon formulations compliant with updated energy codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Residential Construction Market |
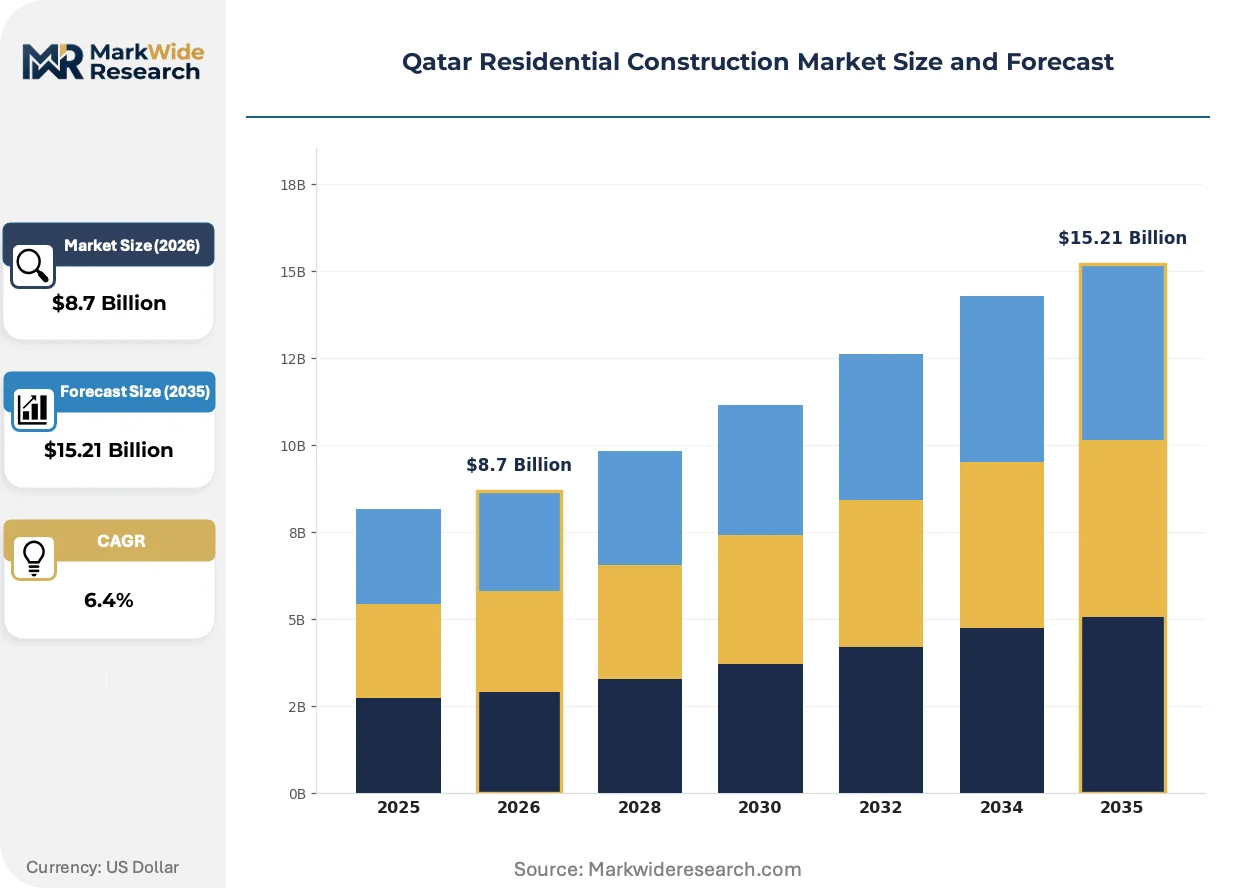
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Single-Family Homes, Multi-Family Units, Townhouses, Luxury Condominiums Building Material: Concrete, Steel, Glass, Timber Construction Method: Modular Construction, Traditional Construction, Precast Construction, Green Building End User: First-Time Buyers, Investors, Renters, Luxury Homebuyers |
| Companies Covered | Galfar Al Misnad Engineering & Contracting, Gulf Contracting Company, Hamad Bin Khalid Contracting (HBK), Contraco WLL, Al-Balagh Trading & Contracting, QD-SBG Construction, Porr Construction Qatar, Mercury MENA, Midmac Contracting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Residential Construction Market Strategic Shifts
Qatar's residential construction market is compressing project timelines through technology convergence while regulatory pressure from GSAS rewrites material specifications and procurement criteria.
Building Information Modeling is unifying thermal performance simulation, structural engineering, and GSAS compliance documentation into single-workflow platforms. Large-scale developers in the Pearl-Qatar and Msheireb Downtown districts adopt these integrated systems to eliminate design-phase revisions. The technology is unifying previously siloed disciplines, collapsing coordination cycles from months to weeks.
Qatar's Ministry of Municipality and Environment updated building energy codes now mandate pre-cooling load calculations and high-performance envelope testing for all residential permits above 10,000 square meters. These rules force developers to specify triple-glazed units and insulated concrete forms earlier in design. Luxury condominium projects in West Bay face the steepest compliance ramps, driving early engagement with GSAS consultants.
Institutional buyers now require outcome-based energy performance guarantees rather than component specifications, transferring operational risk to contractors and equipment suppliers. This procurement compression displaces traditional lump-sum bidding in premium segments. Msheireb Downtown developments demonstrate the shift most visibly, with developer-operator partnerships absorbing ten-year cooling efficiency obligations.
Qatar Residential Construction Market Segmentation
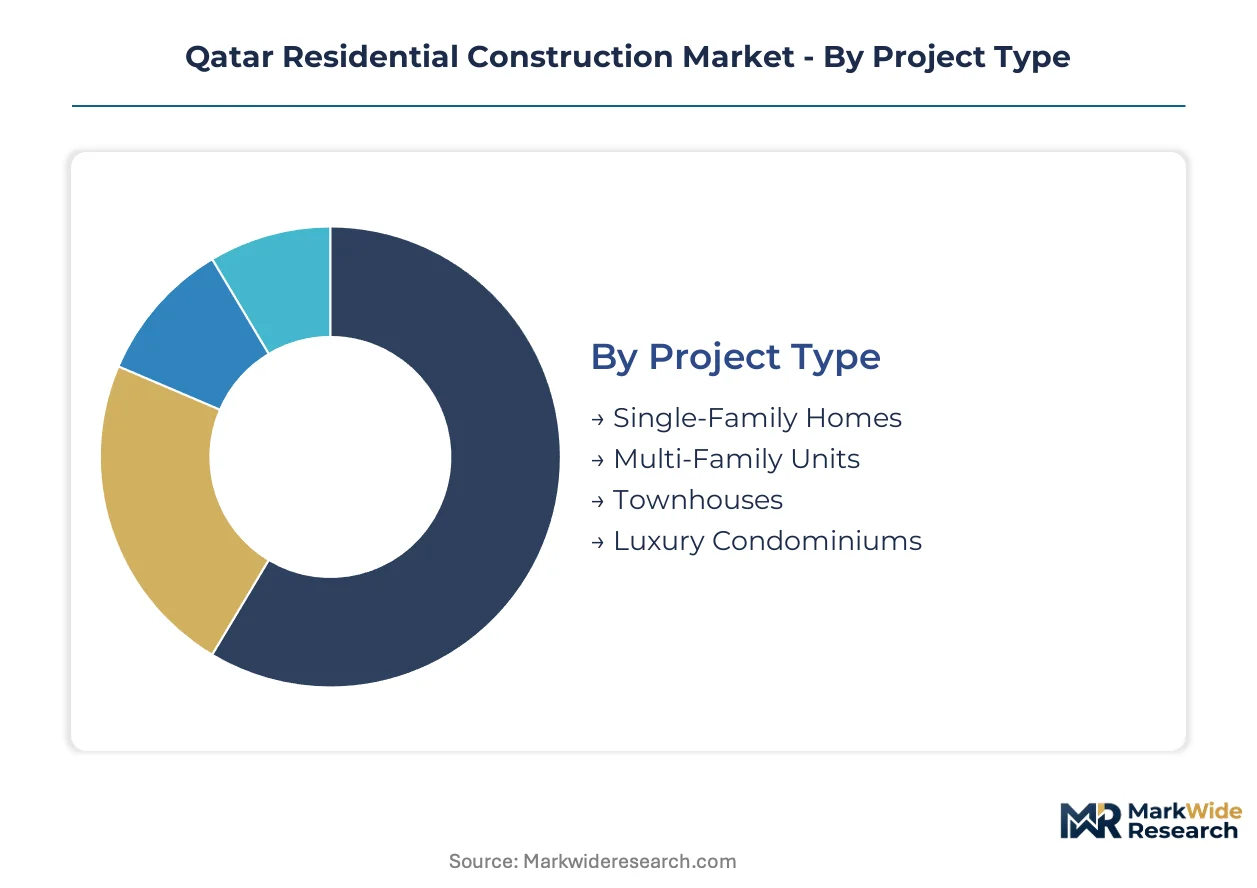
Qatar's residential construction market fragments across four critical dimensions that determine procurement patterns, regulatory compliance burdens, and margin structures. Project type and construction method selections now hinge on GSAS certification requirements, while building material choices increasingly reflect thermal performance mandates from the Ministry of Municipality and Environment.
Project Type:
Household formation patterns among expatriate professionals drive project type selection, with location and amenity expectations varying sharply across income tiers.
- Single-Family Homes:Reinforced concrete frame structures with insulated masonry walls dominate this segment, serving Qatari nationals and long-term expatriate families in Al Wakrah and Al Khor. Demand concentrates in established districts where land titles are secure and utility infrastructure is mature.
- Multi-Family Units:Mid-rise reinforced concrete structures with centralized district cooling connections absorb the bulk of Doha and Lusail demand from professional expatriates. Rental yield visibility and proximity to commercial districts attract institutional capital to this format.
- Townhouses:Hybrid construction blending concrete frames with steel stair cores serves families seeking space efficiency without villa maintenance burdens. Lusail's Marina District and Pearl-Qatar fringes concentrate new supply.
- Luxury Condominiums:High-rise towers with curtain wall glazing and integrated smart building systems command premium pricing in West Bay and Msheireb Downtown. Foreign investor quotas and branded residence concepts differentiate top-tier offerings.
Single-Family Homes leads on scale; Luxury Condominiums leads on momentum.
Building Material:
Desert thermal engineering requirements and GSAS certification thresholds now override first-cost considerations in material specification decisions.
- Concrete:Ready-mix formulations with supplementary cementitious materials and reduced thermal conductivity dominate structural frames across all project types. Qatar's local producers are retrofitting batch plants to deliver low-carbon mixes compliant with updated energy codes.
- Steel:Structural sections and reinforcing bars remain essential for high-rise cores and long-span applications, though regional supply concentration in Saudi and UAE mills exposes developers to freight cost volatility.
- Glass:Triple-glazed low-emissivity units with argon fill are becoming standard for luxury developments facing stringent cooling-load calculations. Specification timelines extend due to Qatar General Organization for Standard and Metrology testing protocols.
- Timber:Cross-laminated and glulam systems gain traction in low-rise boutique projects targeting GSAS innovation credits, constrained by fire code approval timelines and limited local fabrication capacity.
Concrete dominates on installed volume; Glass is climbing the fastest on specification intensity.
Construction Method:
Project delivery speed and labor availability constraints are compressing traditional build schedules toward prefabrication and modular alternatives.
- Modular Construction:European-engineered volumetric units merge with local concrete supply chains to reduce on-site labor dependency. Lusail Smart City parcels with district cooling infrastructure already committed attract this method for speed-to-market.
- Traditional Construction:Cast-in-place concrete with stick-built finishing trades retains share in custom villa projects where design flexibility outweighs schedule pressure. Established subcontractor networks in Doha sustain this approach.
- Precast Construction:Factory-cast wall panels and hollow-core slabs accelerate envelope closure while improving thermal consistency. Integration with GSAS-compliant insulation systems requires early design-phase coordination.
- Green Building:Holistic approaches integrating passive design, renewable energy, and water recycling are mandatory for government-linked projects. GSAS Gold and Platinum ratings unlock expedited permitting from the Ministry of Municipality.
Traditional Construction retains the largest share; Green Building is gaining share fastest on regulatory mandate.
End User:
Purchasing power dispersion and residency security shape end-user segments, with institutional buyers and high-net-worth individuals decoupling from mass-market dynamics.
- First-Time Buyers:Qatari nationals accessing subsidized land programs and mortgage guarantees drive demand for entry-level villas in Al Daayen and Umm Salal. Financing accessibility constrains effective demand more than construction cost.
- Investors:Institutional funds and family offices concentrate on income-producing multi-family assets in Doha and Lusail, requiring ten-year energy performance guarantees from developers.
- Renters:Expatriate professionals on fixed-term contracts sustain demand for furnished apartments with inclusive utility structures. Corporate leaseback arrangements dominate the Pearl-Qatar rental stock.
- Luxury Homebuyers:High-net-worth individuals from GCC states and beyond seek branded residences and penthouse inventory in Msheireb Downtown and West Bay. Customization options and concierge services differentiate offerings.
Renters represent the deepest volume pool; Luxury Homebuyers show the steepest expansion trajectory on inbound wealth migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar outpaces Kuwait in residential construction velocity despite both nations sharing comparable expatriate-driven demand profiles and Gulf Cooperation Council regulatory frameworks. The disparity stems from Qatar's concentrated infrastructure investment cycles tied to mega-event hosting and subsequent legacy repurposing. Neighboring Saudi Arabia and the UAE present alternative demand models that reshape procurement patterns across the peninsula.
Saudi Arabia
Riyadh's giga-project pipeline generates cross-border labor competition that elevates construction wages in Doha. The Saudi Building Code mandates seismic-resistant design standards that exceed Qatar's wind-load-focused regulations. Eastern Province contractors frequently bid on Qatar projects, creating equipment and skilled-trader leakage between markets.
United Arab Emirates
Dubai's saturated luxury condominium inventory redirects Gulf institutional capital toward Doha and Lusail developments. The UAE's Estidama Pearl Rating System influenced Qatar's GSAS certification architecture, creating regulatory harmonization that eases contractor mobility. Abu Dhabi-based engineering consultancies dominate thermal performance modeling for Pearl-Qatar towers.
Kuwait
Kuwait City's stalled public housing programs contrast with Qatar's accelerated permitting for private developers. The Kuwait Municipality enforces stricter setback requirements that limit density compared to Doha's vertical expansion incentives. Hawalli and Salmiya districts show nascent modular construction adoption that lags Qatar's European-system integration by approximately three years.
Bahrain
Manama's financial district conversion to residential use creates demand patterns distinct from Qatar's purpose-built new-city approach. The Bahrain Works Ministry maintains simpler energy code compliance pathways that attract developers deterred by Qatar's GSAS documentation burdens. Northern Governorate villa projects compete for Saudi weekend-home buyers who otherwise concentrate in Doha's luxury segments.
Qatar Residential Construction Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Qatar's residential construction sector, creating a tiered competitive structure where scale advantages clash with agility premiums. Qatari-owned engineering groups with state-linked heritage dominate land-bank access and municipal relationship depth. European and regional contractors occupy technology-forward niches where modular methods and sustainability credentials command price premiums. Consolidation pressure operates through joint-venture formations rather than outright acquisition, as foreign ownership restrictions preserve local partnership requirements.
Among vertically integrated Qatari operators, Galfar Al Misnad Engineering & Contracting and Hamad Bin Khalid Contracting occupy positions exemplifying the conglomerate archetype with project delivery spanning infrastructure through finishing trades. Porr Construction Qatar represents the European-engineered specialization tier, anchoring modular system deployment that reduces on-site labor intensity. These three entities collectively illustrate the market's bifurcation between scale-driven local consolidation and technology-importing international presence.
| Leading Market Players |
|---|
| Galfar Al Misnad Engineering & Contracting |
| Gulf Contracting Company |
| Hamad Bin Khalid Contracting (HBK) |
| Contraco WLL |
| Al-Balagh Trading & Contracting |
| QD-SBG Construction |
| Porr Construction Qatar |
| Mercury MENA |
| Midmac Contracting |
| Others |
Value Chain & Pricing Dynamics
GSAS certification mandates from Qatar's Global Sustainability Assessment System gate qualified supply access and premium-tier pricing power, forcing developers to absorb material cost premiums for triple-glazed envelopes and low-carbon concrete formulations. This regulatory filter bifurcates procurement pools between GSAS-accredited suppliers commanding price premiums and conventional vendors locked into government-excluded project tiers.
Pricing Analysis
Capacity additions in Saudi Arabia and the UAE are reshaping price floors for structural steel and cement, compressing margins for Qatari developers locked into long-term offtake agreements. Project-based pricing dominates, with differentiation running through GSAS certification tier and thermal performance grade. Pricing pressure intensifies in standard-tier segments as regional oversupply meets fixed import duty structures. Institutional investors show lowest price sensitivity, absorbing premium envelopes for ten-year energy guarantees, while first-time Qatari buyers accessing subsidized land programs face financing constraints that amplify cost consciousness.
Supply Chain Analysis
GSAS auditor certification bottlenecks restrict qualified supplier pools, concentrating procurement leverage among accredited concrete batchers and glazing fabricators. Structural steel draws from Saudi and UAE mills, while specialized HVAC-integrated envelope systems source from European engineering houses. Single-source vulnerability concentrates in GSAS-accredited project managers and thermal performance engineers based in Doha. Distribution runs through vertically integrated Qatari conglomerates with municipal relationship depth, supplemented by European modular system providers serving Lusail Smart City parcels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's residential construction market functions as a regulatory compounder where GSAS certification mandates from the Global Sustainability Assessment System continuously escalate material specifications and compliance thresholds, structurally advantaging early green building adopters with expedited permitting access.
For Market Incumbents: Deepen backward integration into low-carbon concrete production to capture margin pools eroding from regional steel and cement price volatility. Anchor municipal relationships through GSAS Gold-rated project pipelines that secure expedited approval cycles, insulating against emerging European modular competitors penetrating Lusail Smart City developments.
For New Entrants and Emerging Players: Launch via outcome-based energy performance contracting that transfers operational risk from institutional buyers, bypassing lump-sum bidding barriers. Target secondary districts beyond Doha where GSAS auditor scarcity constrains incumbent rollout speed, penetrating through specialized thermal engineering partnerships rather than capital-intensive land banking.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale GSAS-accredited engineering consultancies because auditor certification bottlenecks create captive revenue streams with limited supply expansion. Long-term viability centers on ten-year energy performance guarantee underwriting capabilities; watch for Ministry of Municipality cooling-load regulation tightening as the inflection signal requiring balance sheet strengthening.
| Strategic Initiative | Industry Significance |
|---|---|
| GSAS Certification Investment | Gold and Platinum ratings unlock expedited permitting from Qatar's Ministry of Municipality, compressing project approval cycles. |
| Modular Construction Integration | European-engineered volumetric systems merge with local concrete supply chains to reduce on-site labor dependency in Lusail. |
| Backward Integration into Low-Carbon Concrete | Batch plant retrofitting captures margin pools exposed to Saudi and UAE import price volatility and freight cost swings. |
| Outcome-Based Energy Performance Partnerships | Ten-year cooling efficiency obligations transfer operational risk from institutional investors to contractor-operator consortia. |
| District Cooling Infrastructure Lock-In | Lusail Smart City parcels with committed district cooling attract modular methods for speed-to-market advantage. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Qatari Ministry of Municipality permitting officers, GSAS-accredited project managers, thermal performance engineers, and procurement leads at diversified construction conglomerates with secondary validation against Qatar General Organization for Standard and Metrology testing protocols, Ministry of Environment building energy code filings, and Gulf Cooperation Council trade flow data. Bottom-up project pipeline aggregation and top-down sectoral expenditure analysis triangulated market sizing.
Segment-weighting across project type, building material, construction method, and end user dimensions anchored the analytical framework, with luxury condominium and multi-family unit trajectories modeled separately from single-family home dynamics. CAGRs derived from fitted growth curves applied to disclosed permitting volumes and announced development pipelines, incorporating cooling-load regulation evolution and GSAS certification adoption curves as Qatar-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden Ministry of Municipality energy code tightening or accelerated GSAS auditor certification expansion. Forecasts reflect documented assumptions regarding expatriate professional inflow sustainability and regional steel-cement supply stability. A model refresh is warranted upon material change in GSAS certification mandate scope or Lusail Smart City infrastructure commitment pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Canada Residential Construction Market
Residential Construction
Siding Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
US Residential Remodeling Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
North America Residential Construction Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Residential Roofing Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Japan Residential Construction Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
US Residential Construction Market