
 Commercial Air Conditioner (AC) Market | 2026-2036
Commercial Air Conditioner (AC) Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Air Conditioner (AC) Market Intelligence
The capital-intensity divergence between full-system manufacturers and component assemblers is unwinding competitive stability across the commercial AC sector. Daikin Industries leverages captive compressor production to control cost architecture in rooftop and VRF systems. Carrier Global sustains scale advantages through its North American chiller and packaged unit footprint. Gree Electric anchors volume leadership in inverter-driven split systems exported across Asia-Pacific and Middle Eastern markets.
Commercial air conditioners are electromechanical climate-control systems designed to maintain thermal comfort and air quality in non-residential built environments, typically operating at capacities from three tons to several hundred tons with coefficient-of-performance ratings that determine energy efficiency compliance. Their primary commercial purpose centers on protecting occupant productivity, sensitive equipment, and perishable inventory across conditioned spaces. Chillers and rooftop units occupy the largest installed base in North American office buildings and institutional facilities, while variable refrigerant flow systems are capturing incremental share in hotel retrofits where zonal control commands premium pricing. Data center applications represent the fastest-expanding demand pool, with precision cooling and heat rejection requirements driving specification toward higher-efficiency inverter technology and evaporative-assisted designs.
The EPA enforces HFC phasedown timelines under the AIM Act that compel OEMs to transition toward lower-global-warming-potential refrigerants in new commercial equipment. The Department of Energy imposes minimum efficiency standards through federal test procedures that reset compliance baselines for rooftop units and split systems. California's Title 24 building energy code extends stricter demand thresholds that manufacturers must satisfy for market access across the country's largest state economy. Stakeholders must monitor refrigerant transition timelines, efficiency standard ratcheting, and regional code divergence to align product roadmaps with procurement cycles.
Market Dynamics
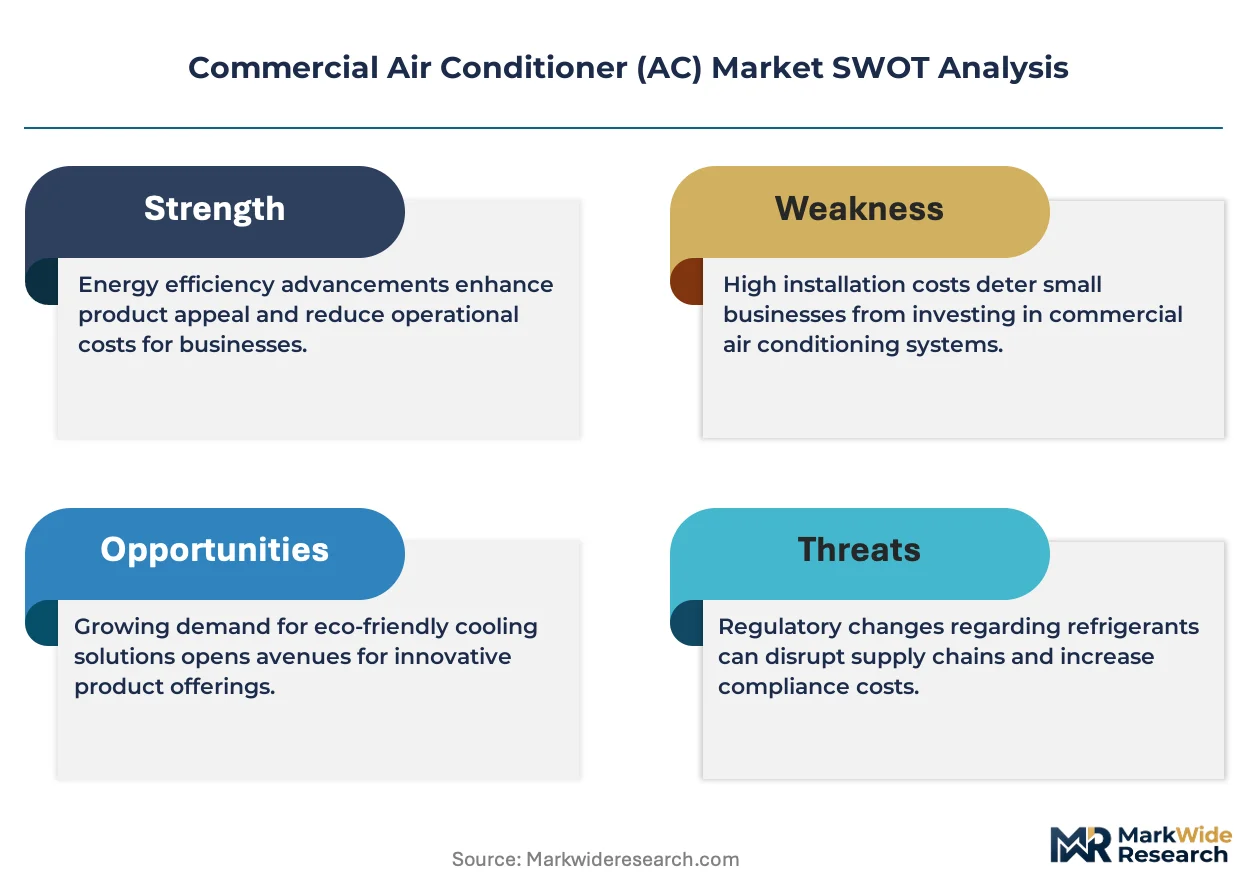
The EPA's phasedown of HFC refrigerants under the AIM Act is compressing equipment replacement cycles and forcing OEMs to accelerate lower-GWP refrigerant transitions across rooftop and chiller product lines.
Growth Catalysts
- Data Center Cooling Demand:Hyperscale operators in the United States are expanding precision cooling infrastructure to support AI workload density, driving specification toward higher-capacity chiller and evaporative-assisted systems.
- AIM Act Compliance Deadlines:The EPA's refrigerant phasedown timeline is compelling commercial building owners to advance replacement schedules for rooftop units and split systems ahead of 2028-2036 cutoffs.
- Inverter Technology Maturation:Variable-speed compressor control is penetrating mid-market packaged units, enabling part-load efficiency gains that satisfy Title 24 and federal test procedure baselines.
Market Restraints
- Copper and Aluminum Price Volatility:Coil and heat exchanger material costs fluctuate with commodity markets, compressing assembler margins and destabilizing project bidding for institutional buyers.
- Compressor Supply Concentration:Captive production at Japanese and Korean manufacturers limits independent sourcing options for mid-tier OEMs assembling rooftop and VRF systems.
- R-410A Equipment Stranding Risk:The phasedown trajectory threatens residual value for installed base equipment, dampening retrofit investment in buildings with 10-15 year remaining depreciation schedules.
Strategic Opportunities
- Evaporative Cooling in Sun Belt States:Arizona, Texas, and Florida building codes are relaxing water-use restrictions for hybrid cooling designs, opening specification pathways for indirect evaporative-assisted chillers in dry climates.
- Heat Pump Retrofit Acceleration:The Inflation Reduction Act's commercial tax credits for electrification are repositioning rooftop heat pumps as drop-in replacements for gas-fired heating in Midwest and Northeast facilities.
- AI-Driven Predictive Maintenance:Equipment-embedded sensors converging with cloud analytics platforms are enabling service revenue unbundling from hardware sales for multi-site retail and hospitality operators.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:EPA Section 608 technician credentialing capacity is constraining installation workforce expansion, delaying project completion for mechanical contractors.
- Legacy BAS Integration Complexity:Newer inverter-driven systems require protocol translation layers to communicate with existing building automation systems, extending commissioning timelines and callback rates.
- Supply Chain Reconfiguration Friction:Transition to lower-GWP refrigerants is forcing coil and valve supplier qualification cycles that compress product launch windows for 2025-2026 model year introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Air Conditioner (AC) Market |
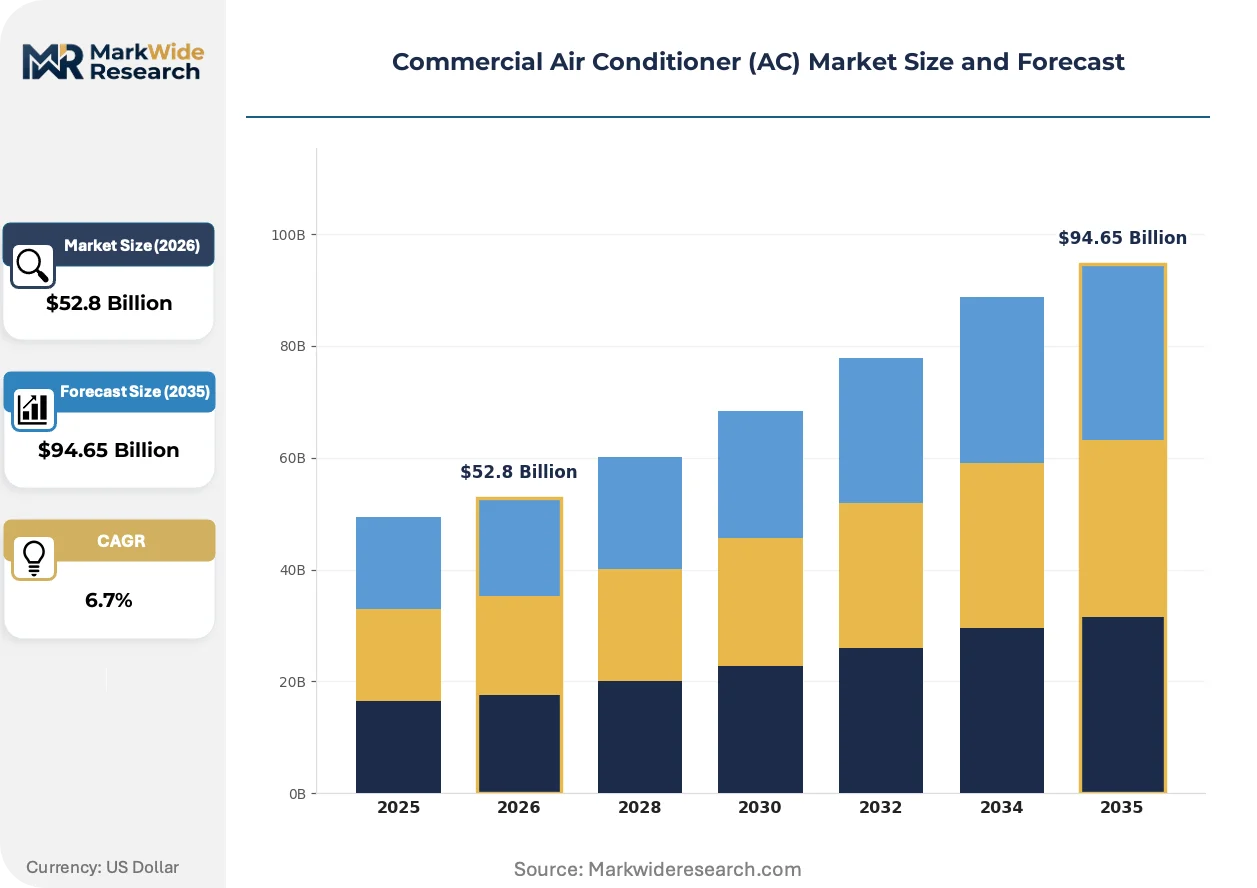
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $94.65 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rooftop Units, Split Systems, Packaged Air Conditioners, Chillers, Portable ACs Technology: Inverter Technology, Variable Refrigerant Flow, Heat Pump, Absorption Cooling, Evaporative Cooling Application: Office Buildings, Hotels, Educational Institutions, Data Centers, Manufacturing Facilities End User: Property Managers, Facility Management Firms, Commercial Real Estate Developers, Institutional Owners |
| Companies Covered | Johnson Controls, Gree Electric, Daikin Industries, Lennox International, Midea, Carrier Global, Mitsubishi Electric, Rheem Manufacturing, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Air Conditioner (AC) Market Strategic Shifts & Innovations
Refrigerant chemistry transitions and intelligent system controls are restructuring how commercial cooling equipment is specified, procured, and serviced across institutional and industrial verticals.
Magnetic-bearing chiller technology is eliminating oil management systems and reducing mechanical friction losses in large-tonnage applications. Data center operators and hospital facility managers are specifying these units for 24/7 base-load operations where maintenance access is constrained. The technology is bifurcating the centrifugal chiller market into oil-free premium tiers and conventional lubricated economy tiers.
The EPA's Technology Transitions Program under AIM Act Section 103 is prohibiting certain HFC blends in new commercial refrigeration and air conditioning equipment. OEMs must certify alternative refrigerants through SNAP approval pathways, compressing product development timelines. California's Title 24 2025 standards are extending this pressure by mandating GWP thresholds below 750 for new packaged rooftop units.
Building owners are unbundling equipment purchase from long-term service agreements, treating cooling systems as operational expenditures rather than capital assets. Third-party energy service companies are capturing specification influence through performance contracting models. This pattern concentrates in Texas and Florida school districts and municipal buildings where budget authority has shifted to facilities-as-a-service frameworks.
Commercial Air Conditioner (AC) Market Segmentation
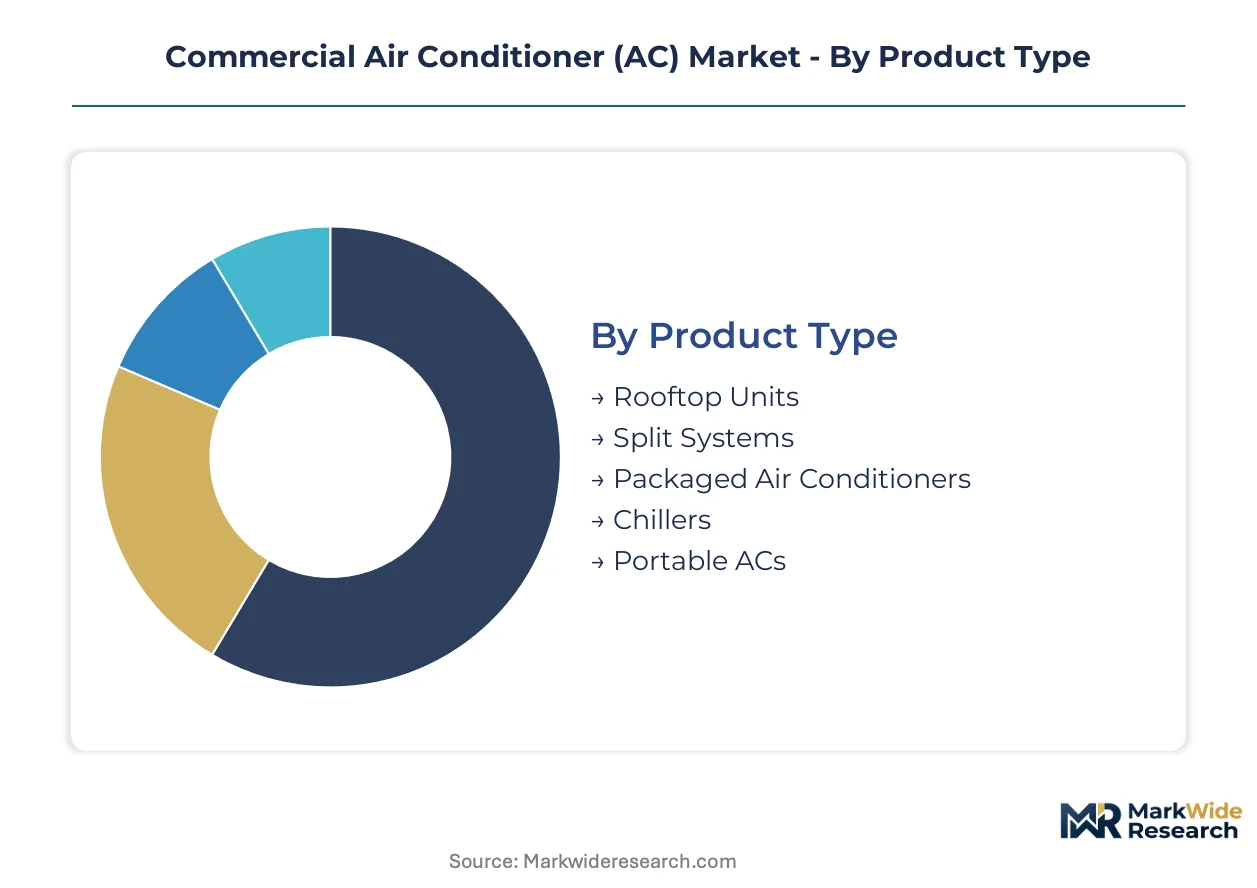
Commercial AC procurement patterns diverge sharply across equipment categories, with refrigerant transition timelines and building automation compatibility creating distinct substitution pressures. Specification authority varies by end-user type, fragmenting pricing power and service bundling strategies across the value chain.
Product Type:
Rooftop units and chillers face intensifying substitution pressure from modular split configurations as zonal control requirements reshape building retrofit economics.
- Rooftop Units:Self-contained packaged systems mounted on flat commercial roofs, integrating compressors, coils, and air handlers in weatherized enclosures. Demand concentrates in Sun Belt retail and office construction where single-story footprints dominate, though EPA refrigerant deadlines are compressing replacement cycles for aging R-410A stock.
- Chillers:Centralized water-cooled or air-cooled systems delivering conditioned fluid to air-handling units across large facilities. Data center operators in Northern Virginia and Dallas-Fort Worth are specifying magnetic-bearing oil-free variants for 24/7 base-load operations where maintenance access carries premium cost.
- Split Systems:Separated indoor evaporator and outdoor condenser units connected by refrigerant lines, enabling flexible zoning without ductwork reconstruction.
- Packaged Air Conditioners:Factory-assembled units combining compressor, coil, and fan in single cabinets for ground-level or mechanical room installation.
- Portable ACs:Mobile spot-cooling units deployed for temporary climate control during equipment failures or construction phasing.
Rooftop units retain volume leadership in North American commercial stock; chillers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium inverter platforms from conventional fixed-speed equipment, with payback period sensitivity determining adoption depth across customer segments.
- Inverter Technology:Variable-frequency drives modulate compressor speed to match thermal load, eliminating on-off cycling losses. Hotels in Florida and Arizona are retrofitting with inverter splits to capture Title 24 compliance credits and reduce peak demand charges.
- Variable Refrigerant Flow:Refrigerant-based zonal systems with individual evaporator control per thermal zone, minimizing distribution losses. Hospitality operators in Texas are specifying VRF for full-building retrofits where simultaneous heating and cooling recovery improves seasonal efficiency.
- Heat Pump:Reversible vapor-compression cycles providing heating and cooling from common hardware, displacing gas-fired furnaces in electrification mandates.
- Absorption Cooling:Heat-activated refrigeration cycles using lithium bromide or ammonia-water pairs, deployed where waste heat or natural gas pricing favors thermal over electric drive.
- Evaporative Cooling:Direct and indirect water-assisted heat rejection systems exploiting dry-bulb/wet-bulb differentials in arid climates.
Inverter technology commands the premium tier by efficiency certification; heat pumps are climbing the fastest on electrification policy tailwinds.
Application:
Volume concentration in legacy office stock contrasts with specification intensity in emerging verticals where thermal precision carries operational risk.
- Data Centers:Precision cooling infrastructure maintaining server inlet temperatures within tight bands, with redundancy requirements driving N+1 or 2N configurations. Hyperscale operators in Phoenix and Ashburn are expanding chiller and evaporative-assisted capacity to support AI training cluster density.
- Hotels:Guest room and common area climate control with high part-load operating hours and occupancy-driven variability. Full-service properties in Miami and Houston are prioritizing VRF retrofits to unbundle energy costs from franchise fee structures.
- Office Buildings:Centralized or zoned comfort conditioning for tenant-occupied commercial space, representing the largest installed base by tonnage.
- Educational Institutions:K-12 and university facilities with seasonal occupancy patterns and public procurement constraints.
- Manufacturing Facilities:Process cooling and occupant comfort in industrial environments with high internal heat gains and contamination control requirements.
Office buildings retain volume leadership by installed base; data centers hold the steepest expansion curve.
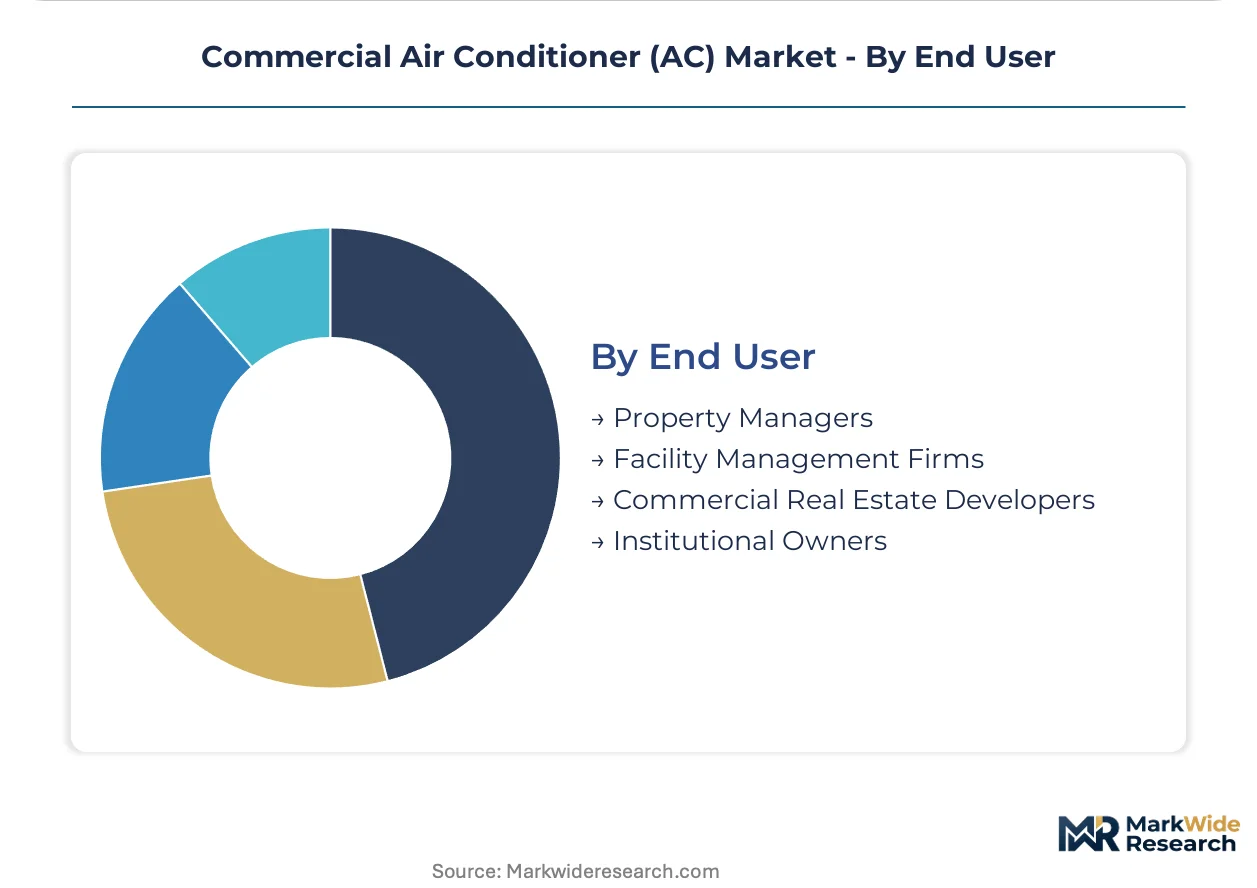
End User:
Procurement authority fragmentation separates capital-budget owners from operational-expenditure managers, reshaping vendor relationship economics.
- Facility Management Firms:Third-party operators assuming lifecycle responsibility for mechanical systems under multi-year service agreements. National FM providers are consolidating specification influence across Sun Belt commercial portfolios, unbundling equipment selection from installation contracting.
- Commercial Real Estate Developers:Spec builders and renovation sponsors targeting lease-up velocity and asset disposition timelines. Developers in Austin and Atlanta are pre-wiring rooftop units for future heat pump conversion to capture Inflation Reduction Act tax credit eligibility.
- Property Managers:Asset-level operators balancing tenant satisfaction against utility cost recovery in multi-tenant buildings.
- Institutional Owners:Self-managed entities including school districts, hospital systems, and government agencies with extended hold periods and maintenance staff capabilities.
Facility management firms retain volume leadership by contract scope; commercial real estate developers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where regulatory deadlines compress replacement cycles, while Chinese manufacturers anchor volume production for cost-sensitive export markets across Southeast Asia and the Middle East.
United States
Data center clusters in Northern Virginia and Phoenix are scaling precision cooling infrastructure to support AI workload density. The EPA's AIM Act refrigerant phasedown is compelling building owners to advance rooftop unit replacements ahead of 2028-2036 cutoffs. Sun Belt metropolitan areas including Dallas-Fort Worth and Houston are experiencing concentrated demand for high-efficiency heat pump retrofits.
China
Domestic commercial construction in tier-one cities is stabilizing while export manufacturing for inverter-driven split systems accelerates. The Ministry of Ecology and Environment is enforcing dual carbon goals that tighten efficiency standards for packaged equipment. Manufacturing clusters in Guangdong and Zhejiang provinces are reconfiguring coil and valve supply chains for lower-GWP refrigerant compatibility.
Japan
Building stock modernization in Tokyo and Osaka is driving VRF system upgrades for improved zonal control. METI efficiency standards are ratcheting minimum performance thresholds for commercial equipment sold domestically. Nagoya-based industrial corridors maintain captive compressor production that supplies regional OEM assembly operations.
Germany
Industrial facility retrofits in North Rhine-Westphalia are specifying heat pump chillers to displace gas-fired heating under electrification mandates. The EU F-Gas Regulation is prohibiting high-GWP refrigerants in new commercial equipment ahead of broader phase-down timelines. Manufacturing concentration in Baden-Württemberg supports precision engineering for magnetic-bearing chiller components.
India
Commercial real estate expansion in Mumbai and Bangalore is generating demand for ducted split systems in Class A office developments. Bureau of Indian Standards certification requirements are tightening energy efficiency labeling for imported packaged units. Gujarat-based manufacturing zones are scaling assembly capacity for mid-tonnage rooftop units serving domestic and Middle Eastern export markets.
Commercial Air Conditioner (AC) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the commercial AC sector. Japanese and Korean manufacturers control premium inverter and magnetic-bearing platforms through captive component production, while Chinese and Southeast Asian assemblers dominate volume tiers through modular sourcing strategies. Three archetypes define competitive positioning: vertically integrated system specialists, component-scale assemblers, and regional service-integrated distributors. Consolidation pressure is intensifying through backward integration into compressor manufacturing and forward integration into predictive maintenance service platforms.
Within the integrated system specialist tier, Daikin Industries and Carrier Global exemplify divergent geographic anchoring strategies. Daikin leverages Japanese captive production networks across VRF and rooftop portfolios, while Carrier sustains North American scale advantages through chiller and packaged unit infrastructure. Gree Electric occupies a position within the volume-tier assembler archetype, exporting inverter-driven split systems across Asia-Pacific and Middle Eastern markets.
| Leading Market Players |
|---|
| Johnson Controls |
| Gree Electric |
| Daikin Industries |
| Lennox International |
| Midea |
| Carrier Global |
| Mitsubishi Electric |
| Rheem Manufacturing |
| Trane Technologies |
| Others |
Cost & Logistics Intelligence
EPA Section 608 technician certification requirements gate both contractor qualification and installed-system pricing premiums simultaneously. The AIM Act's refrigerant phasedown compresses supply qualification timelines for coil and valve suppliers while forcing price differentiation between R-410A legacy stock and lower-GWP alternatives.
Pricing Analysis
Configured-to-order magnetic-bearing chillers command substantial premiums over standard fixed-speed packaged units. Three-tier pricing structure across premium inverter platforms, standard fixed-speed equipment, and economy-grade split systems reflects certification grade and after-sales service bundling. Cost compression in mid-tier rooftop units is intensifying because copper and aluminum coil material volatility destabilizes project bidding. Institutional owners in educational and healthcare verticals exhibit highest price sensitivity, while data center operators prioritize thermal precision over capital cost.
Supply Chain Analysis
Strategic stockpiling of compressor inventories dominates over just-in-time preferences given Japanese and Korean captive production concentration. Component supply concentrates in China, Japan, and South Korea for inverter drives and magnetic bearings; coil fabrication rests on copper sourcing from Chile and aluminum from Australia. Single-source vulnerability around compressor supply constrains independent OEM assembly capacity. Distribution runs through authorized dealer networks and direct mechanical contractor relationships for specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, California Title 24, and state-level electrification mandates creates niche positioning opportunities for specialized compliance-focused suppliers.
For Market Incumbents: Compound scale advantages in captive compressor production to defend against emerging inverter-technology specialists from Southeast Asia. Prioritize backward integration into refrigerant handling certification training capacity to address EPA Section 608 technician bottlenecks constraining installation throughput. Expand service platform revenue through predictive maintenance analytics unbundled from hardware sales. For New Entrants and Emerging Players: Differentiate on rapid refrigerant transition compliance for 2025-2026 model year launches where incumbent qualification cycles lag. Target Sun Belt municipal and school district facilities-as-a-service frameworks where procurement authority has shifted to third-party operators. Pursue white-label manufacturing partnerships with established coil suppliers to compress time-to-market. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across magnetic-bearing chiller sub-segments where oil-free technology requires specialized component fabrication. Long-term viability favors vertically integrated system specialists over modular assemblers as refrigerant chemistry transitions force tighter supplier qualification. Target acquisition archetypes include predictive maintenance software platforms and regional service-integrated distributors. Monitor EPA refrigerant allocation rulemaking as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Acceleration | AIM Act compliance deadlines compress product development timelines for lower-GWP equipment certification. |
| Predictive Maintenance Platform Development | Equipment-embedded sensors enable service revenue unbundling for multi-site retail operators. |
| Heat Pump Retrofit Capacity Expansion | Inflation Reduction Act tax credits reposition rooftop heat pumps as gas-fired replacements. |
| Evaporative Cooling Hybrid Systems | Arizona and Texas building code relaxations open specification pathways for indirect designs. |
| Technician Certification Infrastructure | EPA Section 608 credentialing capacity constraints delay project completion for mechanical contractors. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, DOE efficiency standard dockets, and equipment shipment databases. Interviews with facilities management executives, mechanical contractor operations directors, OEM product managers, and building automation systems integrators inform demand-side validation. Secondary sources include AHRI certification directories, customs trade data for compressor imports, and state-level building code adoption records. Bottom-up equipment shipment analysis triangulates against top-down construction spending allocation models.
Segmentation dimensions modeled span product type, technology architecture, application vertical, and end-user procurement authority across the analysis window. CAGRs derive from regression analysis of historical shipment volumes against regulatory deadline impacts and replacement cycle compression effects. Industry-specific forecast inputs incorporate AIM Act phasedown trajectory assumptions and Title 24 efficiency threshold ratcheting.
The analysis sits within stated boundaries; outcomes outside assumed refrigerant transition timelines or commodity price stabilization would require recalibration. Forecasts reflect documented assumptions regarding technician certification capacity expansion and supply chain reconfiguration velocity. Revision becomes warranted when copper-aluminum price volatility crosses thresholds that destabilize project economics for institutional buyers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
Utility and Industrial Boilers Market