
 China Residential Heat Pump Market | 2026-2036
China Residential Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
China Residential Heat Pump Market Insights
Retrofit homeowners is collapsing as the dominant buyer archetype, displacing new construction developers who dominated prior installation cycles. Midea Group leverages its inverter compressor manufacturing scale to anchor pricing power across mid-tier residential projects. Gree Electric Appliances differentiates through in-house production of permanent magnet motors, sustaining margin control that external suppliers cannot match. Haier Group competes on smart home integration, extending its IoT ecosystem into thermal management interfaces that lock in recurring service revenue.
China residential heat pumps electromechanically transfer thermal energy from ambient air, ground, or water sources into indoor space heating and domestic hot water circuits, typically achieving coefficient of performance ratings between 3.0 and 5.0 under standard test conditions. Air Source products dominate unit volume due to lower installation complexity and minimal site preparation, though Ground Source installations command premium positioning where drilling access permits deep borehole fields. Inverter technology leads the technology dimension by modulating compressor speed against partial heating loads, while Split-system configurations capture the fastest growth trajectory as consumers replace aging coal-fired radiator infrastructure with distributed refrigerant-based heating.
MIIT enforces GB standards that mandate seasonal performance factors for residential heat pumps sold in China, directly disqualifying legacy fixed-speed models from eligibility for provincial clean heating subsidies. NMPA coordinates with provincial energy bureaus to align equipment certification with building code enforcement, creating compliance barriers for uncertified imports. Stakeholders must monitor how municipal carbon-accounting rules reshape subsidy allocation across northern heating zones versus southern emerging markets.
Market Dynamics
Retrofit installations in aging urban residential blocks are compressing replacement cycles and redirecting demand away from new construction channels, fundamentally restructuring how equipment flows reach end users.
Growth Catalysts
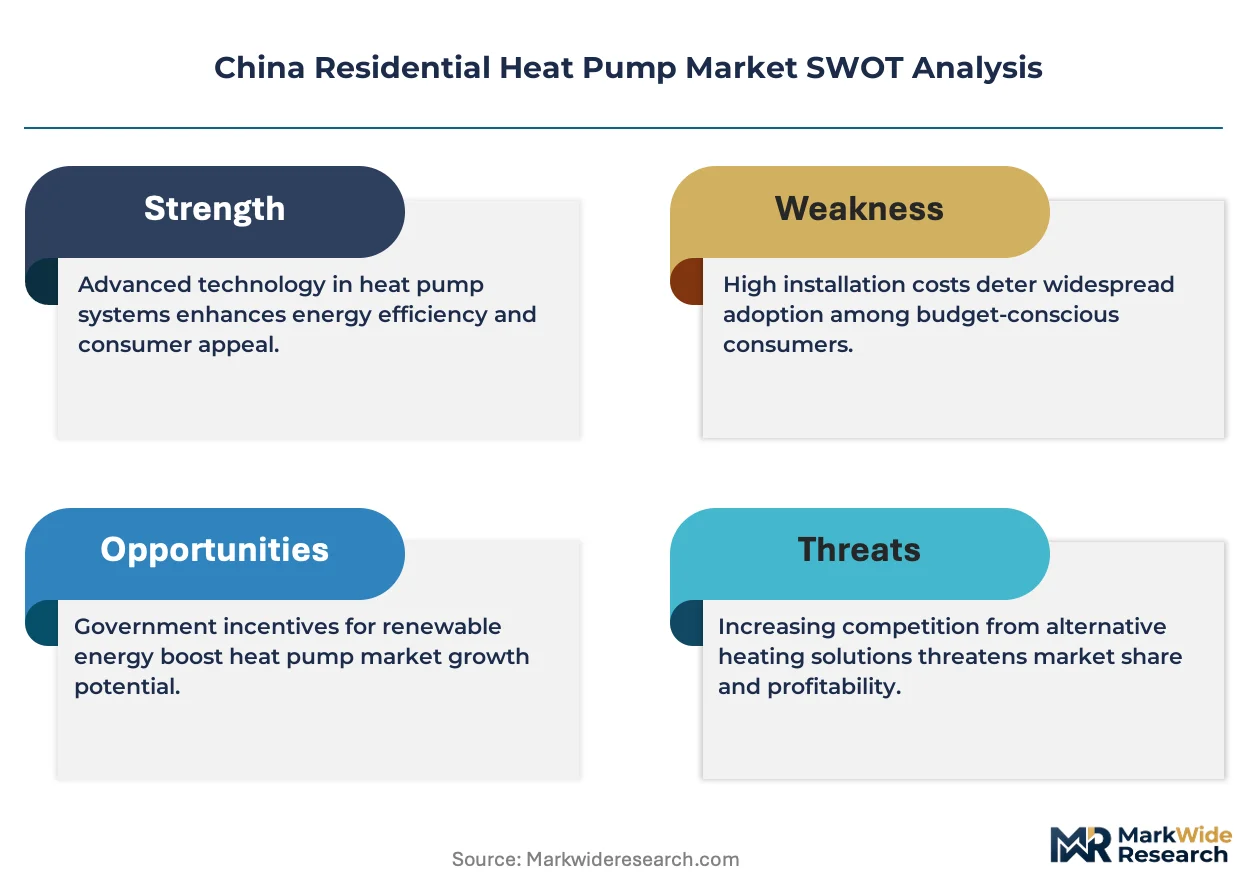
- Dual carbon goals:China's national emissions targets mandate building sector decarbonization, creating policy-backed demand pull for electrified heating infrastructure in residential zones previously dependent on coal.
- Updated GB energy-efficiency standards:MIIT-enforced seasonal performance factor requirements disqualify fixed-speed legacy equipment from provincial clean heating subsidies, accelerating equipment turnover.
- Yangtze River Delta humidity conditions:Winter moisture profiles in this cluster amplify heat pump coefficient-of-performance advantages versus conventional gas boilers, concentrating adoption in high-density coastal cities.
Market Restraints
- Copper and rare-earth magnet costs:Permanent magnet motor production depends on neodymium supply chains concentrated in Inner Mongolia processing facilities, exposing margins to raw material volatility.
- Deep borehole drilling constraints:Ground-source installations require geological survey approvals and urban drilling permits that extend project timelines in dense municipal jurisdictions.
- Legacy radiator incompatibility:Existing cast-iron radiator infrastructure in northern heating zones operates at temperature profiles mismatched with low-temperature heat pump output, forcing full system replacement.
Strategic Opportunities
- Southern emerging markets:Provinces south of the Qinling-Huaihe line lack centralized district heating, creating first-mover advantage for distributed air-source deployment in cities like Changsha and Nanchang.
- IoT-thermal convergence:Smart home platforms integrating heat pump control with photovoltaic generation and battery storage enable whole-home energy optimization services.
- Rural clean heating subsidies:Municipal carbon-accounting rules in northern counties prioritize heat pump installations over biomass alternatives, redirecting fiscal support to electrified solutions.
Industry Challenges
- Refrigerant handling certification:Installation crews require MEE-accredited credentials for R32 and R290 systems, constraining workforce scalability during peak autumn installation windows.
- Interoperability with legacy controls:Coal-to-electric retrofits demand integration with existing thermostat wiring and zoning valves originally designed for high-temperature boiler operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Residential Heat Pump Market |
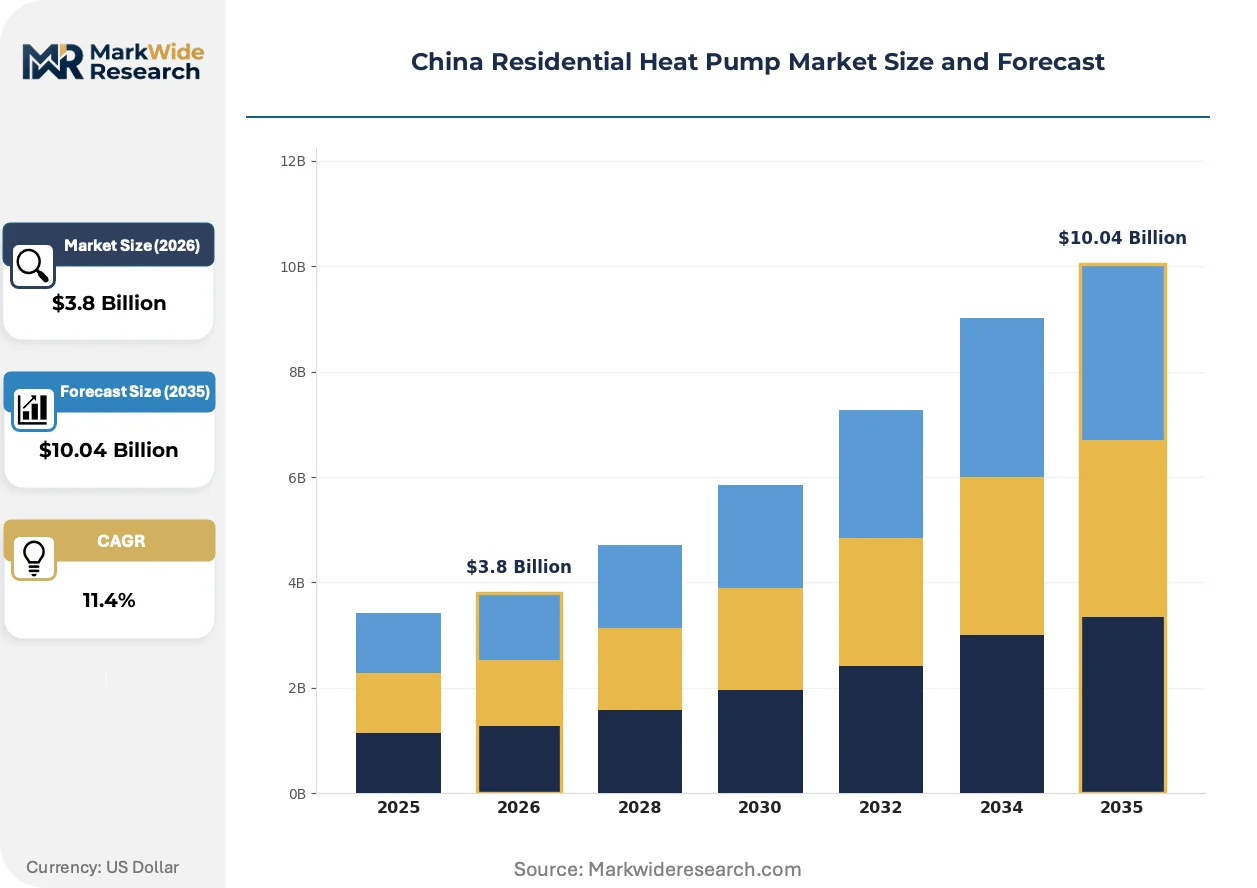
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Water Source, Hybrid Technology: Inverter, Split-system, Portable, Mini-split End User: Single-family Homes, Multi-family Dwellings, Residential Complexes, Condominiums Installation Type: New Construction, Retrofit, Replacement, Pre-installed |
| Companies Covered | LinkedGo Technology, Guangzhou SPRSUN New Energy Technology Development Co., Ltd., Midea Group, Aux, Power World Machinery Equipment Co., Ltd., Gree Electric Appliances, Newntide, Haier Group, PHNIX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Residential Heat Pump Market Trends and Innovations
Inverter modulation algorithms and refrigerant chemistry advances are compressing the performance gap between air-source and ground-source systems, eroding the historical premium positioning of borehole-dependent installations.
Variable-speed inverter compressors are supplanting fixed-speed scroll units in mid-tier residential projects. Retrofit homeowners in Shanghai and Hangzhou specify inverter systems for partial-load efficiency during shoulder seasons. This technology is supplanting legacy on-off cycling equipment that dominated prior replacement cycles in aging apartment blocks.
MIIT's GB standards mandate seasonal performance factor testing under partial-load conditions, disqualifying equipment that only meets full-load efficiency metrics. Manufacturers must redesign heat exchanger circuits and expansion valve control logic to maintain coefficient-of-performance ratings across operating envelopes. Northern heating zone distributors now stock exclusively inverter-compliant inventory to preserve subsidy eligibility.
Service unbundling is fragmenting the traditional equipment-plus-installation bundle. Homeowners in Jiangsu and Zhejiang provinces separately procure hardware through e-commerce channels and contract certified technicians through municipal installer registries. This pattern concentrates in cities where NMPA-aligned certification databases enable consumer verification of installer credentials independent of manufacturer networks.
China Residential Heat Pump Market Segmentation
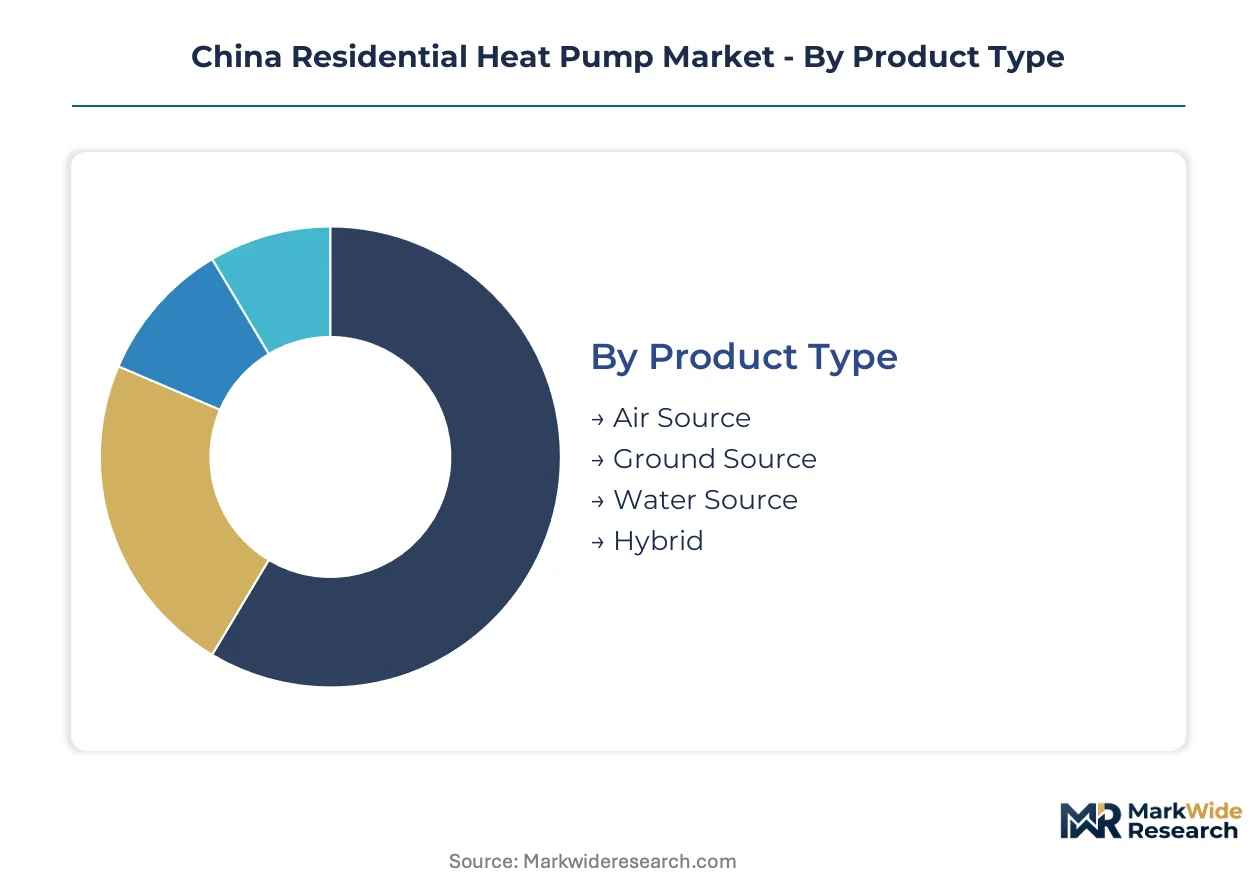
Segmentation in the China residential heat pump market determines subsidy eligibility through MIIT's GB standards compliance and shapes channel economics across retrofit versus new construction flows. Distinct technology-product combinations command different margin profiles and installation crew certification requirements.
Product Type:
Air Source units flow primarily through municipal installer registries and e-commerce channels, while Ground Source projects require geological survey coordination that extends sales cycles through specialized engineering firms.
- Air Source:Electromechanical systems extract thermal energy from ambient air through vapor-compression cycles, achieving coefficient-of-performance ratings between 3.0 and 5.0 under standard test conditions. Demand concentrates in Yangtze River Delta cities where winter humidity amplifies efficiency advantages over gas boilers, though legacy radiator incompatibility in northern zones forces full system replacement during retrofits.
- Ground Source:Borehole-dependent installations utilize deep vertical or horizontal ground loops to access stable subsurface temperatures year-round. Project timelines extend in dense municipal jurisdictions where urban drilling permits and geological approvals create compliance barriers that air-source systems bypass.
- Water Source:Systems leverage adjacent water bodies or aquifers as thermal exchange media, requiring site-specific hydrological assessments.
- Hybrid:Configurations combine heat pump operation with auxiliary fossil-fuel heating for extreme cold-weather performance margins.
By volume, Air Source leads. By growth pace, Hybrid configurations are expanding most quickly as northern heating zones seek cold-climate performance assurance.
Technology:
Cost tiers separate inverter-based variable-speed systems from fixed-speed legacy equipment, with MIIT's seasonal performance factor mandates pushing distributor inventory toward premium modulation technologies.
- Inverter:Variable-speed compressor modulation optimizes partial-load efficiency during shoulder seasons, with algorithms adjusting refrigerant flow against real-time heating demand. Retrofit homeowners in Shanghai and Hangzhou specify these systems for operational cost control, while GB standards now disqualify fixed-speed alternatives from provincial clean heating subsidies.
- Split-system:Distributed refrigerant-based heating replaces aging coal-fired radiator infrastructure through separate indoor and outdoor units connected by line sets. This configuration captures steep expansion trajectories in Jiangsu and Zhejiang provinces where consumers separately procure hardware and contract certified technicians.
- Portable:Self-contained units require no permanent installation, serving rental markets and temporary heating needs.
- Mini-split:Compact ductless configurations target apartment-scale applications with minimal structural modification.
Inverter technology commands the revenue concentration. Split-system configurations are gaining share fastest through retrofit channel acceleration.
End User:
Customer type determines project scale and procurement pattern, with single-family homeowners driving service unbundling trends that fragment traditional equipment-plus-installation bundles.
- Single-family Homes:Detached residential structures with dedicated mechanical rooms and exterior equipment pads enable flexible system sizing. Homeowners in southern emerging markets like Changsha and Nanchang pursue first-mover advantage where centralized district heating infrastructure remains absent.
- Multi-family Dwellings:Shared wall construction and centralized utility distribution create economies of scale for stacked installation configurations. Building management procurement in aging urban residential blocks compresses replacement cycles as coal-to-electric mandates cascade through municipal housing bureaus.
- Residential Complexes:Master-planned developments with unified architectural standards enable standardized equipment specifications across multiple units.
- Condominiums:Individual unit ownership with common-area infrastructure creates split-incentive challenges for thermal system investment.
Multi-family Dwellings dominate unit volume through retrofit concentration. Single-family Homes show the steepest expansion trajectory as southern provinces electrify heating for the first time.
Installation Type:
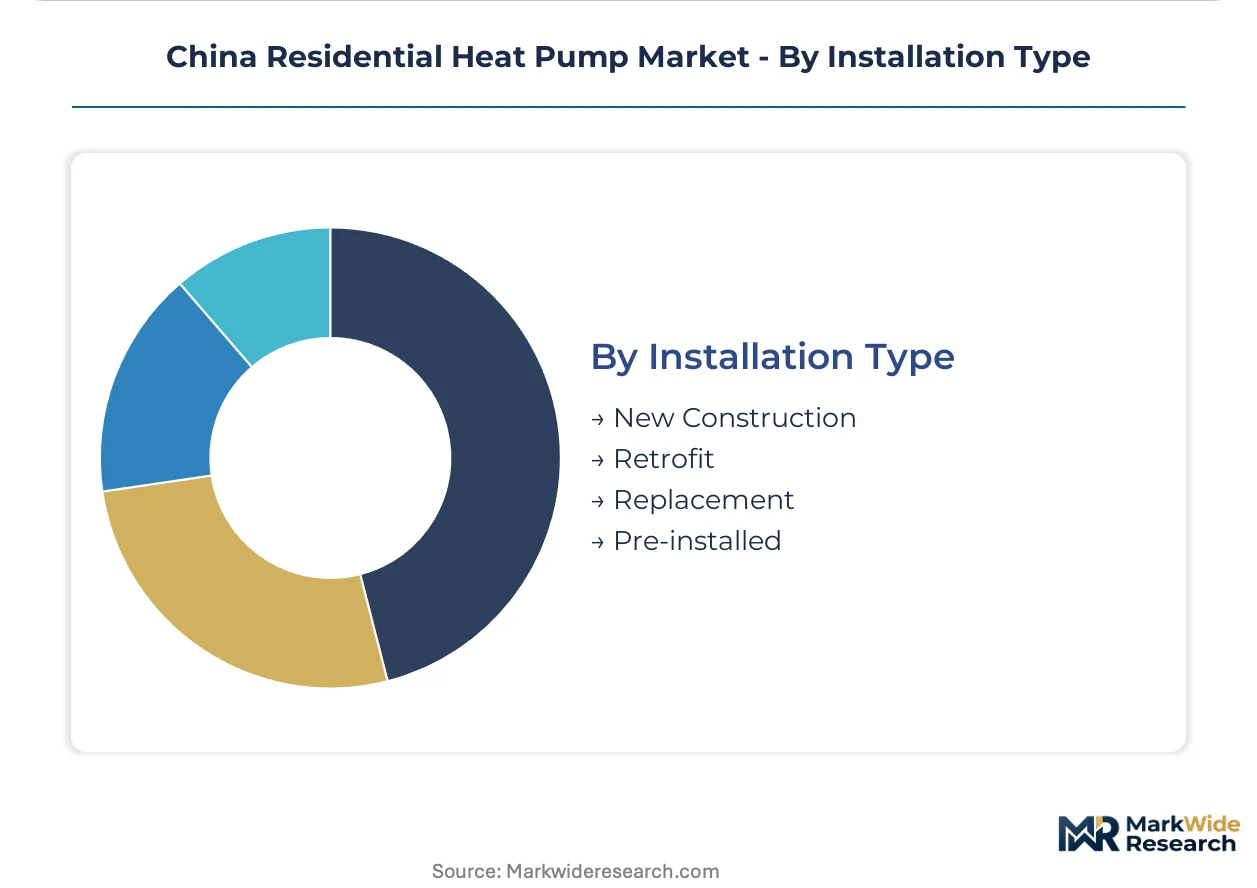
Maturity gradients separate established replacement flows from emerging pre-installed channels, with new construction volumes declining relative to retrofit as policy priorities shift toward existing building stock decarbonization.
- Retrofit:Coal-to-electric conversions in aging urban residential blocks demand integration with existing thermostat wiring and zoning valves originally designed for high-temperature boiler operation. Municipal carbon-accounting rules in northern counties prioritize these installations over biomass alternatives, redirecting fiscal support to electrified solutions.
- Replacement:Equipment swap-outs of prior-generation heat pumps occur on accelerated cycles as GB efficiency standards tighten minimum performance thresholds nationwide.
- New Construction:Developer-specified systems in greenfield residential projects face compressed margins through volume procurement negotiations.
- Pre-installed:Builder-integrated specifications at construction phase capture standardization benefits but require long-dated inventory commitments.
Retrofit installations lead by volume. Replacement activity is climbing the fastest as fixed-speed equipment loses subsidy eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for residential heat pumps clusters along China's eastern seaboard, with compressor and heat exchanger fabrication concentrating in provinces with established HVAC supply chains. Provincial subsidy programs and building code enforcement vary substantially across heating zones, creating divergent adoption timelines.
Yangtze River Delta
Winter humidity conditions in Shanghai, Hangzhou, and Nanjing amplify heat pump coefficient-of-performance advantages over conventional gas boilers. MIIT's GB standards enforcement here predates northern provinces, accelerating fixed-speed equipment obsolescence. Retrofit installations in aging apartment blocks dominate procurement, with homeowners separately sourcing hardware through e-commerce channels.
Beijing-Tianjin-Hebei
Coal-to-electric mandates from municipal carbon-accounting rules prioritize heat pump installations over biomass alternatives in rural counties surrounding the capital. Legacy cast-iron radiator infrastructure creates temperature-profile mismatches with low-temperature heat pump output, forcing full system replacement. Deep borehole drilling constraints extend project timelines in dense municipal jurisdictions.
Pearl River Delta
First-time electrification of residential heating drives demand in Guangzhou and Shenzhen where centralized district heating remains absent. NMPA coordinates with provincial energy bureaus to align equipment certification with building code enforcement. Manufacturing scale for inverter compressors concentrates in Foshan and Dongguan industrial corridors.
Sichuan-Chongqing
Western expansion of residential heat pump markets targets emerging middle-class housing in Chengdu and Chongqing megacities. Ground-source installations face geological survey requirements that air-source systems bypass. Provincial clean heating subsidies redirect fiscal support toward electrified solutions as dual carbon goals cascade through municipal housing bureaus.
Shandong Peninsula
Northern heating zone distributors stock exclusively inverter-compliant inventory to preserve subsidy eligibility under tightened GB efficiency standards. Rare-earth magnet processing facilities in Inner Mongolia feed permanent magnet motor production, exposing margins to raw material volatility. Qingdao and Jinan anchor distribution networks serving retrofit replacement cycles.
China Residential Heat Pump Market Competitive Landscape
Concentration sits with diversified appliance conglomerates that leverage captive compressor manufacturing and established distribution networks. The competitive structure tiers across three distinct archetypes: integrated appliance groups with inverter technology scale, specialized heat pump fabricators focused on export-grade engineering, and emerging smart-home platforms extending IoT ecosystems into thermal management. Dominant competitive moves include backward integration into permanent magnet motor production and strategic partnerships with municipal installer registries to secure retrofit channel access.
Among integrated appliance conglomerates, Midea Group and Gree Electric Appliances exemplify scale-driven positioning through captive supply chains. Haier Group occupies a position within the smart-home convergence archetype, extending platform ecosystems into distributed heating interfaces. Specialized fabricators including Guangzhou SPRSUN New Energy Technology Development Co., Ltd. and PHNIX represent engineering-focused tiers targeting export specifications and premium efficiency ratings. Newntide and Power World Machinery Equipment Co., Ltd. sit within mid-market positioning, while regional technology providers such as LinkedGo Technology and Aux anchor value-tier supply. Zhengzhou-based Newntide and Foshan-area SPRSUN illustrate geographic clustering alongside component manufacturing corridors.
| Leading Market Players |
|---|
| LinkedGo Technology |
| Guangzhou SPRSUN New Energy Technology Development Co., Ltd. |
| Midea Group |
| Aux |
| Power World Machinery Equipment Co., Ltd. |
| Gree Electric Appliances |
| Newntide |
| Haier Group |
| PHNIX |
| Others |
Pricing and Supply Chain Analysis
Inverter compressor substitution for fixed-speed scroll units is redrawing manufacturing geography toward eastern seaboard industrial corridors while compressing margin structures across mid-tier residential projects. This technology displacement simultaneously concentrates pricing power with captive producers and erodes premium positioning for import-dependent assemblers.
Pricing Analysis
MIIT's GB seasonal performance factor mandates dictate the pricing tier structure across the China residential heat pump market. Three-tier pricing structure across premium inverter-compliant, standard modulation, and economy fixed-speed levels separates subsidy-eligible inventory from legacy equipment facing obsolescence. Cost compression in economy tiers is intensifying because neodymium magnet volatility and copper futures expose non-integrated assemblers to margin erosion. Multi-family dwelling retrofit buyers exhibit highest price sensitivity due to municipal procurement negotiations, while single-family homeowners in southern emerging markets show lowest sensitivity when pursuing first-time electrification.
Supply Chain Analysis
China anchors compressor and heat exchanger fabrication, with permanent magnet motor production drawing from Inner Mongolia rare-earth processing facilities and inverter control module assembly concentrating in Guangdong industrial corridors. Neodymium, copper tubing, and refrigerant-grade aluminum constitute critical input dependencies. Single-source vulnerability in rare-earth magnet supply creates exposure to export quota fluctuations and environmental compliance shutdowns. Distribution runs through municipal installer registries and e-commerce channels that fragment traditional manufacturer-controlled logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installation crew scarcity constrains peak-season capacity expansion, creating a bottleneck that separates equipment manufacturers able to secure trained labor partnerships from those facing autumn installation backlogs.
For Market Incumbents: Secure exclusive contracting relationships with MEE-accredited installer networks before peak retrofit windows compress available labor pools. Backward integration into permanent magnet motor production defends margin structures against Inner Mongolia rare-earth price volatility. Dominant appliance conglomerates must preemptively acquire geological survey licenses in Yangtze River Delta municipalities to accelerate ground-source project timelines before specialized engineering firms consolidate drilling access. For New Entrants and Emerging Players: Anchor in southern emerging markets south of the Qinling-Huaihe line where centralized district heating absence creates first-mover advantage for distributed air-source deployment. Changsha and Nanchang residential complexes represent the most penetrable segment due to nascent competitive presence and provincial subsidy alignment. Direct-to-consumer hardware procurement through e-commerce platforms, paired with municipal registry technician contracting, bypasses incumbent distribution control. For Investors and Strategic Acquirers: Secondary-cycle assets sit with export-grade engineering specialists holding PHNIX-tier efficiency certifications but lacking smart-home platform integration. Long-term viability hinges on IoT-thermal convergence capabilities that enable recurring service revenue streams beyond equipment sales. Watch for municipal carbon-accounting rule expansions beyond northern heating zones as the inflection signal for subsidy reallocation toward southern provinces.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | In-house neodymium motor production insulates margins from Inner Mongolia processing volatility. |
| Municipal Installer Registry Partnerships | Exclusive MEE-accredited crew access secures peak-season installation capacity against labor scarcity. |
| IoT-Thermal Platform Convergence | Smart home integration with photovoltaic and battery storage locks in recurring optimization service revenue. |
| Southern Province Geographic Expansion | First-mover positioning in Changsha and Nanchang captures electrification demand absent district heating infrastructure. |
| Geological Survey License Acquisition | Pre-secured drilling permits in Yangtze River Delta municipalities compress ground-source project timelines. |
Research Methodology
Desk research of MIIT regulatory filings, GB standards documentation, and provincial clean heating subsidy announcements preceded structured interviews with inverter compressor procurement directors, MEE-accredited installation contractors, municipal housing bureau officials, and rare-earth magnet supply specialists. Secondary validation drew from customs trade data, SAMR equipment certification databases, and eastern seaboard industrial zone production statistics. Bottom-up channel volume estimates triangulated against top-down policy mandate targets.
Variance decomposition across product type, technology tier, end-user category, and installation channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from replacement cycle compression rates in aging urban residential blocks and first-time electrification adoption curves in southern provinces. Seasonal performance factor compliance thresholds and refrigerant chemistry transition timelines served as industry-specific forecast inputs.
Material uncertainties — rare-earth export quota revisions, municipal carbon-accounting rule expansions, and R290 refrigerant safety code amendments — sit outside the modeled envelope. Forecasts reflect assumptions regarding subsidy continuity and inverter technology cost curves. Recalibration cycles align with material shifts in MIIT efficiency standard enforcement and provincial clean heating fiscal allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Compressor Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
HVAC Actuators Market