
 US Residential Furnace Market | 2026-2036
US Residential Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
US Residential Furnace Market Intelligence
Buyer concentration among single-family developers and large regional HVAC contractors is hardening across the US residential furnace landscape. Carrier leverages its extensive dealer network and brand recognition to sustain premium positioning in replacement markets. Rheem Manufacturing anchors its competitive stance through manufacturing scale and broad fuel-type coverage across natural gas and electric lines. Goodman competes aggressively on price-point accessibility while maintaining distribution through national wholesale channels.
A residential furnace is a forced-air heating appliance designed to generate and distribute warmed air through ductwork, typically achieving Annual Fuel Utilization Efficiency ratings from 80% to over 98% in condensing models, with heat output measured in British Thermal Units per hour. Its primary purpose is to maintain thermal comfort and indoor air quality in detached and attached dwellings during cold seasons. Gas furnaces dominate installed base and replacement volume, though electric furnace demand accelerates in regions with grid-decarbonization commitments and limited natural gas infrastructure. The replacement installation category generates the majority of revenue flow, as the US housing stock ages and DOE efficiency mandates render older units non-compliant.
DOE furnace efficiency standards, EPA emissions guidelines, and regional building codes governed by state-level energy commissions shape product design cycles and market access requirements across the United States. NHTSA and DOT regulations indirectly influence supply chain logistics and equipment transport standards for furnace distribution. Stakeholders must monitor state-level electrification mandates and utility rebate structures, as these policy levers increasingly determine fuel-type selection and installation economics in key metropolitan markets.
Market Dynamics
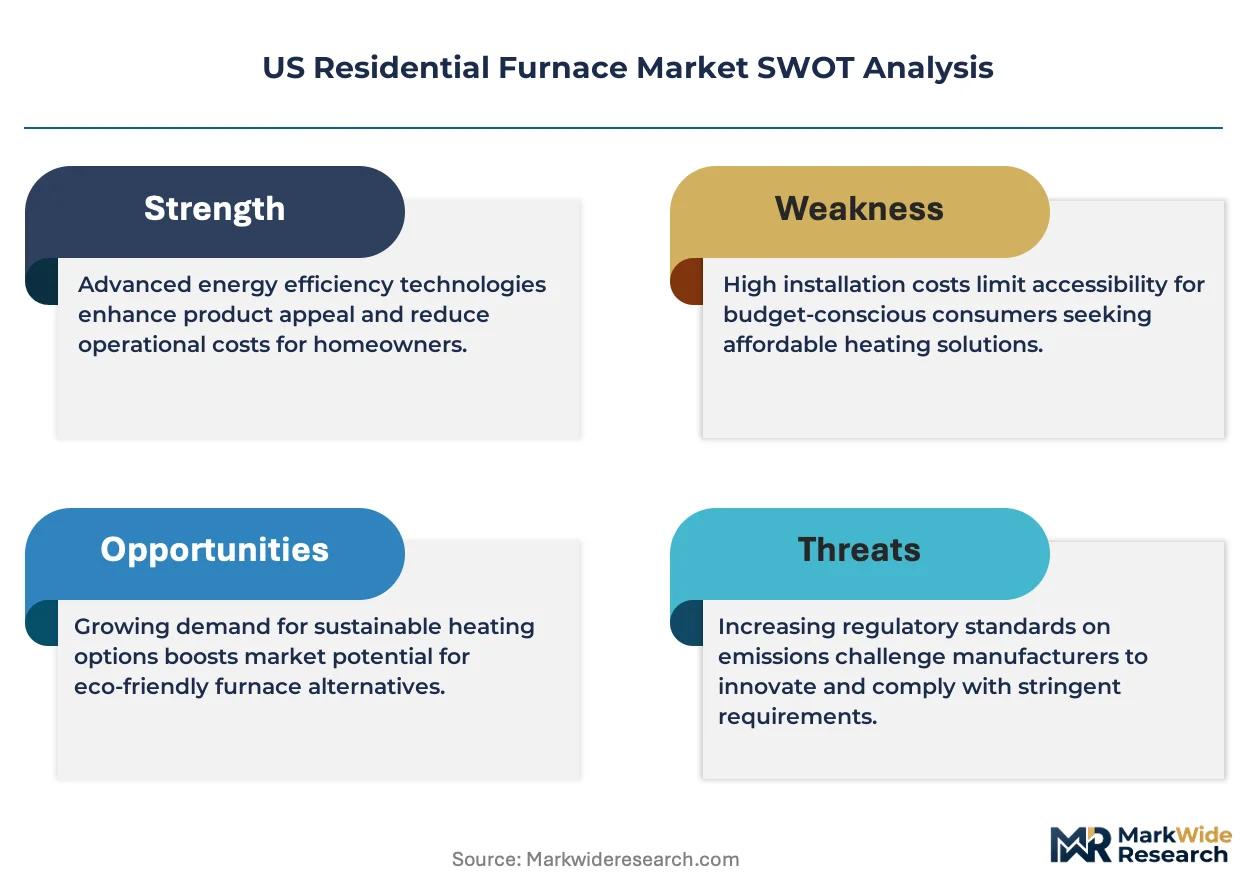
DOE furnace efficiency standards are compressing replacement cycles across the US housing stock while forcing condensing heat-exchanger adoption. Single-family homeowners now face non-compliance exposure on aging 80% AFUE units.
Growth Catalysts
- State-level electrification mandates:California and New York utility rebate structures accelerate electric furnace installations in grid-decarbonization corridors.
- Aging housing stock replacement:Midwest and Northeast cold-climate zones drive forced-air system turnover as 15-20 year equipment lifespans expire.
- Condensing technology maturation:Secondary heat-exchanger designs now achieve 98% AFUE ratings, satisfying tightened federal minimums.
Market Restraints
- Natural gas infrastructure lock-in:Pipeline availability in established Midwest neighborhoods limits fuel-switching economics for electrification.
- Steel and copper input volatility:Heat-exchanger fabrication costs fluctuate with commodity pricing, pressuring manufacturer margins.
- Heat pump substitution threat:Cold-climate air-source heat pumps displace furnace-only solutions in moderate heating-load zones.
Strategic Opportunities
- DOE efficiency standard non-compliance window:Regional HVAC contractors capture replacement demand from homeowners with pre-2015 furnaces facing retrofit requirements.
- Smart thermostat convergence:Variable-speed blower integration with connected home platforms creates premium upgrade paths.
- Utility demand-response programs:Grid-interactive furnace controls open recurring revenue streams through wholesale power market participation.
Industry Challenges
- EPA Section 608 technician certification:Refrigerant handling credentials complicate workforce scaling for heat-pump-furnace hybrid installations.
- Legacy ductwork compatibility:Existing plenum dimensions and airflow rates constrain high-efficiency unit retrofit without full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Residential Furnace Market |
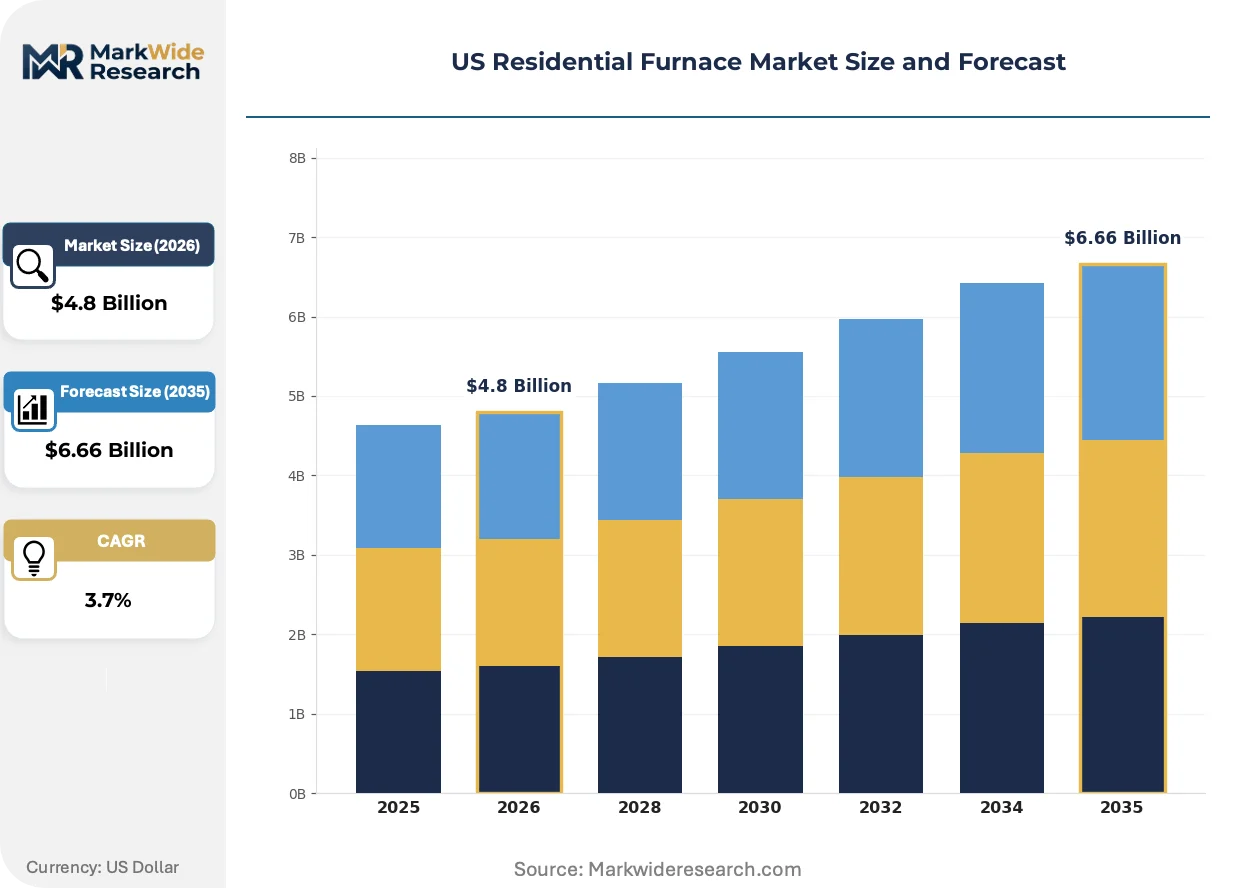
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Furnace, Electric Furnace, Oil Furnace, Propane Furnace, Multi-Fuel Furnace Fuel Type: Natural Gas, Electricity, Diesel, Propane, Biomass Installation Type: New Installation, Replacement, Retrofit, Upgrade End User: Single-family Homes, Multi-family Units, Manufactured Houses, Vacation Houses |
| Companies Covered | American Standard, Rheem Manufacturing, Carrier, Daikin, Goodman, Trane Technologies, Bryant, Amana, Lennox International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Residential Furnace Market Strategic Shifts & Innovations
Equipment design is compressing around modularity and connectivity, with regulatory pressure forcing faster product cycles than historical 10-year replacement patterns allowed.
Variable-capacity gas valves paired with ECM blower motors is modularizing furnace architecture. Single-family replacement buyers in the Northeast adopt staged-combustion units at accelerated rates. This modularity is compressing the premium-economy price gap while enabling zone-control retrofits without full system replacement.
The Department of Energy's 2023 furnace efficiency standards triggered non-condensing unit phaseouts. Manufacturers now engineer exclusively around sealed-combustion, direct-vent configurations. Cold-climate states with aging basements face installation cost inflation as atmospheric-venting equipment exits the market.
Homeowner buying patterns now favor bundled HVAC-system replacement over component-level repair. Regional contractors displace independent installers through financing-integrated proposals. This concentration is most visible in Midwest metropolitan markets where utility rebate administration requires certified installer networks.
US Residential Furnace Market Segmentation
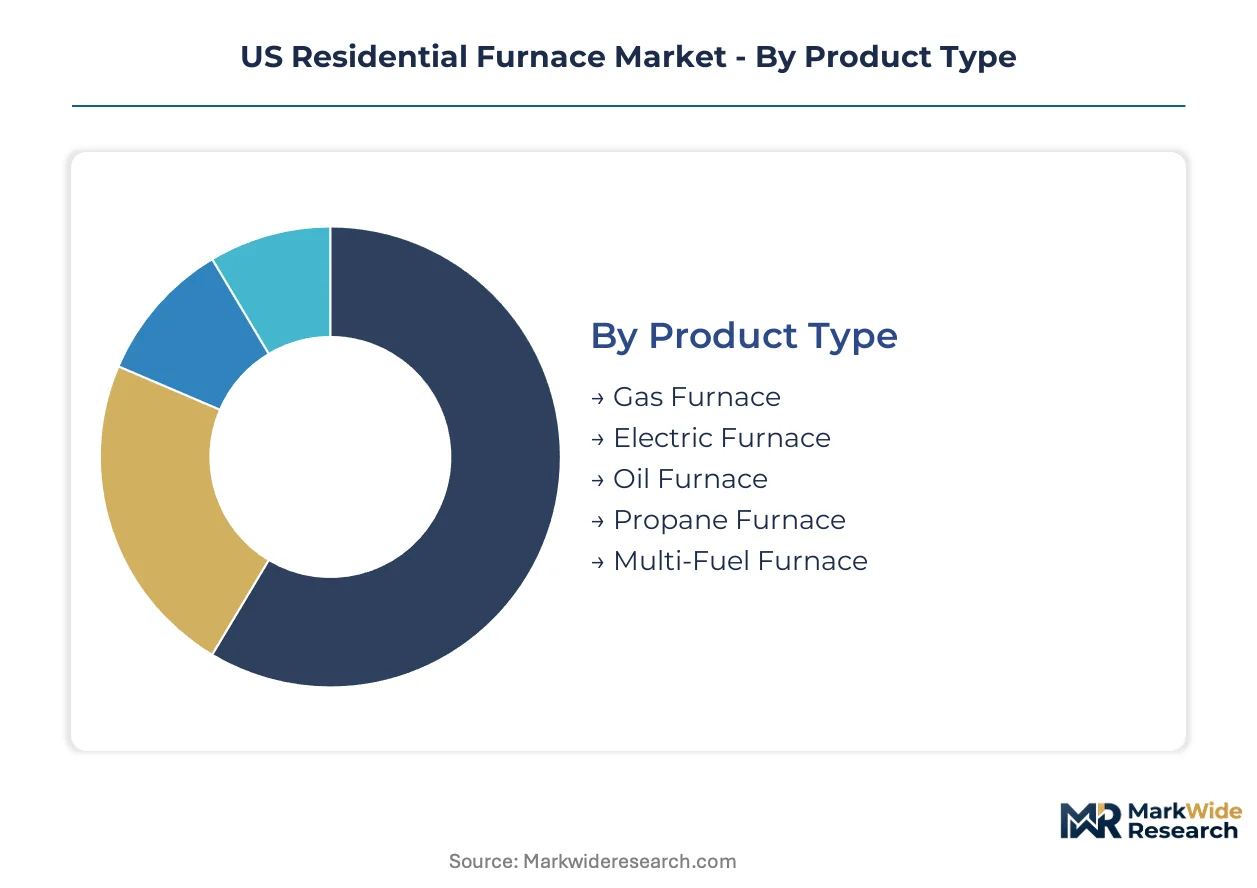
Segmentation in the US residential furnace market reveals how DOE efficiency mandates, fuel infrastructure availability, and housing stock age create divergent compliance burdens and replacement economics across buyer categories. Understanding these splits allows manufacturers to align product development with the specific certification and installation requirements governing each segment.
Product Type:
Gas furnaces carry EPA emissions compliance obligations under Clean Air Act stationary source guidelines, while electric models face state-level electrification mandates and utility interconnection standards. Oil and propane units trigger additional storage tank regulations under OSHA and DOT hazardous materials rules.
- Gas Furnace:Sealed-combustion designs with condensing heat exchangers achieve 98% AFUE ratings under DOE's tightened standards. Midwest single-family replacement markets concentrate demand as atmospheric-venting units face forced retirement.
- Electric Furnace:Resistive heating elements paired with ECM blower motors serve grid-decarbonization corridors in California and New York where utility rebates offset higher operating costs. Cold-climate performance limitations constrain penetration in northern tier states.
- Oil Furnace:Cast-iron heat exchangers and retention-head burners persist in rural Northeast markets lacking natural gas pipeline access. Above-ground tank regulations drive replacement cycles independent of equipment failure.
- Propane Furnace:Modulating gas valves accommodate variable heating loads in vacation homes and manufactured housing with limited thermal mass. DOT cylinder transport rules complicate fuel logistics.
- Multi-Fuel Furnace:Convertible burner systems switch between natural gas and propane without orifice replacement, serving rural subdivisions with uncertain pipeline extension timelines.
Leading the category by volume: Gas Furnace. Growing fastest: Electric Furnace.
Fuel Type:
Cost tier differentiation separates pipeline-connected natural gas from delivered fuels requiring storage infrastructure and periodic resupply logistics.
- Natural Gas:Pipeline distribution networks in established Midwest and Northeast metropolitan areas anchor the lowest per-therm heating costs. Local distribution company infrastructure extension moratoria in some jurisdictions cap addressable market growth.
- Electricity:Grid-interactive controls enable demand-response revenue streams through FERC-regulated wholesale power markets. Time-of-use rate structures in decarbonization states reshape operating economics.
- Diesel:Backup generator fuel compatibility and off-grid reliability sustain niche demand in remote Alaska and mountain West locations. EPA non-road diesel sulfur standards affect burner maintenance intervals.
- Propane:Above-ground tank leasing models reduce upfront capital barriers for manufactured housing and rural single-family construction. Regional supply disruptions during agricultural drying seasons create price volatility.
- Biomass:Wood pellet and corn-burning furnaces qualify for USDA rural energy assistance programs in agricultural counties. Ash handling and emissions testing requirements limit urban deployment.
Dominant by installed base: Natural Gas. Steepest expansion trajectory: Electricity.
Installation Type:
Application maturity varies from new construction specifications to legacy system compatibility challenges in aging housing stock.
- New Installation:Integrated HVAC design with Manual J load calculations and duct sizing optimizes system efficiency from construction. Builder-grade specifications favor 80% AFUE units in markets without local efficiency mandates.
- Replacement:Forced-air system turnover dominates revenue flow as 15-20 year equipment lifespans expire across Midwest and Northeast cold-climate zones. DOE non-compliance exposure on pre-2015 units accelerates decision timelines.
- Retrofit:Existing plenum dimensions and airflow rates constrain high-efficiency unit installation without full ductwork modification. Regional contractors capture margin through financing-integrated proposals.
- Upgrade:Variable-speed blower integration with smart thermostat platforms creates premium paths for connected home convergence. Utility rebate administration requires certified installer networks.
Highest volume category: Replacement. Fastest-growing application: Upgrade.
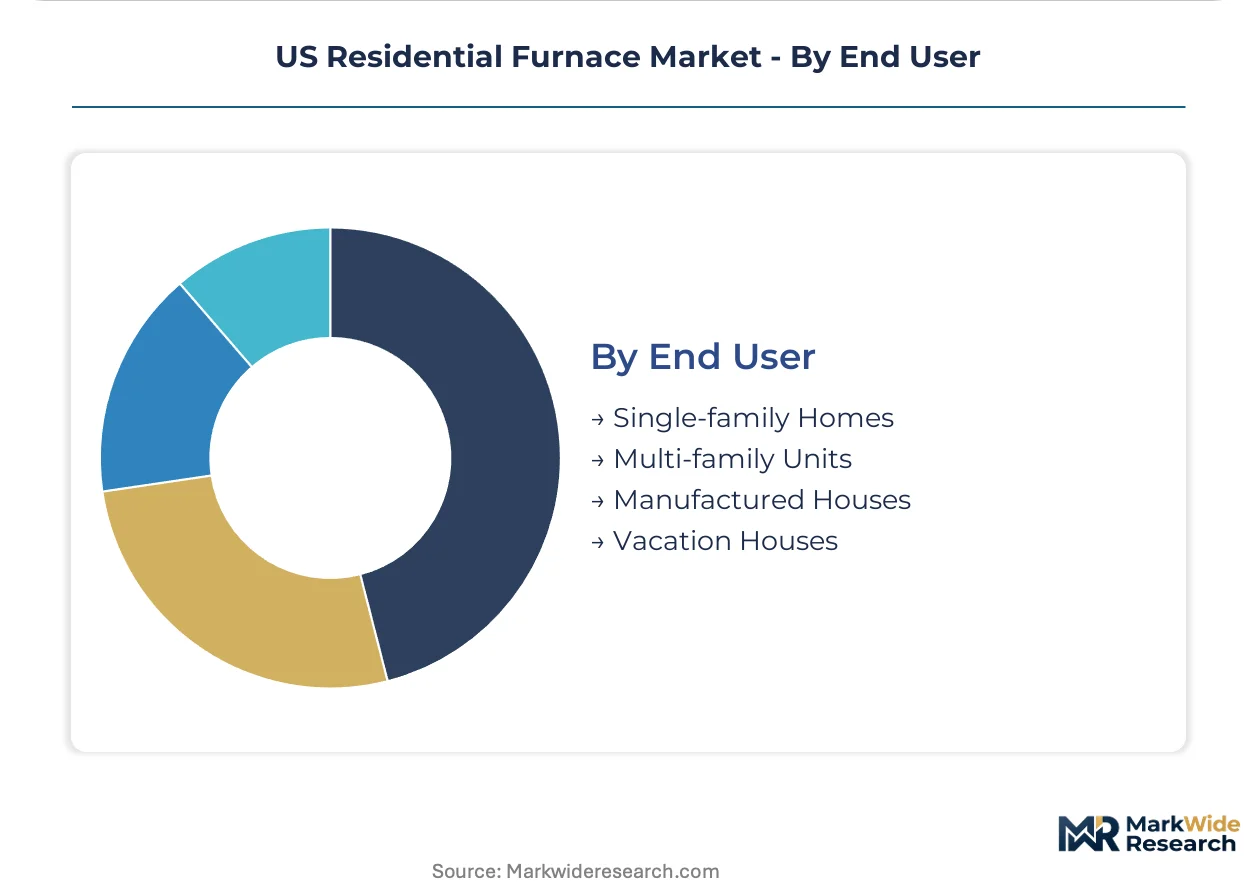
End User:
Customer type determines batch size, specification authority, and financing structure across the housing spectrum.
- Single-family Homes:Owner-occupied detached dwellings generate replacement demand through individual decision-making with full efficiency upgrade incentives. Aging baby boomer housing stock in suburban counties drives turnover concentration.
- Multi-family Units:Central boiler and individual furnace hybrid systems split capital and operating cost responsibilities between landlords and tenants. HUD energy conservation standards govern federally assisted properties.
- Manufactured Houses:HUD Code construction standards limit furnace dimensional compatibility and combustion air requirements. Factory installation reduces field labor cost but constrains aftermarket specification flexibility.
- Vacation Houses:Intermittent occupancy patterns favor programmable setback controls and freeze protection over continuous operation efficiency. Propane and electric resistance dominate where pipeline gas is unavailable.
Largest addressable market: Single-family Homes. Expanding most quickly: Multi-family Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in cold-climate states where aging housing stock and DOE efficiency mandates force replacement cycles. The Midwest and Northeast generate the majority of volume, though regional variations in fuel infrastructure and electrification policy create divergent growth trajectories.
Midwest
Ohio, Michigan, and Illinois anchor replacement demand as 15-20 year furnace lifespans expire across suburban counties. EPA emissions guidelines and state-level energy commission rules enforce condensing unit adoption. The Chicago metropolitan corridor sees concentrated contractor activity as atmospheric-venting equipment faces forced retirement.
Northeast
New York and Massachusetts drive electric furnace acceleration through utility rebate structures aligned with grid-decarbonization commitments. DOE furnace efficiency standards compress decision timelines for pre-2015 unit owners. The Boston-Providence corridor exhibits bundled HVAC-system replacement patterns favoring certified installer networks.
Southeast
Florida and Georgia show rising heat-pump-furnace hybrid installations as cold-climate air-source technology improves. Regional building codes governed by state energy commissions lag northern efficiency mandates. The Atlanta metropolitan area experiences contractor consolidation through financing-integrated proposals.
Southwest
Texas and Arizona exhibit propane and electric resistance dominance where natural gas pipeline extension remains uneconomical. Above-ground tank regulations under OSHA and DOT rules drive independent replacement cycles. The Dallas-Fort Worth metroplex shows manufactured housing furnace turnover concentration.
Pacific Coast
California's electrification mandates accelerate electric furnace installations in grid-decarbonization corridors, though cold-climate performance limitations constrain northern tier penetration. Utility demand-response programs through FERC-regulated wholesale power markets create grid-interactive revenue opportunities. The Los Angeles basin sees premium connected-home convergence with variable-speed blower integration.
US Residential Furnace Market Key Industry Players
Midwestern producers anchor the replacement-tier supply base; southern specialists hold distribution advantages in new construction channels. The vendor base concentrates around three tiers differentiated by dealer network depth and certification requirements. Strategic archetypes include national wholesale-anchored price competitors, premium brand-recognized dealers, and regional scale manufacturers. Dominant competitive moves center on certified installer network expansion and utility rebate program capture.
Within the premium-tier vector, Carrier and Trane Technologies occupy positions defined by dealer network density and brand recognition in replacement markets. Rheem Manufacturing represents the scale-driven archetype through broad fuel-type coverage across natural gas and electric lines. Goodman anchors the price-accessibility tier with national wholesale channel penetration. These three companies exemplify how certification requirements and financing integration increasingly determine competitive positioning.
| Leading Market Players |
|---|
| American Standard |
| Rheem Manufacturing |
| Carrier |
| Daikin |
| Goodman |
| Trane Technologies |
| Bryant |
| Amana |
| Lennox International |
| Others |
Cost & Logistics Intelligence
Steel and copper commodity benchmarks cascade through furnace manufacturing tiers, compressing margins on economy-grade units while premium condensing models absorb volatility through brand-premium pricing power. Midwestern foundry concentration and EPA emissions compliance costs stratify final pricing across certified installer networks.
Pricing Analysis
Volume concentrates in replacement-grade 80-92% AFUE units where contractor procurement drives thin margins, while premium 96-98% condensing systems sustain markup through DOE compliance scarcity and smart-thermostat bundling. Price differentiation hinges on certification tier (EPA Section 608 technician credentials, NATE accreditation) and regional utility rebate capture. Pricing pressure stems from steel heat-exchanger fabrication cost volatility pressuring manufacturer margins. Single-family homeowners in cold-climate zones show highest price sensitivity, while multi-family property managers prioritize lifecycle operating cost over upfront capital.
Supply Chain Analysis
Domestic-content mandates under Buy America provisions reshape heat-exchanger sourcing toward US-based foundry operations in Ohio and Indiana. Manufacturing concentrates in the United States, Mexico, and China, with cast-iron components and ECM blower motors drawing from established Midwest supplier clusters. Raw material dependencies center on cold-rolled steel, copper tubing, and aluminum coil stock. Supply chain risk rests on single-source vulnerability for variable-capacity gas valve assemblies. Distribution runs through national wholesale channels (Ferguson, Watsco) into certified dealer networks requiring NATE accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contractor certification bottlenecks constrain installation capacity, propping replacement pricing as DOE efficiency mandates compress decision timelines for pre-2015 unit owners.
For Market Incumbents: Anchor dealer network density in Midwest metropolitan corridors where atmospheric-venting retirements accelerate. Deepen backward integration into ECM blower motor production to offset commodity volatility. Defend against cold-climate heat pump substitution by bundling furnace-thermostat connectivity packages through utility demand-response programs. For New Entrants and Emerging Players: Begin with electric furnace white-space in California and New York grid-decarbonization corridors where utility rebates offset higher operating costs. Target manufactured housing segments constrained by HUD Code dimensional limits that exclude established OEM product lines. Pursue certified installer network partnerships rather than direct wholesale channel competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional scale manufacturers with NATE-accredited installer networks in Michigan and Illinois suburban counties. Long-term viability centers on electrification-mandate exposure and condensing technology transition completion. Watch FERC grid-interactive control standardization as inflection signal for recurring revenue model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | NATE accreditation requirements under EPA Section 608 concentrate replacement volume through qualified contractors. |
| Backward Integration into ECM Motors | In-house production of variable-speed blower assemblies insulates margins from copper and rare-earth price volatility. |
| Utility Rebate Program Capture | California and New York decarbonization corridors channel electric furnace demand through certified installer networks. |
| Condensing Heat-Exchanger Scale-Up | DOE 2023 efficiency standards force atmospheric-venting phaseout, concentrating 98% AFUE production investment. |
| Smart Thermostat Platform Integration | Variable-speed blower convergence with connected-home platforms creates premium upgrade paths beyond commodity replacement. |
Research Approach
DOE efficiency standard filings, EPA emissions compliance databases, and FERC grid-interactive control dockets formed the secondary backbone. Primary interviews with HVAC contractor operations managers, regional distributor procurement leads, NATE certification administrators, and utility rebate program administrators validated demand-side assumptions. Bottom-up and top-down triangulation cross-referenced equipment shipment data against housing stock age distributions and replacement cycle modeling.
Bottom-up modeling tracked unit shipments by AFUE tier, fuel type, and installation category across the projection horizon. Segmentation dimensions included product type (gas, electric, oil, propane, multi-fuel), end user (single-family, multi-family, manufactured housing, vacation homes), and installation type (new, replacement, retrofit, upgrade). CAGRs derived from housing stock turnover rates, DOE compliance deadline impacts, and state-level electrification mandate adoption curves. Forecast inputs incorporated steel and copper commodity price scenarios alongside utility rebate program expansion trajectories.
Underlying measurement precision varies by segment; replacement installation volumes carry tighter precision than new construction forecasts given established equipment lifespan data. Forecasts reflect assumptions on electrification mandate adoption speed, heat pump substitution rates, and commodity price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Duct Fans Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
India Chillers Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
North America Commercial HVAC Market