
 Air-Conditioning Natural Convection Refrigerator Market | 2026-2036
Air-Conditioning Natural Convection Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Conditioning Natural Convection Refrigerator Market Insights
The gap between vapor compression and thermoelectric cooling architectures is narrowing as solid-state modules achieve coefficient-of-performance parity in sub-500-liter enclosures. Samsung leverages in-house semiconductor fabrication to control thermoelectric element costs across its Southeast Asian production network. Haier anchors its competitive stance through backward integration into compressor manufacturing, while Midea specializes in absorption-cycle variants for off-grid commercial deployments.
An air-conditioning natural convection refrigerator employs passive airflow circulation—driven by density differentials rather than forced fans—to maintain uniform temperature distribution across refrigerated compartments, typically operating at 2°C to 8°C for fresh-food preservation with defrost cycles managed through heater-wire or hot-gas injection systems. French door configurations command the widest margin pools in residential channels due to compartmentalization complexity and premium positioning, while absorption technology leads in industrial off-grid segments where electrical infrastructure remains unreliable. Top freezer designs retain volume dominance in developing markets through manufacturing simplicity and repair accessibility.
EPA SNAP regulations in the United States restrict high-global-warming-potential hydrofluorocarbon refrigerants, compelling manufacturers to reformulate cooling loops around R-600a or R-290 hydrocarbons. Ecodesign requirements under the EU F-Gas Regulation mandate minimum energy efficiency indices that natural convection systems must satisfy to access European markets. Stakeholders must monitor refrigerant-phase-down schedules and test-protocol harmonization between EPA and ECHA frameworks to avoid stranded certification investments.
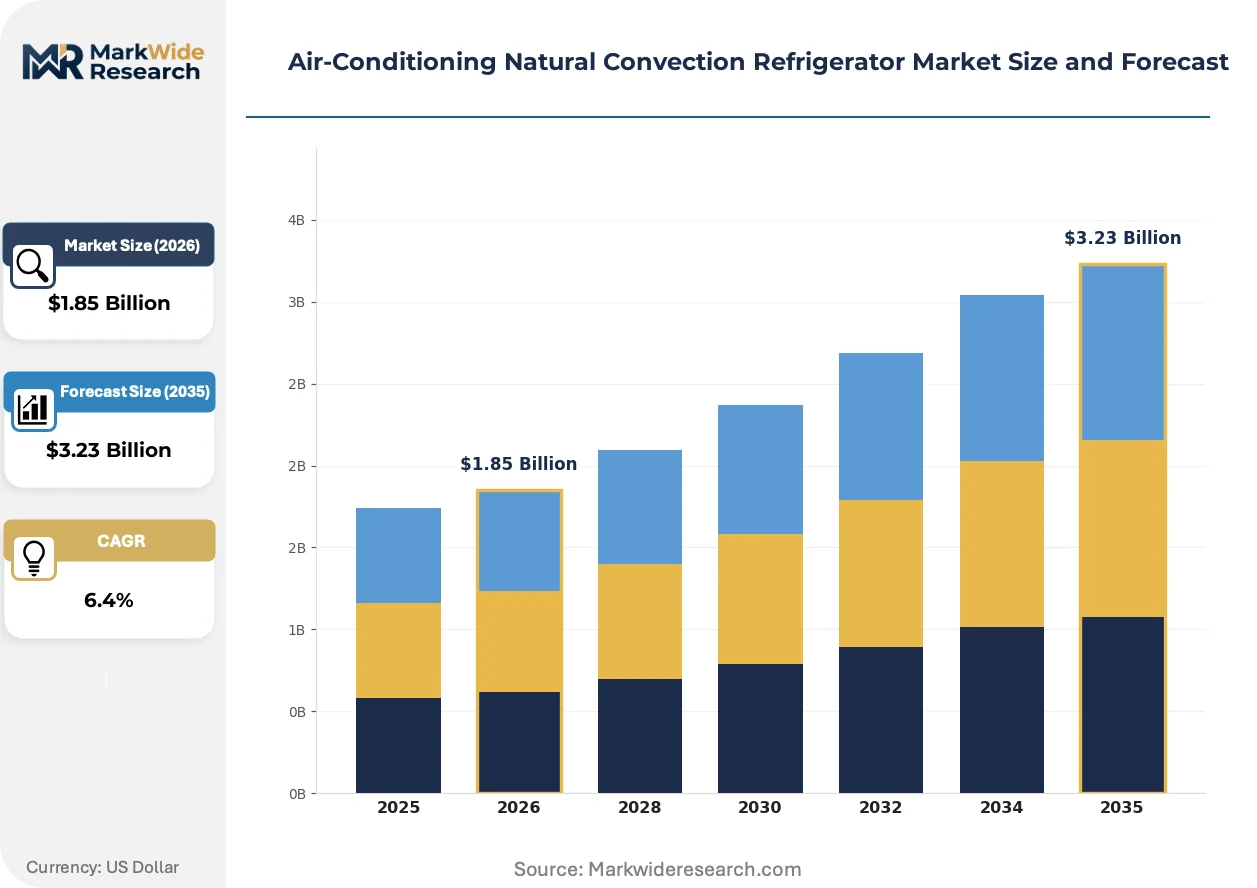
Market Dynamics
Passive cooling architectures face intensifying pressure from hydrocarbon refrigerant phase-down mandates across Southeast Asian manufacturing zones, forcing absorption-cycle suppliers to revalidate thermal performance under R-600a and R-290 formulations.
Growth Catalysts
- EU F-Gas Regulation:Ecodesign minimum energy efficiency indices for natural convection systems create compliance-driven replacement cycles in European cold-chain infrastructure, pulling mid-tier manufacturers toward certified product lines.
- Commercial hospitality expansion:Hotel and restaurant operators in Vietnam's urban corridor are scaling cold-storage capacity ahead of tightened national energy-efficiency mandates, prioritizing absorption technology for kitchen deployments.
- Hydrocarbon cooling loops:R-600a and R-290 formulations narrow performance gaps between premium and mid-tier product tiers, enabling specification upgrades without full system redesign.
Market Restraints
- Copper-aluminum alloy volatility:Heat exchanger material costs fluctuate with commodity markets, compressing margin pools for manufacturers lacking long-term supply contracts.
- Indonesian component concentration:Java-based manufacturing belts dominate compressor and coil sourcing, creating geographic single-point vulnerability for regional supply chains.
- Thermoelectric performance ceiling:Solid-state modules remain coefficient-of-performance constrained above 500-liter enclosures, limiting addressable market in commercial-scale deployments.
Strategic Opportunities
- Off-grid commercial segments:Absorption-cycle variants serve industrial deployments across Indonesian archipelago islands where electrical infrastructure reliability remains inconsistent, opening service-contract revenue streams.
- EPA SNAP refrigerant pathways:US hydrofluorocarbon restrictions create export certification arbitrage for Southeast Asian manufacturers already producing R-600a compliant systems.
- Hot-gas defrost integration:Convergence of passive airflow circulation with heater-wire alternatives enables frost-management without forced-fan energy penalties, appealing to net-zero building specifications.
Industry Challenges
- Refrigerant-handling certification gaps:Hydrocarbon-based cooling loops require specialized technician training that remains scarce in Vietnam's service networks, delaying installation capacity scaling.
- EPA-ECHA test-protocol divergence:Harmonization gaps between American and European certification frameworks force duplicate validation investments, straining R&D budgets for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Conditioning Natural Convection Refrigerator Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Freezer, Bottom Freezer, Side-by-Side, French Door End User: Residential, Commercial, Industrial, Hospitality Technology: Vapor Compression, Thermoelectric, Absorption, Hybrid Distribution Channel: Online Retail, Specialty Store, Hypermarket, Distributors |
| Companies Covered | Whirlpool, Samsung, LG, Electrolux, Haier, Panasonic, Midea, BSH, Hisense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Conditioning Natural Convection Refrigerator Market Trends and Innovations
Passive thermal management architectures are absorbing semiconductor and materials-science advances that were originally developed for active cooling systems, blurring traditional performance boundaries between forced-air and natural convection approaches.
Thermoelectric solid-state modules are migrating from laboratory instrumentation into sub-500-liter fresh-food preservation enclosures. Boutique hotel operators in Thailand's resort corridors specify these units for premium villa deployments where acoustic signature matters. The technology is migrating from niche positioning toward mid-volume commercial channels as in-house semiconductor fabrication reduces element cost structures.
EPA SNAP regulations restrict high-global-warming-potential hydrofluorocarbon refrigerants across United States commercial cold-chain equipment. Manufacturers reformulate cooling loops around R-600a or R-290 hydrocarbons to maintain market access. French door configurations face the steepest compliance costs due to compartmentalization complexity and refrigerant charge volume scaling.
After-sales service unbundling accelerates across Indonesian manufacturing belt procurement offices. Buyers separate equipment acquisition from maintenance contracts, pitting independent service networks against manufacturer-captive technicians. This pattern concentrates in Java-based food processing clusters where multi-vendor cold rooms complicate single-source service commitments.
Air-Conditioning Natural Convection Refrigerator Market Segmentation
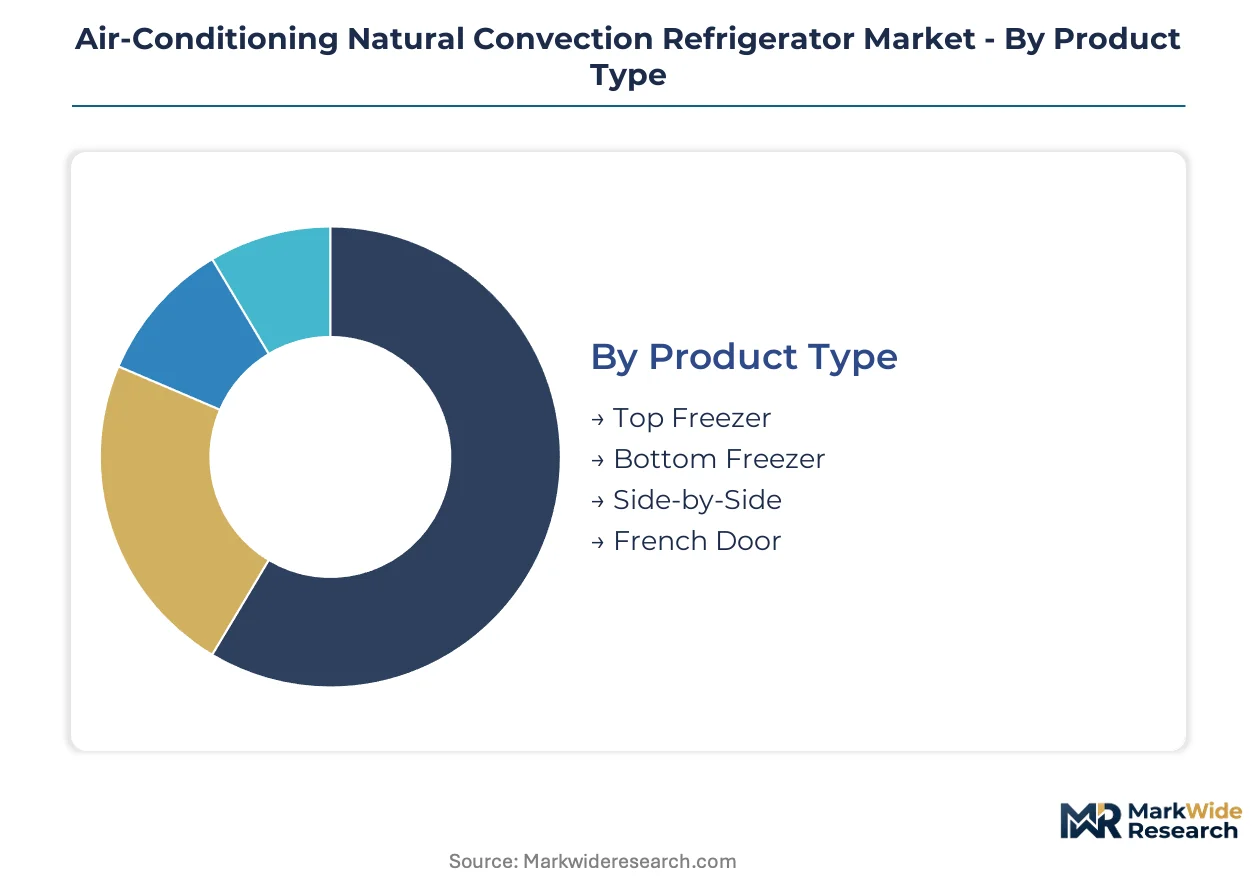
Segmentation in air-conditioning natural convection refrigerators reveals how passive cooling architectures align with distinct operational requirements, procurement patterns, and regulatory exposure across product configurations, end-use environments, and technology platforms.
Product Type:
Replacement cycles vary dramatically across configurations, with commercial installations turning over every 7-10 years while residential units average 12-15 year lifespans.
- Top Freezer:Simple two-chamber design with freezer compartment above fresh-food zone, utilizing single evaporator coils and minimal electronic control systems. Manufacturing concentrates in Indonesia's Java-based production belts where component standardization supports repair accessibility and margin preservation for mid-tier suppliers.
- French Door:Multi-compartment configuration with side-by-side upper doors and bottom freezer drawer, requiring complex refrigerant distribution networks and precision temperature zoning. Boutique hotel operators across Vietnam's urban corridor specify these units for premium kitchen deployments where compartmentalization complexity justifies acquisition premiums.
- Bottom Freezer:Ergonomic configuration placing fresh food at eye level with pull-out freezer drawer below, popular in aging-population demographics.
- Side-by-Side:Vertical split design offering narrow door swing clearance for constrained kitchen footprints, common in Southeast Asian high-rise residential towers.
Top Freezer dominates installed base across developing markets. French Door is where expansion concentrates in premium commercial channels.
End User:
Procurement authority and specification complexity diverge sharply between owner-operated installations and third-party managed facilities.
- Commercial:Food service operators, retail grocers, and institutional cafeterias requiring continuous temperature documentation and HACCP compliance protocols. Restaurant chains across Thailand's resort corridors prioritize absorption-cycle variants for kitchen reliability where electrical infrastructure consistency varies seasonally.
- Hospitality:Hotels, resorts, and cruise operators demanding acoustic signature minimization and aesthetic integration with interior design schemes. Villa operators in Bali and Phuket specify thermoelectric solid-state modules for guest room minibars where fan noise compromises sleep quality ratings.
- Residential:Individual households purchasing through retail channels with energy efficiency labels and purchase price as primary decision factors.
- Industrial:Food processing plants, pharmaceutical cold storage, and logistics hubs requiring specialized temperature ranges and backup redundancy systems.
Commercial holds the largest active fleet population. Hospitality is expanding most quickly as tourism infrastructure scales across Southeast Asian archipelago destinations.
Technology:
Capital intensity and operating cost structures create distinct total-cost-of-ownership profiles that reshape competitive positioning across end-use segments.
- Absorption:Heat-driven cooling cycle using ammonia-water or lithium bromide solutions, operable on waste heat, natural gas, or electrical resistance. Off-grid industrial deployments across Indonesia's outer islands rely on these systems where diesel generator dependency creates fuel cost volatility and reliability risk.
- Vapor Compression:Mechanical refrigeration cycle using compressor-driven refrigerant phase change, dominant in grid-connected applications with superior coefficient-of-performance metrics. EPA SNAP compliance pressures are accelerating hydrocarbon refrigerant transitions from R-134a to R-600a formulations.
- Thermoelectric:Solid-state Peltier modules generating temperature differential through electrical current, eliminating moving parts and refrigerant handling entirely. Sub-500-liter enclosures in acoustic-sensitive environments drive current adoption with semiconductor cost curves enabling mid-volume commercial migration.
- Hybrid:Combined architectures switching between vapor compression and thermoelectric modes based on load conditions and ambient temperature profiles.
Vapor Compression commands installed base dominance. Absorption is gaining share fastest in infrastructure-constrained geographies.
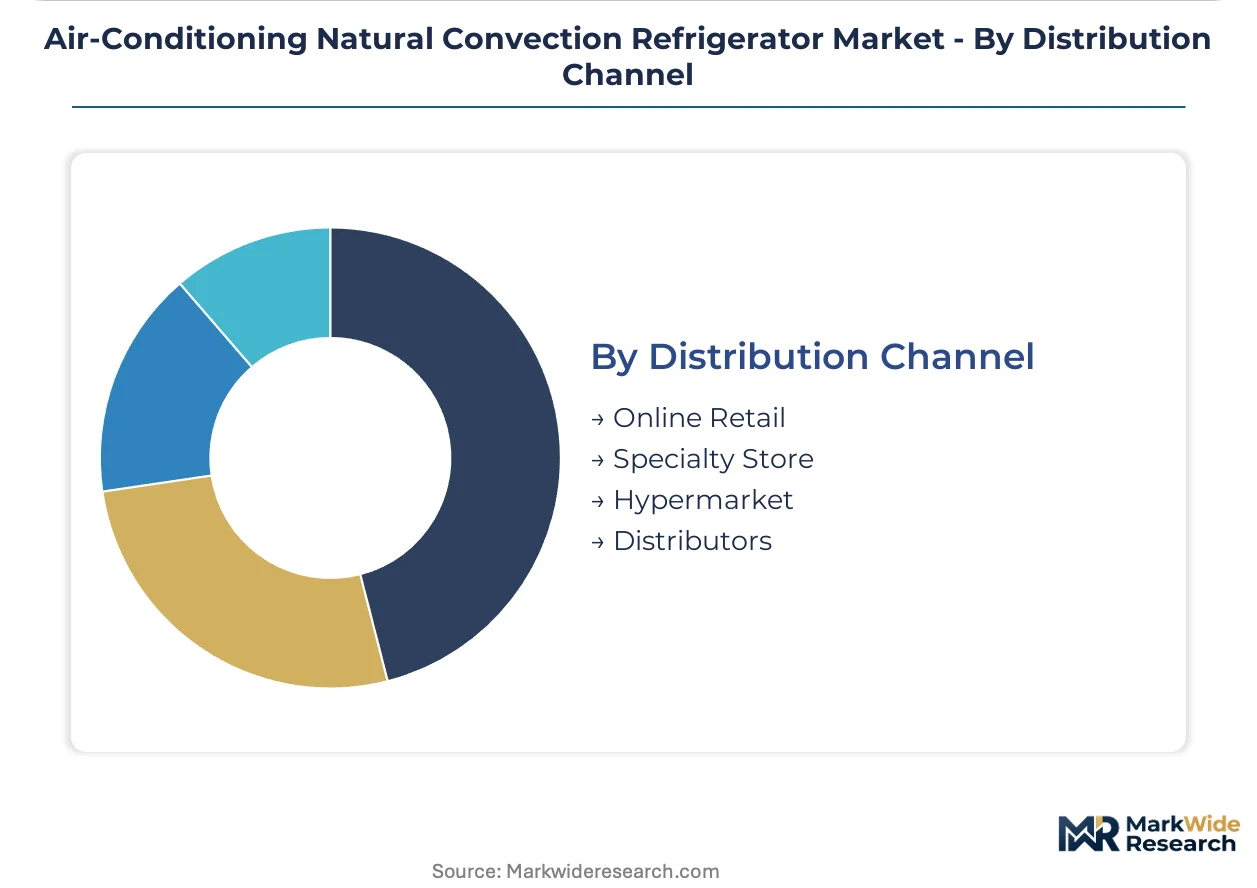
Distribution Channel:
Channel economics and service bundling arrangements determine manufacturer margin capture and end-user total cost structures.
- Distributors:Independent regional networks providing installation, commissioning, and aftermarket service contracts alongside equipment sales. Java-based food processing clusters in Indonesia increasingly unbundle procurement from maintenance, pitting distributor service networks against manufacturer-captive technician programs.
- Specialty Store:Focused retail outlets offering specification consulting, energy efficiency modeling, and customized configuration services for commercial buyers.
- Hypermarket:Mass retail channels emphasizing price transparency, immediate availability, and standardized warranty terms for residential replacement purchases.
- Online Retail:E-commerce platforms with logistics integration for last-mile delivery and digital warranty registration systems.
Distributors retain largest commercial equipment flow. Online Retail is climbing the fastest in residential replacement cycles among urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Java-based manufacturing belt exports compressor assemblies and coil systems to Vietnam's urban corridor, where hospitality operators are expanding cold-storage capacity ahead of tightened national energy-efficiency mandates.
United States
Commercial food service operators and institutional cafeterias drive replacement demand as aging vapor compression systems face EPA SNAP hydrofluorocarbon restrictions. The EPA mandates R-600a or R-290 hydrocarbon formulations for new equipment certification. Cold-chain infrastructure concentrates in California's Central Valley agricultural processing zones and Texas's meatpacking corridors.
Germany
Industrial food processors and pharmaceutical cold storage facilities prioritize absorption-cycle reliability under the EU F-Gas Regulation's ecodesign minimum energy efficiency indices. ECHA enforcement of refrigerant-phase-down schedules accelerates hydrocarbon cooling loop validation. Manufacturing and R&D activity clusters in Bavaria's industrial automation belt around Munich and Nuremberg.
Vietnam
Hotel and restaurant operators in Ho Chi Minh City and Hanoi scale kitchen cold-storage deployments ahead of anticipated national energy-efficiency mandates. The country's technical standards body is aligning refrigerant-handling certification requirements with ASEAN harmonization protocols. Absorption technology procurement concentrates in Da Nang's emerging resort corridor.
Indonesia
Off-grid industrial deployments across the outer islands rely on absorption-cycle variants where diesel generator dependency creates fuel cost volatility. The national energy ministry is drafting hydrocarbon refrigerant safety protocols for archipelago logistics. Component manufacturing dominates Java's Bekasi and Tangerang industrial zones.
Thailand
Boutique resort operators in Phuket and Koh Samui specify thermoelectric solid-state modules for premium villa minibars where acoustic signature affects guest satisfaction ratings. The country's industrial standards institute is updating test protocols for sub-500-liter enclosures. Hospitality procurement offices concentrate in Bangkok's Sukhumvit corridor.
Air-Conditioning Natural Convection Refrigerator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: diversified appliance conglomerates with captive semiconductor or compressor fabrication, mid-tier absorption-cycle specialists serving off-grid commercial segments, and emerging solid-state module integrators targeting acoustic-sensitive hospitality deployments. Dominant competitive moves include backward integration into heat exchanger manufacturing and geographic expansion through distributor network unbundling.
Among diversified appliance conglomerates, Samsung Electronics Co., Ltd. and Haier Group Corporation exemplify scale-driven positions with in-house control over critical component costs. LG Electronics Inc. anchors the Korean-origin competitive vector. These entities represent the consolidated tier where manufacturing depth and multi-market certification portfolios create defensive positioning against hydrocarbon refrigerant transition costs.
| Leading Market Players |
|---|
| Whirlpool |
| Samsung |
| LG |
| Electrolux |
| Haier |
| Panasonic |
| Midea |
| BSH |
| Hisense |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Indonesia's Java-based compressor manufacturing belt is compressing component pricing and forcing suppliers toward long-term service contract bundling to defend margin pools. This utilization dynamic creates divergent pricing postures between integrated conglomerates with captive heat exchanger production and mid-tier assemblers exposed to spot-market copper-aluminum alloy volatility.
Pricing Analysis
The technology-generation pricing gap between R-134a legacy systems and R-600a/R-290 hydrocarbon-compliant next-generation units has widened as EPA SNAP certification costs concentrate in French door configurations. Three-tier pricing structure across premium, standard, and economy levels separates absorption-cycle specialists from vapor compression incumbents and thermoelectric solid-state entrants. Price differentiation hinges on refrigerant-handling certification tier and after-sales service bundling intensity. Cost compression in mid-tier vapor compression is intensifying because hydrocarbon transition investments are not yet amortized across production volumes. Commercial hospitality buyers in Vietnam's urban corridor exhibit lowest price sensitivity due to mandate-driven replacement timelines, while residential retail channels in Indonesian hypermarkets remain acutely cost-conscious.
Supply Chain Analysis
Export-control regime restrictions on semiconductor-grade bismuth telluride thermoelectric elements limit solid-state module flows from Chinese fabrication facilities to Southeast Asian integrators. Manufacturing gravity centers on Indonesia's Java belt for compressor assemblies and coil systems, Vietnam's northern industrial zones for cabinet fabrication, and South Korea for precision electronic controls. Raw material dependencies include copper-aluminum heat exchanger alloys, hydrocarbon refrigerant feedstocks, and semiconductor-grade thermoelectric substrates. Single-source vulnerability concentrates in Indonesian compressor sourcing where geographic clustering creates exposure to archipelago logistics disruptions. Distribution runs through captive distributor networks for commercial deployments and unbundled independent channels for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where aftermarket maintenance contracts and refrigerant-handling certification programs are expanding faster than hardware unit economics across Southeast Asian hospitality deployments.
For Market Incumbents: Harden defensive positioning through backward integration into heat exchanger manufacturing and captive refrigerant-handling technician certification programs. Samsung and Haier exemplify scale-driven consolidation through in-house semiconductor and compressor fabrication control. Thermoelectric solid-state entrants threaten vapor compression incumbents in sub-500-liter acoustic-sensitive hospitality segments. Capacity addition in Vietnam's Da Nang corridor anchors regional service network density against Indonesian supply concentration risks.
For New Entrants and Emerging Players: Establish a beachhead in Indonesia's outer-island off-grid industrial segment where absorption-cycle reliability commands service-contract premiums. The most penetrable white-space sits in thermoelectric solid-state modules for Thailand's boutique resort minibars where fan-noise sensitivity overrides first-cost considerations. A go-to-market angle through unbundled distributor service networks in Java-based food processing clusters bypasses incumbent-captive technician programs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermoelectric solid-state sub-500-liter enclosures as semiconductor cost curves enable mid-volume commercial viability. The long-term viability window favors diversified appliance conglomerates with multi-market EPA-ECHA certification portfolios over pure-play absorption-cycle specialists exposed to hydrocarbon refrigerant transition costs. Acquisition target archetypes include mid-tier absorption-cycle specialists with established Indonesian archipelago service networks. The signal to monitor is EPA-ECHA test-protocol harmonization progress that would eliminate duplicate validation investments and revalue multi-certified asset bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Manufacturing | Captive supply of copper-aluminum coil systems insulates margin pools from commodity volatility in Southeast Asian production networks. |
| Hydrocarbon Refrigerant Certification Investment | EPA SNAP and EU F-Gas Regulation compliance unlocks market access across American and European cold-chain infrastructure replacement cycles. |
| Service Contract Unbundling | Independent aftermarket networks in Java-based food processing clusters capture recurring revenue streams separated from equipment procurement. |
| Thermoelectric Solid-State Module Integration | Semiconductor fabrication cost control enables acoustic-sensitive hospitality deployments in Thailand's resort corridors. |
| Archipelago Logistics Partnership | Diesel-generator-dependent outer-island industrial sites in Indonesia require specialized absorption-cycle service coverage. |
Research Methodology
Operator-level perspectives from commercial hospitality procurement managers, refrigeration system maintenance directors, hydrocarbon refrigerant handling technicians, and compressor manufacturing plant engineers anchored the qualitative base. Primary interview insights were cross-validated against secondary sources including EPA SNAP regulatory filings, EU F-Gas Regulation ecodesign documentation, ASEAN technical standards harmonization protocols, and Indonesian national energy ministry hydrocarbon safety drafts. Bottom-up unit economics modeling and top-down macroeconomic scenario triangulation ensured forecast robustness across the analysis window.
Scenario-bracketing framed demand projections across low, baseline, and high penetration assumptions for thermoelectric solid-state adoption in acoustic-sensitive hospitality segments. The analytical framework modeled volume and value outputs across product configuration, end-use environment, technology platform, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs included hydrocarbon refrigerant phase-down schedules and semiconductor thermoelectric element cost curve trajectories.
Stress conditions across copper-aluminum alloy price volatility, Indonesian archipelago logistics disruption frequency, and EPA-ECHA test-protocol divergence duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding mandate implementation timelines and technology cost reduction slopes. Material shifts in hydrocarbon refrigerant safety protocol enforcement stringency or thermoelectric module performance breakthroughs above 500-liter enclosures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Global Air Conditioner Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Equipment for HVAC Market