
 Global VRF System Market | 2026-2036
Global VRF System Market Size, Share, and Industry Trends Forecast 2026-2036
Global VRF System Market Outlook
R32 refrigerant is decoupling VRF product economics from legacy R410A cost structures across Asia-Pacific manufacturing bases. Daikin Industries leverages captive fluorochemical production to sustain margin advantage in heat pump configurations. Mitsubishi Electric anchors its position through inverter compressor R&D intensity in Japan. Midea Group competes on manufacturing scale in multi-zone system exports from Guangdong province.
Variable refrigerant flow systems modulate compressor speed to match real-time thermal loads across multiple indoor units connected to a single outdoor chassis, typically operating with refrigerant capacities between 3 hp and 54 hp per outdoor module. The primary commercial purpose is delivering individualized zone temperature control without centralized air handling ducts. Heat recovery configurations command premium positioning by enabling simultaneous heating and cooling across building zones. Multi-zone system design is accelerating fastest in retrofit installations where existing structures cannot accommodate ductwork. Commercial end users represent the dominant margin pool due to longer replacement cycles and service contract attach rates.
EPA Significant New Alternatives Policy shapes refrigerant selection timelines for US-bound equipment. EMA F-Gas Regulation and Japan METI refrigerant phase-down mandates are compressing product development cycles across export-oriented manufacturers. China's MEE dual carbon goals enforce efficiency benchmarks that favor inverter-driven VRF over conventional split systems. Stakeholders must monitor refrigerant transition cost pass-through mechanics as supply chains rebalance around lower-GWP chemistries.
Market Dynamics
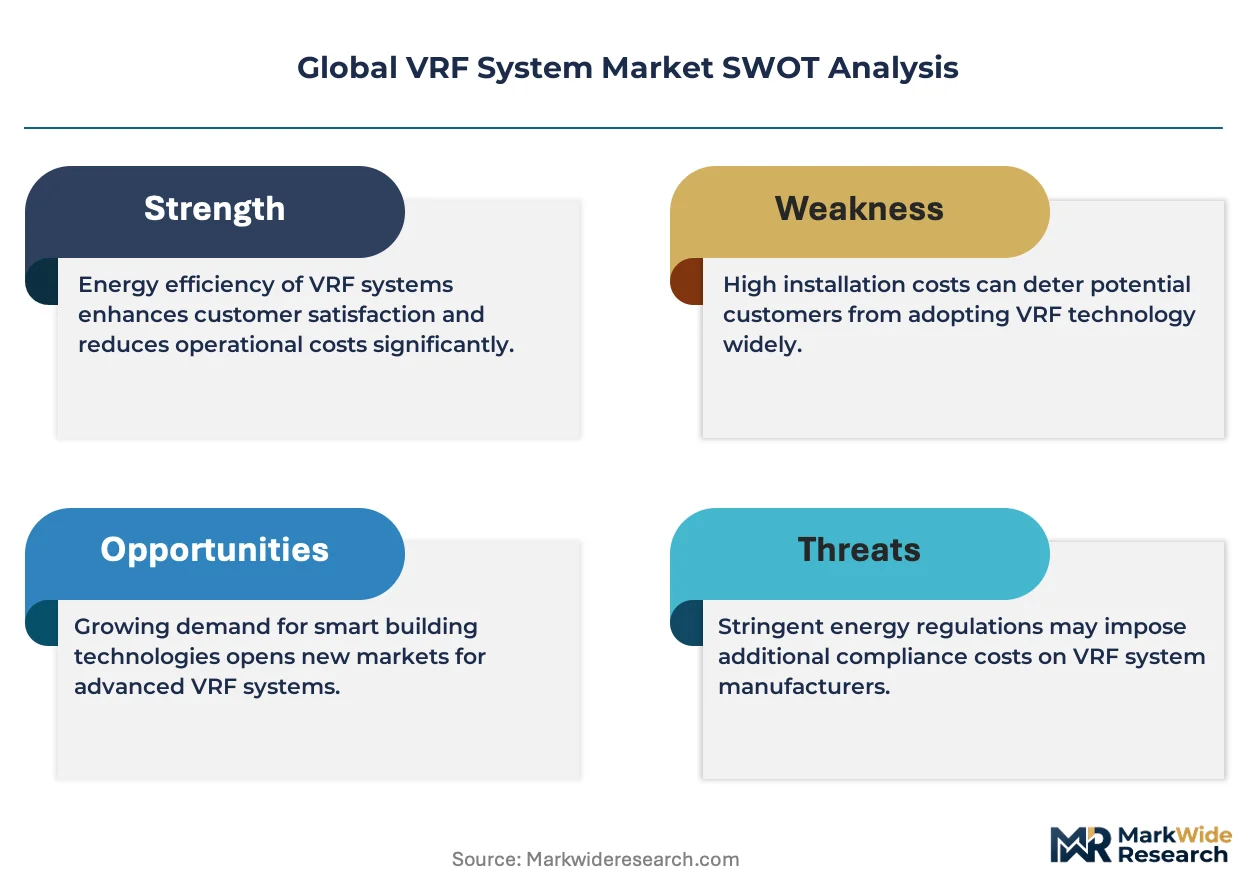
Refrigerant chemistry transitions are compressing product development timelines across VRF manufacturing, forcing simultaneous retooling of compressor architectures, heat exchanger designs, and field service protocols.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-down of high-GWP refrigerants accelerates R32 and R290 platform adoption across European commercial installations.
- Urban commercial construction:Tier-1 cities in India generate concentrated demand for zoned climate control in high-rise office towers and retail complexes.
- Inverter compressor efficiency:Variable-speed modulation technology reduces energy consumption by matching refrigerant flow to real-time thermal loads.
Market Restraints
- Fluorochemical supply concentration:Captive production of next-generation refrigerants limits supplier diversity to Japanese and Chinese chemical conglomerates.
- Retrofit installation complexity:Existing building electrical infrastructure often cannot support multi-zone outdoor unit amperage demands without costly upgrades.
- Heat pump performance degradation:Low-ambient heating efficiency drops constrain deployment in continental climate zones below -15°C.
Strategic Opportunities
- Heat recovery configurations:Simultaneous heating and cooling across building zones commands premium positioning in mixed-use developments.
- Japan METI refrigerant mandates:Accelerated phase-down timelines create first-mover advantage for manufacturers with lower-GWP platforms certified for export.
- Service contract unbundling:Predictive maintenance subscriptions using IoT-enabled diagnostics generate recurring revenue independent of equipment sales.
Industry Challenges
- Refrigerant handling certification:Technician licensing requirements for mildly flammable A2L chemistries lengthen installation crew deployment timelines.
- Legacy control system integration:Proprietary communication protocols between outdoor and indoor units complicate third-party building management system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global VRF System Market |
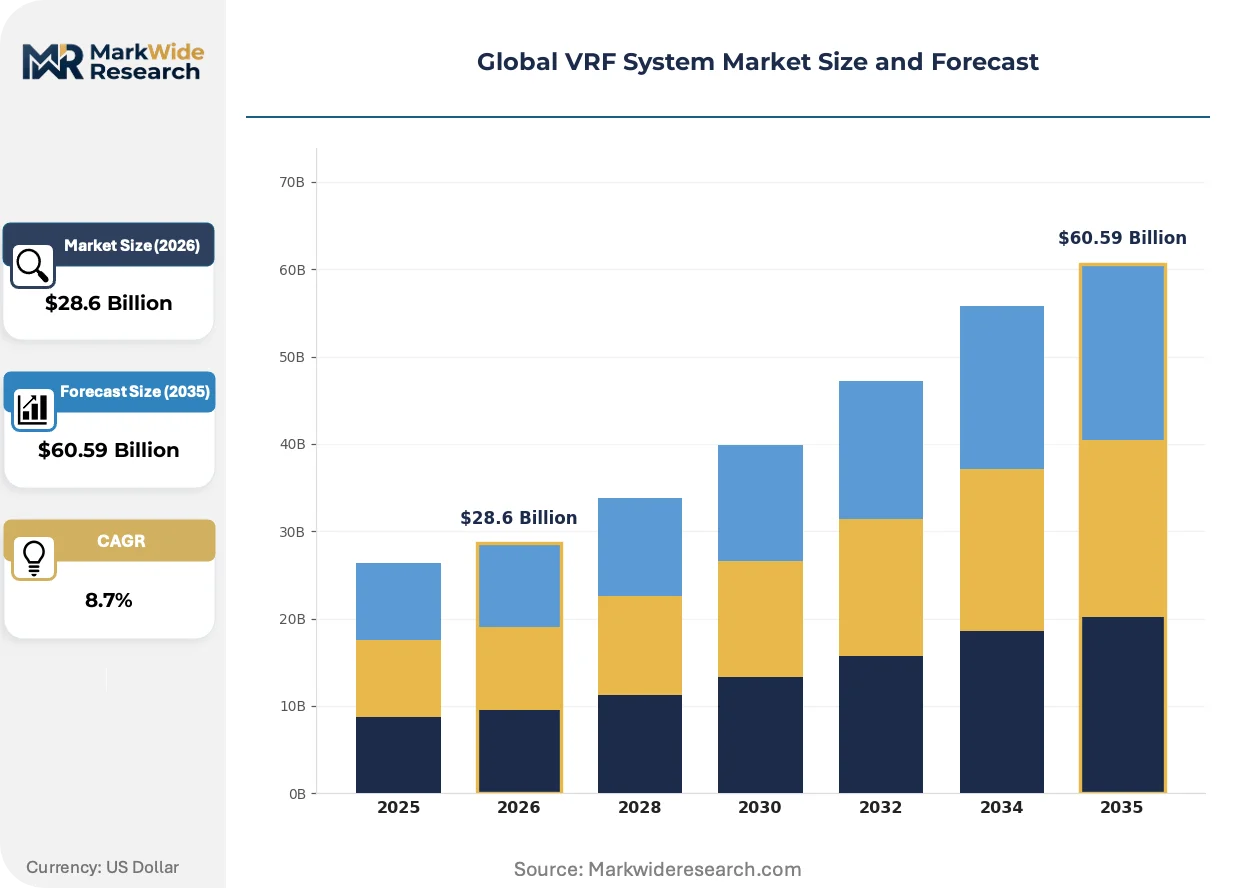
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Pump, Heat Recovery, Multi-Split, Variable Capacity End User: Commercial, Residential, Industrial, Institutional System Design: Single-Zone, Multi-Zone, Centralized, Distributed Installation Type: New Construction, Retrofit, Replacement, Upgrade |
| Companies Covered | Daikin Industries, Mitsubishi Electric, Toshiba Corporation, LG Electronics, Johnson Controls, Midea Group, Panasonic Corporation, Fujitsu General, Carrier Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global VRF System Market Strategic Shifts
Digitalization of thermal management is redefining how building operators procure, monitor, and optimize climate systems across distributed commercial portfolios.
Artificial intelligence-driven load prediction is converging with VRF system controls to anticipate occupancy patterns and pre-condition spaces before demand spikes. Facility managers in Singapore and Dubai commercial towers deploy these algorithms to shave peak demand charges. The technology is converging with utility demand-response programs to create automated grid-interactive buildings.
EPA Significant New Alternatives Policy is compressing refrigerant approval timelines for US-bound equipment, forcing manufacturers to parallel-track chemistries across multiple regulatory jurisdictions. The industrial consequence is fragmented product portfolios with region-locked refrigerant charges. US commercial distributors now stock separate inventory streams for domestic and re-export markets.
Performance-based energy contracting is displacing traditional equipment procurement in European commercial real estate. Property developers in Germany and the Netherlands now purchase guaranteed thermal output rather than capital assets, transferring operational risk to HVAC service providers. This model concentrates buyer power among large facility management firms capable of underwriting long-term efficiency guarantees.
Global VRF System Market Segmentation
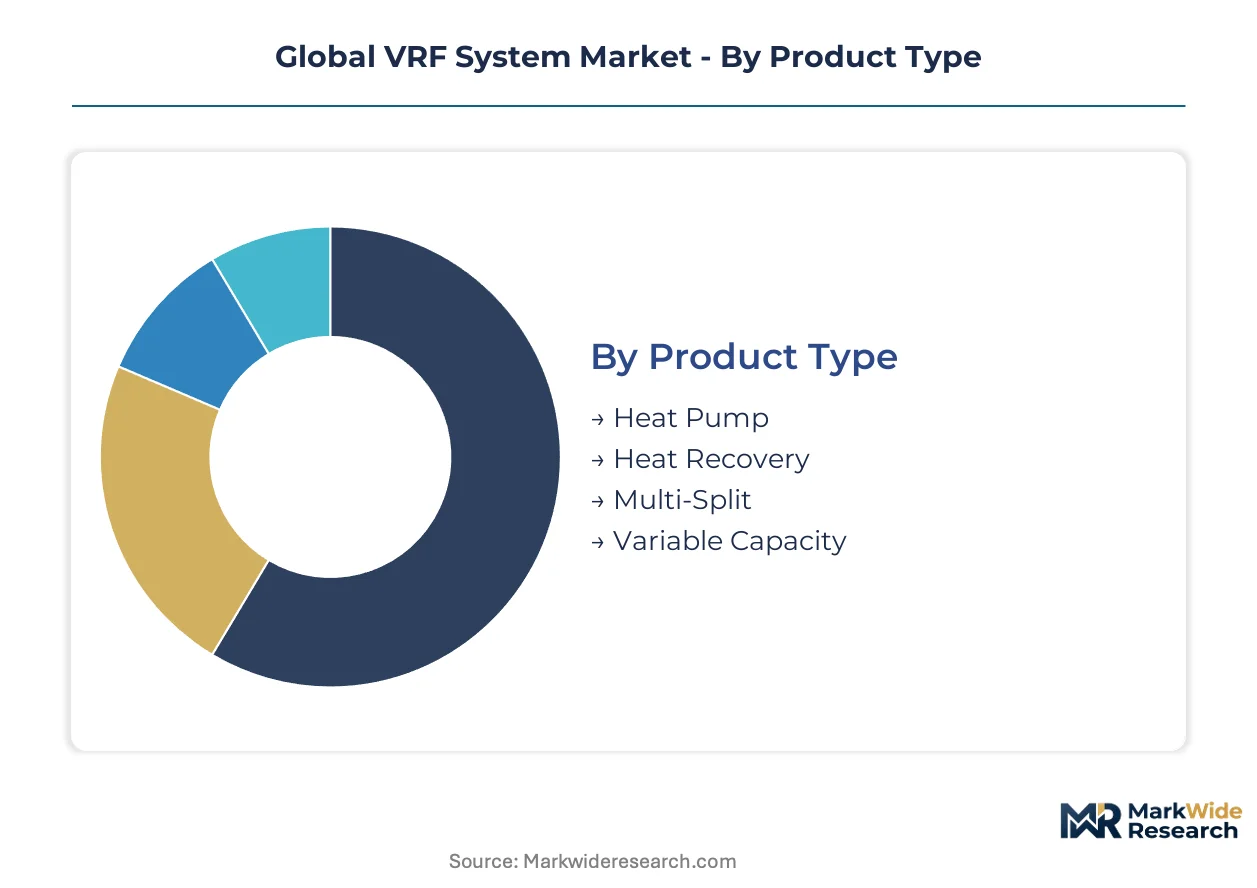
VRF system segmentation reveals how refrigerant architecture, building typology, and installation constraints fragment procurement decisions across commercial portfolios. Supply-side specialization concentrates around heat recovery configurations and multi-zone designs where technical barriers protect margin structures.
Product Type:
Captive refrigerant chemistry capabilities determine which manufacturers dominate each product tier.
- Heat Pump:Configurations deliver heating or cooling to all zones simultaneously through single-mode refrigerant flow. Demand clusters in Germany and the Netherlands where building codes mandate seasonal efficiency thresholds for commercial new construction.
- Heat Recovery:Simultaneous heating and cooling across zones requires complex refrigerant piping and dedicated heat exchanger modules. Premium positioning in Singapore and Dubai mixed-use towers drives manufacturer R&D allocation toward these systems.
- Multi-Split:Simplified zoning for smaller commercial footprints with reduced refrigerant charge requirements.
- Variable Capacity:Entry-level modulation for cost-sensitive retrofit applications in Tier-2 Indian cities.
Heat recovery absorbs the bulk of installed capacity in premium commercial segments; multi-split configurations are expanding most quickly across mid-market retrofit opportunities.
End User:
Procurement sophistication varies sharply across customer archetypes, with service contract attach rates defining profitability.
- Commercial:High-rise office towers and retail complexes in Mumbai and Bangalore generate concentrated demand for zoned climate control with centralized monitoring. Long replacement cycles and mandatory maintenance contracts sustain aftermarket revenue pools.
- Residential:Luxury apartment developments in Shanghai and Shenzhen adopt VRF for aesthetic flexibility without ductwork penetration. Smaller refrigerant charges per unit reduce regulatory compliance burdens under China's MEE efficiency benchmarks.
- Industrial:Process cooling applications with specialized temperature stability requirements.
- Institutional:Schools and hospitals with extended operating hours prioritizing redundancy.
Commercial end users command the dominant share of system value; residential deployment is climbing the fastest as urban density rises in Chinese megacities.
System Design:
Electrical infrastructure constraints in existing buildings shape design selection more than thermal load calculations.
- Multi-Zone:Distributed indoor units connect to centralized outdoor chassis through refrigerant piping networks, enabling individualized temperature control across 20-plus zones. Retrofit installations in Tokyo and Osaka commercial buildings accelerate uptake where ductwork retrofit is structurally impossible.
- Single-Zone:Simplified architecture for small commercial footprints with uniform thermal requirements. Cost advantages in Indian Tier-2 cities where capital constraints limit system complexity.
- Centralized:Large-capacity outdoor modules serving entire building footprints through extensive piping networks.
- Distributed:Multiple smaller outdoor units reducing single points of failure in critical facilities.
Multi-zone designs capture the majority of new commercial installations; single-zone systems are gaining share fastest in cost-constrained emerging markets.
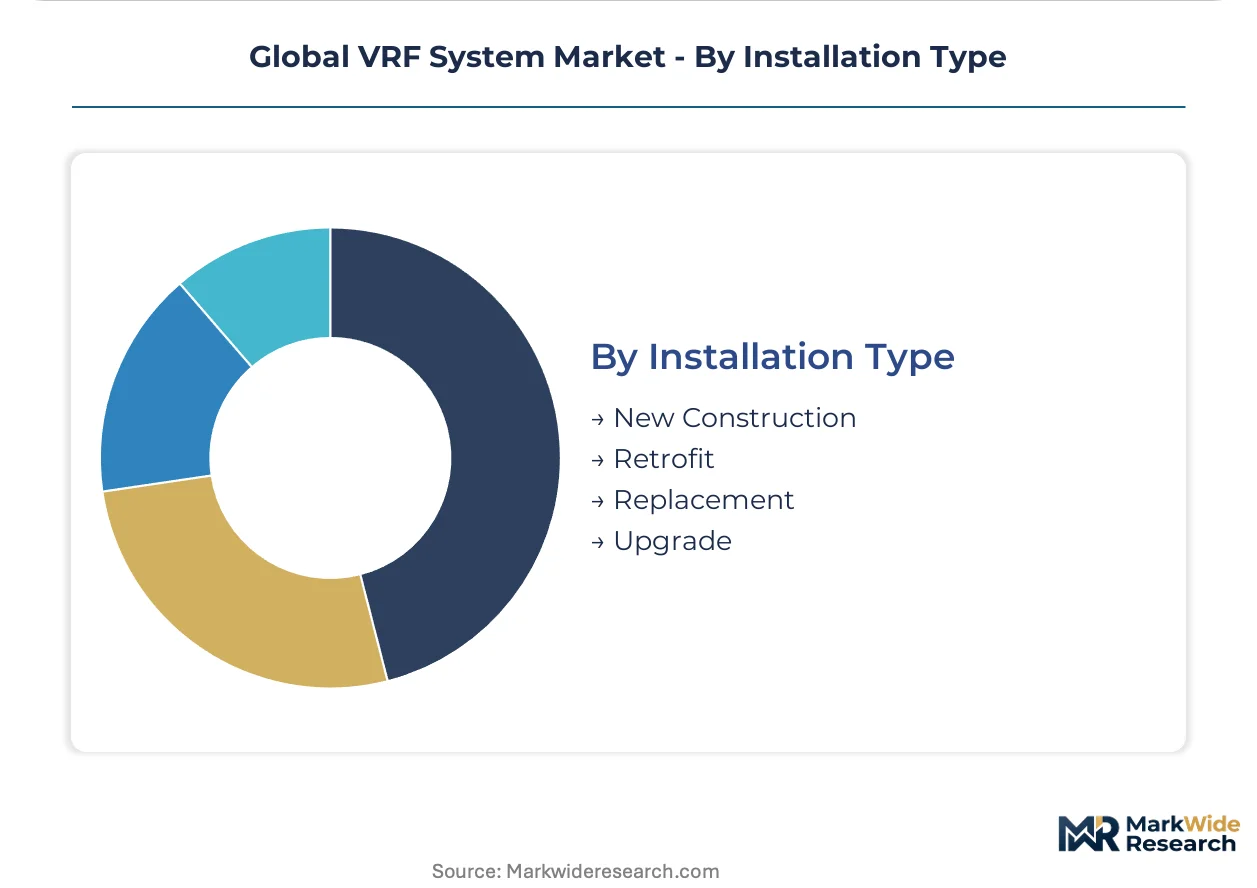
Installation Type:
Project timing relative to building lifecycle determines refrigerant platform selection and margin realization.
- Retrofit:Existing structures without ductwork capacity drive demand for refrigerant-based zoning in European heritage buildings and Asian high-density districts. Electrical infrastructure upgrades often represent 15-25% of total project cost in pre-1990s commercial stock.
- New Construction:Integrated design allows optimized refrigerant piping routes and outdoor unit placement. Developers in Singapore and Dubai specify heat recovery configurations during schematic design to secure green building certifications.
- Replacement:End-of-life system swaps maintaining existing piping where refrigerant chemistry permits.
- Upgrade:Capacity expansion or efficiency improvement of partially functional installations.
New construction absorbs the largest share of high-value heat recovery systems; retrofit activity is expanding most rapidly as building stock ages across developed Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the fastest commercial deployment as Tier-1 cities add high-rise stock without ductwork capacity. Southeast Asian developers specify zoned climate systems for mixed-use towers. European regulatory pressure on refrigerant chemistry is fragmenting product portfolios across export markets.
United States
Commercial retrofit activity in New York and Chicago drives demand for refrigerant-based zoning where structural constraints block ductwork installation. EPA Significant New Alternatives Policy compresses refrigerant approval timelines, forcing parallel-track chemistry development. Southern California data centers deploy multi-zone configurations for precision cooling without centralized air handling.
Germany
Performance-based energy contracting displaces traditional equipment procurement in Frankfurt and Munich commercial real estate. EU F-Gas Regulation mandates phase-down of high-GWP refrigerants, accelerating R32 platform adoption. Bavarian industrial zones specify heat pump configurations to meet seasonal efficiency thresholds in building codes.
Japan
Inverter compressor R&D intensity in Osaka and Nagoya sustains technical leadership in variable-speed modulation systems. METI refrigerant phase-down mandates compress product development cycles for export-oriented manufacturers. Tokyo commercial buildings accelerate multi-zone retrofit installations where ductwork modification is structurally impossible.
India
Urban commercial construction in Mumbai and Bangalore generates concentrated demand for zoned climate control in high-rise office towers. Central Electricity Authority efficiency benchmarks favor inverter-driven VRF over conventional split systems. Delhi-NCR retail complexes specify heat recovery configurations to secure green building certifications.
Singapore
Mixed-use developments in the central business district command premium positioning for simultaneous heating and cooling across building zones. Building and Construction Authority green mark standards incentivize heat recovery system specification during schematic design. Marina Bay commercial towers deploy AI-driven load prediction algorithms to shave peak demand charges through automated grid interaction.
Global VRF System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with captive refrigerant chemistry capabilities determining tier positioning. Japanese and Chinese chemical conglomerates concentrate supply of next-generation refrigerants, limiting supplier diversity. Three archetypes dominate: integrated fluorochemical producers, inverter technology specialists, and manufacturing-scale exporters. Capacity expansion and portfolio diversification around lower-GWP platforms constitute the dominant competitive moves.
Within the integrated producer tier, Daikin Industries and Mitsubishi Electric anchor positioning through captive supply chain control and compressor R&D intensity respectively. Midea Group occupies a scale-driven position among Guangdong-based exporters. These three exemplify how refrigerant chemistry access and manufacturing footprint determine competitive viability as regulatory timelines compress across multiple jurisdictions.
| Leading Market Players |
|---|
| Daikin Industries |
| Mitsubishi Electric |
| Toshiba Corporation |
| LG Electronics |
| Johnson Controls |
| Midea Group |
| Panasonic Corporation |
| Fujitsu General |
| Carrier Global Corporation |
| Others |
Value Chain & Pricing Dynamics
Fluorochemical feedstock indices in East Asia cascade through VRF manufacturing tiers, compressing margins for assemblers without captive refrigerant production while concentrating pricing power among integrated Japanese and Chinese chemical conglomerates. Contract structures stratify across equipment-only transactions, bundled installation packages, and long-term service agreements with predictive maintenance subscriptions.
Pricing Analysis
Volume concentrates in mid-market heat pump configurations while margins pool in heat recovery systems and IoT-enabled service contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU F-Gas Regulation and Japan METI mandates, brand positioning, and after-sales bundling intensity. Cost compression in entry-level multi-split configurations is intensifying because Guangdong-based exporters compete on manufacturing scale. Price sensitivity peaks among Indian Tier-2 commercial developers facing capital constraints, while Singapore mixed-use developers prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
India's phased manufacturing program and local-content requirements for public-sector commercial projects are reshaping sourcing patterns, pressuring foreign OEMs to establish compressor finishing or assembly operations within the country. Manufacturing gravity centers on Japan for inverter compressor R&D, China for multi-zone system assembly, and Thailand for Southeast Asian export hubs. Supply chains draw from fluorochemical feedstocks, copper refrigerant piping, and advanced power electronics. Single-source vulnerability concentrates in next-generation low-GWP refrigerant platforms controlled by captive production at Daikin Industries and select Chinese chemical groups. Distribution runs through authorized dealer networks with mandatory technician certification for A2L refrigerant handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VRF sector sits in a refrigerant-transition phase, with R32 and emerging R290 platforms displacing legacy R410A architectures across regulatory jurisdictions. This chemistry shift compresses product development timelines while redistributing competitive advantage toward integrated fluorochemical producers.
For Market Incumbents: Anticipate margin pressure from Chinese manufacturing-scale competitors by accelerating R290 platform certification under EU F-Gas Regulation timelines and securing captive refrigerant supply through backward integration into fluorochemical production. Channel control through exclusive dealer networks with A2L technician certification programs protects installed-base service revenue against independent service aggregators. For New Entrants and Emerging Players: Enter via heat recovery system specialization for Singapore and Dubai mixed-use developments, where premium positioning and green building certification requirements create defendable margin pools. The most penetrable white space sits in predictive maintenance software layers atop existing VRF installations, using IoT-enabled diagnostics to unbundle service contracts from equipment sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European VRF service providers with established heat recovery installation capabilities and METI-certified R32 platform expertise, particularly in Germany and the Netherlands where performance-based energy contracting concentrates buyer relationships. The signal to watch is refrigerant platform certification velocity under compressed EPA SNAP timelines, separating manufacturers capable of parallel-track chemistry development from those locked in single-platform dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Diversification | Parallel-track R32 and R290 development secures access across EU, US, and Japanese regulatory jurisdictions. |
| Backward Integration into Fluorochemicals | Captive refrigerant production insulates margin structures from East Asian feedstock price volatility. |
| Predictive Maintenance Software Launch | IoT-enabled diagnostics unbundle recurring service revenue from cyclical equipment sales cycles. |
| Heat Recovery Configuration Scale-Up | Premium positioning in Singapore and Dubai mixed-use towers commands superior installed-value capture. |
| Technician Certification Network Expansion | A2L refrigerant handling licenses create defensive moats around aftermarket service attach rates. |
Study Parameters
Independent corroboration across facility management executives, HVAC contractor operations managers, refrigerant supply specialists, and commercial real estate developers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with these stakeholder categories against secondary validation through EU F-Gas Regulation implementation reports, EPA SNAP refrigerant approval databases, Japan METI policy circulars, and customs trade data on compressor and heat exchanger flows. Bottom-up installation project tracking across Mumbai, Singapore, Frankfurt, and Tokyo commercial developments triangulates against top-down manufacturer shipment disclosures.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon, modeling refrigerant platform transitions, installation type evolution, and end-user procurement pattern shifts. Segmentation dimensions span product architecture, building typology, system design complexity, and installation timing relative to building lifecycle. CAGRs derive from installed-base expansion rates, replacement cycle compression, and efficiency benchmark adoption curves under China's MEE dual carbon goals and India's Central Electricity Authority standards.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated refrigerant phase-down timelines, copper price volatility, or electrical infrastructure retrofit delays in pre-1990s commercial stock. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Europe HVAC Market