
 Asia-Pacific Industrial Heat Pump Market | 2026-2036
Asia-Pacific Industrial Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Heat Pump Market Analytics
Food processing conglomerates are unwinding legacy steam-boiler dependency as energy-intensive manufacturers pivot toward electrified thermal systems. Carrier leverages its centrifugal chiller heritage to anchor large-scale ammonia heat pump deployments across Australian cold-chain infrastructure. Daikin Industries sustains technology leadership in inverter-driven vapor compression platforms optimized for high-lift industrial duty cycles. Mitsubishi Electric competes through integrated building-energy platforms that merge heat recovery with grid-responsive controls.
Asia-Pacific industrial heat pumps are electromechanical systems that transfer thermal energy from low-grade sources—ambient air, process wastewater, or geothermal fields—to deliver process heat between 60°C and 150°C through vapor compression or absorption cycles, with coefficient-of-performance ratios typically exceeding three under design conditions. Their primary purpose is displacing fossil-fuel combustion in manufacturing thermal loads while capturing waste heat from cooling operations. Air source equipment dominates unit volume given minimal site-work requirements, though water source configurations command premium positioning where adjacent river discharge or treated effluent streams provide stable sink temperatures. Absorption technology leads in facilities with stranded low-pressure steam or combined heat and power integration, while magnetic bearing compressors represent the fastest-growing sub-category for large-tonnage process cooling-heat recovery hybrids.
Japan's METI enforces Top Runner efficiency standards that progressively tighten allowable performance thresholds for commercial and industrial thermal equipment, directly compressing sales windows for legacy-technology inventory. China's GB standards for industrial energy consumption, administered by SAMR, mandate heat recovery in designated high-energy-intensity sectors and effectively gate market access for non-compliant imported systems. Australia's Clean Energy Regulator operates offset-certification pathways that monetize emissions reductions from fuel-switching projects, improving project economics for heat pump capital deployment. Stakeholders must monitor evolving carbon-border adjustment mechanisms and align product certification roadmaps with jurisdictions where import compliance timelines are tightening fastest.
Market Dynamics
Japan's METI Top Runner program compresses replacement cycles for thermal equipment while China's GB standards mandate heat recovery, forcing manufacturers to accelerate electrification roadmaps across chemical and textile clusters in Jiangsu and Zhejiang provinces.
Growth Catalysts
- Carbon border adjustment mechanisms:Australia's Clean Energy Regulator monetizes emissions reductions through offset-certification pathways, improving project economics for fuel-switching capital deployment in heavy manufacturing.
- Food processing expansion:Southeast Asian pasteurization and drying operations are unwinding legacy steam-boiler dependency in favor of high-temperature vapor compression systems.
- Dual carbon goals:China's MEE enforcement of industrial energy consumption standards gates market access for non-compliant imported equipment, accelerating domestic and foreign OEM certification alignment.
Market Restraints
- Refrigerant supply concentration:Ammonia and low-GWP working fluid production clusters in select East Asian chemical hubs expose project timelines to input volatility and logistics bottlenecks.
- High-lift compressor technical ceiling:Magnetic bearing and centrifugal platforms face durability constraints above 120°C lift conditions, limiting addressable process heat segments.
- Grid interconnection friction:Australia's NEM connection standards and Japan's regional utility protocols create permitting delays for megawatt-scale electromechanical thermal installations.
Strategic Opportunities
- Vietnam and Indonesia manufacturing corridors:Underpenetrated food processing and electronics assembly clusters lack legacy thermal infrastructure, enabling greenfield heat pump specification without retrofit constraints.
- CHP integration:Absorption cycle convergence with stranded low-pressure steam assets in Japanese steel and paper facilities opens hybrid thermal platform deployment.
- Geothermal source pairing:New Zealand's stable subsurface temperatures and Philippines volcanic field proximity enable water-source configurations with coefficient-of-performance advantages unavailable to air-source alternatives.
Industry Challenges
- Refrigeration technician scarcity:Ammonia-safe handling certification pipelines in Australia and Japan fail to match installation demand, extending commissioning timelines for industrial-scale deployments.
- Legacy control integration:SCADA and building management system interoperability gaps force custom engineering for grid-responsive heat recovery platforms in established manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Heat Pump Market |
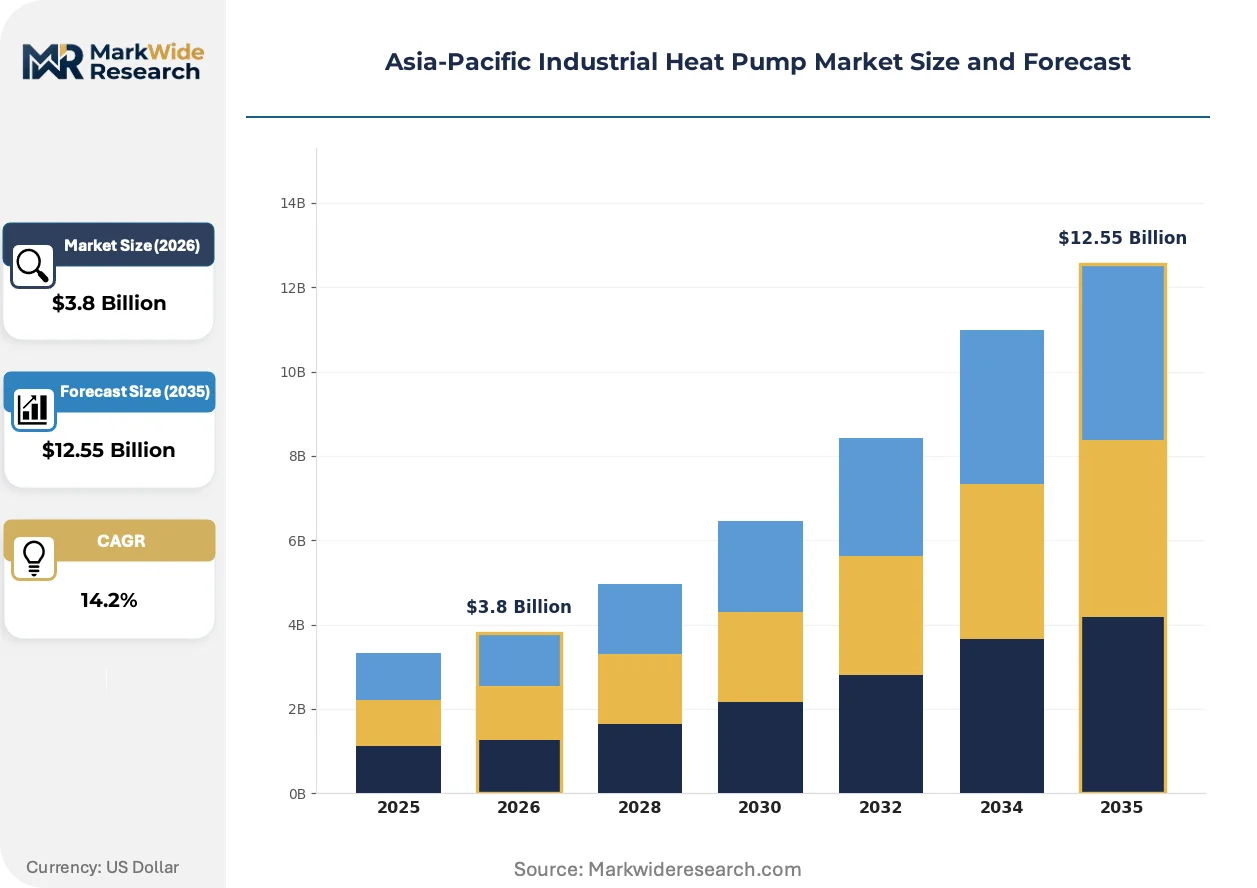
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Water Source, Ground Source, Hybrid End User: Manufacturing, Agriculture, Food Processing, Textile Application: Heating, Cooling, Hot Water Supply, Drying Technology: Vapor Compression, Absorption, Thermoelectric, Magnetic |
| Companies Covered | Carrier, Trane Technologies, Mitsubishi Electric, GEA Group Aktiengesellschaft, Emerson Electric, Daikin Industries, Johnson Controls, Siemens Energy, Atlas Copco AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Heat Pump Market Evolving Landscape
Electrification of process heat is compressing fossil-fuel combustion windows while magnetic bearing compressors and ammonia working fluids redefine performance boundaries for high-lift industrial duty cycles.
Magnetic bearing centrifugal compressor technology is supplanting oil-lubricated screw platforms in large-tonnage process cooling-heat recovery hybrids. Australian cold-chain infrastructure operators specify these systems for simultaneous chilled water and hot water production. The shift is compressing maintenance intervals and enabling variable-speed operation across wider lift ranges than conventional flooded evaporator designs.
Japan's METI Top Runner efficiency standards progressively tighten allowable performance thresholds for commercial and industrial thermal equipment. The regulatory compression directly shortens sales windows for legacy-technology inventory and accelerates OEM development cycles. Heavy manufacturing sectors face the steepest compliance ramps, with equipment replacement timelines contracting from fifteen-year cycles toward eight-year horizons.
Energy service contracting is displacing direct capital purchase for thermal infrastructure in Australian and Japanese industrial parks. Third-party operators assume performance risk and retain equipment ownership, unbundling after-sales service from hardware margins. The model concentrates most visibly in chemical processing clusters where heat load predictability supports guaranteed savings structures.
Asia-Pacific Industrial Heat Pump Market Segmentation
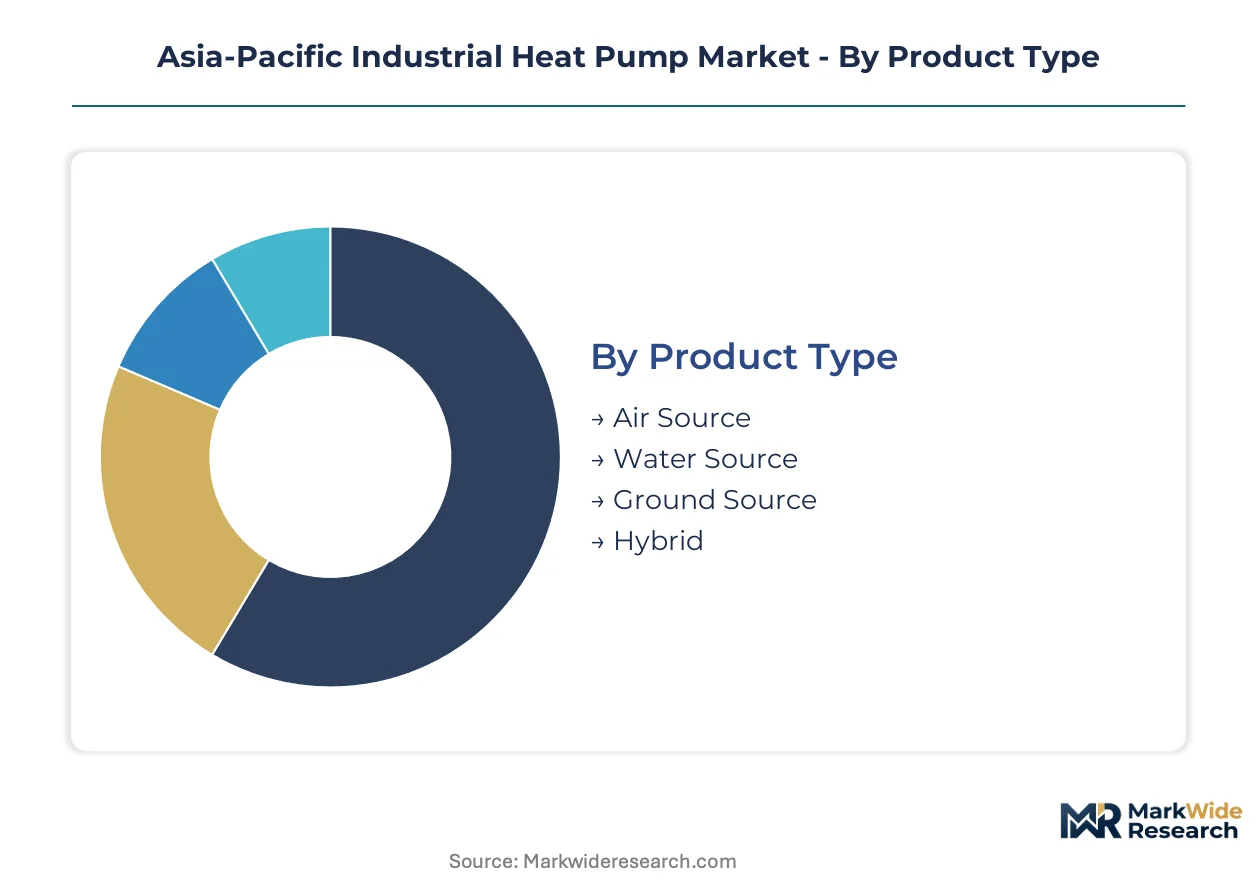
Industrial heat pump procurement channels diverge sharply by configuration complexity and site-work requirements. OEM-direct relationships dominate large-tonnage process installations, while distributor networks capture standardized air-source replacements across fragmented manufacturing bases.
Product Type:
Channel mix varies by source stability and infrastructure investment, with water-source and ground-source systems flowing through engineering-procurement-construction integrators while air-source units move through HVAC distributors.
- Air Source:Ambient-air heat exchangers with minimal site-work requirements deploy across rooftop and pad-mounted configurations. Demand concentrates in eastern China's Jiangsu and Zhejiang textile clusters where factory roof availability supports distributed thermal infrastructure. Procurement friction is lowest in this configuration.
- Water Source:River-discharge and treated-effluent heat exchangers deliver stable sink temperatures for high-lift process duty. Australian cold-chain operators specify these for simultaneous chilled water and hot water production, exploiting coastal and riverine infrastructure proximity.
- Ground Source:Geothermal field pairings with buried loop arrays command premium positioning where subsurface thermal stability offsets higher capital intensity. New Zealand's stable ground temperatures enable performance coefficients unavailable to air-source alternatives.
- Hybrid:Dual-source configurations switching between ambient air and water sources based on seasonal conditions. Japanese heavy manufacturing facilities deploy these to hedge against ambient temperature volatility in coastal industrial zones.
By volume, Air Source leads. By growth pace, Water Source is gaining share fastest.
End User:
Cost tier stratification separates continuous-process manufacturers with predictable thermal loads from batch-operation facilities with intermittent demand profiles.
- Manufacturing:Continuous-process chemical and heavy industrial facilities with 24/7 thermal demand profiles. METI Top Runner compliance deadlines in Japan compress replacement cycles toward eight-year horizons from legacy fifteen-year baselines.
- Food Processing:Pasteurization and drying operations across Southeast Asian conglomerates unwind steam-boiler dependency in favor of electrified thermal systems. Australia's Clean Energy Regulator offset-certification pathways improve project economics for this capital-intensive transition.
- Agriculture:Greenhouse climate control and grain drying applications with seasonal load concentration. Procurement patterns favor smaller-tonnage air-source units through agricultural equipment distributors.
- Textile:Dyeing and finishing operations in China's dual carbon-regulated industrial corridors face mounting decarbonization mandates from MEE enforcement of GB energy consumption standards.
Manufacturing captures the largest revenue pool. Food Processing shows the steepest expansion trajectory.
Application:
Volume concentration sits with heating and cooling loads, though hot water supply and drying applications command margin premiums through process-integration complexity.
- Heating:Process heat delivery between 60°C and 150°C displaces fossil-fuel combustion in manufacturing thermal loads. China's chemical clusters in Jiangsu province drive concentrated specification for high-temperature vapor compression platforms.
- Cooling:Simultaneous chilled water production with heat recovery to hot water loops. Australian cold-chain infrastructure operators specify magnetic bearing centrifugal systems for this dual-output configuration.
- Hot Water Supply:Continuous domestic and process hot water generation with coefficient-of-performance ratios exceeding three under design conditions. Japanese commercial and institutional facilities integrate these with building-energy management platforms.
- Drying:Low-temperature desiccation applications in food processing and agricultural operations. Southeast Asian pasteurization facilities specify high-temperature heat pumps to replace legacy steam-based drying infrastructure.
Heating dominates installed base. Drying applications are climbing the fastest.
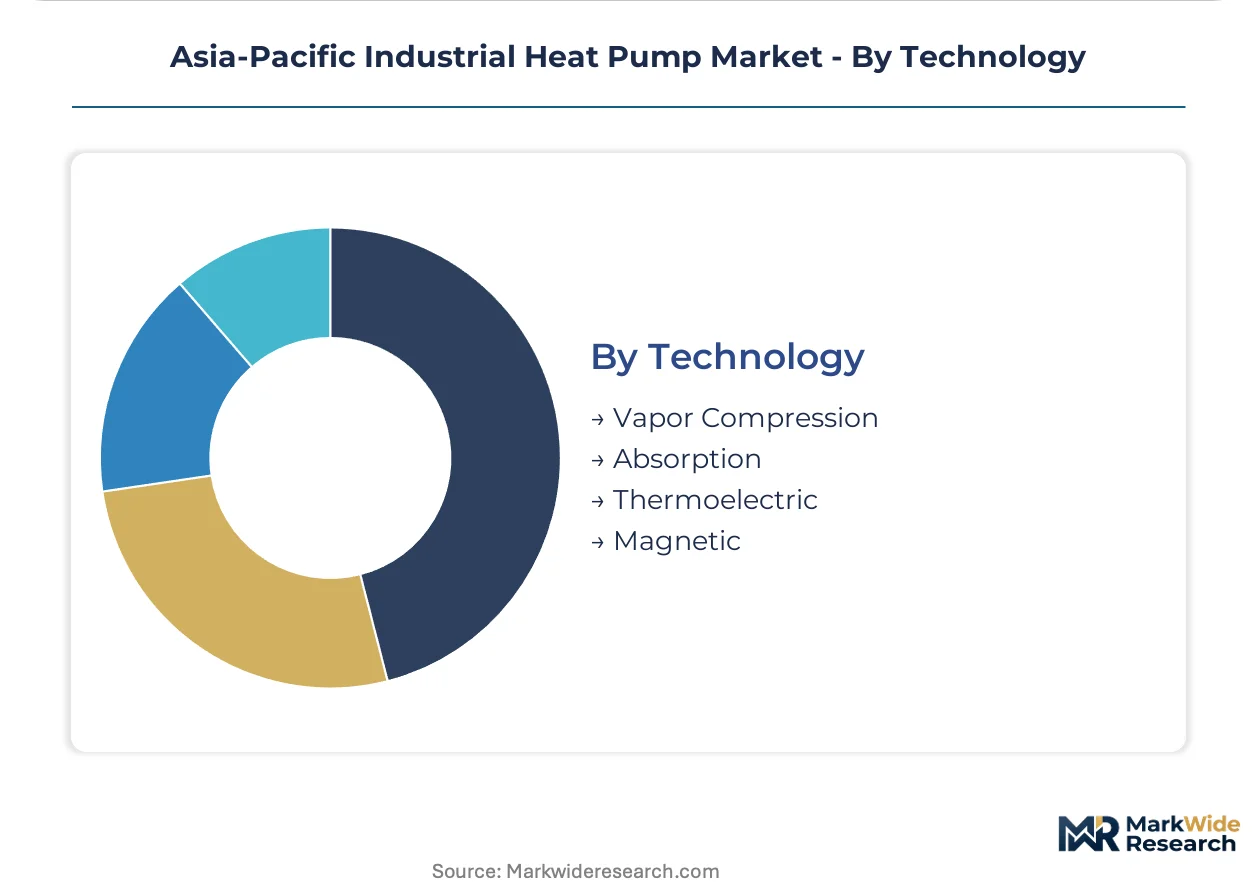
Technology:
Maturity gradients separate proven vapor compression platforms from emerging magnetic bearing and thermoelectric alternatives with narrower commercial track records.
- Vapor Compression:Inverter-driven refrigerant cycles optimized for high-lift industrial duty cycles. Daikin Industries sustains technology leadership in this platform category across Japanese and Australian deployments.
- Absorption:Thermal-activated cycles leveraging stranded low-pressure steam or waste heat sources. Japanese steel and paper facilities integrate these with combined heat and power assets for hybrid thermal platform deployment.
- Magnetic:Oil-free centrifugal compressors with magnetic bearings enabling variable-speed operation across wider lift ranges. Australian large-tonnage process cooling-heat recovery hybrids specify this fastest-growing sub-category.
- Thermoelectric:Solid-state heat pumping through Peltier-effect junctions with no moving parts. Niche applications in precision temperature control for electronics assembly clusters in Vietnam and Indonesia.
Vapor Compression anchors current revenue. Magnetic platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor and heat exchanger fabrication clusters in Japan, South Korea, and eastern China supply the bulk of regional equipment. These manufacturing hubs feed project pipelines across Southeast Asian food processing corridors and Australian cold-chain infrastructure.
China
Jiangsu and Zhejiang province chemical and textile clusters face tightening GB energy consumption standards enforced by SAMR. MEE decarbonization mandates accelerate electrification timelines for process heat systems. Nanjing and Hangzhou industrial parks specify high-temperature vapor compression platforms for dyeing and finishing operations.
Japan
Heavy manufacturing facilities in the Chubu and Kansai regions unwind fifteen-year replacement cycles under METI Top Runner efficiency standards. Steel and paper mills integrate absorption cycles with stranded low-pressure steam assets. Nagoya industrial corridors compress equipment sales windows toward eight-year horizons.
Australia
Cold-chain infrastructure operators along the eastern seaboard deploy magnetic bearing centrifugal systems for simultaneous chilled water and hot water production. The Clean Energy Regulator monetizes fuel-switching emissions reductions through offset-certification pathways. Sydney and Melbourne distribution hubs anchor large-tonnage process cooling-heat recovery hybrid specifications.
Vietnam
Underpenetrated food processing and electronics assembly corridors in the Red River Delta and Mekong Delta lack legacy thermal infrastructure. Greenfield pasteurization facilities specify high-temperature heat pumps without retrofit constraints. Ho Chi Minh City industrial zones attract ammonia heat pump deployments for drying operations.
Indonesia
Java-based manufacturing clusters expand adoption of electrified thermal systems for batch-process operations. National energy efficiency directives pressure conglomerates to displace diesel-fired boilers in export-oriented facilities. Surabaya and Bandung industrial estates pilot water-source configurations exploiting riverine proximity.
Asia-Pacific Industrial Heat Pump Market Competitive Landscape
Concentration sits with diversified electromechanical conglomerates possessing captive compressor technology and regional service networks. Japanese and European industrial majors anchor premium-tier positioning through integrated building-energy platforms. Three archetypes dominate: full-system integrators with chiller heritage, component specialists supplying magnetic bearing compressors, and energy service companies unbundling hardware from performance contracts. Competitive moves center on technology licensing partnerships and backward integration into ammonia-safe handling certification pipelines.
Within the full-system integrator tier, Carrier leverages centrifugal chiller heritage to anchor large-scale deployments, while Daikin Industries sustains technology leadership in inverter-driven vapor compression platforms. Mitsubishi Electric competes through integrated building-energy platforms that merge heat recovery with grid-responsive controls. These three exemplify the strategic tension between equipment-centric margins and service-contract recurring revenue models.
| Leading Market Players |
|---|
| Carrier |
| Trane Technologies |
| Mitsubishi Electric |
| GEA Group Aktiengesellschaft |
| Emerson Electric |
| Daikin Industries |
| Johnson Controls |
| Siemens Energy |
| Atlas Copco AB |
| Others |
Value Network & Pricing Analysis
Ninety-day compressor lead times from Japanese fabrication hubs concentrate pricing power among integrated OEMs serving Australian and Southeast Asian project pipelines. This inventory compression amplifies cost pass-through capacity for magnetic bearing and ammonia-safe handling components while squeezing margins for distributor-dependent installers.
Pricing Analysis
China's GB standards dictate the pricing tier structure across the Asia-Pacific industrial heat pump landscape. Three-tier pricing separates premium magnetic bearing platforms from standard inverter-driven vapor compression and economy-grade air-source units. Price differentiation centers on certification grade for ammonia-safe handling and after-sales service bundling. Pricing pressure stems from refrigerant supply volatility in East Asian chemical hubs. Batch-operation facilities in Indonesian manufacturing corridors exhibit highest price sensitivity, while continuous-process chemical plants in Jiangsu province prioritize performance guarantees over capital expenditure minimization.
Supply Chain Analysis
Strait of Malacca transit underwrites component logistics for compressor and heat exchanger fabrication clusters across Japan, South Korea, and eastern China. Raw material dependencies center on rare-earth magnetic alloys, ammonia working fluid, and precision-machined aluminum castings. Single-source vulnerability concentrates in low-GWP refrigerant production anchored to select chemical hubs. Distribution runs through engineering-procurement-construction integrators for water-source and ground-source configurations, while HVAC distributor networks capture standardized air-source unit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific industrial heat pump market functions as a service-attach opportunity where energy performance contracting and ammonia-safe handling certification revenues expand faster than hardware margins. Recurring-revenue layers from guaranteed savings structures and aftermarket technical support now dominate OEM strategic planning.
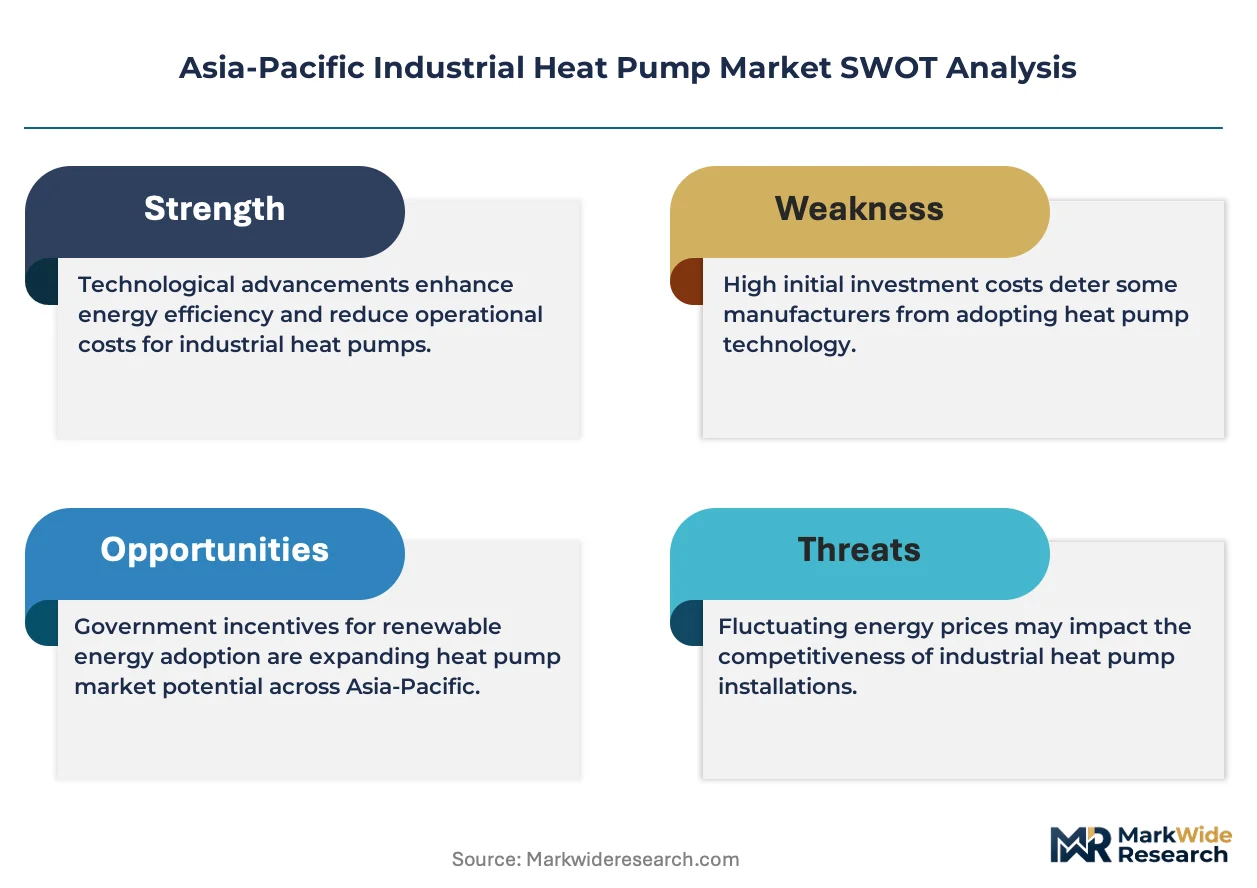
For Market Incumbents: Shield installed base relationships through captive ammonia-safe handling certification pipelines that extend commissioning timelines for non-integrated competitors. Accelerate backward integration into magnetic bearing compressor production to reduce exposure to rare-earth supply volatility. Prioritize channel control in Vietnamese and Indonesian greenfield corridors where legacy thermal infrastructure absence eliminates retrofit friction. For New Entrants and Emerging Players: Anchor in underpenetrated food processing clusters across Vietnam's Red River Delta and Mekong Delta where pasteurization facilities lack steam-boiler legacy constraints. Target electronics assembly corridors in Indonesian Batam and Malaysian Penang for precision thermoelectric applications. Pursue equipment-as-a-service go-to-market structures that unbundle capital risk from performance delivery. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electromechanical conglomerates seeking to divest non-core thermal assets amid portfolio rebalancing pressures. Long-term viability rests on service-contract recurring revenue ratios exceeding hardware shipment volatility. Monitor METI Top Runner compliance deadline acceleration as inflection indicator for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Safe Certification Pipeline Buildout | Captive technician training infrastructure locks out distributor-dependent competitors in Australian and Japanese markets. |
| Magnetic Bearing Compressor Backward Integration | In-house production of oil-free centrifugal platforms reduces rare-earth alloy exposure and maintenance interval compression. |
| Energy Performance Contracting Expansion | Third-party ownership models concentrate in Chinese chemical clusters where heat load predictability supports guaranteed savings. |
| Geothermal Source Pairing Partnerships | New Zealand and Philippines subsurface temperature stability enables water-source configurations with coefficient-of-performance advantages. |
| Grid-Responsive Control Platform Integration | SCADA interoperability investments address legacy building management system gaps in established Japanese manufacturing facilities. |
Research Methodology
A spread of perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and EPC contractors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with maintenance directors at chemical processing facilities and thermal infrastructure planners at Australian cold-chain operators. Secondary validation drew from METI efficiency standard filings, SAMR GB compliance databases, Australian Clean Energy Regulator offset certification records, and customs trade data for compressor and heat exchanger imports. Bottom-up project pipeline enumeration triangulated against top-down sectoral energy consumption forecasts.
Segmentation dimensions modeled include source configuration stability, end-use industry thermal load profile, application temperature range, and technology maturity gradient across the projection horizon. Vapor compression platform revenue trajectories incorporated inverter efficiency curves and high-lift duty cycle degradation rates. Absorption cycle penetration assumptions rested on stranded low-pressure steam availability in Japanese steel and paper facilities. CAGR derivation weighted regulatory compliance deadline acceleration against refrigerant supply chain volatility.
Decision-makers should treat outputs as directional under base assumptions of sustained METI Top Runner enforcement and stable ammonia working fluid supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as carbon border adjustment mechanism coverage expands and grid interconnection standards evolve across Australian NEM and Japanese regional utility jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Europe Heat Exchanger Market