
 Heat Moisture Exchanger Market | 2026-2036
Heat Moisture Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Moisture Exchanger Market Outlook
ISO 18562 biocompatibility certification is reorganizing competitive tiers across the heat moisture exchanger landscape. Medtronic leverages its vertically integrated filtration manufacturing to sustain premium positioning in critical care circuits. Draeger anchors European hospital procurement through direct channel control and anesthesia system bundling. Teleflex competes in North American acute care with specialized pediatric and neonatal heat moisture exchanger configurations.
A heat moisture exchanger is a passive humidification device composed of a hygroscopic membrane or foam element that captures expired heat and moisture and returns it to inspired gas, typically achieving 70-90% efficiency in moisture conservation with dead space volumes under 100 mL. The device serves primarily to condition breathing gases for mechanically ventilated patients, reducing mucosal drying and ventilator-associated complications without active heating elements. Plate heat exchangers occupy the mature core of product architecture, while energy recovery applications in healthcare HVAC retrofits represent the fastest-expanding demand pool. Stainless steel and aluminum material grades concentrate margin capture where thermal conductivity specifications exceed 200 W/m·K for high-flow anesthesia circuits.
The U.S. FDA's 510(k) pathway for passive humidifiers and ISO 18562-1 through -4 biocompatibility testing standards shape product development timelines and market access thresholds for all manufacturers. The EU Medical Device Regulation's Class IIa classification for heat moisture exchangers imposes clinical evidence requirements that favor established players with notified body relationships. Stakeholders must monitor evolving hospital sustainability mandates that tie procurement decisions to energy recovery performance metrics in building ventilation systems.
Market Dynamics
ISO 18562 biocompatibility certification is reorganizing competitive tiers across the heat moisture exchanger landscape, forcing manufacturers to consolidate testing capabilities or exit critical care segments entirely.
Growth Catalysts
- EU Medical Device Regulation Class IIa classification:Clinical evidence requirements favor established players with notified body relationships, accelerating hospital procurement consolidation toward certified suppliers.
- Energy recovery ventilation mandates:Germany's healthcare construction standards now require heat recovery performance metrics in building ventilation systems, expanding specification opportunities for high-efficiency exchangers.
- Hygroscopic membrane material advances:New polymer formulations achieving 90% moisture conservation efficiency are opening pediatric and neonatal applications where dead space minimization is critical.
Market Restraints
- Aluminum price volatility:Thermal conductivity-grade aluminum inputs exceeding 200 W/m·K specifications face supply concentration in primary smelter networks, compressing margin predictability for high-flow anesthesia circuit manufacturers.
- Passive humidifier substitution threat:Active heated humidification systems with precise temperature control are reclaiming share in long-term ventilation cases exceeding 96 hours.
- FDA 510(k) pathway friction:Substantial equivalence determinations for novel membrane geometries are extending premarket timelines, delaying revenue recognition for product line refreshes.
Strategic Opportunities
- Healthcare HVAC retrofit wave:Energy recovery ventilation mandates in German hospital procurement networks are accelerating specification upgrades for building-integrated heat exchanger systems.
- Pediatric circuit specialization:Neonatal intensive care units are demanding sub-50 mL dead space configurations, creating premium positioning for manufacturers with micro-molding capabilities.
- ISO 18562-4 testing service bundling:Biocompatibility certification bottlenecks are creating adjacent revenue streams for manufacturers offering regulatory package solutions to smaller competitors.
Industry Challenges
- Polymer science talent scarcity:Hygroscopic membrane formulation expertise concentrates in medical device hubs, forcing manufacturers to relocate R&D functions or pay premium compensation.
- Legacy anesthesia system integration:Heat moisture exchanger retrofit compatibility with installed Draeger and Medtronic circuit architectures requires proprietary connector engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Moisture Exchanger Market |
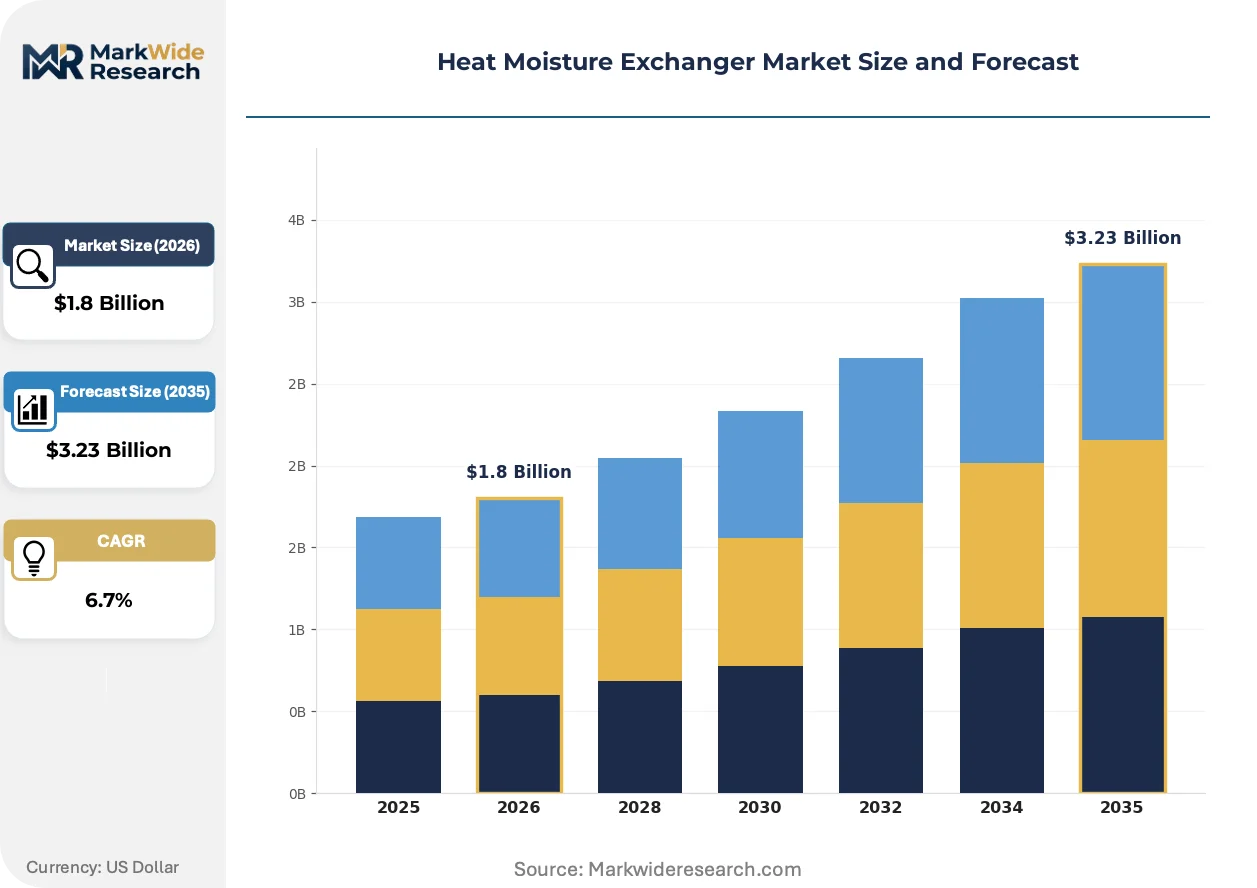
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plate Heat Exchangers, Shell and Tube Heat Exchangers, Air-to-Air Heat Exchangers, Rotary Heat Exchangers Material: Stainless Steel, Aluminum, Plastic, Copper End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Healthcare Facilities Application: HVAC Systems, Dehumidification, Energy Recovery, Indoor Air Quality |
| Companies Covered | Medtronic, Draeger, Teleflex, Intersurgical, Smiths Medical, GVS Group, King Systems, Biopsybell, GaleMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Moisture Exchanger Market Strategic Shifts
Membrane material science and regulatory testing consolidation are actively reshaping product development priorities, while procurement centralization is compressing vendor access to hospital networks.
Electrospun nanofiber hygroscopic membranes are displacing conventional foam elements in premium heat moisture exchanger configurations. Neonatal intensive care units in tertiary hospitals are adopting these materials at accelerated pace due to sub-30 mL dead space achievement. This displacement is compressing margin pools for foam-based manufacturers while concentrating volume with polymer science specialists.
REACH substance restrictions on phthalate plasticizers are forcing reformulation of circuit housing materials across EU supply chains. Industrial consequence includes 18-month validation cycles for alternative polymer compounds in breathing gas pathways. Pediatric and neonatal product categories are most affected, with manufacturers accelerating biocompatible TPE adoption ahead of enforcement deadlines.
Hospital procurement networks are consolidating vendor panels around single-source anesthesia system contracts. Group purchasing organizations are displacing independent distributor relationships with direct manufacturer agreements. This concentration is most visible in German and US acute care networks, where bundled circuit pricing now dominates heat moisture exchanger selection criteria.
Heat Moisture Exchanger Market Segmentation
Segmentation in the heat moisture exchanger market reveals how regulatory pressure and application-specific performance requirements fragment manufacturing strategies. Product architecture, material selection, and end-use certification tiers create distinct competitive battlegrounds with divergent margin structures.
Product Type:
FDA 510(k) clearance pathways and EU MDR Class IIa clinical evidence requirements differentiate product architectures by validation burden and commercial timeline.
- Plate Heat Exchangers:These devices employ stacked corrugated plates with gasket or brazed seals to transfer thermal energy between fluid streams with minimal dead space. German hospital procurement networks specify plate configurations for energy recovery ventilation retrofits where thermal efficiency mandates exceed 75% heat transfer rates. The ISO 18562 biocompatibility certification timeline for new plate geometries runs 14-18 months, favoring incumbents with established testing protocols.
- Shell and Tube Heat Exchangers:Cylindrical pressure vessels containing tube bundles handle high-flow anesthesia circuits in acute care settings. Demand concentrates in US tertiary hospitals where Draeger and Medtronic anesthesia system bundling locks in shell and tube specifications for legacy circuit compatibility. Thermal conductivity requirements above 200 W/m·K restrict material sourcing to specialized aluminum and copper grades.
- Air-to-Air Heat Exchangers:Cross-flow or counter-flow configurations dominate building-integrated HVAC applications.
- Rotary Heat Exchangers:Desiccant-coated wheels achieve highest moisture recovery efficiency for dehumidification-intensive environments.
Plate heat exchangers handle the majority of throughput; rotary configurations are gaining share fastest in healthcare construction specifications.
Material:
Cost tier stratification separates premium thermal conductivity grades from commodity substitutes in procurement decisions.
- Stainless Steel:Austenitic grades 304 and 316L deliver corrosion resistance for breathing gas pathways requiring ISO 18562-1 cytotoxicity compliance. German and Swiss hospital networks specify stainless for reusable circuit components subject to autoclave sterilization cycles exceeding 500 uses. REACH substance restrictions on nickel alloy processing are extending supply lead times for medical-grade sheet stock.
- Aluminum:6061-T6 and 3003 alloys achieve thermal conductivity above 200 W/m·K for high-flow anesthesia circuits. Primary smelter concentration in Canada and Norway creates price volatility exposure for manufacturers lacking long-term offtake agreements. The US FDA's updated device classification rules tighten quality benchmarks for aluminum surface finish specifications in passive humidification elements.
- Plastic:Polysulfone and polyetherimide formulations serve disposable single-use segments.
- Copper:Antimicrobial properties drive specification in pediatric and neonatal intensive care applications.
Aluminum captures the steepest expansion trajectory in high-performance segments; plastic dominates unit volume in disposable circuits.
End User:
Customer type determines certification depth, with healthcare facilities requiring full ISO 18562 biocompatibility validation that residential and commercial segments bypass.
- Healthcare Facilities:Acute care hospitals and neonatal intensive care units demand sub-50 mL dead space configurations with 90% moisture conservation efficiency. Germany's energy recovery ventilation mandates in healthcare construction standards accelerate specification upgrades for building-integrated systems. The EU MDR Class IIa classification imposes clinical evidence requirements that consolidate procurement around certified suppliers with notified body relationships.
- Commercial Buildings:Office and retail HVAC retrofits prioritize energy recovery performance metrics tied to sustainability procurement criteria. Demand clusters in German municipal hospital networks where building ventilation upgrades must demonstrate heat recovery efficiency above 70%.
- Residential Buildings:Single-family and multi-family ventilation systems specify lower-cost plastic and aluminum configurations.
- Industrial Facilities:Manufacturing and process applications emphasize thermal duty capacity over biocompatibility certification.
Healthcare facilities command premium pricing tiers; commercial buildings show the fastest procurement volume acceleration.
Application:
Application maturity separates established HVAC replacement demand from emerging energy recovery and indoor air quality specification pools.
- HVAC Systems:Heating, ventilation, and air conditioning integration represents the installed base replacement market with predictable seasonal demand patterns. US hospital construction and German healthcare facility retrofits sustain specification volume for plate and shell-and-tube configurations. Energy efficiency code updates in California and New York mandate minimum heat recovery effectiveness ratings.
- Energy Recovery:Exhaust air heat and moisture capture for supply air conditioning achieves fastest specification growth in German hospital procurement networks. Building ventilation mandates tie contractor selection to verified thermal performance metrics, concentrating awards around manufacturers with in-house testing laboratories.
- Dehumidification:Rotary exchanger applications in swimming pools and archival storage.
- Indoor Air Quality:Filtration-integrated exchangers for allergen and pathogen control.
HVAC systems anchor current revenue; energy recovery is climbing the fastest on specification share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary aluminum smelter concentration in Canada and Norway shapes raw material access for thermal conductivity-grade components. Hospital procurement networks in Germany and the United States dominate specification volume for critical care applications. Regulatory divergence between FDA 510(k) pathways and EU MDR Class IIa requirements fragments certification strategies across major demand centers.
United States
Acute care hospitals in tertiary medical centers drive specification of sub-50 mL dead space configurations for neonatal intensive care. The FDA's updated medical device classification rules for passive humidification devices tighten quality benchmarks and extend premarket timelines for novel membrane geometries. The Boston-Cambridge medical device cluster anchors domestic R&D concentration for hygroscopic membrane formulation.
Germany
Energy recovery ventilation mandates in healthcare construction standards accelerate specification upgrades for building-integrated heat exchanger systems. The EU Medical Device Regulation's Class IIa classification imposes clinical evidence requirements that consolidate procurement around certified suppliers with notified body relationships. The Rhine-Ruhr industrial corridor hosts concentrated anesthesia system manufacturing and direct channel control operations.
Switzerland
Swissmedic oversight of Class IIa medical devices reinforces premium positioning for reusable circuit components subject to autoclave sterilization cycles. REACH substance restrictions on nickel alloy processing extend supply lead times for medical-grade stainless steel sheet stock. The Basel-Zurich corridor concentrates polymer science expertise for hygroscopic membrane development.
China
NMPA medical device registration requirements for imported passive humidifiers create market access friction for foreign manufacturers. Domestic hospital construction in tier-one cities drives demand for HVAC-integrated energy recovery systems. The Yangtze River Delta manufacturing base supplies aluminum thermal conductivity-grade components for export-oriented medical device assemblers.
Japan
METI energy efficiency standards for healthcare facility retrofits specify minimum heat recovery effectiveness ratings in building ventilation upgrades. PMDA quality management system requirements for Class II medical devices align with ISO 18562 biocompatibility certification timelines. The Kansai-Osaka industrial region concentrates precision metalworking for high-flow anesthesia circuit components.
Heat Moisture Exchanger Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the heat moisture exchanger landscape. Vertically integrated filtration manufacturers with in-house membrane production capabilities occupy premium positioning in critical care segments. Specialist polymer science firms with electrospinning expertise capture neonatal and pediatric sub-50 mL dead space niches. Scale-driven fabricators serving HVAC and building ventilation applications compete on thermal conductivity specifications and procurement network access. Consolidation pressure from group purchasing organization centralization favors direct manufacturer agreements over independent distributor relationships.
Among diversified medical technology conglomerates, Medtronic and Draeger exemplify archetypes with upstream control over filtration manufacturing and direct channel dominance respectively. Teleflex occupies a position within the acute care specialization tier. These three anchors represent distinct competitive vectors: integrated supply chain control, European procurement network anchoring, and North American pediatric circuit focus.
| Leading Market Players |
|---|
| Medtronic |
| Draeger |
| Teleflex |
| Intersurgical |
| Smiths Medical |
| GVS Group |
| King Systems |
| Biopsybell |
| GaleMed |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for thermal conductivity-grade aluminum lock in both supply access and price visibility for high-flow anesthesia circuit manufacturers facing primary smelter concentration in Canada and Norway. German hospital procurement networks leverage these contract structures to secure volume commitments while insulating against commodity volatility in 6061-T6 and 3003 alloy inputs.
Pricing Analysis
EU MDR Class IIa classification dictates the pricing tier structure across heat moisture exchanger configurations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 18562-certified pediatric circuits from general acute care disposables and commodity HVAC retrofit components. Cost compression in aluminum-intensive shell and tube architectures is intensifying because REACH substance restrictions on nickel alloy processing extend supply lead times for medical-grade alternatives. Pediatric and neonatal intensive care units demonstrate lowest price sensitivity due to dead space minimization requirements, while commercial building HVAC contractors exhibit highest sensitivity to thermal efficiency per dollar metrics.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp trade lanes elevates inbound logistics costs for hygroscopic membrane raw materials sourced from the Basel-Zurich polymer science corridor. Manufacturing concentration in Germany, Switzerland, and the Yangtze River Delta feeds from specialized aluminum smelter networks, electrospun nanofiber production facilities, and precision metalworking clusters. Single-source vulnerability concentrates in thermal conductivity-grade aluminum exceeding 200 W/m·K specifications, where long-term offtake agreements with Canadian and Norwegian primary producers dominate procurement strategy. Distribution runs through direct manufacturer agreements with group purchasing organizations, displacing independent distributor relationships in German and US acute care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement network consolidation and group purchasing organization centralization, fragmenting vendor access for smaller manufacturers without direct channel control or anesthesia system bundling relationships.
For Market Incumbents: Shield premium positioning in critical care segments by deepening backward integration into electrospun nanofiber membrane production and securing notified body relationships for EU MDR Class IIa certification. Active heated humidification systems with precise temperature control represent a substitution threat in long-term ventilation cases exceeding 96 hours, requiring defensive R&D investment in hybrid passive-active configurations. For New Entrants and Emerging Players: Lead with pediatric and neonatal circuit specialization where sub-50 mL dead space requirements create specification barriers for incumbent foam-based manufacturers. The German healthcare HVAC retrofit wave offers the most penetrable entry point, with energy recovery ventilation mandates driving demand for building-integrated plate heat exchangers without the certification burden of critical care applications. A regulatory package bundling strategy—offering ISO 18562-4 testing services alongside product supply—addresses biocompatibility certification bottlenecks for smaller competitors. For Investors and Strategic Acquirers: Electrospinning-capable polymer science specialists with neonatal dead space expertise represent the most attractive acquisition target archetype for long-term positioning through the projection horizon. These firms capture margin concentration as membrane material science displaces conventional foam elements in premium configurations. Watch FDA 510(k) pathway friction for novel membrane geometries as an inflection indicator—extended premarket timelines signal consolidation pressure favoring established testing protocol holders.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 18562-4 Testing Service Bundling | Biocompatibility certification bottlenecks create adjacent revenue streams for regulatory package providers. |
| Electrospun Nanofiber Capacity Expansion | Sub-30 mL dead space achievement captures neonatal intensive care specification share from foam incumbents. |
| Direct GPO Channel Control | Hospital procurement centralization favors manufacturer agreements over independent distributor relationships. |
| German HVAC Retrofit Partnership | Energy recovery ventilation mandates accelerate building-integrated heat exchanger specification upgrades. |
| Hybrid Passive-Active R&D Investment | Active humidification substitution threat in long-term ventilation requires defensive product architecture development. |
Study Parameters
Desk research of FDA 510(k) filings, EU MDR notified body guidance documents, and German healthcare construction standards preceded structured interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and anesthesia system manufacturers. Primary fieldwork with clinicians and regulatory affairs leads validated secondary findings on ISO 18562 biocompatibility certification timelines. Customs data on aluminum thermal conductivity-grade imports and hospital procurement database extracts provided volume anchor points. Bottom-up segment modeling triangulated against top-down macro healthcare construction expenditure trends.
Variance decomposition across product architecture, material grade, and end-use certification tiers shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include plate versus shell and tube versus rotary configurations, stainless steel versus aluminum versus plastic material grades, and healthcare facility versus commercial building versus residential end users. CAGRs derived from installed base replacement cycles, energy recovery ventilation mandate implementation schedules, and neonatal intensive care unit expansion patterns. Aluminum price volatility assumptions and REACH substance restriction enforcement timelines fed sensitivity analysis.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR Class IIa enforcement intensity or German healthcare construction standard adherence would require recalibration. Forecasts reflect assumptions on membrane material substitution rates, hospital procurement centralization velocity, and primary aluminum smelter capacity expansion. Regulatory pathway friction, commodity input volatility, and active humidification technology advancement represent specific revision triggers. Recalibration cycles align with material shifts in notified body guidance, energy efficiency code updates, and REACH substance restriction enforcement deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
Commercial HVAC Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
India Chillers Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Compressor Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Global Air Conditioner Market