
 Global Heat Exchangers Market | 2026-2036
Global Heat Exchangers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heat Exchangers Market Analysis
ASME Section VIII certification is rotating the competitive landscape toward pressure-rated fabrication capabilities. Alfa Laval leverages its plate heat exchanger specialization to dominate high-efficiency HVAC and industrial installations across Europe and Asia. Danfoss sustains technology leadership through advanced brazed plate designs that serve refrigeration and climate control applications. Kelvion Holding GmbH anchors its position with extensive shell and tube portfolios for power generation and heavy process industries.
A heat exchanger is a thermal transfer device that facilitates energy exchange between two or more fluids at different temperatures, typically constructed with specified tube diameters, plate corrugation patterns, or fin densities to achieve target heat transfer coefficients and pressure drop characteristics; its primary purpose is to recover waste heat, regulate process temperatures, or condense vapors across industrial, commercial, and power systems. Plate heat exchangers command the fastest growth trajectory due to compact footprint advantages and modularity for capacity scaling in chemical processing and food manufacturing. Shell and tube configurations retain the largest installed base and margin pools in oil and gas refining, where high-pressure tolerance and fouling resistance justify premium material specifications in stainless steel and exotic alloys.
The EPA enforces emissions limits that compel power generators and petrochemical operators to upgrade to higher-efficiency heat recovery systems, while the EU F-Gas Regulation and Ecodesign Directive mandate minimum thermal performance thresholds that filter non-compliant equipment from European markets. China's MEE implements dual carbon goals that accelerate replacement of legacy shell and tube units in provincial steel and cement clusters. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional efficiency benchmarking to align product portfolios with procurement criteria that now embed lifecycle thermal performance into capital expenditure decisions.
Market Dynamics
ASME Section VIII certification requirements are concentrating fabrication capabilities among pressure-rated specialists while the EU F-Gas Regulation and China's dual carbon goals simultaneously compress equipment replacement cycles across industrial clusters.
Growth Catalysts
- EU Green Deal thermal mandates:The EU F-Gas Regulation and Ecodesign Directive enforce minimum efficiency thresholds that filter non-compliant equipment from European installations, accelerating replacement demand in Germany and France.
- Chemical processing expansion:Rising capacity buildouts in specialty chemicals and polymer production amplify equipment replacement cycles, particularly for corrosion-resistant plate configurations in batch reactor cooling loops.
- China's MEE enforcement:Provincial steel and cement clusters face mandatory retirement of legacy shell and tube units under dual carbon goals, concentrating demand in Shandong and Jiangsu industrial zones.
Market Restraints
- Nickel and titanium price volatility:Exotic alloy input costs swing unpredictably, squeezing margin pools for stainless steel and titanium-clad fabricators serving offshore and chemical applications.
- ASME certification concentration:Pressure vessel fabrication capabilities cluster among a limited base of certified shops in the US Gulf Coast and German Ruhr region, creating supply bottlenecks for large-format shell and tube orders.
- Air-cooled heat exchanger substitution:Dry cooling systems displace water-cooled configurations in water-stressed regions of Spain and Australia, eroding addressable volume for traditional wet-surface designs.
Strategic Opportunities
- India's PLI scheme tailwinds:Production-linked incentives for green hydrogen and petrochemical capacity create virgin demand for compact plate heat exchangers in Gujarat and Maharashtra industrial corridors.
- Refrigerant transition convergence:Low-GWP refrigerant chemistry and microchannel aluminum fabrication are converging to enable next-generation climate control systems for commercial HVAC retrofits.
- Digital twin integration:Predictive maintenance platforms and IoT sensor networks open recurring revenue streams through performance-based service contracts in European district heating utilities.
Industry Challenges
- ASME Section VIII welder certification gaps:Qualified pressure vessel welders remain scarce in North American fabrication yards, extending lead times for coded pressure equipment by 12-16 weeks.
- Legacy system integration friction:Retrofitting compact plate designs into existing shell and tube footprints demands custom piping manifolds and control logic reconfiguration, complicating brownfield deployments.
- Cross-border carbon accounting complexity:Evolving EU carbon border adjustment mechanisms require lifecycle thermal performance documentation that many Asian fabricators cannot yet supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heat Exchangers Market |
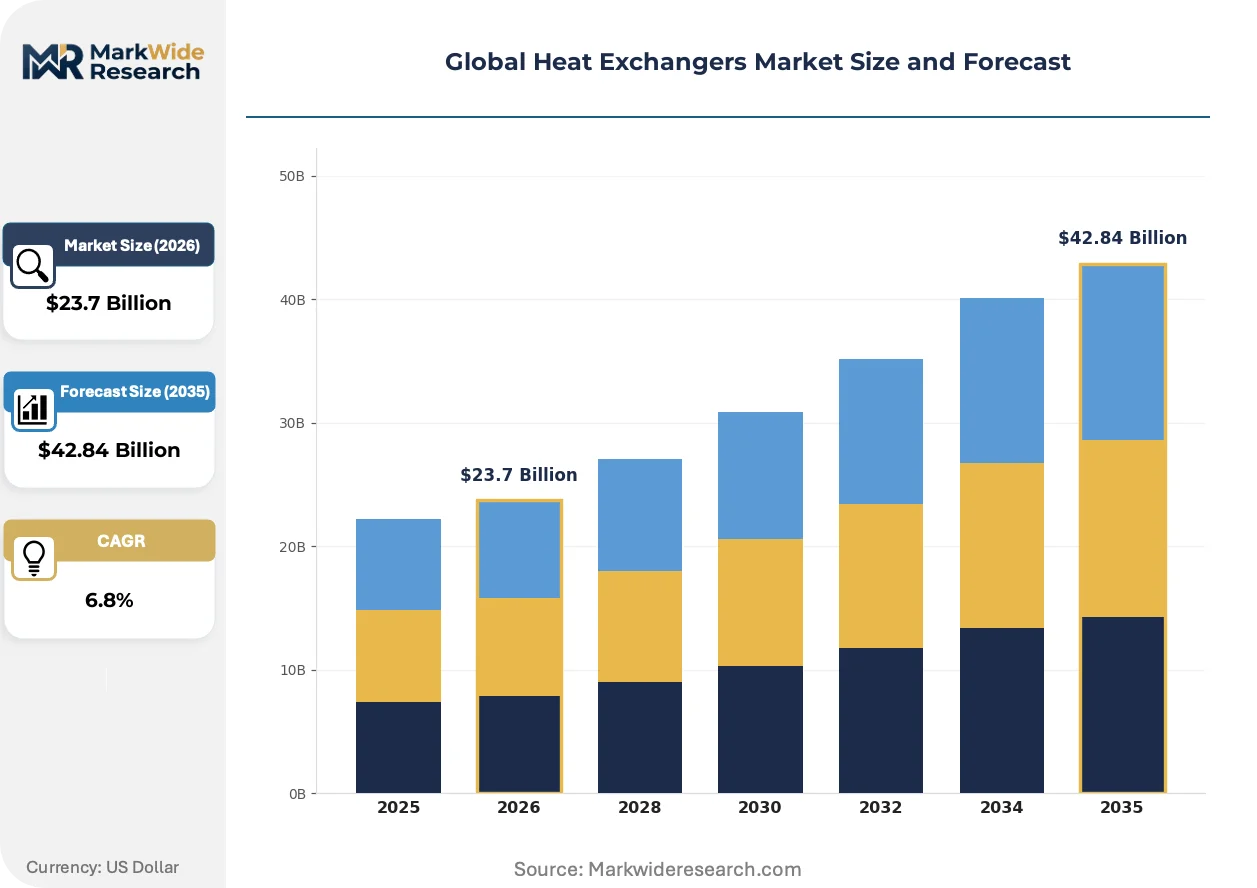
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell & Tube, Plate, Air Cooled, Double Pipe Application: Power Generation, HVAC, Chemical Processing, Food & Beverage Material: Aluminium, Copper, Stainless Steel, Carbon Steel End User: Oil & Gas, Automotive, Industrial, Commercial |
| Companies Covered | Alfa Laval, Danfoss, Kelvion Holding GmbH, Xylem, SPX Flow, API Heat Transfer, SWEP International, GEA Group, Mersen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heat Exchangers Market Emerging Trajectories
Additive manufacturing of heat transfer surfaces is compressing prototyping cycles while enabling geometries impossible through conventional stamping or rolling, reshaping how OEMs validate new corrugation patterns.
Printed circuit heat exchanger (PCHE) technology, constructed from chemically etched stainless steel plates diffusion-bonded into monolithic blocks, handles extreme pressure-temperature combinations for supercritical CO2 power cycles. Oil and gas operators in the North Sea and US Permian Basin are piloting PCHE units for compact gas processing skids. The technology is fragmenting the high-pressure heat recovery segment by displacing traditional shell and tube footprints with tenfold density improvements.
The EPA's emissions limits for power generators and petrochemical operators compel upgrades to higher-efficiency heat recovery systems, while the EU F-Gas Regulation tightens thermal performance thresholds for equipment placed on European markets. Combined cycle gas turbine operators in Texas and Louisiana face simultaneous pressure from both regulatory regimes, driving procurement toward certified high-efficiency recuperators.
Lifecycle cost contracting is displacing upfront capital purchasing in European district heating and Scandinavian pulp and paper installations. Energy service companies now guarantee thermal output per euro invested, shifting technical risk onto equipment suppliers. This model concentrates in Denmark and Sweden where municipal utilities possess long-term concession agreements and standardized performance benchmarking protocols.
Global Heat Exchangers Market Segmentation
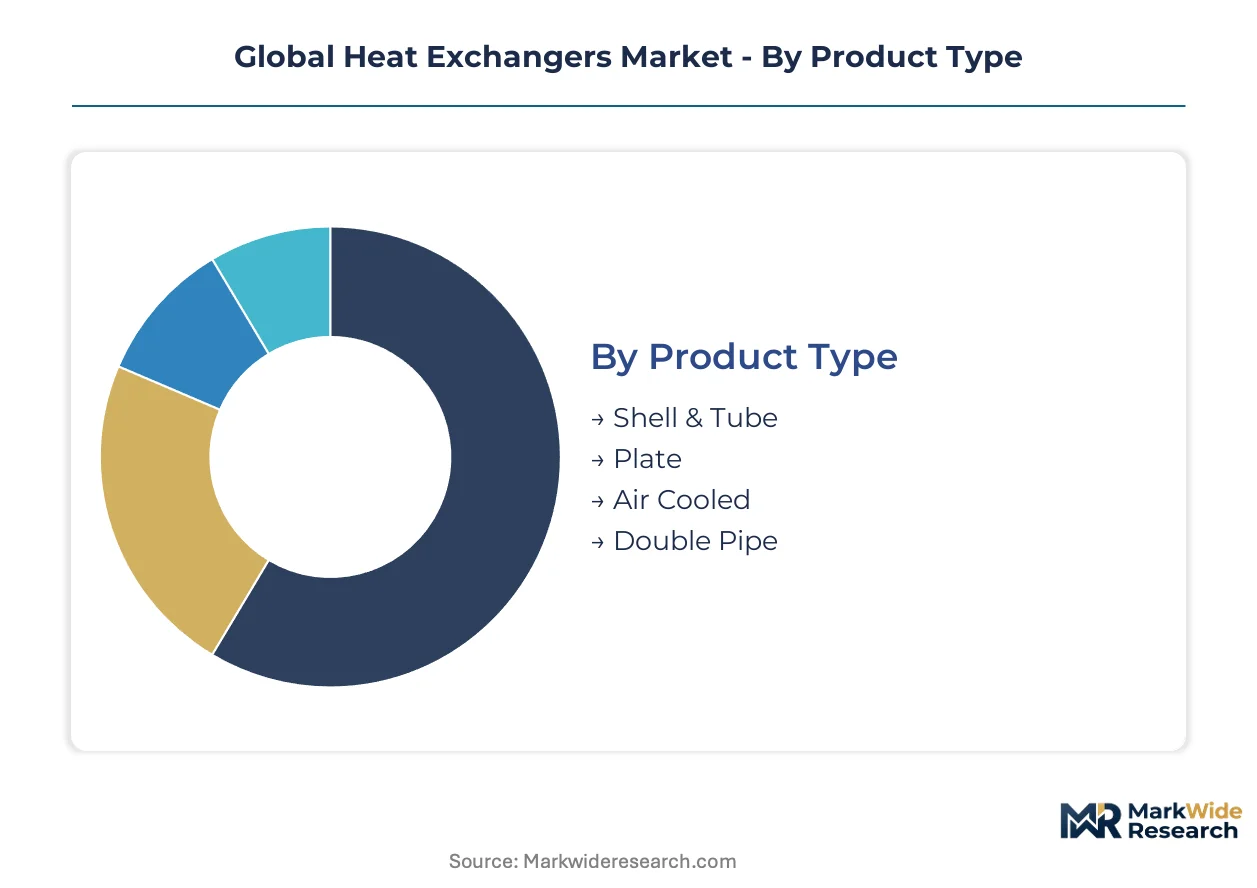
Segmentation reveals how substitution pressures and regulatory mandates reshape procurement patterns across equipment categories. Understanding these divisions exposes where margin pools concentrate and which specifications face the steepest efficiency-driven displacement.
Product Type:
Air-cooled designs exert the strongest substitution pressure on water-cooled configurations as water scarcity tightens operational constraints across industrial clusters.
- Shell & Tube:Constructed from cylindrical pressure vessels containing tube bundles for fluid separation, these units tolerate extreme pressures and temperatures. Demand concentrates in Texas and Louisiana refineries where ASME Section VIII certification is mandatory for hydrocracker and catalytic reformer service. The EPA's emissions limits compel upgrades to higher-efficiency heat recovery systems in these installations.
- Plate:Stacked corrugated plates create turbulent flow channels with high heat transfer coefficients in compact footprints. German and French chemical processors favor these for batch reactor cooling loops under EU F-Gas Regulation efficiency mandates. China's MEE enforcement accelerates replacement of legacy units in Shandong steel clusters.
- Air Cooled:Finned tube bundles forced by ambient air eliminate cooling water consumption entirely. Spanish and Australian operators deploy these in water-stressed regions where dry cooling systems displace wet-surface designs.
- Double Pipe:Concentric tube arrangements handle small-scale heat transfer with minimal fouling risk. These serve auxiliary cooling duties in offshore platforms and remote pipeline stations.
Shell and tube anchors the volume base while plate configurations gain share at the steepest rate.
Application:
Cost tier differentiation separates premium-specification installations from standardized equipment procurement.
- Power Generation:Combined cycle gas turbine recuperators and condensers require certified pressure ratings and thermal performance guarantees. Texas and Louisiana operators face simultaneous EPA and EU regulatory pressure driving procurement toward high-efficiency units.
- HVAC:Commercial building climate control systems prioritize compact footprints and modularity for retrofit installations. Danish and Swedish district heating utilities now demand lifecycle cost contracting with performance guarantees per euro invested.
- Chemical Processing:Corrosion-resistant plate configurations dominate specialty chemical and polymer production capacity buildouts. Batch reactor cooling loops in Gujarat and Maharashtra industrial corridors create virgin demand under India's PLI scheme.
- Food & Beverage:Sanitary plate designs with clean-in-place capability serve pasteurization and sterilization duties. These applications emphasize surface finish specifications and regulatory compliance documentation.
HVAC commands the broadest installed base while chemical processing applications expand most quickly.
Material:
Supply concentration for exotic alloys creates margin volatility that ripples through fabrication economics.
- Stainless Steel:Austenitic grades 304 and 316 dominate chemical and food processing applications where corrosion resistance justifies premium pricing. Jiangsu and Shandong fabricators face carbon border adjustment documentation requirements for European export orders.
- Aluminium:Microchannel extrusions enable lightweight, high-surface-area designs for commercial HVAC and automotive climate control. Low-GWP refrigerant chemistry convergence drives next-generation system development.
- Copper:Superior thermal conductivity suits small-diameter tubing in residential HVAC and refrigeration applications. Price volatility constrains procurement planning for high-volume OEMs.
- Carbon Steel:Cost-effective standard for low-corrosion environments in power generation and heavy industry. ASME certification requirements concentrate fabrication capabilities among pressure-rated specialists.
Stainless steel dominates value capture while aluminium climbs fastest in climate-control applications.
End User:
Customer type segmentation separates project-based capital expenditure from recurring maintenance procurement.
- Oil & Gas:North Sea and US Permian Basin operators pilot printed circuit heat exchanger technology for compact gas processing skids. Extreme pressure-temperature combinations demand specialized fabrication capabilities.
- Industrial:Pulp and paper installations in Scandinavia adopt performance-based service contracts with guaranteed thermal output. Municipal utilities with long-term concession agreements standardize benchmarking protocols.
- Automotive:Thermal management systems for electric vehicle battery packs and power electronics create emerging specification requirements. Compact brazed plate designs serve cabin climate control and powertrain cooling.
- Commercial:Building owners and facility managers prioritize energy efficiency retrofits with rapid payback periods. IoT sensor networks enable predictive maintenance platforms for recurring revenue streams.
Industrial end users anchor replacement demand while automotive applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation enforcement and China's dual carbon goals are compressing equipment replacement cycles across industrial clusters. National efficiency mandates in Germany, China, the United States, India, and Japan are redirecting procurement toward certified high-performance units.
Germany
Chemical processors in the Ruhr region favor compact plate configurations for batch reactor cooling loops. The EU Ecodesign Directive filters non-compliant equipment from German installations. BASF and Bayer facilities in Ludwigshafen and Leverkusen accelerate retirement of legacy shell and tube units under thermal performance benchmarking protocols.
China
Provincial steel and cement clusters face mandatory equipment upgrades under MEE dual carbon enforcement. GB standards for industrial energy efficiency tighten procurement criteria for heat recovery systems. Shandong and Jiangsu industrial zones concentrate demand for corrosion-resistant plate heat exchangers in petrochemical capacity expansions.
United States
Texas and Louisiana refineries require ASME Section VIII certification for hydrocracker and catalytic reformer service. EPA emissions limits compel power generators to upgrade heat recovery systems. Houston Ship Channel petrochemical operators pilot printed circuit heat exchanger technology for compact gas processing skids.
India
Production-linked incentives for green hydrogen and petrochemical capacity create virgin demand in Gujarat and Maharashtra industrial corridors. Bureau of Indian Standards certification requirements shape procurement specifications for imported equipment. Reliance and Adani facilities in Jamnagar and Mundra scale district heating and refinery capacity buildouts.
Japan
Automotive thermal management systems for electric vehicle battery packs drive specification requirements for compact brazed plate designs. METI energy efficiency standards accelerate HVAC retrofit cycles in commercial buildings. Toyota and Honda supply chain clusters in Aichi Prefecture demand high-surface-area microchannel configurations for powertrain cooling.
Global Heat Exchangers Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with pressure vessel fabrication capabilities and specialized heat transfer technology firms. Market structure concentrates among ASME-certified shops in the US Gulf Coast and German Ruhr region, with European and Asian specialists competing on compact plate designs. Strategic archetypes include full-service industrial groups, pure-play heat transfer specialists, and regional fabrication houses. Dominant competitive moves involve M&A to secure coded pressure vessel capabilities and geographic expansion to capture India's PLI-driven demand.
Among European-based industrial groups, Alfa Laval and Danfoss occupy positions exemplifying the premium-tier specialization archetype, while Kelvion Holding GmbH represents the pressure-rated fabrication specialist model. These three anchors illustrate how competitive positioning stratifies across HVAC climate control, industrial process cooling, and heavy-duty power generation applications.
| Leading Market Players |
|---|
| Alfa Laval |
| Danfoss |
| Kelvion Holding GmbH |
| Xylem |
| SPX Flow |
| API Heat Transfer |
| SWEP International |
| GEA Group |
| Mersen |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at ASME-certified fabrication yards in the US Gulf Coast and German Ruhr region determines price floors across pressure-rated equipment tiers, compressing margin pools for non-certified competitors while elevating premiums for coded shell and tube orders.
Pricing Analysis
Certification level (ASME Section VIII/CE/GB-grade) creates the primary spread between premium and standard tiers. Project-based contract pricing dominates, with differentiation resting on pressure rating tolerance and exotic alloy specifications. Cost compression in stainless steel and titanium-clad configurations is intensifying because nickel price volatility feeds directly into fabrication economics. Municipal utilities in Scandinavian district heating markets exhibit lowest price sensitivity due to lifecycle cost contracting models, while commercial HVAC retrofit buyers in Spain and Australia prioritize rapid payback periods.
Supply Chain Analysis
China and India anchor raw material processing and component fabrication for carbon steel and stainless steel heat transfer surfaces. The supply chain draws from nickel ore concentrates in Indonesia, titanium sponge from Japan, and aluminum extrusions from domestic Chinese mills. Single-source vulnerability concentrates in ASME-certified welder pools, where qualified pressure vessel fabricators remain scarce. Distribution runs through direct OEM sales for large-format shell and tube units and specialized distributors for compact plate configurations serving HVAC and food processing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Heat Exchangers Market is entering a cyclical recovery phase as industrial capacity buildouts in chemical processing and power generation accelerate equipment replacement cycles suppressed during prior investment pauses.
For Market Incumbents: Compound technology leadership in compact plate designs through additive manufacturing capabilities that compress prototyping cycles for next-generation corrugation patterns. Defend margin position by securing captive supply of exotic alloy inputs amid nickel price volatility, while extending ASME certification coverage into India's Gujarat and Maharashtra industrial corridors before PLI-driven demand peaks. For New Entrants and Emerging Players: Predictive maintenance platform integration represents the service-layer gap where incumbents under-serve European district heating utilities. Target Denmark and Sweden municipal operators with IoT-enabled performance guarantees, leveraging lifecycle cost contracting adoption to bypass capital-intensive fabrication capabilities. Deploy digital twin technology as the primary go-to-market angle, converting technical risk into recurring revenue streams. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with installed base service contracts in Scandinavian pulp and paper and European district heating verticals. Long-term viability over the next decade hinges on carbon border adjustment compliance capabilities and dual carbon goal alignment. Monitor ASME Section VIII welder certification queue lengths as the inflection indicator for supply-side pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Expansion | Unlocks access to Texas and Louisiana refinery procurement where EPA emissions limits compel upgrades. |
| Exotic Alloy Backward Integration | Captures margin pools eroded by nickel volatility in North Sea and Permian Basin offshore applications. |
| Digital Twin Platform Launch | Enables performance-based contracts with Danish and Swedish municipal utilities standardizing benchmarking protocols. |
| Printed Circuit Heat Exchanger Scale-Up | Displaces traditional shell and tube footprints in supercritical CO2 power cycles for combined cycle gas turbine operators. |
| India PLI Corridor Joint Venture | Positions for virgin demand in Gujarat and Maharashtra green hydrogen and petrochemical capacity buildouts. |
Methodological Framework
A standing panel of plant engineers at Texas and Louisiana refineries, procurement leads at German chemical processors, aftermarket service heads at European district heating utilities, and EPC contractors specializing in power generation provided ongoing calibration across the analysis window. Primary interview findings were cross-referenced with secondary validation from EPA emissions filings, EU Ecodesign Directive compliance databases, Chinese MEE enforcement notices, SEC 10-K disclosures from listed industrial conglomerates, and customs trade data on nickel and titanium alloy imports. Bottom-up unit shipment estimates by product type and application were triangulated against top-down market value reconstruction.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including equipment configuration (shell and tube, plate, air cooled, double pipe), end-use industry (power generation, HVAC, chemical processing, food and beverage), material specification (stainless steel, aluminum, copper, carbon steel), and regional regulatory cluster (EPA-governed, EU F-Gas regulated, China MEE enforced, India PLI incentivized). CAGRs were derived from fitted growth curves incorporating industrial capacity utilization rates, replacement cycle compression factors, and efficiency mandate compliance deadlines. Industry-specific forecast inputs included ASME certification queue lengths and nickel LME price volatility indices.
Underlying assumptions cover sustained enforcement of EU F-Gas Regulation and China dual carbon goals, with deviation risk concentrated in carbon border adjustment mechanism implementation timelines and nickel supply disruptions from Indonesian ore export policies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Blowers Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Canada HVAC Equipment Market