
 United Kingdom Heat Pumps Market | 2026-2036
United Kingdom Heat Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Heat Pumps Market Insights
Installation service revenue is fragmenting between certified MCS-accredited contractors and manufacturer-direct fitting networks. Worcester Bosch Group leverages its nationwide installer certification program to sustain channel control across domestic retrofit projects. Viessmann Group anchors its position through captive heat pump production and in-house training academies for British heating engineers. Daikin competes on inverter-driven air-source systems optimized for the UK's moderate ambient temperatures.
A heat pump extracts thermal energy from ambient air, ground, or water sources and elevates it via vapor-compression refrigeration cycles to temperatures suitable for space heating and domestic hot water, typically achieving coefficient of performance ratings between three and five under standard test conditions. Air-source products dominate unit shipments due to lower capital outlay and minimal site disruption, though ground-source configurations command premium pricing where geological conditions permit borehole or slinky-trench collector arrays. Residential installation types absorb the majority of policy incentives, while inverter technology segments are displacing conventional fixed-speed compressors across new-build specifications.
The UK Department for Business, Energy and Industrial Strategy structures demand through the Boiler Upgrade Scheme voucher mechanism, while Part L Building Regulations mandate minimum efficiency thresholds that effectively exclude direct electric resistance heating from new dwellings. MCS certification requirements create a gatekeeping function that shapes installer capacity and consumer access to grant funding. Stakeholders must track whether future iterations of the Future Homes Standard extend heat pump mandates to existing housing stock or retain technology-neutral carbon targets.
Market Dynamics
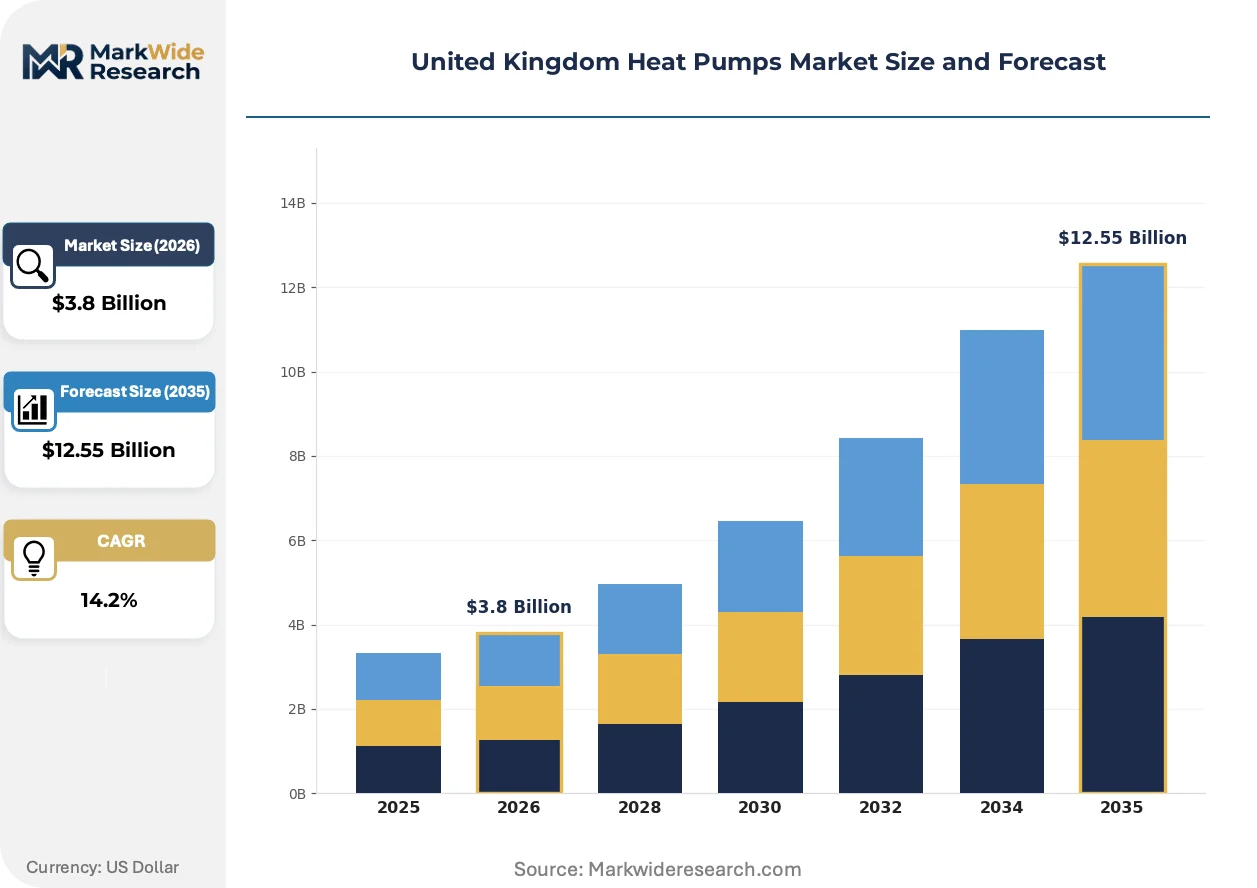
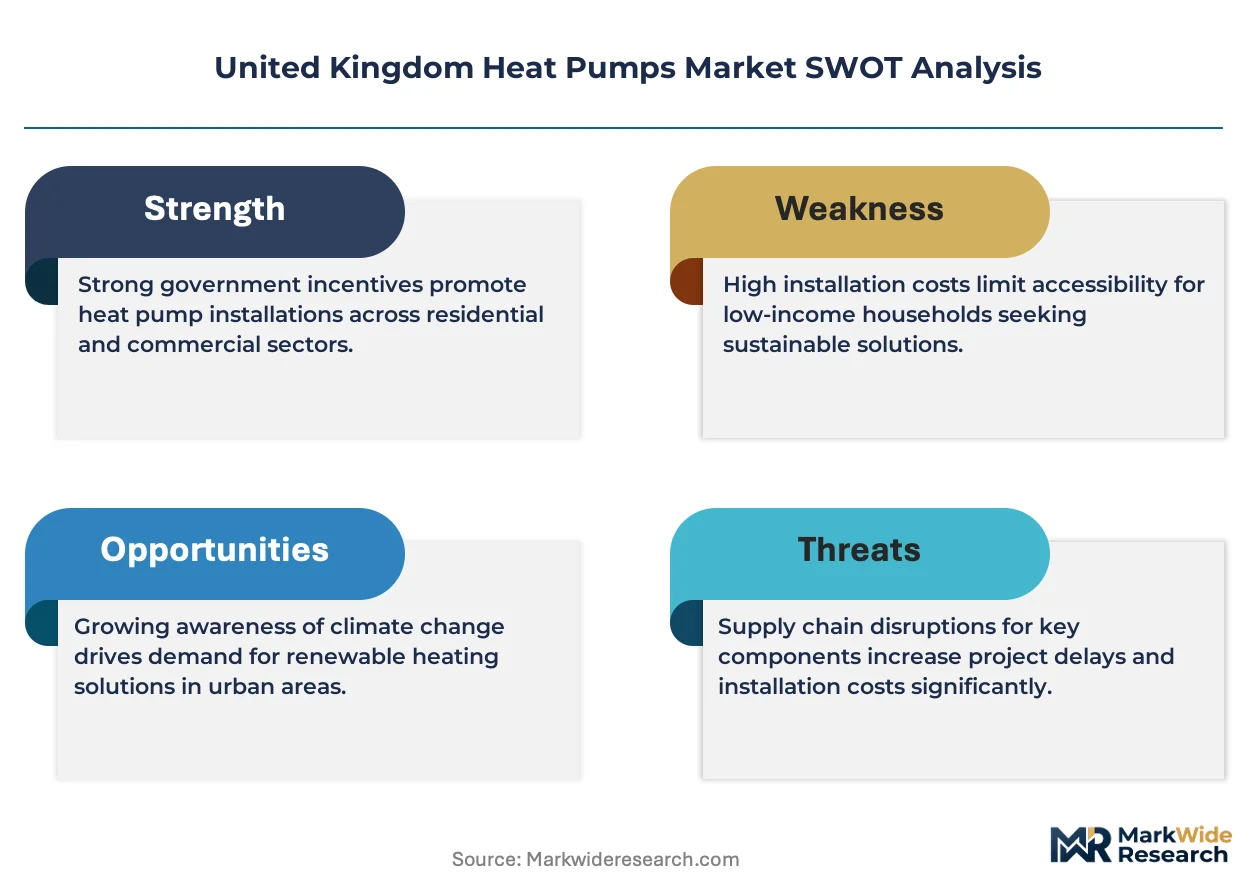
The UK heat pumps market pivots on regulatory compression forcing gas boiler displacement, with the Boiler Upgrade Scheme voucher mechanism and Part L Building Regulations creating artificial demand pull that outpaces installer capacity formation.
Growth Catalysts
- Boiler Upgrade Scheme:The UK Department for Business, Energy and Industrial Strategy voucher mechanism subsidizes residential retrofit installations, accelerating homeowner conversion from aging gas boilers.
- Part L Building Regulations:Minimum efficiency thresholds for new dwellings effectively exclude direct electric resistance heating, mandating heat pump specification in construction pipelines.
- Off-gas-grid housing stock:England's suburban properties in the South East and Midlands concentrate demand where no mains gas alternative exists.
Market Restraints
- Copper and refrigerant input volatility:Heat pump manufacturing depends on copper coil assemblies and HFC refrigerants subject to F-Gas Regulation phase-down schedules and commodity price swings.
- MCS certification gatekeeping:Microgeneration Certification Scheme requirements restrict installer pool expansion, creating supply-side bottlenecks that limit consumer access to grant funding.
- Direct electric resistance heating:Lower capital cost substitutes persist in rental and temporary housing segments where upfront heat pump investment cannot be recovered.
Strategic Opportunities
- Future Homes Standard extension:Potential mandate expansion to existing housing stock would amplify addressable market beyond new-build specifications.
- Hybrid heat pump-gas boiler systems:Technology convergence allows phased electrification for properties with insufficient insulation or radiator sizing for full heat pump conversion.
- Manufacturer-direct fitting networks:Channel innovation bypasses fragmented MCS-accredited contractor layers, capturing installation service margin in captive distribution models.
Industry Challenges
- Heating engineer retraining timelines:MCS certification and in-house manufacturer academy programs cannot scale fast enough to match policy-driven installation targets.
- Legacy radiator and pipework incompatibility:Domestic retrofit projects require system-wide upgrades that extend project duration and disrupt household occupancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Heat Pumps Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Hybrid, Water Source Installation Type: Residential, Commercial, Industrial, Retrofit Technology: Variable Speed, Inverter Technology, Conventional, Smart End User: Homeowners, Builders, Facility Managers, Energy Suppliers |
| Companies Covered | Vaillant Group, Worcester Bosch Group, Viessmann Group, Daikin, Panasonic, Baxi Heating UK, IMS Heat Pumps, Mitsubishi, Kensa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Heat Pumps Market Trends and Innovations
Technology hybridization and regulatory tightening are compressing traditional heating supply chains while reshaping how residential and commercial buyers procure low-carbon systems.
Inverter-driven compressor technology is hybridizing with conventional fixed-speed architectures to optimize performance across the UK's moderate ambient temperature range. Residential new-build specifications increasingly specify variable-speed systems that modulate output rather than cycle on-off. This convergence is enabling manufacturers to serve both high-efficiency new construction and retrofit markets with unified product platforms.
The UK F-Gas Regulation implements phased HFC refrigerant restrictions that force heat pump manufacturers toward lower-global-warming-potential alternatives. Industrial consequence includes accelerated R&D investment in propane and hydrofluoroolefin refrigerant circuits. Air-source product categories face the steepest compliance timeline, driving suppliers to redesign outdoor units ahead of 2027 cut-off thresholds.
Retrofit procurement patterns are fragmenting between turnkey MCS-accredited contractor packages and unbundled equipment-plus-installation sourcing. Homeowner buyers in England's suburban corridors increasingly separate equipment purchase from installation tender, compressing contractor margin capture. Channel disintermediation is most visible in the South East where manufacturer-direct fitting networks have established localized presence.
United Kingdom Heat Pumps Market Segmentation
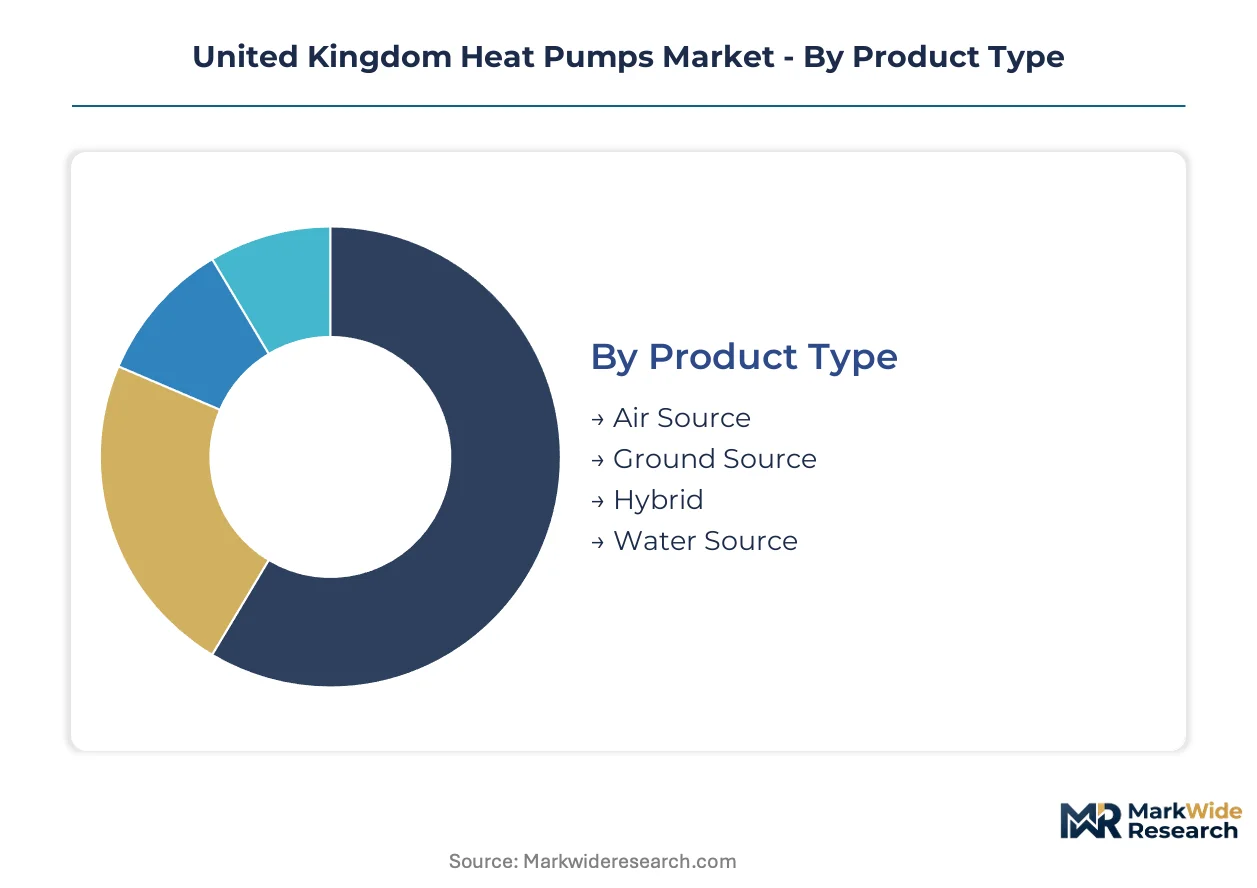
Segmentation reveals how after-sales service intensity varies dramatically across UK heat pump configurations. Installer certification requirements, maintenance protocols, and warranty structures differ by product complexity and application setting.
Product Type:
After-sales service intensity escalates with collector complexity and refrigerant circuit sophistication across UK deployment scenarios.
- Air Source:Outdoor unit configurations with finned-coil evaporators and hermetic scroll compressors dominate residential retrofits. Demand concentrates in England's South East suburban corridors where off-gas-grid properties cluster and MCS-accredited contractors maintain dense service networks.
- Ground Source:Closed-loop borehole or horizontal slinky-trench collector arrays paired with water-to-water heat pumps command premium installation and maintenance protocols. Deployment tracks geological suitability in the Midlands where clay and sandstone formations permit cost-effective ground coupling.
- Hybrid:Dual-fuel systems combining air-source heat pumps with condensing gas boilers require integrated control sequencing and dual-service competency.
- Water Source:Open-loop lake or river extraction configurations face Environment Agency abstraction licensing and specialized corrosion management.
Air Source holds the largest share; momentum sits with Hybrid configurations bridging retrofit feasibility gaps.
Installation Type:
Cost tier stratification separates capital-intensive new-build specifications from disruption-heavy retrofit conversions.
- Residential:Single-family and multi-occupancy dwellings absorb Boiler Upgrade Scheme voucher allocations. Demand concentrates in owner-occupied suburban stock where 25-year financing aligns with equipment depreciation.
- Commercial:Office, retail, and hospitality applications specify modular cascade systems with building management system integration. Deployment tracks Part L compliance deadlines for non-domestic building stock.
- Industrial:Process heat and warehouse applications require high-temperature output variants with ammonia or CO2 refrigerant circuits.
- Retrofit:Existing building conversions face radiator resizing, insulation upgrading, and pipework replacement that extend project timelines and service touchpoints.
Retrofit commands premium pricing tiers; Residential volume expansion is climbing the fastest.
Technology:
Customer type differentiation separates efficiency-optimizing variable systems from price-sensitive conventional specifications.
- Variable Speed:Electronically commutated motors and modulating compressors match thermal output to building load profiles. New-build specifications in southeast England increasingly mandate part-load optimization for Future Homes Standard compliance.
- Inverter Technology:Frequency-driven scroll and rotary compressors modulate capacity between 30% and 100% nominal output. Worcester Bosch and Daikin compete on ambient temperature performance curves suited to UK maritime climate conditions.
- Conventional:Fixed-speed on/off cycling architectures persist in rental housing and temporary structures where capital minimization overrides efficiency.
- Smart:Grid-responsive controls with demand-side response capability and remote diagnostics integrate with UK energy supplier tariff optimization programs.
Inverter Technology holds the largest share; momentum sits with Smart systems enabling grid flexibility services.
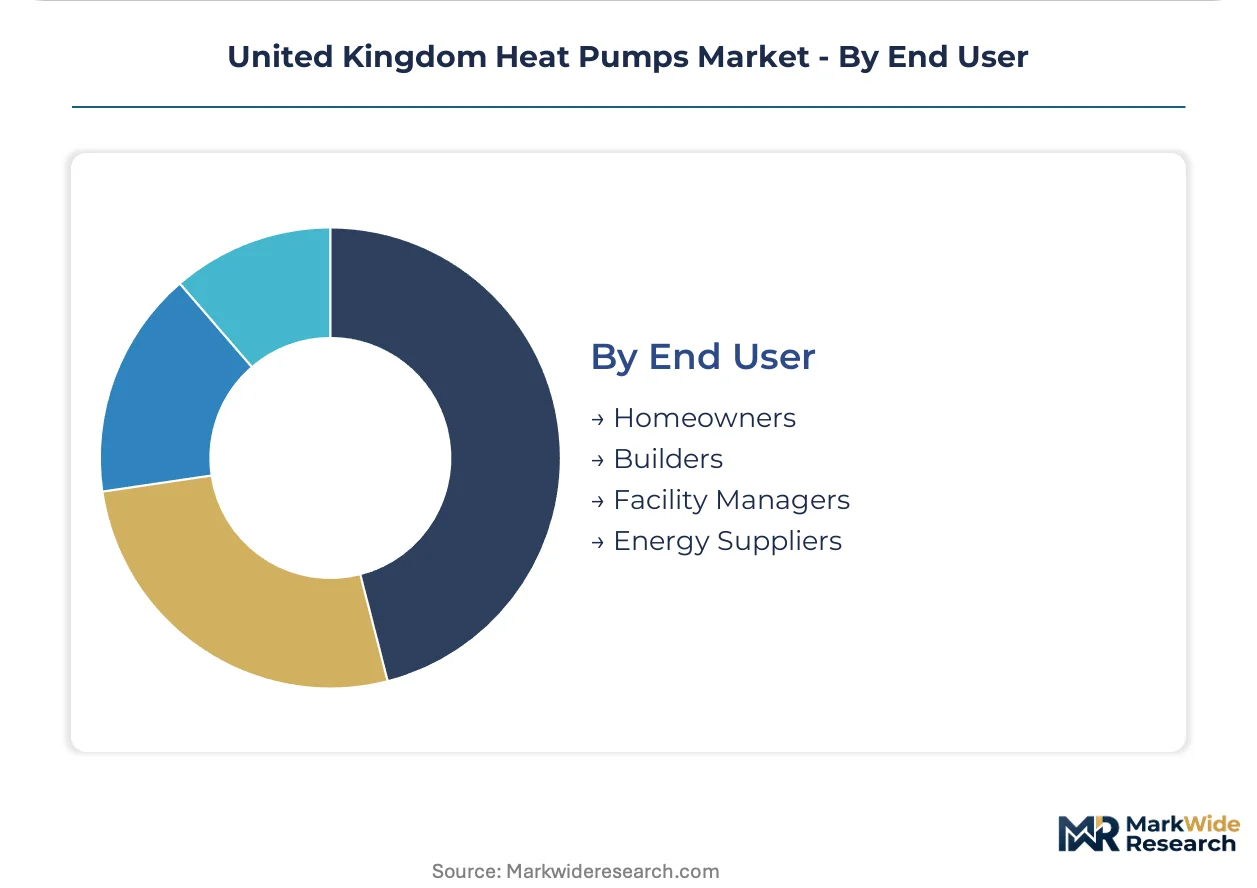
End User:
Margin structure varies by procurement sophistication and technical specification authority across buyer categories.
- Homeowners:Individual purchasers navigate MCS certification requirements and grant application processes with contractor guidance. South East England concentration reflects higher disposable income and off-gas-grid prevalence.
- Builders:Volume housebuilders specify standardized platforms across development portfolios with manufacturer framework agreements. Procurement centralization compresses unit pricing while demanding installation training commitments.
- Facility Managers:Commercial estate operators prioritize lifecycle costing and service contract bundling over capital expenditure minimization.
- Energy Suppliers:Utility-led electrification programs aggregate residential demand for bulk procurement and installation network coordination.
Builders hold the largest share; Energy Suppliers are expanding most quickly through aggregated demand programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer price sensitivity varies sharply across the United Kingdom. Rural off-gas-grid households in England's South East absorb premium retrofit costs, while urban rental markets in Northern England remain tethered to lower-capital alternatives.
London and the South East
Off-gas-grid suburban properties in Surrey, Kent, and Sussex generate concentrated heat pump demand. The Boiler Upgrade Scheme channels voucher funding through MCS-accredited contractors clustered around Guildford and Crawley. Installation service providers compete on financing packages aligned with 25-year equipment depreciation schedules.
Midlands
Geological suitability for ground-source borehole arrays distinguishes the clay and sandstone formations of Staffordshire and Warwickshire. The Future Homes Standard compliance deadlines for new housing developments in Birmingham and Coventry accelerate specification of variable-speed systems. Worcester Bosch maintains installer training academies in the region to address capacity constraints.
North England
Legacy gas boiler infrastructure and lower average household incomes suppress retrofit conversion rates in Yorkshire and Greater Manchester. Part L Building Regulations apply to new-build developments in Leeds and Sheffield, though rental housing stock resists capital-intensive electrification. Energy supplier aggregation programs attempt to unlock volume procurement.
Scotland
Rural housing dispersion and severe winter temperature profiles favor ground-source and hybrid system configurations in Aberdeenshire and the Highlands. The Scottish Government's Heat in Buildings Strategy supplements UK-wide voucher mechanisms with additional capital support. Installer certification backlogs in Edinburgh and Glasgow constrain grant uptake.
Wales
Off-gas-grid prevalence in rural Powys and Ceredigion matches English demand drivers, though installer network density lags. MCS-accredited contractor shortages extend project timelines for domestic retrofits in Cardiff and Newport new-build pipelines. Welsh building regulations track UK Part L minimum efficiency thresholds.
United Kingdom Heat Pumps Market Competitive Landscape
Capability concentration sits with German-engineered system specialists; scale advantage sits with Japanese electronics conglomerates with heat pump divisions. The vendor base stratifies into three tiers: premium integrated manufacturers, mid-market HVAC diversifiers, and regional installation service aggregators. Dominant competitive moves include captive installer certification programs and refrigerant circuit R&D ahead of F-Gas Regulation phase-down deadlines.
Within the premium-engineering tier, Worcester Bosch Group and Viessmann Group exemplify European manufacturers with captive British installer networks. Daikin anchors the Asian electronics contingent with inverter-driven product platforms optimized for UK maritime climate conditions. These three occupy positions across the pricing spectrum without overlapping segment focus.
| Leading Market Players |
|---|
| Vaillant Group |
| Worcester Bosch Group |
| Viessmann Group |
| Daikin |
| Panasonic |
| Baxi Heating UK |
| IMS Heat Pumps |
| Mitsubishi |
| Kensa |
| Others |
Pricing and Supply Chain Analysis
Copper coil and refrigerant input volatility compresses both pricing tier spreads and supply chain configuration in the UK heat pumps market. F-Gas Regulation phase-down schedules tether manufacturer margins to HFC availability, forcing tier differentiation by refrigerant circuit sophistication rather than brand premium alone.
Pricing Analysis
Installation service contracts and extended warranty bundles drive lifetime value capture across domestic retrofit segments. Three-tier pricing structure across premium, standard, and economy levels separates MCS-accredited turnkey packages from unbundled equipment-plus-labor sourcing. Cost compression in mid-market air-source configurations intensifies because manufacturer-direct fitting networks bypass contractor margin layers. Rental housing buyers exhibit highest price sensitivity; owner-occupied suburban households in England's South East absorb premium pricing for ground-source borehole arrays.
Supply Chain Analysis
UK F-Gas Regulation export-control restrictions on high-global-warming-potential refrigerants limit component flows from non-compliant overseas suppliers. Manufacturing draws from Germany for precision compressor assemblies, Japan for inverter drive electronics, and China for finned-coil heat exchangers. Single-source vulnerability concentrates in hermetic scroll compressor supply. Distribution runs through MCS-accredited contractor networks and manufacturer-direct fitting channels to residential end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK heat pumps market sits at a regulatory-driven inflection where Boiler Upgrade Scheme voucher mechanisms and Future Homes Standard tightening compress decade-long technology transition into a compressed installation window.
For Market Incumbents: Build installer certification moats through captive training academy scale-up that outpaces MCS backlog formation. Worcester Bosch Group and Viessmann Group should deepen backward integration into refrigerant circuit manufacturing to offset F-Gas supply restriction exposure. Channel control through direct fitting networks defends margin capture against unbundled procurement fragmentation. For New Entrants and Emerging Players: Build out hybrid heat pump-gas boiler system offerings targeting radiator-incompatible suburban retrofit properties where full electrification fails. Northern England rental housing and Welsh off-gas-grid corridors present penetrable white-space demand. Aggregated procurement partnerships with energy suppliers unlock volume access without MCS contractor network dependency. For Investors and Strategic Acquirers: The market sits at a policy-acceleration phase that favors vertically integrated manufacturers with captive British installer networks. Long-term viability hinges on refrigerant R&D positioning ahead of 2027 HFC phase-down deadlines. Acquisition targets should demonstrate F-Gas-compliant product pipelines and regional training infrastructure. The signal to watch is Future Homes Standard mandate extension to existing housing stock.| Strategic Initiative | Industry Significance |
|---|---|
| MCS Certification Academy Expansion | Installer capacity formation determines grant funding access velocity across England's suburban corridors. |
| Propane Refrigerant Circuit Development | F-Gas Regulation compliance secures product marketability ahead of 2027 HFC restriction deadlines. |
| Manufacturer-Direct Fitting Network Buildout | Channel disintermediation captures installation service margin in captive distribution models. |
| Hybrid System Platform Launch | Dual-fuel configurations bridge retrofit feasibility gaps for radiator-constrained properties. |
| Energy Supplier Aggregation Partnership | Bulk procurement coordination unlocks volume demand in Northern England rental housing segments. |
Research Methodology
A standing panel of MCS-accredited installation contractors, heat pump manufacturing product managers, Department for Business, Energy and Industrial Strategy policy officers, and energy supplier electrification program directors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against Boiler Upgrade Scheme disbursement records, Part L Building Regulation compliance filings, and F-Gas Regulation implementation guidance. Customs data on refrigerant imports and copper coil trade flows anchored supply-side triangulation alongside bottom-up installation volume tracking and top-down policy target reconciliation.
Scenario-bracketing around Boiler Upgrade Scheme voucher allocation trajectories and Future Homes Standard mandate scope variations bounded high-low growth paths across the projection horizon. Segmentation modeling incorporated product type, installation category, technology tier, and end-user procurement sophistication dimensions. CAGRs derived from policy-driven demand pull elasticity estimates cross-referenced against installer capacity formation constraints. Forecast inputs included MCS certification backlog projections and F-Gas refrigerant availability curves.
Sensitivities concentrate around Future Homes Standard mandate timing, F-Gas Regulation enforcement intensity, and MCS certification processing rate revisions. Forecasts reflect documented assumptions on policy continuity and supply chain adaptation timelines. Material shifts in Boiler Upgrade Scheme funding levels or refrigerant phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
Global Snow Making System Market