
 Canada Commercial HVAC Market | 2026-2036
Canada Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Commercial HVAC Market Insights
Performance-based maintenance contracts is restructuring how Canadian building operators procure HVAC lifecycle services. Carrier Corporation leverages its national service network to anchor long-term aftermarket revenue. Johnson Controls International competes through building automation integration that extends equipment monitoring into real-time energy management. Daikin Industries specializes in VRF system servicing, sustaining premium positioning in multi-zone commercial retrofits.
Canada Commercial HVAC encompasses mechanical systems designed to regulate temperature, humidity, and air quality within non-residential buildings, typically operating at capacities from 5 tons to over 1,000 tons with coefficient of performance ratings dictating energy consumption. These systems serve essential functions in preserving occupant health, protecting equipment, and maintaining operational continuity across commercial infrastructure. Rooftop units dominate existing building stock due to their modular installation and ease of replacement, though VRF systems are capturing fastest growth in urban multi-tenant properties where zoning flexibility commands premium pricing. Heat pump technology is displacing conventional gas-fired heating in new construction as building electrification mandates intensify, while hydronic systems retain stronghold status in institutional applications requiring stable thermal mass.
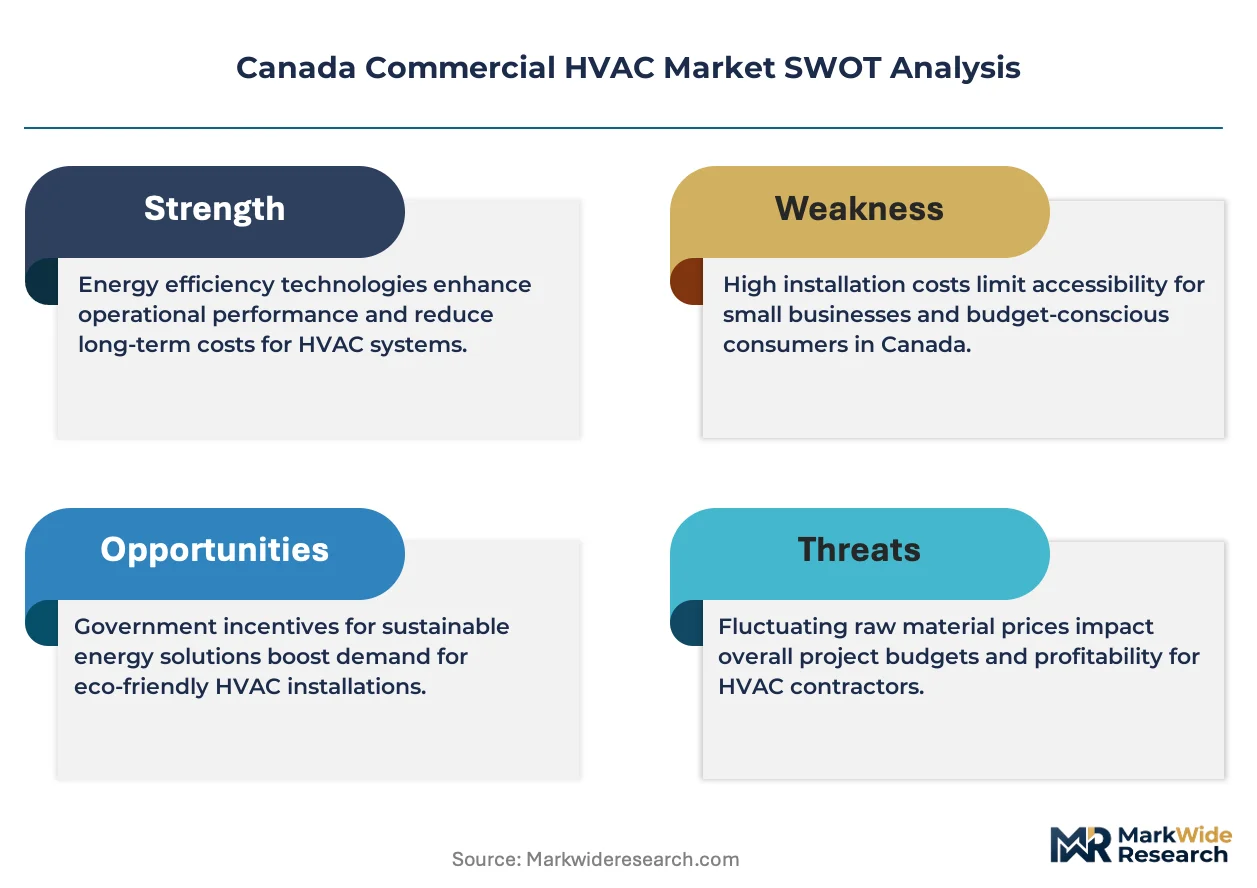
Health Canada sets indoor air quality guidelines that directly influence ventilation rate requirements and filtration specifications in commercial designs. Natural Resources Canada administers the Energy Efficiency Regulations under the Energy Efficiency Act, establishing minimum standards that filter non-compliant equipment from import and sale. Provincial regulators including Ontario's Technical Standards and Safety Authority enforce installation codes that shape contractor certification requirements and market access barriers. Stakeholders must monitor accelerating alignment between federal carbon pricing trajectories and municipal building performance standards that will redefine total cost of ownership calculations for replacement decisions.
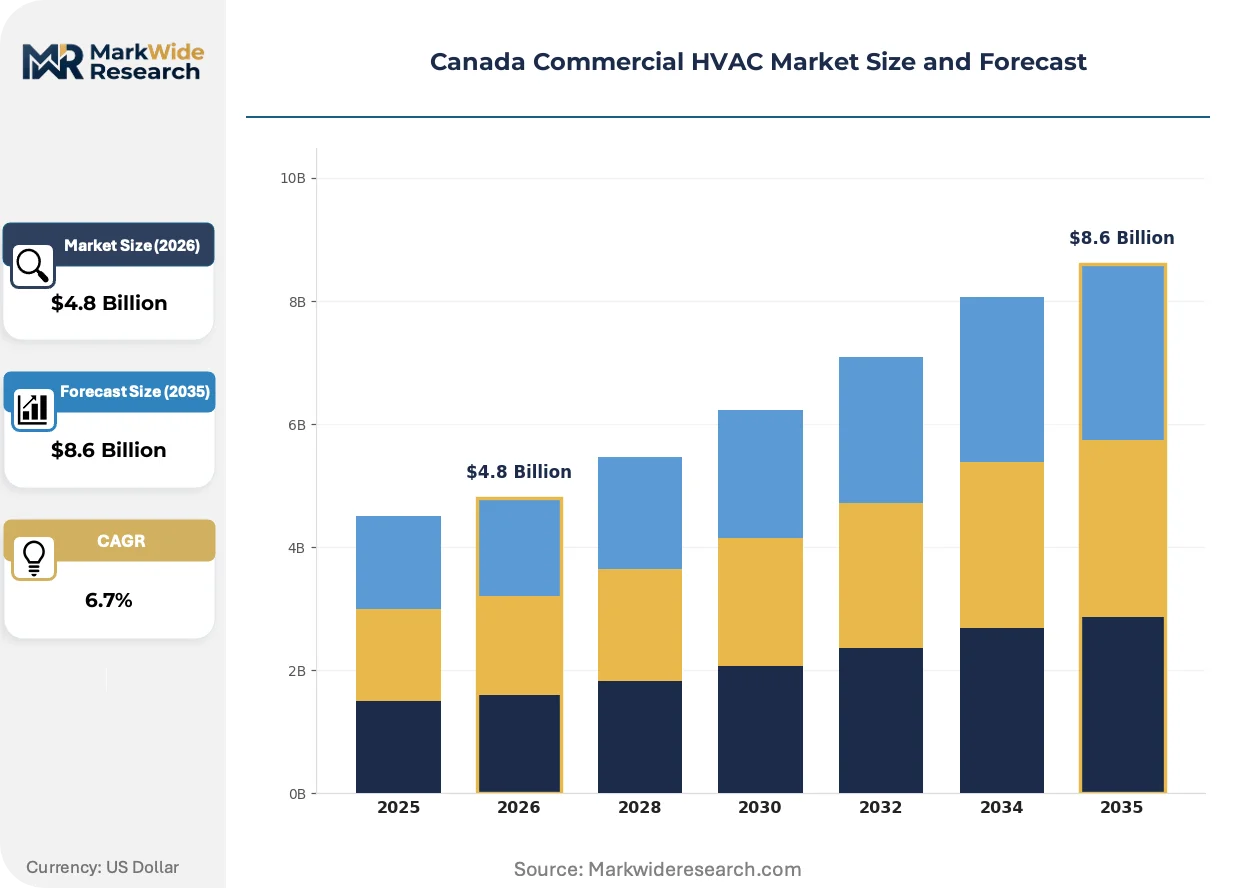
Market Dynamics
Natural Resources Canada's tightening Energy Efficiency Regulations are compressing equipment replacement cycles as building operators face stranded asset risk from non-compliant systems. Provincial carbon pricing trajectories now factor into total cost of ownership calculations.
Growth Catalysts
- Healthcare Infrastructure Expansion:Provincial governments are funding climate-controlled medical facilities across Ontario, Quebec, and British Columbia. These projects specify high-performance HVAC systems with dedicated outdoor air requirements.
- Building Electrification Mandates:Municipal performance standards in Vancouver and Toronto are accelerating heat pump adoption in new commercial construction. Natural gas hookup restrictions in select jurisdictions favor electric alternatives.
- Energy Efficiency Regulations:Natural Resources Canada's minimum performance standards filter non-compliant equipment from import channels. This regulatory pressure sustains replacement demand for higher-efficiency units.
Market Restraints
- Copper and Aluminum Price Volatility:Raw material cost swings compress manufacturer margins on commercial equipment. Input price uncertainty delays project bidding and procurement timelines.
- Certified Technician Shortage:Provincial trade certification requirements create bottlenecks in installation capacity. Ontario's Technical Standards and Safety Authority licensing limits contractor pool expansion.
- Refrigerant Transition Complexity:Provincial phase-down schedules for high-GWP refrigerants strand existing service infrastructure. Equipment incompatibility between refrigerant generations extends replacement cycles.
Strategic Opportunities
- Indigenous Community Infrastructure:Federal funding programs target northern and remote facility upgrades. These projects require cold-climate heat pump solutions with specialized engineering support.
- Building Automation Convergence:Integration of HVAC controls with energy management platforms creates premium service revenue. Real-time monitoring contracts extend customer relationships beyond equipment sales.
- Deep Energy Retrofits:Municipal building performance standards in Montreal and Vancouver mandate comprehensive system overhauls. Performance contracting models align contractor incentives with measured energy savings.
Industry Challenges
- Refrigerant Handling Certification:Provincial environmental regulations require specialized technician credentials for low-GWP alternatives. Training program capacity limits workforce scaling.
- Legacy Control Integration:Existing building automation protocols create interoperability friction with new equipment. Retrofit projects demand custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Commercial HVAC Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Boilers, Rooftop Units, VRF Systems Technology: Variable Speed Drive, Heat Pump, Direct Expansion, Hydronic End User: Office Buildings, Retail Spaces, Educational Institutions, Healthcare Facilities Installation Type: New Construction, Retrofit, Centralized, Decentralized |
| Companies Covered | Carrier Corporation, Trane Technologies, Johnson Controls International, Daikin Industries, Panasonic Holdings Corporation, LG Electronics, Rheem Manufacturing Company, Nortek Air Solutions, Robert Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Commercial HVAC Market Trends and Innovations
Equipment intelligence and refrigerant chemistry are converging to redefine commercial HVAC value propositions. Building operators now prioritize measurable energy outcomes over capital cost minimization.
Variable refrigerant flow technology is integrating advanced zoning controls with real-time occupancy sensing. Multi-tenant office properties in Toronto and Vancouver deploy these systems to allocate energy costs by actual usage. The technology is integrating tenant billing accuracy with demand response capabilities that qualify for utility incentive programs.
Natural Resources Canada's Energy Efficiency Regulations are tightening minimum coefficient of performance thresholds for commercial equipment. Non-compliant products face import prohibition, compressing manufacturer product line refresh cycles. Ontario's Greater Toronto Area building stock shows highest sensitivity to these standards due to dense commercial replacement activity.
Performance-based service agreements are displacing traditional break-fix maintenance contracts in institutional buyer segments. Universities and hospital authorities in Quebec and British Columbia now specify guaranteed uptime and energy efficiency outcomes. This procurement evolution concentrates contract value with national service networks capable of remote diagnostics and predictive intervention.
Canada Commercial HVAC Market Segmentation
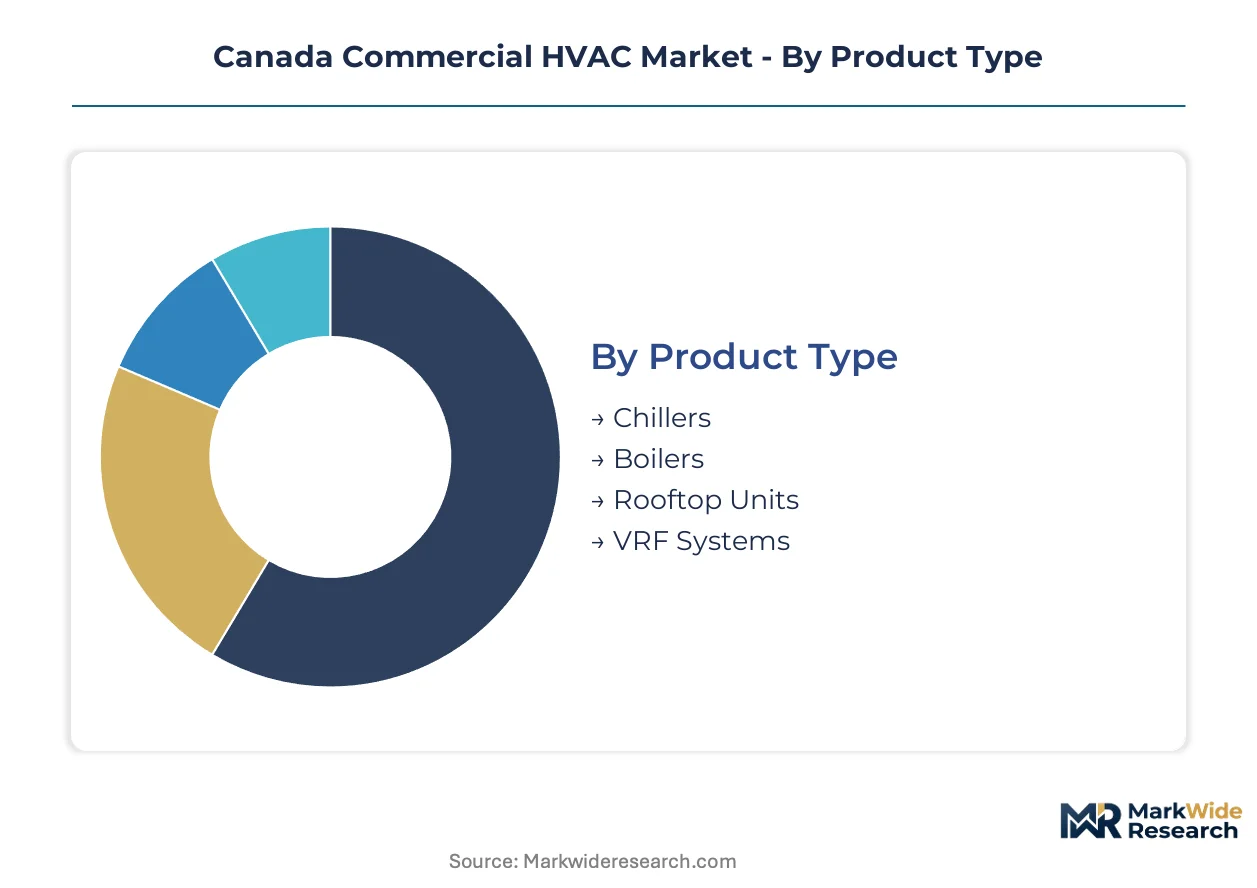
Capital deployment patterns across product categories reveal divergent equipment lifecycles and margin profiles. Procurement decisions in this market hinge on whether building operators prioritize upfront cost containment or long-term energy performance contracting.
Product Type:
Capital intensity varies sharply across equipment categories, with chillers and VRF systems demanding the highest upfront investment per ton of capacity while rooftop units minimize initial outlay.
- Chillers:Centralized water-cooled systems operate at capacities from 100 to over 1,000 tons, serving large institutional footprints with stable thermal loads. Ontario's hospital expansion programs specify magnetic bearing centrifugal chillers for their part-load efficiency advantages. Natural Resources Canada's efficiency regulations are compressing replacement cycles for aging chiller plants in Toronto's commercial core.
- VRF Systems:Variable refrigerant flow technology enables individualized zone control through a single outdoor condensing unit connected to multiple indoor fan coils. Vancouver's multi-tenant office towers favor these systems for tenant billing accuracy and demand response eligibility. British Columbia's building electrification mandates accelerate VRF adoption where gas hookup restrictions apply.
- Rooftop Units:Packaged systems dominate existing Canadian commercial stock for their modular installation and simplified maintenance access.
- Boilers:Hydronic heating equipment retains stronghold status in institutional applications requiring thermal mass stability.
Most installed capacity flows through Rooftop Units. Expansion is steepest in VRF Systems.
Technology:
Technology selection tracks regional energy pricing structures and electrification policy intensity across Canadian provinces.
- Heat Pump:Refrigeration-based heating technology extracts thermal energy from ambient air or water sources, achieving coefficient of performance ratings that exceed combustion alternatives. Toronto's municipal building performance standards mandate heat pump primacy in new commercial construction. Natural Resources Canada's tightening minimum performance standards filter lower-efficiency equipment from import channels.
- Variable Speed Drive:Electronically controlled motor modulation matches compressor and fan output to real-time thermal demand rather than cycling on-off. Quebec's university retrofits specify VSD-equipped chillers for their part-load efficiency advantages. Hydro-Quebec's incentive programs accelerate adoption in commercial sectors with high cooling degree days.
- Hydronic:Water-based distribution systems circulate heated or chilled fluid through terminal units, preserving thermal mass in large institutional footprints.
- Direct Expansion:Refrigerant-based cooling distributes conditioned air through ductwork without intermediate heat transfer fluid.
Heat Pump technology is capturing replacement share fastest in jurisdictions with carbon pricing exposure. Variable Speed Drive retrofits concentrate in provinces with elevated electricity rates.
End User:
End-use demand segmentation reflects divergent operational continuity requirements and indoor air quality regulatory exposure.
- Healthcare Facilities:Hospitals and clinics operate under Health Canada ventilation guidelines mandating dedicated outdoor air systems and enhanced filtration. Provincial capital programs in Ontario and British Columbia fund climate-controlled medical infrastructure. These installations specify redundant equipment configurations with guaranteed uptime contracting.
- Office Buildings:Commercial workspace properties prioritize tenant comfort metering and zone-level control for lease rate competitiveness. Toronto's Greater Toronto Area concentrates multi-tenant retrofit activity where energy cost allocation drives technology selection. Vancouver's municipal performance standards mandate deep energy retrofits for Class B and C office stock.
- Retail Spaces:Big-box and strip mall properties emphasize rapid installation and minimal operational disruption.
- Educational Institutions:Universities and school boards balance capital constraints against extended equipment lifecycles in publicly funded procurement.
Healthcare Facilities command premium pricing for infection control specifications. Office Buildings generate the highest retrofit transaction volume.
Installation Type:
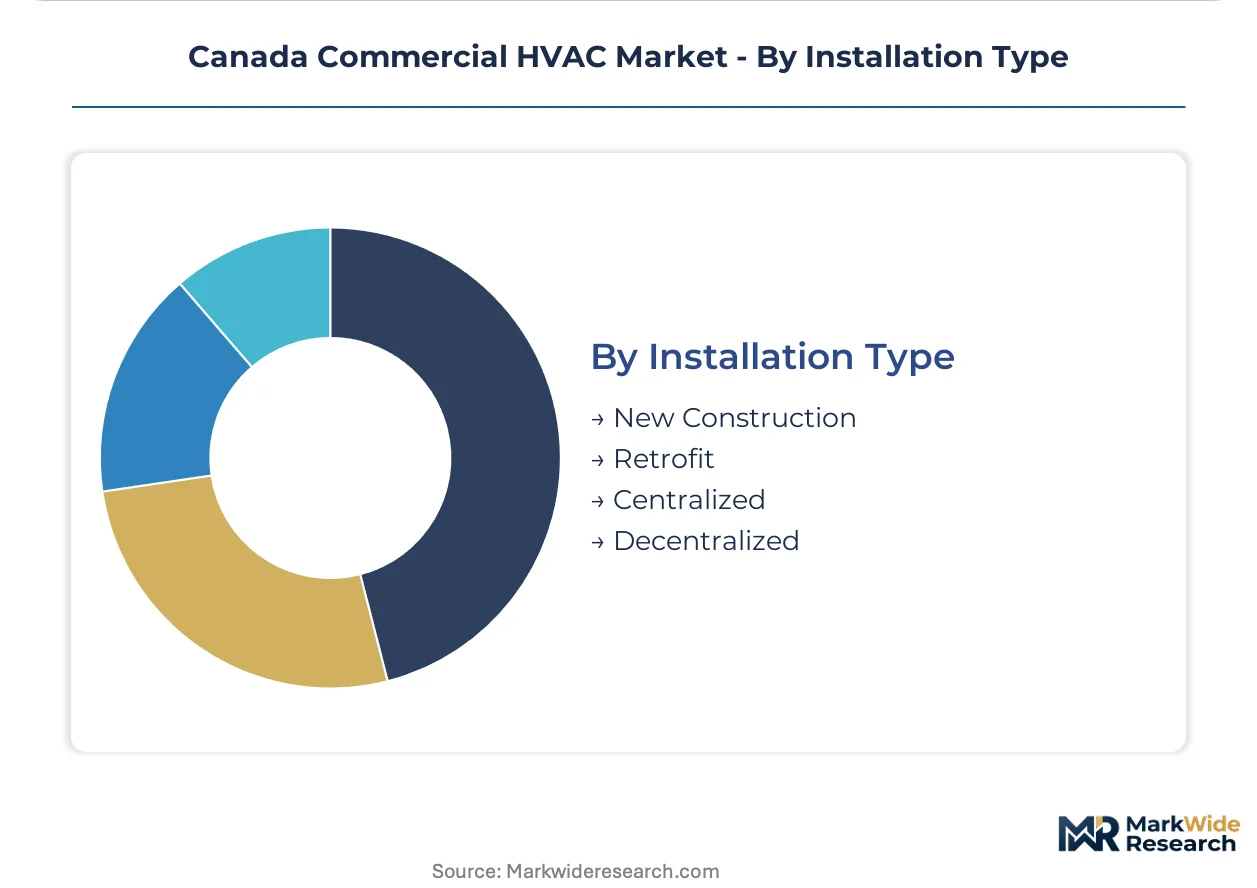
Installation mode segmentation tracks building age distribution and provincial energy retrofit program design.
- Retrofit:Equipment replacement in existing buildings navigates structural constraints, legacy control integration, and phased construction to maintain occupancy. Montreal's deep energy retrofit mandates target commercial stock built before 1990. Performance contracting models align contractor compensation with measured energy savings outcomes.
- New Construction:Greenfield installations specify integrated building automation and electrification-ready infrastructure from commissioning. Vancouver's building code amendments prohibit natural gas hookups in select commercial new builds. Toronto's Green Standard tiers mandate escalating efficiency performance for development approvals.
- Centralized:Single-plant configurations serve large contiguous footprints with uniform thermal loads.
- Decentralized:Distributed equipment placement enables zone-level redundancy and simplified maintenance access.
Retrofit activity dominates transaction volume in Ontario and Quebec. New Construction specifications concentrate in Vancouver and Toronto where municipal standards are most stringent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in commercial HVAC equipment favors provinces with less stringent carbon pricing trajectories, though tightening federal standards under Natural Resources Canada are compressing these gaps. Manufacturers and service providers are repositioning inventory and technical training capacity to align with provincial implementation schedules.
Ontario
The Greater Toronto Area concentrates Canada's densest commercial building stock and replacement activity. Ontario's Technical Standards and Safety Authority enforces installation codes that shape contractor certification requirements and market access barriers. Hospital expansion programs across Toronto, Ottawa, and Hamilton specify high-performance HVAC systems with dedicated outdoor air requirements and redundant equipment configurations.
Quebec
Hydro-Quebec's electricity rate structures and incentive programs accelerate adoption of variable speed drive retrofits in commercial sectors with high cooling degree days. The province's university and hospital authorities now specify guaranteed uptime and energy efficiency outcomes in performance-based service agreements. Montreal's deep energy retrofit mandates target commercial stock built before 1990, concentrating contract value with national service networks.
British Columbia
Vancouver's municipal building performance standards mandate deep energy retrofits for Class B and C office stock while prohibiting natural gas hookups in select commercial new builds. The province's building electrification mandates accelerate VRF adoption where gas restrictions apply. Multi-tenant office towers in Vancouver and Burnaby deploy variable refrigerant flow systems for tenant billing accuracy and demand response eligibility.
Alberta
Calgary and Edmonton's commercial property markets prioritize rapid installation and minimal operational disruption in retail and office retrofits. The province's carbon pricing exposure remains lower than coastal jurisdictions, though federal backstop mechanisms are narrowing this differential. Cold-climate heat pump deployment lags other provinces due to extended payback periods at current natural gas rates.
Canada Commercial HVAC Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated building automation providers capturing premium positioning in institutional procurement while equipment-focused suppliers dominate replacement transactions. The vendor base organizes into three tiers: national service networks with predictive maintenance platforms, regional contractors with deep local relationships, and emerging specialists in electrification-ready heat pump systems. Consolidation pressure intensifies as performance contracting models concentrate contract value with providers capable of remote diagnostics and guaranteed efficiency outcomes. Dominant competitive moves include backward integration into controls engineering and strategic partnerships with utility demand response programs.
Within the integrated building automation tier, Carrier Corporation, Johnson Controls International, and Daikin Industries exemplify divergent positioning strategies. Carrier leverages its national service network to anchor long-term aftermarket revenue through lifecycle service contracts. Johnson Controls competes through building automation integration that extends equipment monitoring into real-time energy management platforms. Daikin occupies a specialist position in variable refrigerant flow system servicing, sustaining premium positioning in multi-zone commercial retrofits where zoning flexibility commands pricing power.
| Leading Market Players |
|---|
| Carrier Corporation |
| Trane Technologies |
| Johnson Controls International |
| Daikin Industries |
| Panasonic Holdings Corporation |
| LG Electronics |
| Rheem Manufacturing Company |
| Nortek Air Solutions |
| Robert Bosch |
| Others |
Pricing and Supply Chain Analysis
Backward integration into compressor manufacturing anchors pricing power for national service networks serving Ontario's dense commercial building stock. This captive production of critical components insulates integrated vendors from copper and aluminum price volatility while compressing procurement timelines for healthcare and institutional buyers.
Pricing Analysis
Distributor margins on commercial equipment typically range from 15-22 percent for standardized rooftop units, while direct-to-OEM channels command steeper discounts on volume chiller contracts. Three-tier pricing structure across premium, standard, and economy levels separates magnetic bearing centrifugal systems from conventional screw compressors and entry-level packaged units. Cost compression in the standard tier is intensifying because Natural Resources Canada's tightening efficiency regulations force product line refreshes. Institutional buyers in Quebec and British Columbia demonstrate lowest price sensitivity due to performance contracting requirements, while Alberta retail property operators prioritize upfront capital containment.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Toronto hospital expansion programs and Vancouver multi-tenant towers. Manufacturing concentration in the United States, Mexico, and Japan feeds Canadian import channels with chillers, VRF systems, and heat pump components. Raw material dependencies on copper refrigerant tubing, aluminum heat exchangers, and rare-earth magnetic bearings expose margins to commodity volatility. Single-source vulnerability in semiconductor-based variable speed drive controllers creates procurement bottlenecks for smart equipment lines. Distribution runs through national service networks with regional stocking points in Calgary, Montreal, and Vancouver.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Commercial HVAC market represents a late-cycle quality story as building electrification mandates shift procurement specifications toward cold-climate heat pump systems with integrated building automation.
For Market Incumbents: Deploy predictive maintenance platforms to lock in long-term service revenue from institutional buyers. National service networks should acquire certified technician training capacity to address Ontario's Technical Standards and Safety Authority licensing bottlenecks. Backward integration into controls engineering defends margin position against emerging specialists in electrification-ready heat pump systems. For New Entrants and Emerging Players: Digital-channel routes through utility demand response program partnerships offer low-friction customer acquisition. Indigenous community infrastructure in northern provinces presents the most penetrable geography, with federal funding programs requiring specialized cold-climate engineering support. Performance-based contracting models align contractor compensation with measured energy savings, differentiating against traditional break-fix competitors. For Investors and Strategic Acquirers: Roll-up economics work for regional contractors with deep local relationships because municipal building performance standards concentrate contract value with providers capable of remote diagnostics. Five-to-ten year viability hinges on exposure to Vancouver and Toronto retrofit mandates versus Alberta's slower electrification trajectory. Watch Natural Resources Canada's refrigerant phase-down schedules as the inflection signal for stranded asset risk in existing service infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Performance Contracting Model | Aligns contractor incentives with measured energy savings outcomes in Montreal and Vancouver retrofits. |
| Building Automation Integration | Extends equipment monitoring into real-time energy management platforms for Ontario hospital authorities. |
| Cold-Climate Heat Pump Development | Captures federal funding programs targeting northern and remote Indigenous community infrastructure upgrades. |
| Certified Technician Training Expansion | Addresses Ontario's Technical Standards and Safety Authority licensing bottlenecks limiting contractor pool growth. |
| Utility Demand Response Partnership | Qualifies VRF installations for Hydro-Quebec incentive programs in high cooling degree day sectors. |
Research Methodology
Direct dialogue with HVAC contractors, building automation engineers, hospital facility directors, and provincial procurement officers grounded qualitative insights. Secondary validation drew from Natural Resources Canada Energy Efficiency Regulations filings, Ontario Technical Standards and Safety Authority licensing data, Health Canada ventilation guidelines, and municipal building performance standards in Vancouver and Toronto. Bottom-up equipment shipment analysis triangulated with top-down construction spending forecasts across the analysis window.
Segmented projections by product type, technology, end user, and installation mode fed into province-level demand modeling. The analytical framework incorporated healthcare infrastructure expansion timelines, building electrification mandate implementation schedules, and refrigerant transition pathways throughout the forecast period. CAGRs were derived from replacement cycle compression rates under tightening federal efficiency standards and provincial carbon pricing trajectories. Cold-climate heat pump adoption curves and VRF penetration rates in multi-tenant properties served as key demand inputs.
Commodity price volatility, regulatory delay, and technician training program capacity are the dominant revision risks to baseline projections. Forecasts reflect assumptions regarding federal carbon pricing continuity and municipal standard enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
ASEAN Heat Exchanger Market