
 Global Home Ventilation System Market | 2026-2036
Global Home Ventilation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Ventilation System Market Foresight
Subscription-based filter replacement and remote diagnostics is recalibrating how manufacturers monetize home ventilation beyond unit sales. Daikin Industries leverages its refrigerant expertise to anchor premium integrated heat-recovery offerings across Asian markets. Zehnder Group specializes in compact decentralized ventilation units for retrofits, occupying a niche that larger HVAC conglomerates struggle to serve. Panasonic Corporation extends its sensor portfolio into air-quality-linked ventilation automation, differentiating through real-time particulate and CO2 responsiveness.
A home ventilation system encompasses mechanical equipment designed to exchange indoor and outdoor air while controlling temperature, humidity, and contaminant levels, typically incorporating heat exchangers with recovery efficiencies between 70% and 95% and fans rated for continuous operation at low decibel levels. Its primary purpose is to maintain indoor air quality and thermal comfort in residential structures that achieve high airtightness through modern building envelopes. Positive pressure ventilators lead in new construction applications where controlled air distribution prevents moisture accumulation, while remote monitoring systems represent the fastest-expanding deployment category as homeowners seek app-based oversight of energy recovery performance. Portable ventilators remain a mature segment with limited growth, though they retain margin pools in emergency backup and temporary residential applications.
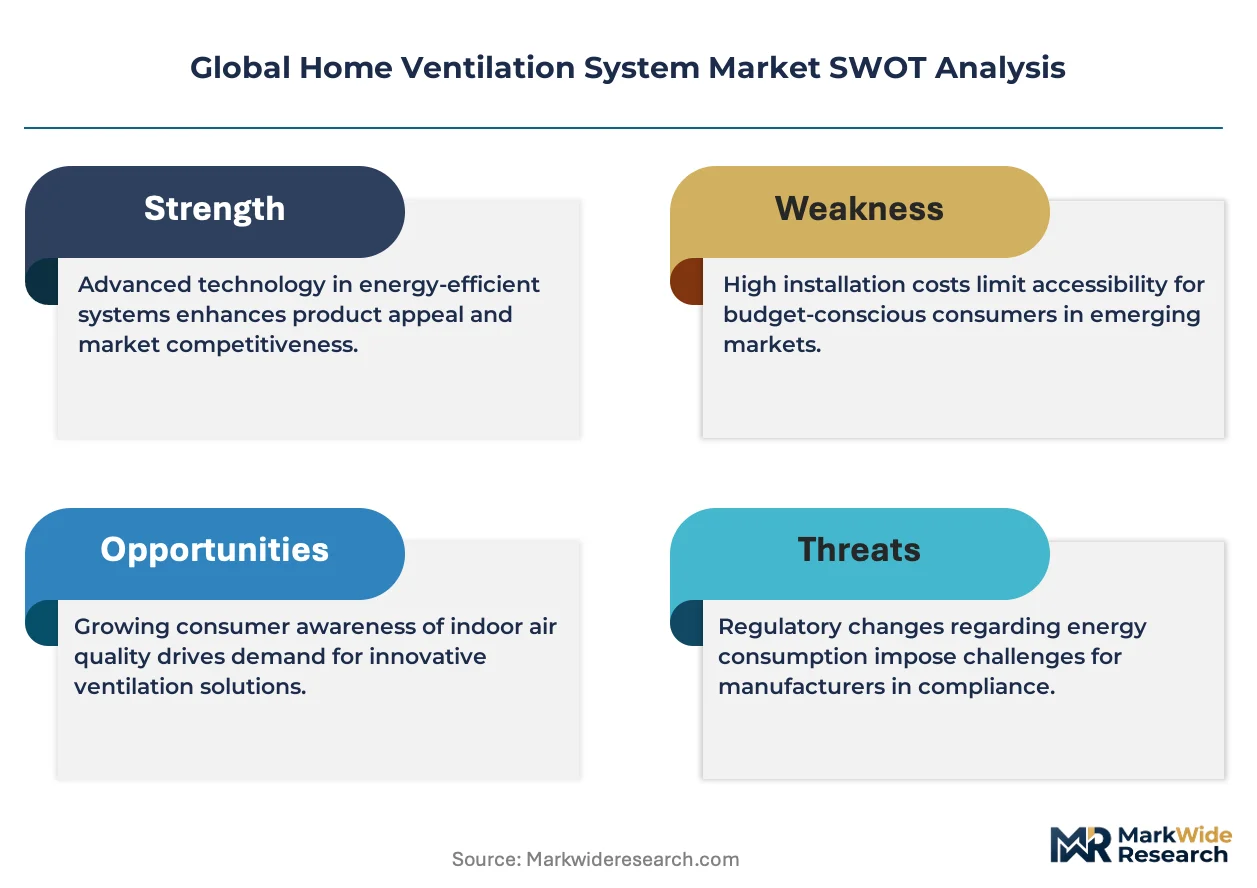
The EU Green Deal and F-Gas Regulation shape product development by restricting refrigerants in integrated heat-pump ventilation systems and mandating minimum energy recovery thresholds in member states. The EPA's Energy Star certification program in the United States filters market access by setting fan-efficiency benchmarks that exclude conventional constant-volume models from utility rebate eligibility. Japan's METI building energy standards push manufacturers toward higher heat-recovery ratios through performance-based compliance pathways. Stakeholders must weigh whether to prioritize heat-recovery efficiency gains or smart-home integration as the primary axis of product differentiation.
Market Dynamics
Building airtightness mandates across Germany, Japan, and Canada are forcing replacement of natural ventilation with controlled mechanical systems, compressing installation timelines and recalibrating contractor capacity planning.
Growth Catalysts
- EU Green Deal building renovation requirements:Tightened airtightness standards in multifamily housing retrofits mandate balanced ventilation with minimum heat-recovery thresholds, pulling demand toward centralized and decentralized recovery units.
- Suburban North American new construction:Residential developers in Texas, Florida, and Ontario are specifying mechanical ventilation with heat recovery as standard equipment in single-family subdivisions.
- Heat exchanger efficiency gains:Polymer membrane and aluminum plate technologies now achieve recovery rates between 70% and 95%, reducing auxiliary heating loads and accelerating payback calculations for homeowners.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger cores and fan motor windings depend on these inputs, exposing manufacturers to commodity swings that compress margin on fixed-price installation contracts.
- Skilled installer concentration in Germany and Austria:Certified ventilation technicians remain geographically clustered, creating bottlenecks for retrofit deployment in France, Italy, and Eastern European markets.
- Natural ventilation persistence in Mediterranean climates:Window-dependent cooling habits in Spain, Portugal, and Greece limit addressable market penetration despite regulatory pressure.
Strategic Opportunities
- India's emerging green building codes:The Bureau of Indian Standards and state-level energy conservation building codes are beginning to reference mechanical ventilation for high-rise residential, opening a largely unserved market.
- Sensor-integrated automation:Convergence of particulate matter sensing, CO2 monitoring, and variable-speed fan control enables real-time air quality responsiveness that commands premium positioning.
- Subscription filter replacement:Recurring revenue models for HEPA and activated carbon cartridge delivery are displacing one-time component sales in Germany and the Netherlands.
Industry Challenges
- Commissioning complexity with legacy HVAC:Integrating heat-recovery ventilation into existing forced-air systems in US and Canadian homes requires ductwork modification that extends project timelines and triggers cost overruns.
- Acoustic certification delays:Continuous operation at low decibel levels demands fan and housing designs that must pass country-specific sound testing, fragmenting product portfolios and slowing regional rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Ventilation System Market |
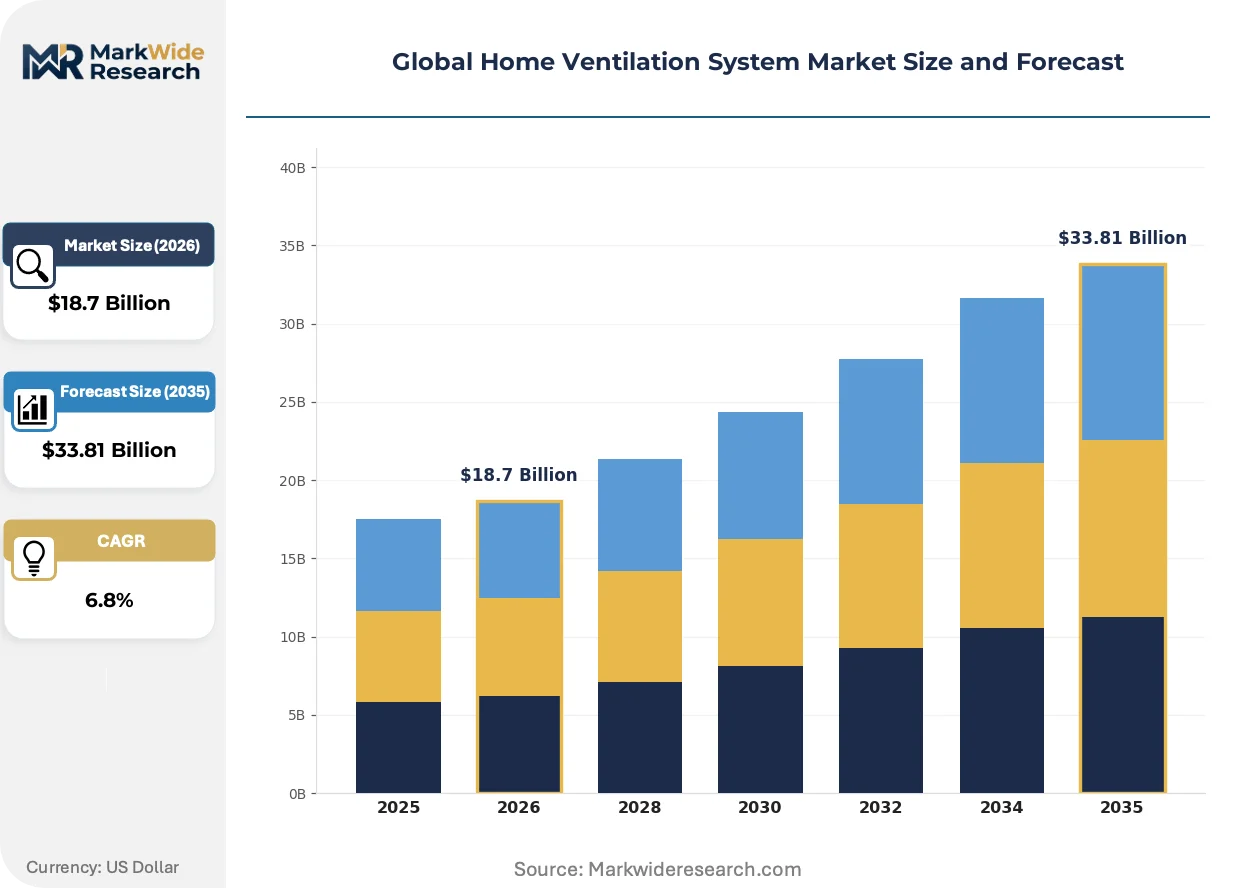
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Pressure Ventilators, Negative Pressure Ventilators, Biphasic Ventilators, Portable Ventilators Application: Chronic Obstructive Pulmonary Disease, Neuromuscular Disorders, Obstructive Sleep Apnea, Chest Wall Deformities End User: Home Care Providers, Respiratory Therapy Clinics, Specialized Nursing Facilities, Individual Patients Deployment: Standalone Systems, Integrated Ventilation Solutions, Remote Monitoring Systems, Mobile Ventilation Units |
| Companies Covered | Broan-NuTone LLC, Daikin Industries, Zehnder Group, Johnson Controls, Honeywell International, Lennox International, Mitsubishi Electric, Trane Technologies, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Ventilation System Market Shifts & Advancements
Product development is pivoting from standalone heat-recovery units toward integrated air quality platforms, with sensor networks and predictive maintenance software absorbing engineering resources previously allocated to core mechanical components.
Electrostatic precipitator modules are absorbing integration attention from manufacturers seeking to reduce filter replacement frequency and capture ultrafine particulates below PM2.5 thresholds. Premium residential developers in Germany and Switzerland are specifying these modules in new multifamily construction. The technology is absorbing margin pressure from rising HEPA media costs by extending service intervals from six to twenty-four months.
The F-Gas Regulation is compressing refrigerant options for integrated heat-pump ventilation systems, forcing manufacturers toward propane and CO2 alternatives with lower global warming potential. Equipment redesign cycles have accelerated in response, with EU-based engineering teams prioritizing compliance over feature expansion. Heat-pump-integrated units sold into Nordic markets face the strictest phase-down timelines, concentrating R&D investment in Scandinavian product lines.
Homeowner purchasing patterns are fragmenting across channel types, with direct-to-consumer online configurators displacing traditional HVAC contractor specification in Germany and the Netherlands. These platforms allow filter subscription bundling and remote diagnostic enrollment at point of sale. The shift is most visible in retrofit applications where decentralized ventilation units require less invasive installation than centralized systems.
Global Home Ventilation System Market Segmentation
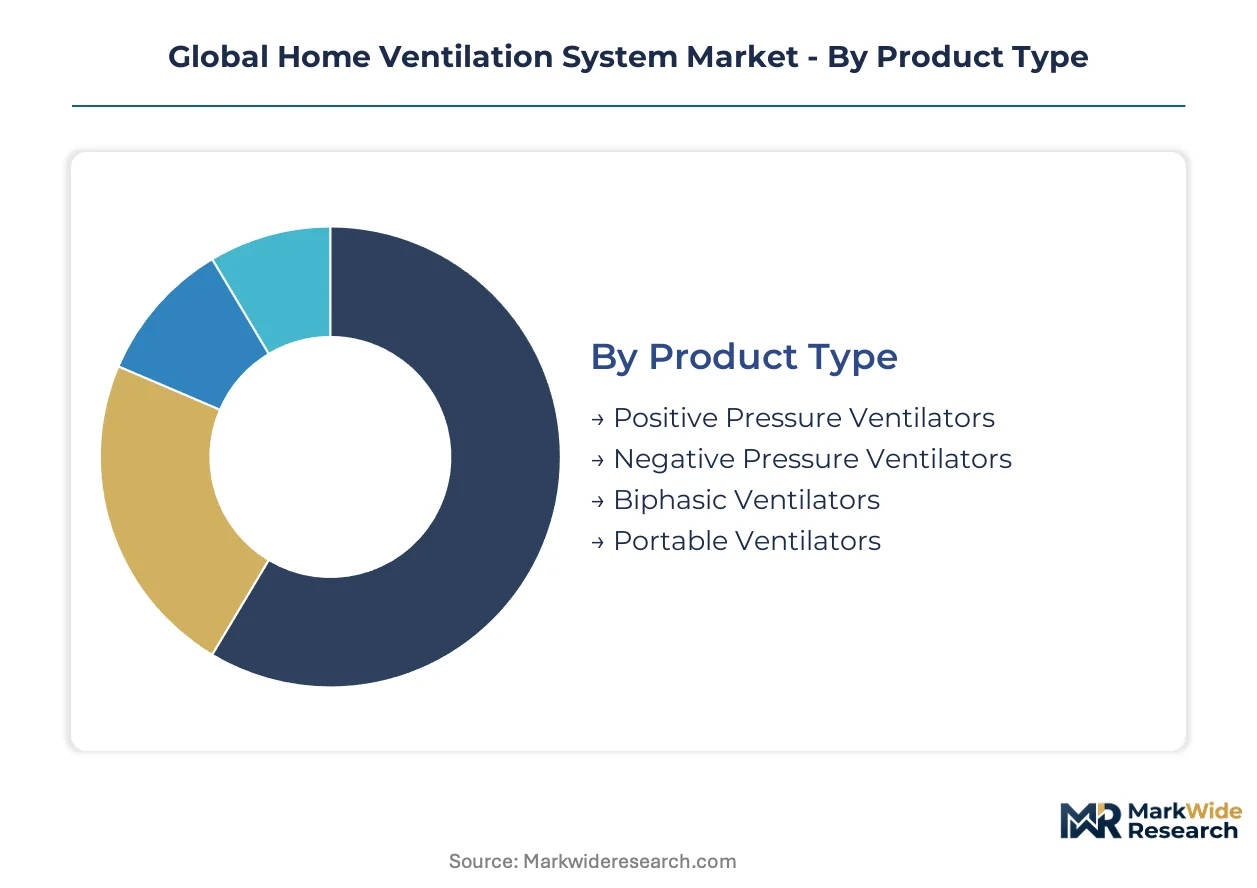
Home ventilation system segmentation reveals how clinical requirements, installation constraints, and care delivery models fragment demand across fundamentally different hardware configurations and service relationships. Understanding these divisions exposes where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
Volume sales concentrate in positive pressure systems for new residential construction, while premium positioning attaches to heat-recovery efficiency tiers and acoustic performance ratings.
- Positive Pressure Ventilators:These systems introduce filtered outdoor air to create slight indoor pressurization, preventing moisture infiltration and pollutant backdraft in airtight building envelopes. Demand clusters in suburban North American new construction where Texas, Florida, and Ontario developers specify mechanical ventilation as standard equipment in single-family subdivisions.
- Negative Pressure Ventilators:Designed to exhaust stale air and create slight depressurization, these units suit specific moisture-control applications and isolation scenarios. Deployment concentrates in specialized nursing facilities managing infectious disease protocols, though residential adoption remains limited by complex balancing requirements with makeup air strategies.
- Biphasic Ventilators:Dual-mode units alternating between positive and negative pressure cycles.
- Portable Ventilators:Compact battery-capable units for emergency backup and temporary residential applications.
Mature deployment sits with portable ventilators in emergency preparedness segments. Newer deployment is concentrated in positive pressure systems specified by North American residential developers.
Application:
Clinical indication severity determines whether systems require professional oversight or support independent home management.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation creates continuous ventilation dependency for advanced cases. Home care providers in Germany and Austria dominate procurement, driven by federal building energy ordinance requirements for controlled mechanical systems in multifamily housing retrofits.
- Neuromuscular Disorders:Diaphragmatic weakness necessitates nocturnal and eventually continuous ventilatory support. Respiratory therapy clinics in the Netherlands specify decentralized ventilation units with remote diagnostic capability, leveraging direct-to-consumer online configurators that bundle filter subscriptions at point of sale.
- Obstructive Sleep Apnea:Intermittent upper airway collapse requiring positive pressure during sleep periods.
- Chest Wall Deformities:Restrictive physiology from structural thoracic abnormalities.
Equipment refresh cycles run longest in obstructive sleep apnea. Steepest expansion trajectory appears in neuromuscular disorder management with integrated monitoring platforms.
End User:
Procurement authority splits between institutional buyers optimizing fleet economics and individual patients prioritizing acoustic comfort and app-based control.
- Home Care Providers:Regional service organizations managing device fleets across patient populations.
- Respiratory Therapy Clinics:Specialized facilities prescribing and titrating ventilation parameters.
- Specialized Nursing Facilities:Long-term care environments with centralized maintenance capabilities.
- Individual Patients:Direct purchasers through retail and online channels, concentrated in Germany and the Netherlands where decentralized retrofit units bypass contractor specification.
Institutional purchasing dominates in biphasic and negative pressure categories. Individual patient acquisition is climbing the fastest in positive pressure segments with consumer-facing configurators.
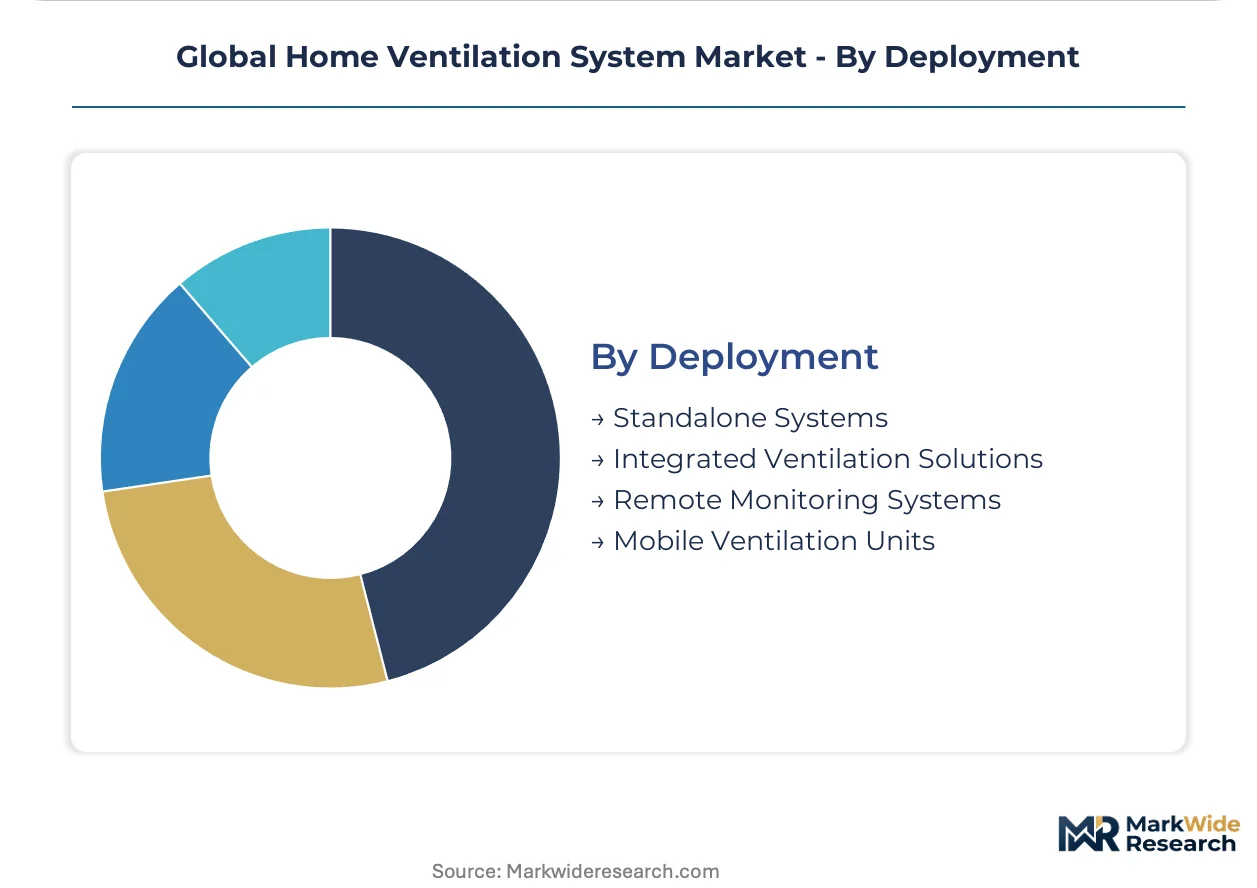
Deployment:
Installation complexity ranges from plug-and-play consumer units to whole-building integrated systems requiring ductwork modification.
- Standalone Systems:Self-contained units operating independently of building HVAC infrastructure.
- Integrated Ventilation Solutions:Heat-recovery ventilation embedded within comprehensive mechanical systems, achieving recovery rates between 70% and 95% through polymer membrane or aluminum plate exchangers.
- Remote Monitoring Systems:Sensor-integrated platforms enabling real-time oversight of energy recovery performance, particulate levels, and CO2 concentrations. These configurations command premium positioning in Germany and Switzerland where electrostatic precipitator modules extend filter service intervals from six to twenty-four months.
- Mobile Ventilation Units:Transportable equipment for temporary or emergency deployment.
Fixed infrastructure investment characterizes integrated solutions in Nordic markets facing strict F-Gas Regulation phase-down timelines. Gaining share fastest are remote monitoring systems with predictive maintenance software absorbing engineering resources from core mechanical development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters dominate heat-recovery ventilation manufacturing, while suburban North American construction absorbs volume shipments. Asian markets concentrate sensor-integrated automation development in Japan and South Korea.
United States
Texas and Florida developers specify mechanical ventilation with heat recovery as standard equipment in single-family subdivisions. The EPA's Energy Star certification program filters market access by setting fan-efficiency benchmarks that exclude conventional constant-volume models from utility rebate eligibility. Installation complexity with legacy HVAC in Midwest retrofit markets extends project timelines and triggers cost overruns.
Germany
The federal building energy ordinance drives replacement of natural ventilation with controlled mechanical systems in multifamily housing retrofits. EU Green Deal building renovation requirements mandate balanced ventilation with minimum heat-recovery thresholds, pulling demand toward centralized and decentralized recovery units. Certified ventilation technicians cluster in Bavaria and Baden-Württemberg, creating deployment bottlenecks for Eastern European markets.
Japan
METI building energy standards push manufacturers toward higher heat-recovery ratios through performance-based compliance pathways. Sensor-integrated automation development concentrates in Osaka and Nagoya industrial corridors. Real-time particulate and CO2 responsiveness commands premium positioning in Tokyo metropolitan new construction.
Canada
Ontario residential developers accelerate adoption of mechanical ventilation with heat recovery in suburban new construction. Natural Resources Canada's EnerGuide rating system shapes procurement specifications for energy recovery ventilators. Vancouver and Toronto metropolitan areas lead retrofit deployment amid tightening building airtightness codes.
Netherlands
Direct-to-consumer online configurators displace traditional HVAC contractor specification in retrofit applications. Filter subscription bundling and remote diagnostic enrollment capture recurring revenue at point of sale. Eindhoven and Randstad engineering clusters specialize in compact decentralized ventilation units for residential retrofits.
Global Home Ventilation System Market Competitive Landscape
Top-tier vendors anchor integrated system supply, while regional specialists occupy decentralized retrofit niches. The vendor base stratifies across three tiers: multinational HVAC conglomerates with refrigerant expertise, mid-scale ventilation specialists with acoustic engineering focus, and sensor-technology integrators with automation platforms. Strategic moves concentrate on heat-exchanger efficiency licensing and filter subscription service expansion.
Among Asia-Pacific-based industrial groups, Daikin Industries and Panasonic Corporation exemplify divergent positioning archetypes. Daikin leverages refrigerant expertise to anchor premium integrated heat-recovery offerings, while Panasonic extends sensor portfolios into air-quality-linked automation. Zehnder Group, a Swiss GmbH-structured specialist, occupies a compact decentralized ventilation niche that larger conglomerates struggle to serve.
| Leading Market Players |
|---|
| Broan-NuTone LLC |
| Daikin Industries |
| Zehnder Group |
| Johnson Controls |
| Honeywell International |
| Lennox International |
| Mitsubishi Electric |
| Trane Technologies |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Polymer membrane heat exchanger manufacturing is consolidating in German and Swiss engineering clusters, simultaneously compressing unit economics for decentralized ventilation units and concentrating procurement leverage among mid-scale specialists who control proprietary membrane formulations. This production-method transition favors buyers with volume commitment power while squeezing margin on spot-market component purchases.
Pricing Analysis
Margin tightening in standard-efficiency tiers reflects aluminum plate commoditization and fan motor oversupply from Chinese producers. Three-tier pricing structure across premium, standard, and economy levels separates electrostatic precipitator-integrated systems from basic heat-recovery units and emergency-grade portable equipment. Cost compression accelerates in retrofit segments as direct-to-consumer configurators bypass contractor markups. Home care providers exhibit highest price sensitivity due to fleet procurement economics, while premium residential developers in Germany and Switzerland absorb acoustic certification premiums with minimal negotiation.
Supply Chain Analysis
Dual-sourcing requirements from German and Dutch home care providers mandate qualified secondary suppliers for heat exchanger cores and sensor modules, fragmenting procurement across Germany, China, and South Korea. Raw material dependencies center on copper winding stock for fan motors, aluminum sheet for plate exchangers, and polymer resin for membrane substrates. Single-source vulnerability concentrates in specialized acoustic housing extrusions from Austrian metalworkers. Distribution runs through HVAC wholesale networks in North America and direct-to-consumer platforms in Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Home Ventilation System Market is becoming a vertical-integration race, with refrigerant expertise and filter subscription infrastructure representing the decisive downstream and upstream levers respectively.
For Market Incumbents: Anticipate margin compression from electrostatic precipitator module commoditization by locking exclusive supply agreements with polymer membrane formulators in Germany and Switzerland. Defensive positioning requires backward integration into sensor calibration capabilities to preserve premium positioning against Panasonic Corporation's automation platforms. Capacity concentration in Bavaria and Baden-Württemberg must expand to Eastern European installer networks to preempt Zehnder Group's retrofit niche expansion. For New Entrants and Emerging Players: EU Green Deal building renovation requirements in Germany open a window for decentralized ventilation unit specialists who can bundle filter subscriptions at point of sale. White-space targets include India's emerging green building codes for high-rise residential mechanical ventilation and acoustic-engineering services for Nordic F-Gas Regulation compliance. The most penetrable segment is individual patient direct acquisition in the Netherlands, where online configurators displace contractor specification. A sensor-integrated automation go-to-market angle commands premium positioning against incumbent mechanical-only offerings. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to HVAC conglomerates seeking refrigerant expertise or sensor platform capabilities. Long-term viability hinges on recurring revenue attachment rates from filter subscriptions and remote diagnostics rather than unit shipment volumes. Acquisition target archetypes include compact decentralized ventilation specialists with established installer networks and electrostatic precipitator module engineers with extended service interval validation. The signal to watch is F-Gas Regulation phase-down acceleration in Nordic markets, which would concentrate R&D investment and create distressed asset opportunities among non-compliant product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Filter Subscription Service Launch | Recurring revenue models displace one-time component sales in Germany and the Netherlands. |
| Electrostatic Precipitator Integration | Extended service intervals from six to twenty-four months absorb HEPA media cost inflation. |
| Refrigerant Platform Redesign | Propane and CO2 alternatives respond to EU F-Gas Regulation phase-down timelines. |
| Sensor-Automation Platform Development | Real-time particulate and CO2 responsiveness differentiates against mechanical-only competitors. |
| Direct-to-Consumer Channel Expansion | Online configurators bypass contractor specification in retrofit applications. |
Research Methodology
Multi-period observation of heat-recovery efficiency thresholds, filter replacement frequency, and installer capacity utilization anchored the trend analysis, supplemented by interviews with HVAC systems engineers, building energy consultants, home care procurement managers, and ventilation technician training program directors. Secondary validation drew from EPA Energy Star certification databases, EU Ecodesign directive implementation reports, METI building energy standard filings, and customs trade data for heat exchanger core materials. Bottom-up unit shipment estimates triangulated against top-down construction permit and building renovation expenditure data.
Segment-weighting across product type, application severity, end-user procurement authority, and deployment complexity shaped the analytical framework throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves against regulatory mandate implementation schedules. Industry-specific forecast inputs included F-Gas Regulation phase-down timelines and federal building energy ordinance enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for electrostatic precipitator module penetration would alter the outlook if HEPA media costs collapse or acoustic performance fails certification. Deviation in copper and aluminum commodity price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Warm Air Heater Market