
 Vacuum Insulation Panels Market | 2026-2036
Vacuum Insulation Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Insulation Panels Market Intelligence
European silica-based core production is realigning around stricter thermal conductivity benchmarks and carbon footprint disclosures. Panasonic Corporation leverages its integrated material science pipeline to sustain premium positioning in appliance-grade panels. Va-Q-tec AG anchors European cold chain contracts through customized profile geometries and logistics-specific validation protocols. Kingspan Group competes across building envelope segments with modular panel systems designed for retrofit compatibility.
Vacuum insulation panels are evacuated enclosures with porous core materials—typically fumed silica, glass fiber, or aerogel—sealed within metallized polymer barrier films to achieve thermal conductivity below 0.007 W/m·K, primarily deployed where extreme space constraints prohibit conventional insulation thickness. The inorganic core segment dominates commercial volume due to silica's established supply base and predictable outgassing performance under prolonged vacuum. Organic core formulations occupy emerging niches in automotive thermal management where weight reduction and vibration resilience outweigh absolute thermal performance. Aerogel core variants lead margin pools despite limited scale, commanding specification in pharmaceutical cold chain applications where sub-ambient stability demands exceed standard duty cycles.
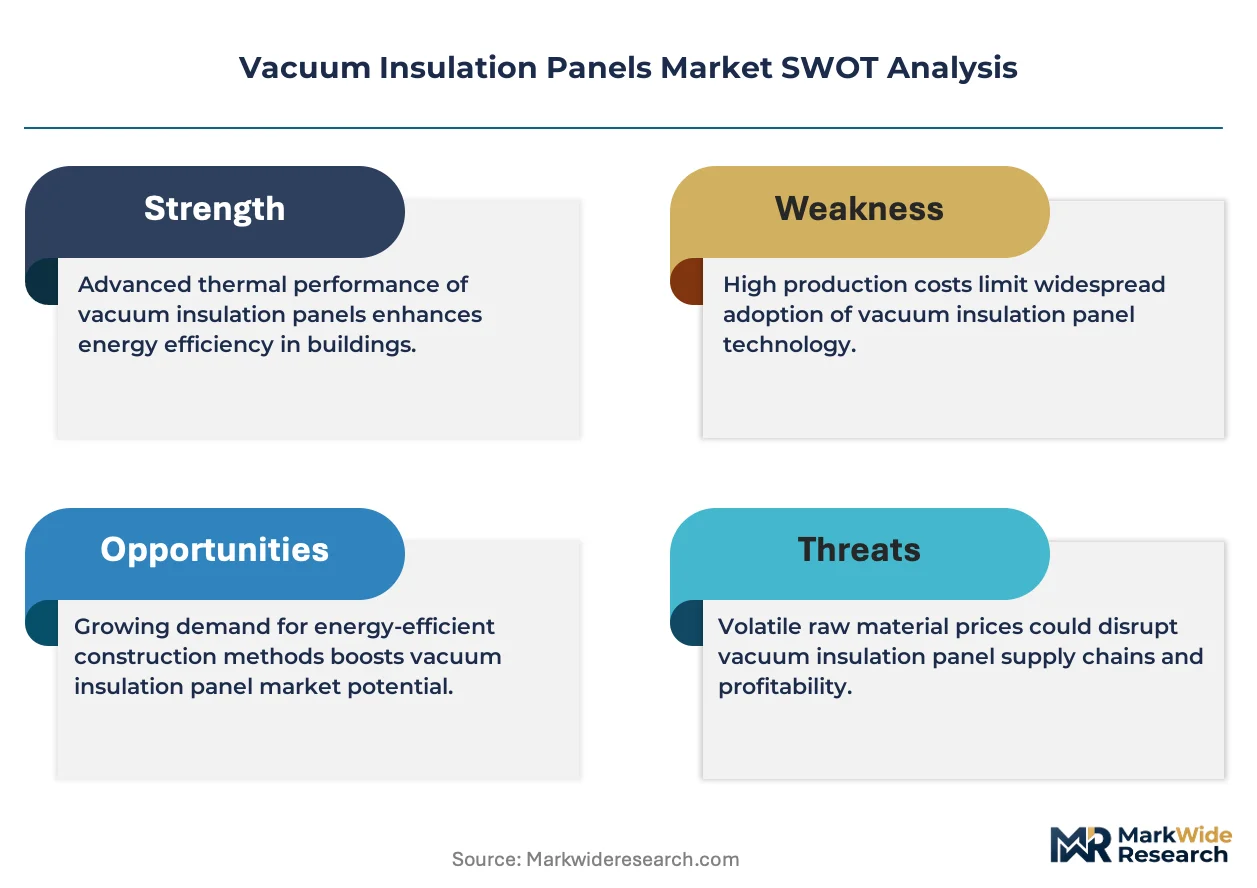
The EU F-Gas Regulation and ECHA REACH compliance frameworks are elevating barrier film chemistry requirements and accelerating fluorinated gas phase-outs in panel manufacturing. EPA energy efficiency standards in the United States and Japan's METI Top Runner program similarly tighten minimum performance thresholds for refrigeration equipment and building envelopes. Stakeholders must monitor evolving barrier material certifications and regional carbon accounting rules to secure specification access across divergent compliance landscapes.
Market Dynamics
EU F-Gas Regulation phase-outs and REACH compliance deadlines are compressing barrier film chemistry cycles while cold chain logistics operators accelerate specification for pharmaceutical shipments. This dual regulatory-manufacturing squeeze forces simultaneous material substitution and performance validation at panel producers.
Growth Catalysts
- EU Green Deal thermal mandates:Member state building renovation waves require super-insulation in heritage structures where space constraints prohibit conventional thickness. Passive house certification spreads from Germany into Austria and Belgium.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics and vaccine distribution networks demand validated VIP systems for last-mile thermal protection. Logistics operators specify panel geometries for standardized pharmaceutical containers.
- Fumed silica core maturation:Established supply chains for inorganic cores enable predictable outgassing performance under prolonged vacuum. Manufacturing scale effects reduce unit cost trajectories for appliance-grade applications.
Market Restraints
- Metallized barrier film cost volatility:Aluminum deposition and polymer substrate prices fluctuate with energy-intensive processing inputs. Panel producers face margin compression when passing through raw material spikes.
- Core material supply concentration:High-purity fumed silica production clusters in limited industrial chemical corridors. Geographic concentration creates vulnerability to logistics disruptions or environmental permitting delays.
- Organic core technical ceilings:Polymer-based alternatives exhibit higher thermal conductivity and vacuum degradation rates. Weight advantages in automotive applications trade off against absolute insulation performance.
Strategic Opportunities
- India cold chain infrastructure buildout:National food security initiatives and pharmaceutical export growth create first-mover positioning for VIP suppliers. BIS thermal performance standards are tightening faster than domestic manufacturing capacity can respond.
- Aerogel core pharmaceutical specialization:Sub-ambient stability demands in cell therapy logistics exceed standard silica duty cycles. Premium positioning captures margin pools in temperature-critical biologics distribution.
- Retrofit building envelope channel development:Modular panel systems designed for existing structure compatibility open specification access where new construction volume stagnates. Installer certification programs reduce adoption friction.
Industry Challenges
- Vacuum integrity validation skill scarcity:Non-destructive testing protocols for sealed panel longevity require specialized metrology expertise. Field service networks struggle to recruit technicians trained in helium leak detection and thermal bridge analysis.
- Barrier film certification timeline compression:ECHA REACH substance evaluation cycles and EPA SNAP program approvals extend qualification periods. Product development pipelines face regulatory hold risks before commercial launch.
- Legacy refrigeration system integration complexity:VIP replacement in existing appliance platforms requires compressor and control system recalibration. OEM engineering resources prioritize new platform development over retrofit optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Insulation Panels Market |
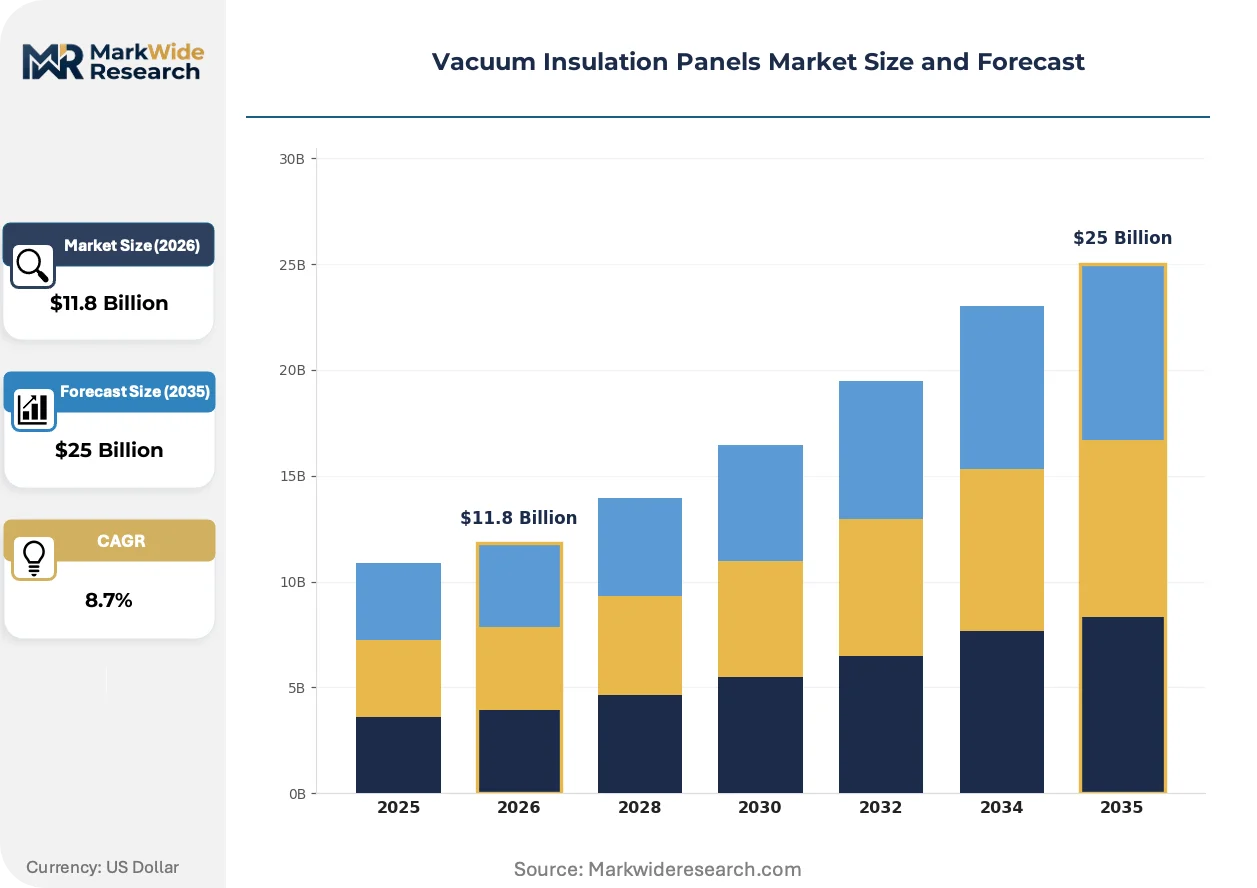
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Core, Inorganic Core, Composite Core, Aerogel Core Application: Refrigeration Equipment, Building & Construction, Automotive Thermal Management, Cold Chain Logistics End User: Appliance Manufacturers, Construction Contractors, Vehicle Assemblers, Logistics Service Providers Packaging Type: Flexible Wrap, Rigid Box, Laminated Film, Custom Profiles |
| Companies Covered | Kevothermal LLC, LG Hausys Ltd, Evonik Industries AG, OCI Company Ltd, Porextherm Dämmstoffe GmbH, Panasonic Corporation, Microtherm Sentronic GmbH, Kingspan Group, va-Q-tec AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Insulation Panels Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are forcing parallel evolution in core formulations and barrier films. Panel producers must synchronize thermal performance gains with fluorinated gas elimination timelines.
Glass fiber core technology is decentralizing vacuum insulation manufacturing by enabling lower-cost production equipment and reduced cleanroom requirements. Regional appliance assemblers in Southeast Asia adopt fiber-based panels for mid-range refrigeration platforms previously served by conventional polyurethane. This technology is decentralizing supply chain control from established silica suppliers toward localized panel fabrication.
REACH authorization restrictions on per- and polyfluoroalkyl substances are compelling barrier film producers to accelerate metal oxide and graphene oxide laminate development. Industrial consequence includes extended validation cycles for new film chemistries against moisture ingress and oxygen permeation benchmarks. Pharmaceutical cold chain applications in Germany and France face earliest substitution deadlines due to national chemical hazard classification precedents.
Specification behavior among cold chain logistics operators now prioritizes validated thermal performance duration over initial conductivity ratings. Asset-light temperature-controlled container leasing models displace ownership-based procurement for pharmaceutical distributors. This pattern concentrates most visibly in Netherlands and Belgium hub operations serving European biologics distribution networks.
Vacuum Insulation Panels Market Segmentation
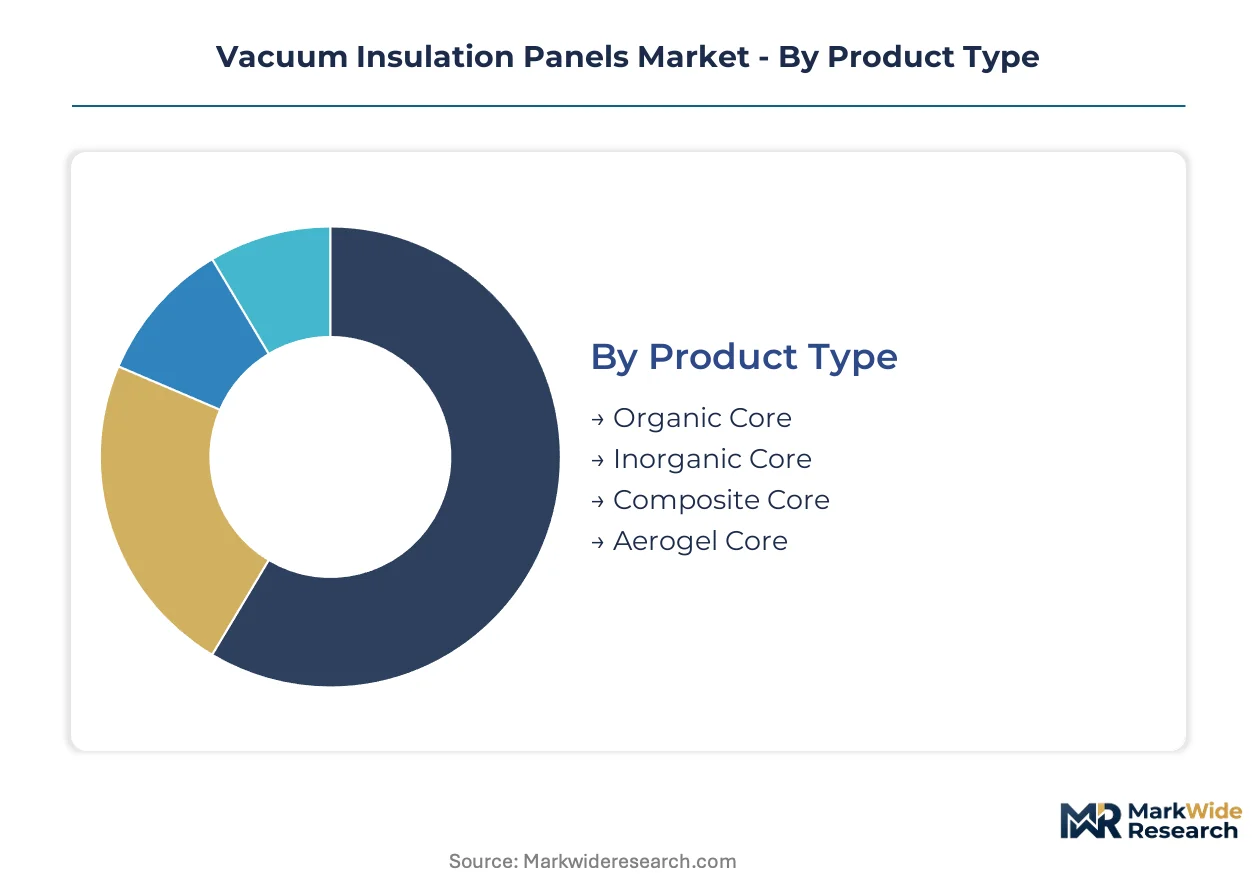
Segmentation in vacuum insulation panels reveals how capital deployment, technical specifications, and regulatory compliance intersect across distinct value chains. Product type determines core chemistry investments and vacuum retention architectures. Application segmentation exposes divergent performance validation requirements between static building envelopes and dynamic cold chain assets.
Product Type:
Capital intensity varies sharply across core formulations, with inorganic silica demanding the heaviest upfront investment in high-purity chemical processing infrastructure and vacuum stabilization equipment.
- Inorganic Core:Fumed silica formulations dominate commercial volume through established supply chains and predictable outgassing performance under prolonged vacuum. German passive house construction and industrial refrigeration clusters in Bavaria drive specification intensity for this segment.
- Aerogel Core:Silica aerogel variants achieve the lowest thermal conductivity values below 0.004 W/m·K, commanding premium positioning in pharmaceutical cold chain applications where sub-ambient stability demands exceed standard duty cycles. Cell therapy logistics in Belgium and the Netherlands specify aerogel panels for temperature-critical biologics distribution.
- Organic Core:Polymer-based alternatives occupy automotive thermal management niches where weight reduction and vibration resilience outweigh absolute thermal performance.
- Composite Core:Hybrid formulations blend inorganic stability with organic processability for emerging appliance platforms requiring intermediate performance tiers.
Most installed capacity flows through Inorganic Core. Expansion is steepest in Aerogel Core.
Application:
Application segmentation tracks how thermal performance requirements and space constraints reshape procurement patterns across stationary and mobile assets.
- Building & Construction:Super-insulation mandates under the EU Green Deal drive specification for heritage structure renovations where conventional insulation thickness is prohibited. Passive house certification spreading from Germany into Austria and Belgium concentrates demand for high-performance envelope systems.
- Cold Chain Logistics:Temperature-sensitive pharmaceutical shipments require validated VIP systems for last-mile thermal protection. Logistics operators in the Netherlands and Belgium specify panel geometries for standardized temperature-controlled container leasing models.
- Refrigeration Equipment:Appliance-grade panels face METI Top Runner program efficiency thresholds in Japan and EPA energy standards in the United States.
- Automotive Thermal Management:Electric vehicle battery enclosures and climate control systems adopt VIP where packaging volume constraints limit conventional insulation options.
Building & Construction absorbs the largest share of panel volume. Cold Chain Logistics is climbing the fastest as biologics distribution networks expand.
End User:
End user categories reflect divergent procurement sophistication, with logistics operators demanding validated performance duration while appliance manufacturers prioritize unit cost trajectories.
- Logistics Service Providers:Asset-light temperature-controlled container leasing models displace ownership-based procurement, prioritizing validated thermal performance duration over initial conductivity ratings.
- Appliance Manufacturers:OEM engineering resources concentrate on new platform development, with VIP integration requiring compressor and control system recalibration.
- Construction Contractors:Installer certification programs for modular panel systems reduce adoption friction in retrofit building envelope channels.
- Vehicle Assemblers:Automotive platforms specify organic core alternatives where weight advantages trade off against absolute insulation performance.
Appliance Manufacturers represent the largest installed base. Logistics Service Providers are gaining share fastest through pharmaceutical cold chain expansion.
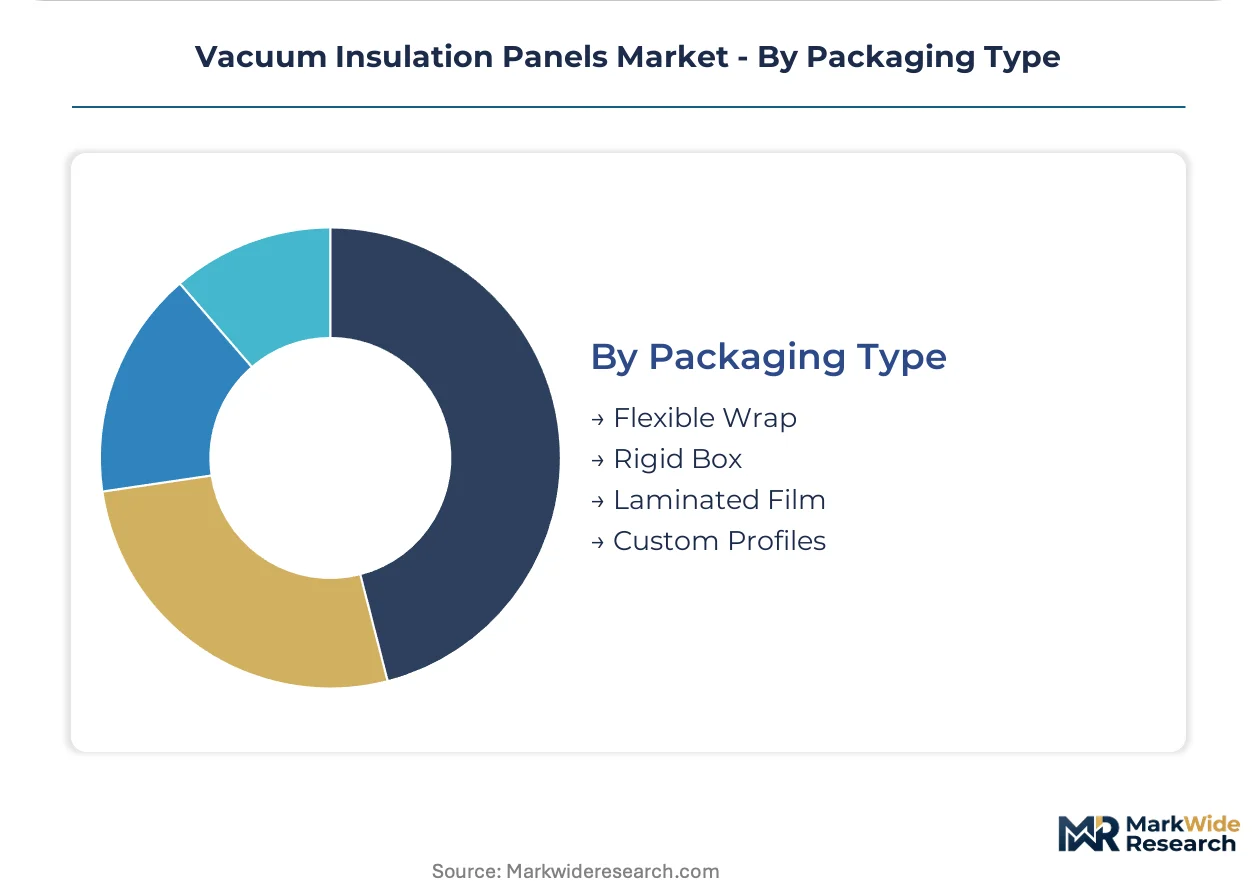
Packaging Type:
Packaging segmentation tracks how barrier film chemistry and geometry customization respond to regulatory constraints and logistics-specific validation protocols.
- Custom Profiles:Geometric tailoring for standardized pharmaceutical containers and specialized appliance cavities commands premium positioning through logistics-specific validation protocols.
- Laminated Film:Multi-layer metallized polymer constructions achieve moisture ingress and oxygen permeation benchmarks required for prolonged vacuum retention.
- Flexible Wrap:Conformable barrier configurations accommodate irregular surface geometries in retrofit building envelope applications.
- Rigid Box:Structural panel formats provide dimensional stability for refrigeration equipment integration and automated assembly lines.
Laminated Film carries the majority of barrier film volume. Custom Profiles are expanding most quickly as cold chain logistics operators accelerate specification for validated container systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting VIP production toward jurisdictions where REACH compliance costs and carbon accounting rules create competitive gaps. Manufacturers are relocating barrier film fabrication to regions with streamlined chemical hazard classifications while maintaining core material sourcing near established silica corridors.
Germany
Passive house construction standards in Bavaria and industrial refrigeration clusters around Munich drive specification intensity for fumed silica panels. The F-Gas Regulation enforces fluorinated gas phase-outs that compress barrier film qualification timelines. Chemical processing corridors in North Rhine-Westphalia concentrate high-purity silica production serving appliance-grade demand.
United States
EPA energy efficiency standards tighten minimum performance thresholds for refrigeration equipment across domestic manufacturing. Cold chain logistics operators in the Northeast Corridor accelerate VIP adoption for temperature-sensitive pharmaceutical distribution. The Pacific Northwest hosts emerging barrier film development responding to SNAP program chemistry constraints.
Japan
METI Top Runner program mandates escalate efficiency benchmarks for domestic appliance platforms. Osaka-based refrigeration OEMs integrate VIP systems requiring compressor recalibration for thinner insulation profiles. Nagoya industrial zones concentrate precision metallized film deposition equipment serving premium appliance segments.
Netherlands
Rotterdam-Antwerp hub operations prioritize validated thermal performance duration for pharmaceutical container leasing models. National chemical hazard classifications precede EU-wide PFAS restrictions, accelerating metal oxide laminate development timelines. Randstad logistics corridors concentrate cold chain validation facilities for biologics distribution networks.
India
National food security initiatives and pharmaceutical export growth strain domestic cold chain capacity. BIS thermal performance standards tighten faster than local manufacturing capacity responds, creating import dependency for high-performance panels. Maharashtra industrial zones attract first-mover VIP suppliers targeting refrigerated transport infrastructure buildout.
Vacuum Insulation Panels Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized pharmaceutical and automotive thermal management niches. The vendor base stratifies across integrated material science conglomerates, modular panel system specialists, and regional fabrication operations. Three archetypes dominate: chemistry-integrated multinationals with captive core supply, logistics-focused customization shops, and scale-driven building envelope suppliers. Competitive moves concentrate on barrier film chemistry substitution partnerships and retrofit installer certification program development.
Within the chemistry-integrated tier, Evonik Industries AG and OCI Company Ltd anchor positions through upstream control over high-purity silica feedstocks. Panasonic Corporation exemplifies appliance-grade specialization, while va-Q-tec AG occupies a position in logistics-specific validation protocols. Kingspan Group sits within the building envelope modularization archetype. LG Hausys Ltd represents Korean-based fabrication scale, and Porextherm Dämmstoffe GmbH anchors German thermal engineering heritage. Kevothermal LLC and Microtherm Sentronic GmbH exemplify regional specialists with concentrated geographic positioning.
| Leading Market Players |
|---|
| Kevothermal LLC |
| LG Hausys Ltd |
| Evonik Industries AG |
| OCI Company Ltd |
| Porextherm Dämmstoffe GmbH |
| Panasonic Corporation |
| Microtherm Sentronic GmbH |
| Kingspan Group |
| va-Q-tec AG |
| Others |
Cost & Logistics Intelligence
Metallized polymer barrier film costs cascade from aluminum deposition energy inputs through three pricing tiers, with German passive house contractors absorbing premium markups while Southeast Asian appliance assemblers negotiate volume discounts on fiber-core alternatives.
Pricing Analysis
Distributor margins widen most sharply for aerogel-core pharmaceutical panels validated under cold chain protocols. Three-tier pricing structure across premium, standard, and economy levels separates certified biologics-grade systems from appliance-grade silica cores and emerging fiber-based economy tiers. Pricing pressure stems from aluminum spot volatility and REACH compliance-driven chemistry substitution costs. Logistics service providers show lowest price sensitivity due to asset-light leasing model economics, while construction contractors in retrofit channels resist premium absorption without installer certification guarantees.
Supply Chain Analysis
Returns and refurbishment flows remain underdeveloped for VIP systems, though end-of-life metallized film recovery is emerging in German chemical processing corridors. High-purity fumed silica production clusters in Germany, South Korea, and limited Chinese industrial zones, with barrier film fabrication increasingly relocating to Southeast Asian jurisdictions with streamlined chemical hazard classifications. Raw material dependencies center on metallized PET substrates, high-purity silica feedstocks, and specialized vacuum sealing equipment. Single-source vulnerability concentrates in precision helium leak detection instrumentation. Distribution runs through direct OEM supply agreements for appliance manufacturers and specialized cold chain integrators for pharmaceutical logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as pharmaceutical cold chain operators displace ownership-based procurement with validated performance duration contracts.
For Market Incumbents: Cement barrier film chemistry substitution partnerships ahead of ECHA REACH authorization deadlines for per- and polyfluoroalkyl substances. Deepen backward integration into high-purity silica feedstocks to defend margin position against raw material volatility. Prioritize retrofit installer certification program development to capture building envelope renovation waves under EU Green Deal thermal mandates. For New Entrants and Emerging Players: The price-point gap between premium aerogel pharmaceutical panels and economy fiber-core appliance tiers offers white-space positioning for hybrid composite formulations. Target India's refrigerated transport infrastructure buildout where BIS thermal standards outpace domestic manufacturing capacity. Pursue automotive thermal management niches where organic core weight advantages offset absolute thermal performance trade-offs. For Investors and Strategic Acquirers: Consolidation pressure builds where barrier film certification timeline compression and core material supply concentration strain mid-scale producers. Long-term viability favors chemistry-integrated multinationals with captive silica supply and logistics-focused customization shops with validated pharmaceutical protocols. Acquisition target archetype: regional specialists with concentrated geographic positioning and established cold chain validation relationships. Monitor ECHA substance evaluation cycle acceleration and national PFAS restriction precedents in France and Netherlands as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Feedstocks | Evonik and OCI anchor positions through upstream control over high-purity chemical processing corridors. |
| Cold Chain Validation Protocol Development | va-Q-tec AG captures pharmaceutical logistics contracts through customized profile geometries and asset-light leasing models. |
| Retrofit Installer Certification Programs | Kingspan Group reduces adoption friction in building envelope channels where new construction volume stagnates. |
| Barrier Film Chemistry Substitution Partnerships | Metal oxide and graphene oxide laminate development accelerates as REACH restrictions compress qualification timelines. |
| Geographic Manufacturing Relocation | Barrier film fabrication shifts toward Southeast Asian jurisdictions with streamlined chemical hazard classifications. |
Research Approach
Multiple input streams — primary interviews with plant managers at silica processing facilities, procurement leads at refrigeration OEMs, and cold chain logistics operators; secondary validation through ECHA REACH substance databases, EU customs trade flows, and METI efficiency program filings; plus technical R&D director surveys — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across the analysis window, with segmentation modeled by core chemistry tier, application channel, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from slope analysis of historical trajectory and normalized adoption curve assumptions, incorporating pharmaceutical cold chain expansion rates and building renovation wave intensity as industry-specific forecast inputs.
Caveats apply where ECHA authorization timeline delays, aluminum energy input volatility, or pharmaceutical distribution network consolidation could materially shift the outlook. Practitioners should monitor national PFAS restriction precedents and cold chain leasing model penetration rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
2D Materials Market
Advanced Materials
Graphite Materials Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Europe Graphene Market
Advanced Materials
Thermal Conductive Material Market