
 Organic Aerogel Market | 2026-2036
Organic Aerogel Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Aerogel Market Insights
Modular aerogel blanket systems is hardening as the dominant packaging format, replacing rigid monolithic panels in retrofit insulation projects. Aspen Aerogels leverages its proprietary fiber-reinforced manufacturing to sustain premium positioning across North American oilfield services. Cabot Corporation anchors its competitive stance through backward integration into silica precursor supply, while BASF SE competes on formulation chemistry tailored to European construction certification schemes.
Organic aerogel denotes a nanoporous solid derived from polymer or biopolymer gel networks, where supercritical drying preserves porosity exceeding 90% with thermal conductivity below 0.020 W/m·K, serving primarily as an ultra-lightweight thermal and acoustic barrier in weight-critical installations. Aerogel insulation leads product type revenue due to mature specification in pipeline and building envelopes, whereas aerogel composites are expanding fastest as aerospace laminates demand multifunctional skins combining fire resistance with dielectric properties. Within application segmentation, thermal insulation occupies the deepest margin pool from long-term industrial maintenance contracts, while electronics cooling substrates represent an emerging volume opportunity driven by power density escalation in electric drivetrains.
The EPA regulates volatile organic compound emissions during aerogel solvent recovery under Clean Air Act provisions, while REACH compliance in Europe governs silane precursor registration and restricts certain crosslinking chemistries, collectively elevating compliance costs for non-integrated producers. China's GB standards on building fire safety classification and the EU's F-Gas Regulation restricting blowing agents in competing foam insulation both redirect specification toward inorganic and organic aerogel alternatives. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide whether to localize precursor production or absorb escalating transatlantic certification overhead.
Market Dynamics
The EU Green Deal's building efficiency mandates are compressing specification cycles for thermal insulation materials, forcing formulators to recertify products under tightened energy performance standards while aerospace OEMs simultaneously advance lightweighting procurement protocols.
Growth Catalysts
- F-Gas Regulation:The EU's restrictions on hydrofluorocarbon blowing agents in conventional foam insulation redirect commercial specification toward organic aerogel alternatives for building envelope applications.
- Electric drivetrain thermal management:Power density escalation in battery packs and inverters generates specification pull for aerogel cooling substrates with dielectric properties.
- Germany's industrial corridor:Co-location of chemical processing and automotive OEMs with specialized aerogel distributors concentrates demand pull and shortens qualification timelines.
Market Restraints
- Silane precursor cost volatility:Tetramethoxysilane and methyltrimethoxysilane feedstock prices fluctuate with semiconductor sector demand cycles, compressing margin predictability for non-integrated producers.
- Supercritical drying equipment concentration:High-pressure CO₂ extraction system fabrication concentrates among specialized German and Japanese machinery suppliers, creating capex bottlenecks for capacity expansion.
- Polyurethane foam substitution:Lower-cost spray foam retains specification share in cost-sensitive residential retrofit segments despite inferior thermal performance.
Strategic Opportunities
- India's PLI scheme for advanced materials:Production-linked incentives for domestic manufacturing of critical insulation materials create localized precursor synthesis opportunities.
- Modular blanket retrofit channel:Direct-to-contractor distribution of pre-cut aerogel blanket systems bypasses traditional distributor markup in European building renovation markets.
- Carbon border adjustment mechanism:Impending EU CBAM implementation on imported insulation products advantages European-sourced aerogel against Asian foam competitors.
Industry Challenges
- Supercritical drying technician scarcity:High-pressure process operation and maintenance expertise concentrates among legacy silica aerogel producers, constraining workforce scaling for organic variants.
- REACH registration timelines:Novel crosslinking chemistry submissions face extended ECHA evaluation periods, delaying product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Aerogel Market |
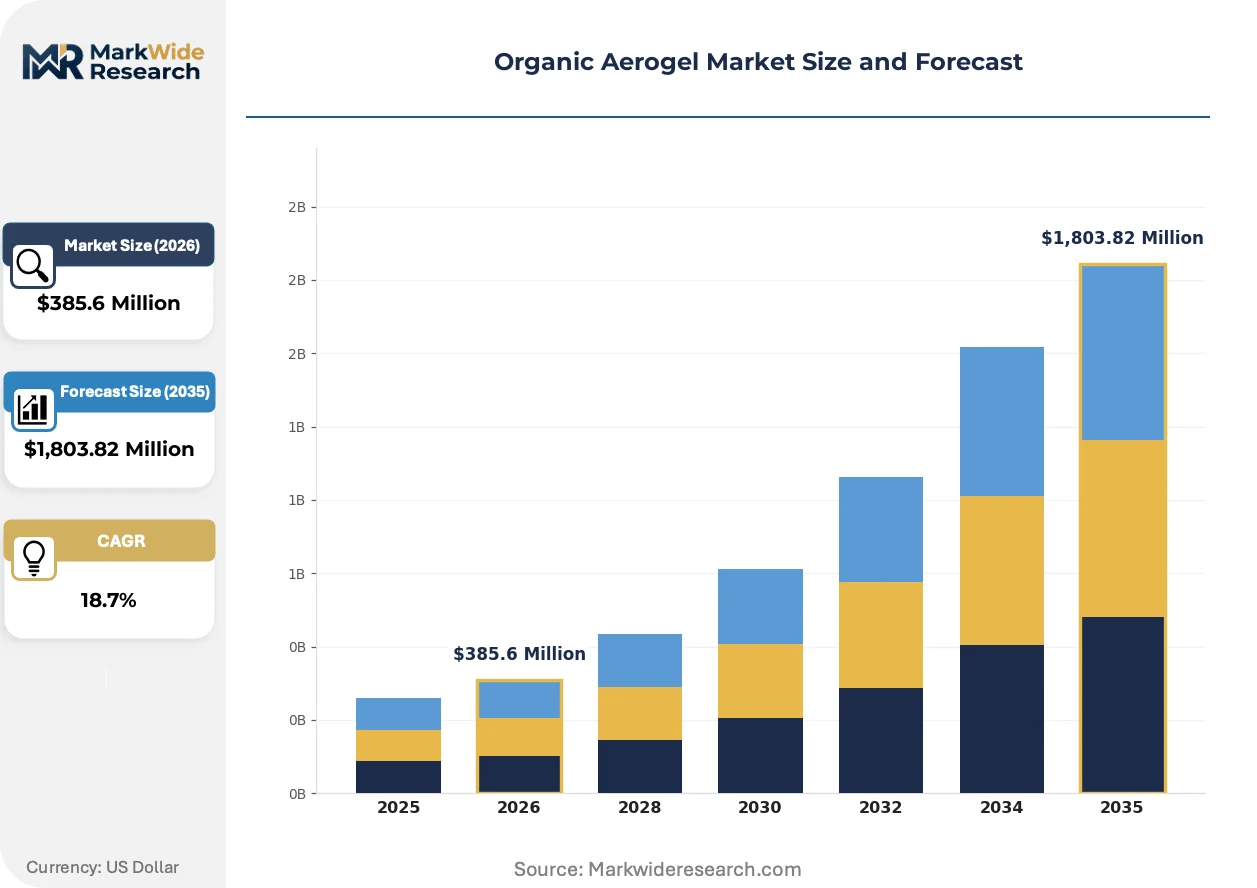
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerogel Insulation, Aerogel Composites, Aerogel Powders, Aerogel Films Application: Thermal Insulation, Oil & Gas, Electronics, Construction End User: Aerospace, Automotive, Energy, Industrial Distribution Channel: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | Nano Technology Co., Ltd., High Tech Material Solutions, Aspen Aerogels, Enersens, Shanghai Aerogelzone Technology Co., Ltd., Cabot Corporation, Armacell International, BASF SE, Aerogel Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Aerogel Market Trends and Innovations
Fiber-reinforced aerogel manufacturing is compressing cost curves while regulatory chemistry restrictions and buyer procurement consolidation simultaneously reshape competitive positioning across insulation categories.
Cellulose-derived biopolymer aerogel is electrifying sustainable insulation specification by replacing petrochemical gel precursors with agricultural waste feedstocks. European construction contractors are accelerating pilot installations in passive house developments. This feedstock pivot is compressing lifecycle carbon assessments and opening premium positioning against conventional silica aerogel.
REACH authorization requirements for silane crosslinkers are tightening precursor availability for European formulators. The restriction list expansion forces producers to reformulate gel networks or secure supply agreements with registered importers. Building envelope applications face the steepest compliance cost escalation as certification schemes incorporate chemical safety scoring.
Integrated design-build firms are consolidating aerogel specification authority away from fragmented mechanical contractor networks. Turnkey energy retrofit providers in Germany and France now mandate aerogel performance guarantees within fixed-price contracts. This channel concentration compresses distributor margins while rewarding manufacturers with direct technical service capabilities.
Organic Aerogel Market Segmentation
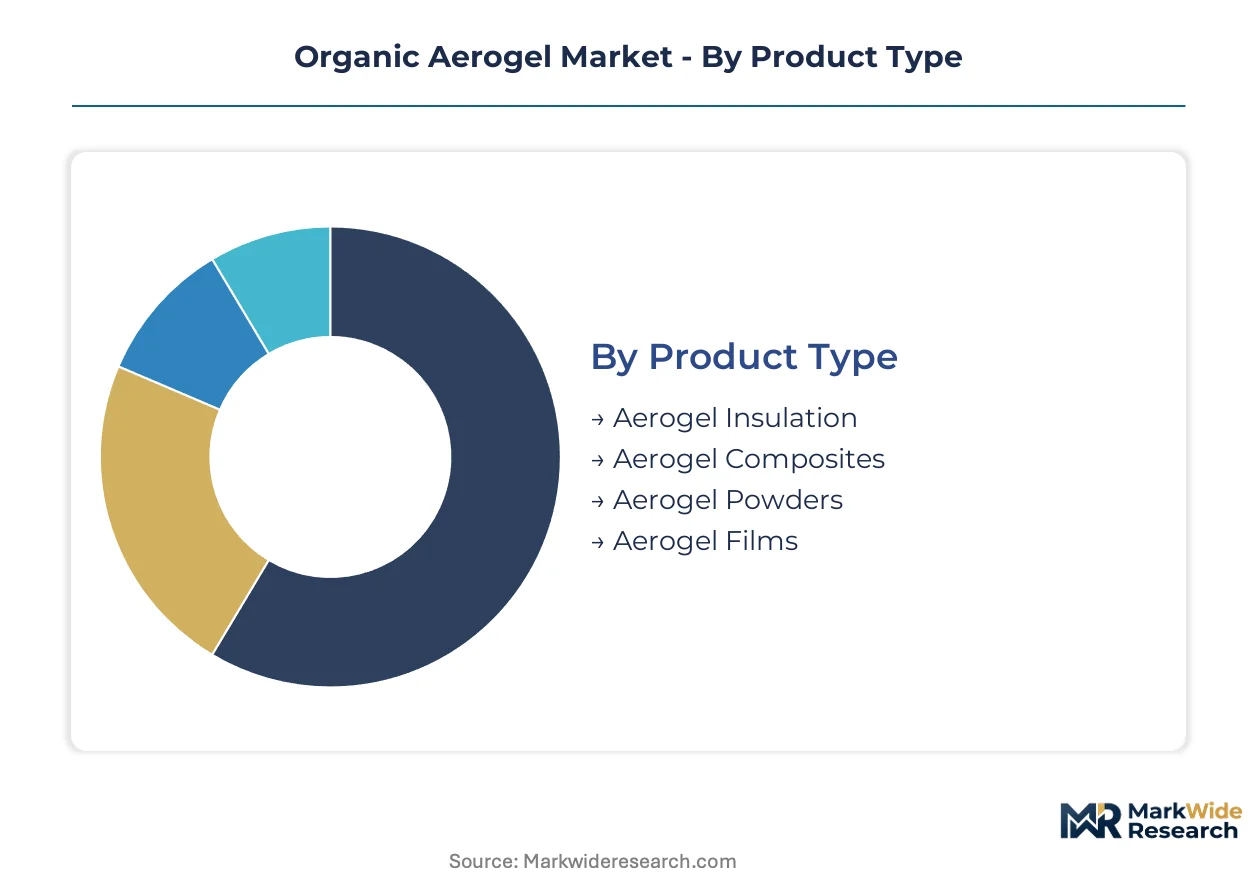
Organic aerogel segmentation reveals divergent margin structures across product formats and channel economics. Procurement patterns in aerospace and building retrofit markets pull specification toward distinct performance tiers rather than uniform commoditization.
Product Type:
Aerogel insulation commands volume leadership through mature pipeline and envelope specifications, while aerogel composites capture premium positioning in multifunctional laminates.
- Aerogel Insulation:Fiber-reinforced blanket and panel formats dominate thermal barrier procurement for oilfield infrastructure and building envelopes. German chemical processors and North American pipeline operators specify these systems for long-term maintenance contracts with performance guarantees.
- Aerogel Composites:Multifunctional skins integrate fire resistance with dielectric properties for aerospace laminates and electric drivetrain cooling substrates. Demand concentrates where Boeing and Airbus advance lightweighting protocols alongside power density escalation in battery packs.
- Aerogel Powders:Additive feedstock for coatings and sealant formulations serving industrial corrosion protection.
- Aerogel Films:Thin-film dielectric layers for electronics thermal management and flexible insulation wraps.
Today's leader: Aerogel Insulation. Tomorrow's challenger: Aerogel Composites.
Application:
Application segmentation tracks regulatory chemistry restrictions and buyer procurement consolidation across insulation categories.
- Thermal Insulation:The deepest margin pool derives from industrial maintenance contracts in oil & gas and building envelope retrofits. EU F-Gas Regulation redirects commercial specification away from hydrofluorocarbon foam toward organic aerogel alternatives in member state construction markets.
- Oil & Gas:Pipeline thermal barriers and subsea insulation systems specify aerogel for extreme temperature differentials. North American producers favor fiber-reinforced formats for Arctic and deepwater extraction infrastructure.
- Electronics:Power density escalation in inverters and battery packs generates specification pull for dielectric cooling substrates. Electric vehicle OEMs in Germany's industrial corridor accelerate qualification timelines.
- Construction:Passive house developments and EU Green Deal efficiency mandates compress specification cycles for envelope materials. Cellulose-derived biopolymer variants gain traction against petrochemical precursors.
Thermal Insulation anchors current revenue. Electronics climbs fastest on drivetrain electrification.
End User:
End user segmentation reflects co-location advantages and direct technical service requirements.
- Aerospace:OEM lightweighting procurement protocols specify aerogel thermal barriers for fuel efficiency and payload optimization. Boeing and Airbus suppliers advance qualification of multifunctional composite skins.
- Automotive:Electric drivetrain thermal management dominates specification, with battery pack and inverter cooling substrates representing emerging volume opportunity.
- Energy:Oil & gas pipeline operators and renewable storage developers specify aerogel for temperature stability across extraction and grid infrastructure.
- Industrial:Chemical processing and manufacturing facilities deploy aerogel for equipment insulation and process energy efficiency.
Aerospace commands premium positioning. Automotive scales fastest on electrification timelines.
Distribution Channel:
Channel segmentation tracks margin compression from consolidated specification authority.
- Direct Sales:Turnkey energy retrofit providers in Germany and France mandate aerogel performance guarantees within fixed-price contracts, rewarding manufacturers with technical service capabilities.
- Distributors:Specialized aerogel distributors in Germany's industrial corridor shorten qualification timelines for chemical processing and automotive OEMs.
- Online Sales:Pre-cut modular blanket systems bypass traditional markup in European building renovation markets through direct-to-contractor platforms.
- Retail:Limited penetration in consumer-accessible formats due to specialized installation requirements and performance certification needs.
Direct Sales captures specification authority. Online Sales disrupts traditional distributor economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic aerogel manufacturing traces its industrial roots to Stanford University laboratories where silica variants first demonstrated commercial viability, with production scaling subsequently concentrating in German chemical corridors and North American energy markets.
United States
Arctic pipeline infrastructure and aerospace lightweighting programs drive specification of fiber-reinforced blanket systems. The EPA regulates solvent recovery emissions under Clean Air Act provisions, elevating compliance costs for non-integrated producers. Houston and Anchorage anchor demand clusters where oilfield service contractors specify aerogel thermal barriers for extreme-temperature extraction equipment.
Germany
Chemical processing facilities and automotive OEMs co-locate with specialized distributors in the Rhine-Ruhr and Bavarian industrial corridors. The EU F-Gas Regulation redirects commercial specification away from hydrofluorocarbon foam insulation toward organic aerogel alternatives. Stuttgart's electric drivetrain developers accelerate qualification timelines for battery pack cooling substrates.
China
GB standards on building fire safety classification tighten envelope material specifications in megacity construction markets. Dual carbon goals under the national climate strategy compress payback periods for high-performance insulation retrofits. Shanghai and Shenzhen manufacturing zones concentrate precursor synthesis capacity alongside supercritical drying equipment fabrication.
France
Turnkey energy retrofit providers in the Île-de-France region mandate aerogel performance guarantees within fixed-price renovation contracts. REACH authorization requirements for silane crosslinkers force reformulation of gel networks for building envelope applications. Lyon and Grenoble aerospace suppliers advance qualification of multifunctional composite skins for Airbus procurement protocols.
India
The PLI scheme for advanced materials production incentivizes domestic manufacturing of critical insulation components. Maharashtra and Gujarat chemical corridors attract precursor synthesis investments from multinational formulators seeking tariff-advantaged supply positions. Mumbai-Pune automotive clusters specify aerogel cooling substrates for emerging electric vehicle platforms.
Organic Aerogel Market Competitive Landscape
The competitive structure tilts toward specialty chemical conglomerates with captive precursor supply and focused aerogel specialists with proprietary fiber-reinforcement manufacturing. Tiered positioning separates premium formulation providers from cost-optimized volume suppliers. Three archetypes dominate: backward-integrated chemical majors controlling silane feedstock, technology specialists with patented drying processes, and regional fabricators serving localized retrofit channels. Capacity expansion and direct technical service capabilities constitute the dominant competitive moves.
Within the technology-specialist tier, Aspen Aerogels and Aerogel Technologies exemplify proprietary manufacturing approaches, while Cabot Corporation anchors the backward-integrated archetype through in-house precursor production. Shanghai Aerogelzone Technology Co., Ltd. represents regional fabrication concentration serving Asia-Pacific construction markets. These three occupy positions reflecting distinct strategic bets on channel control, feedstock security, and geographic focus.
| Leading Market Players |
|---|
| Nano Technology Co., Ltd. |
| High Tech Material Solutions |
| Aspen Aerogels |
| Enersens |
| Shanghai Aerogelzone Technology Co., Ltd. |
| Cabot Corporation |
| Armacell International |
| BASF SE |
| Aerogel Technologies |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal efficiency mandates compressing specification cycles for thermal insulation materials force formulators to recertify products under tightened energy performance standards, elevating compliance costs that suppliers must absorb or pass through and reshaping procurement economics across the value chain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fiber-reinforced blanket systems with full REACH certification from basic panel formats and unbranded regional alternatives. Price differentiation rests on silane precursor purity grades and after-sales technical service bundling. Cost compression in standard tiers intensifies because polyurethane foam retains specification share in residential retrofit segments. Distributor networks show highest price sensitivity, while turnkey energy retrofit providers absorb premiums for performance guarantees.
Supply Chain Analysis
India's PLI scheme for advanced materials and China's dual carbon goals are reshaping sourcing patterns by incentivizing domestic precursor synthesis capacity and redirecting feedstock flows toward tariff-advantaged production zones. Geographic supply concentration centers on Germany, China, and the United States, where supercritical drying equipment fabrication and silane precursor production co-locate. Raw material dependencies draw from tetramethoxysilane, methyltrimethoxysilane, and agricultural waste cellulose feedstocks. Single-source vulnerability concentrates among specialized German and Japanese machinery suppliers for high-pressure CO₂ extraction systems. Distribution runs through direct sales to integrated design-build firms consolidating specification authority away from fragmented mechanical contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU F-Gas Regulation's restrictions on hydrofluorocarbon blowing agents in conventional foam insulation redirecting commercial specification toward organic aerogel alternatives and establishing durable demand tailwinds.
For Market Incumbents: Lock in precursor supply security through backward integration into silane feedstock or long-term offtake agreements with registered importers, while expanding direct technical service capabilities to capture specification authority from consolidating turnkey retrofit providers. Polyurethane foam substitution in cost-sensitive residential segments and REACH registration timeline delays for novel crosslinking chemistries threaten margin stability. Capacity addition in India's PLI-advantaged chemical corridors and certification investment for EU Green Deal compliance represent priority defensive levers. For New Entrants and Emerging Players: The EU F-Gas Regulation in Europe opens a window for modular blanket retrofit channel penetration through direct-to-contractor platforms bypassing traditional distributor markup. White-space targets include cellulose-derived biopolymer aerogel for passive house developments and dielectric cooling substrates for electric drivetrain thermal management. India's Maharashtra and Gujarat chemical corridors offer the most penetrable geography given PLI scheme incentives and nascent local competition. Go-to-market execution should anchor on pilot installation partnerships with European construction contractors accelerating sustainable insulation specification. For Investors and Strategic Acquirers: Asymmetric upside sits with technology specialists possessing proprietary fiber-reinforcement manufacturing and patented supercritical drying processes, positioned to capture premium tier pricing as aerospace lightweighting protocols advance. Long-term viability over the five-to-ten year window hinges on regulatory chemistry restrictions tightening precursor availability and carbon border adjustment mechanisms advantaging European-sourced production. Acquisition target archetype: mid-cap formulators with direct technical service capabilities and established REACH registration portfolios. The signal to watch is supercritical drying technician scarcity constraining workforce scaling for organic variants, indicating capacity expansion bottlenecks that favor incumbents with legacy expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Cabot Corporation's captive silane precursor supply anchors margin predictability against semiconductor sector demand cycles. |
| Capacity Expansion | India's PLI scheme attracts domestic manufacturing investments from multinational formulators seeking tariff-advantaged positions. |
| Green Manufacturing Transition | Cellulose-derived biopolymer aerogel from agricultural waste feedstocks compresses lifecycle carbon assessments for EU construction markets. |
| Long-term Supply Agreement | Turnkey energy retrofit providers in Germany and France mandate aerogel performance guarantees within fixed-price contracts. |
| Joint Venture | Co-location of chemical processing and automotive OEMs with specialized distributors in Germany's industrial corridor shortens qualification timelines. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with plant managers at aerogel manufacturing facilities, procurement leads at oilfield service contractors and automotive OEMs, distribution channel partners in Germany's industrial corridor, and technical R&D directors at specialty chemical conglomerates. Secondary validation draws from customs and trade data, SEC 10-K filings of listed chemical producers, ECHA REACH registration databases, and EU regulatory filings under F-Gas Regulation and Green Deal provisions. Bottom-up volume modeling triangulates against top-down value estimates across product type, application, and end user segmentation.
Granularity-level modeling disaggregates revenue and volume across aerogel insulation, composites, powders, and films by thermal insulation, oil and gas, electronics, and construction applications, with further splits by aerospace, automotive, energy, and industrial end users. CAGRs derive from regression analysis of historical procurement patterns projected across the analysis window, incorporating electric drivetrain thermal management demand curves, EU building efficiency mandate implementation timelines, and aerospace lightweighting protocol adoption rates as industry-specific forecast inputs.
Revisions become necessary when carbon border adjustment mechanism implementation timelines accelerate, silane precursor cost volatility exceeds historical semiconductor sector correlation patterns, or supercritical drying equipment fabrication capacity constraints materially expand. Forecasts reflect documented assumptions regarding regulatory chemistry restriction trajectories and buyer procurement consolidation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Silica Aerogel Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Curable Materials Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Global High Performance Thermoplastics Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Borophene Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Artificial Marble Products Market