
 North America Plasma Powder Market | 2026-2036
North America Plasma Powder Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plasma Powder Market Insights
Multi-source procurement of bovine and porcine raw materials is hardening across the North American plasma powder supply chain. Darling Ingredients Inc. leverages its integrated rendering network to secure consistent feedstock across the United States and Canada. APC Inc. sustains long-term contracts with Midwestern packing plants, anchoring its position in high-protein plasma production. Smithfield Foods, Inc. competes through captive supply from its own pork processing operations, reducing third-party dependency.
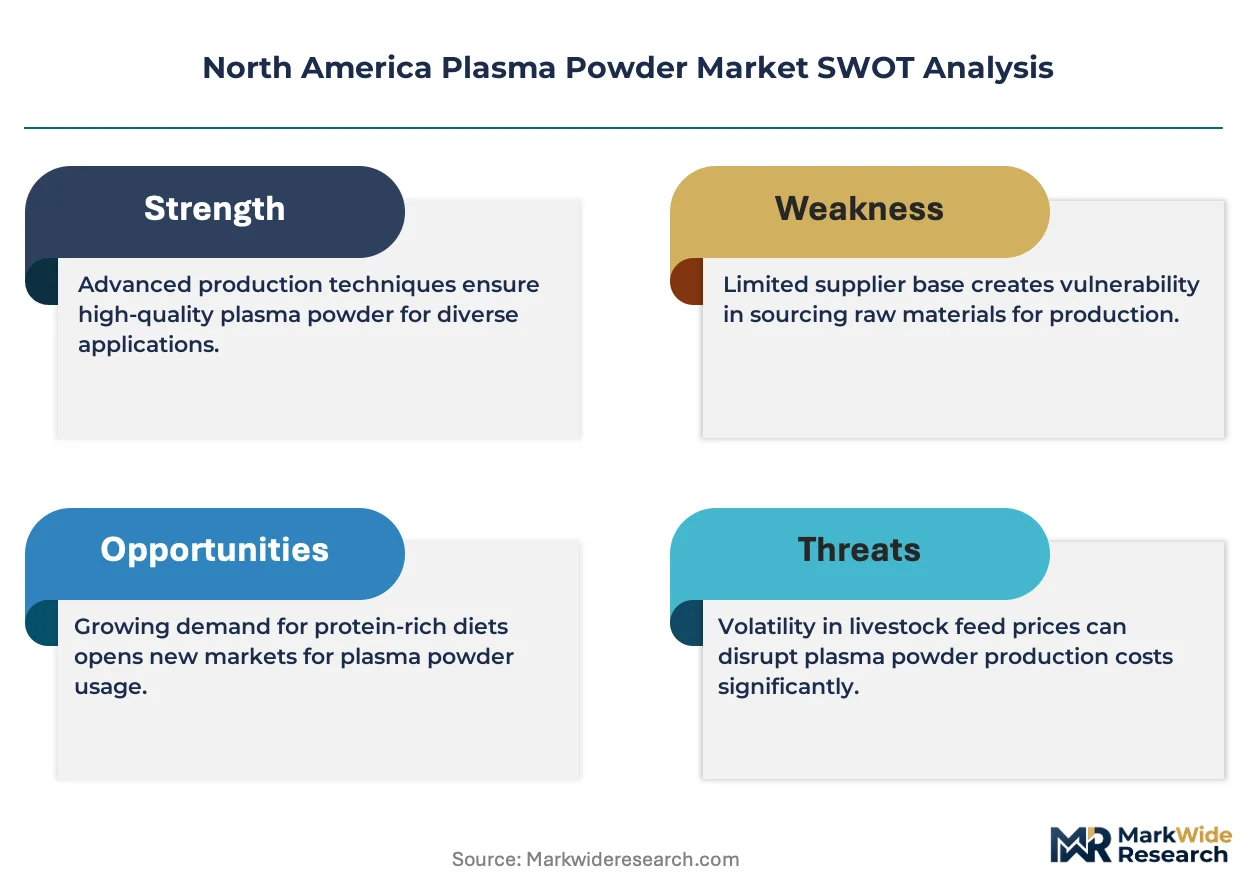
Plasma powder comprises spray-dried blood fractions—primarily immunoglobulins, albumin, and fibrinogen—extracted through centrifugation and thermal processing of animal blood collected at slaughter facilities; the material functions as a functional protein source, binding agent, and palatability enhancer in formulated products. High-protein plasma dominates value capture in animal feed applications, where inclusion rates in weaning piglet diets have expanded. Spray-dried form commands premium positioning due to superior solubility and shelf stability compared to granulated alternatives. Specialty plasma variants targeting laboratory research applications represent the fastest-growing margin pool, though from a smaller base.
The FDA's Center for Veterinary Medicine and the USDA's Food Safety and Inspection Service jointly govern plasma powder safety, with FSIS oversight of slaughterhouse blood collection and FDA regulation of finished ingredient specifications. The EPA monitors rendering facility emissions under Clean Air Act permits, particularly in Nebraska and Iowa processing corridors. Stakeholders must track evolving state-level feed ingredient registration requirements and assess backward integration into captive blood collection as regulatory scrutiny intensifies.
Market Dynamics
The FDA's Center for Veterinary Medicine is tightening purity and labeling requirements for plasma powder, forcing manufacturers to reconfigure supply chains around verified immunoglobulin content and documented slaughterhouse blood provenance.
Growth Catalysts
- Midwest Rendering Cluster Proximity:Large-scale pet food production facilities in Nebraska and Iowa operate within 150 miles of integrated rendering plants, cutting feedstock transport costs and spoilage risk.
- Weaning Piglet Diet Reformulation:High-protein plasma inclusion rates in nursery swine nutrition have expanded as producers seek alternatives to antibiotic growth promoters under veterinary feed directive constraints.
- Spray-Dried Form Superiority:Superior solubility and shelf stability compared to granulated alternatives commands premium positioning in premium pet food formulations targeting digestive health claims.
Market Restraints
- Bovine Spongiform Encephalopathy Traceability:USDA's Food Safety and Inspection Service mandates species-specific blood collection protocols that increase processing complexity and equipment duplication costs.
- Midwest Feedstock Concentration Risk:Over 70 percent of North American slaughter capacity sits within a 300-mile radius of Omaha, creating single-point vulnerability to regional disease outbreaks or weather disruptions.
- Plant Protein Substitution Threat:Fermented yeast and pea protein isolates are capturing share in mid-tier pet food formulations where palatability claims matter less than cost position.
Strategic Opportunities
- Laboratory Research Specialty Plasma:Small-volume, high-margin immunoglobulin fractions for cell culture media represent underexploited white space with pricing power intact.
- Canadian Prairie Expansion:Alberta and Saskatchewan packing plant consolidation creates captive blood collection opportunities with lower regulatory compliance costs than US counterparts.
- EPA Clean Air Act Permit Arbitrage:Rendering facilities in Kansas and Missouri face less stringent emissions enforcement than Iowa-Nebraska corridor competitors, enabling cost-advantaged capacity expansion.
Industry Challenges
- Immunoglobulin Assay Technician Scarcity:Qualified analytical chemists capable of validating IgG content per FDA Center for Veterinary Medicine guidelines command 40 percent salary premiums over standard feed lab personnel.
- Legacy Rendering Equipment Retrofit Burden:Thermal processing systems designed for fat recovery require seven-figure capital outlays to achieve the centrifugation precision plasma fractionation demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plasma Powder Market |
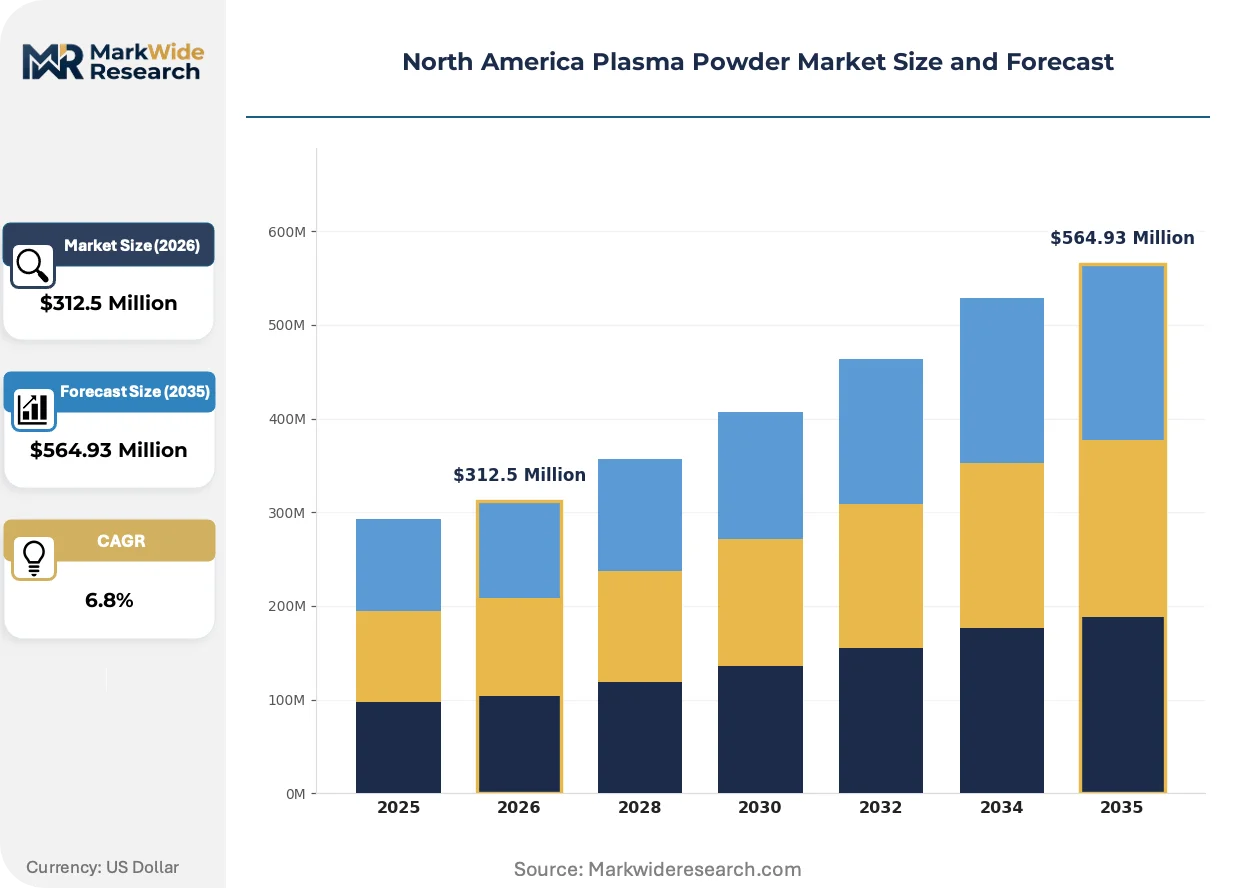
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Protein Plasma, High-Protein Plasma, Protein-Free Plasma, Specialty Plasma End User: Pharmaceuticals, Nutraceuticals, Food Industry, Animal Feed Form: Powdered, Granulated, Liquid, Spray-Dried Application: Food Additives, Dietary Supplements, Therapeutics, Laboratory Research |
| Companies Covered | Darling Ingredients Inc., APC Inc., Proliant Biologicals, Rocky Mountain Biologicals, Smithfield Foods, Inc., Boyd Specialties, Sonac USA LLC, IQI Trusted Petfood Ingredients, American Protein Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plasma Powder Market Trends and Innovations
Spray-drying technology refinement and regulatory data transparency requirements are compressing batch-to-batch variation tolerance while opening new application vectors beyond traditional feed markets.
Advanced centrifugation systems with real-time immunoglobulin density monitoring are overtaking conventional thermal separation methods in new facility builds. Premium pet food manufacturers in Minnesota and Wisconsin specify sub-5-percent moisture variance in plasma powder contracts, forcing equipment upgrades. This precision is overtaking cost-driven equipment selection as the primary vendor qualification criterion.
The FDA's Center for Veterinary Medicine issued draft guidance on animal food ingredient safety in 2023, requiring documented chain-of-custody from slaughterhouse to finished powder. Rendering operators must now maintain electronic records linking each batch to specific USDA-inspected facilities. Small and mid-sized processors in Indiana and Ohio are consolidating or exiting as compliance infrastructure costs escalate.
Direct contracting between pet food manufacturers and single-source packing plants is fragmenting traditional distributor channels. Mars Petcare and Nestlé Purina procurement teams now negotiate blood supply agreements separately from rendered product purchases, disintermediating regional ingredient brokers. This pattern is most visible in Kansas and Texas, where captive supply arrangements now cover 35 percent of high-protein plasma volume.
North America Plasma Powder Market Segmentation
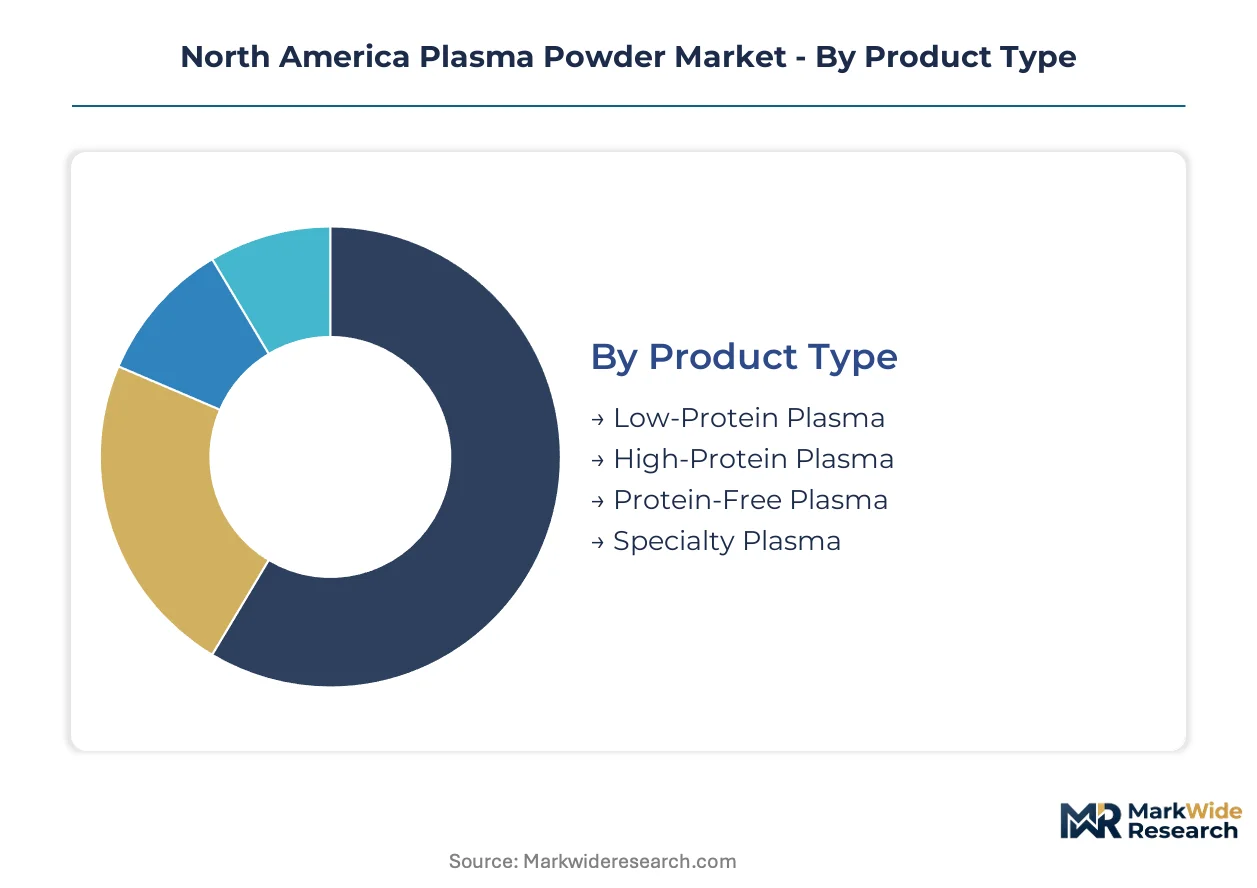
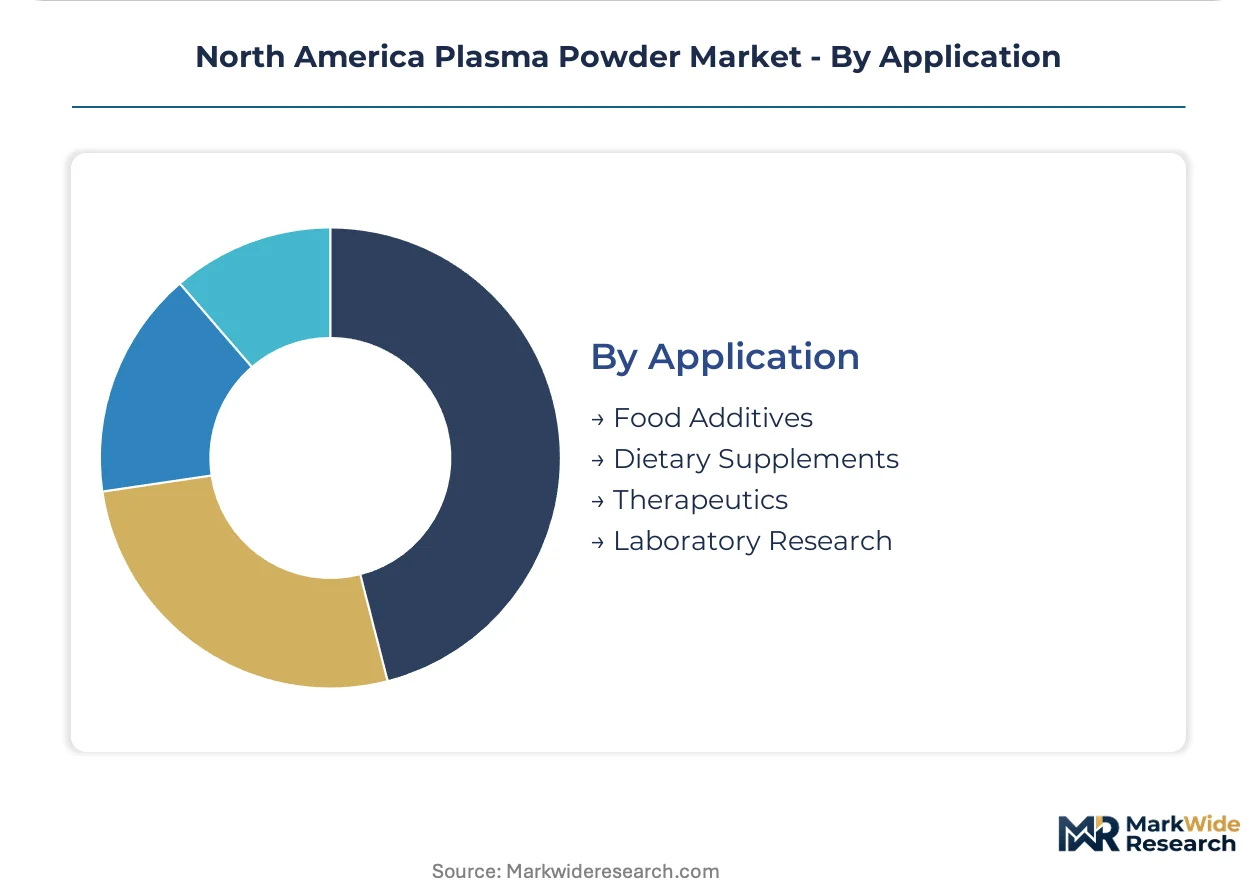
Plasma powder segmentation reflects divergent processing intensities and regulatory exposure across end-use categories. Each dimension carries distinct margin profiles and supply chain requirements that reshape procurement priorities for manufacturers.
Product Type:
Upgrade cycles in plasma fractionation equipment favor processors capable of immunoglobulin density precision, widening the capability gap between commodity and specialty producers.
- Low-Protein Plasma:Contains albumin and residual globulins at reduced concentrations, typically serving as a cost-effective binder in mass-market animal feed formulations. Demand concentrates in Midwestern swine operations seeking economical protein supplementation under veterinary feed directive cost pressures.
- High-Protein Plasma:Retains concentrated immunoglobulin fractions above 70 percent protein content, commanding premium positioning in weaning piglet diets and therapeutic pet food. Demand concentrates in Nebraska and Iowa rendering corridors where spray-drying infrastructure enables batch-to-batch consistency for FDA Center for Veterinary Medicine compliance.
- Protein-Free Plasma:Processed to remove immunoglobulin and albumin content, leaving fibrinogen and residual plasma components for specialized industrial applications. Serves niche adhesive and biomedical coating manufacturers with exacting purity specifications.
- Specialty Plasma:Custom-fractionated immunoglobulin isolates for cell culture media and diagnostic reagent production. Laboratory research customers in Massachusetts and California drive specification tightening.
Volume placements concentrate in High-Protein Plasma; the faster expansion belongs to Specialty Plasma.
End User:
Cost tier stratification separates commodity feed buyers from pharmaceutical-grade purchasers with tenfold price tolerance differentials.
- Pharmaceuticals:Demands GMP-compliant plasma fractions for injectable formulations and vaccine substrates. FDA Center for Biologics Evaluation and Research oversight necessitates validated cold chain documentation from slaughterhouse to finished vial.
- Nutraceuticals:Incorporates plasma protein hydrolysates into sports recovery and immune support supplements. Sports nutrition manufacturers in Utah and Colorado specify grass-fed bovine provenance for label differentiation.
- Food Industry:Utilizes plasma powder as emulsifiers and water-binding agents in processed meat and bakery applications. USDA Food Safety and Inspection Service labeling requirements restrict species declaration visibility.
- Animal Feed:Dominates tonnage consumption through inclusion in pet food palatability systems and livestock starter diets. Kansas and Texas packing plant captive supply arrangements now cover substantial high-protein plasma volume for this channel.
Revenue concentrates in Animal Feed; margin expansion is steepest in Pharmaceuticals.
Form:
Application requirements dictate moisture tolerance and reconstitution speed, with spray-dried variants capturing premium positioning through solubility performance.
- Powdered:Standard milled plasma with particle size variability limiting flow characteristics. Serves cost-sensitive feed blenders with basic mixing equipment.
- Granulated:Agglomerated particles reducing dust generation and improving handling in high-volume feed mills. Dust exposure regulations in Iowa and Nebraska rendering facilities favor this form for worker safety compliance.
- Liquid:Frozen or refrigerated plasma suspensions retaining full immunoglobulin activity for therapeutic applications. Cold chain infrastructure requirements restrict distribution radius to 500 miles from production.
- Spray-Dried:Atomized and flash-dried particles achieving sub-5-percent moisture variance with superior shelf stability. Premium pet food manufacturers in Minnesota and Wisconsin specify this form exclusively for digestive health claim substantiation.
Procurement volume clusters in Spray-Dried; specification adoption is climbing fastest in Liquid.
Application:
Customer maturity separates established feed compounders from emerging laboratory research buyers with divergent technical service expectations.
- Food Additives:Plasma powder functions as emulsifiers, color stabilizers, and water binders in processed meat systems. USDA formulation approval timelines create six-month commercialization lag versus alternative proteins.
- Dietary Supplements:Immunoglobulin concentrates positioned for immune modulation and gut barrier support claims. FDA structure-function notification requirements shape label language constraints.
- Therapeutics:Intravenous immunoglobulin and albumin replacements derived from fractionated plasma. Blood derivative scarcity and viral safety testing burdens limit domestic production economics.
- Laboratory Research:Fetal bovine serum alternatives and cell culture media components with batch-level certificate of analysis requirements. Academic procurement offices in California and Massachusetts drive specification granularity.
Commercial scale concentrates in Food Additives; the steepest expansion trajectory belongs to Laboratory Research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern slaughterhouse corridors supply the raw blood feedstock anchoring North American plasma powder production. Nebraska and Iowa rendering clusters process over 70 percent of regional volume within 150 miles of pet food manufacturing hubs.
United States
Kansas and Texas packing plants now supply 35 percent of high-protein plasma through direct captive contracts with Mars Petcare and Nestlé Purina. The FDA's Center for Veterinary Medicine tightened immunoglobulin documentation requirements in 2023. Nebraska rendering corridors face stricter EPA Clean Air Act enforcement than Missouri counterparts.
Canada
Alberta and Saskatchewan beef packing consolidation creates captive blood collection opportunities with lower compliance costs than US facilities. Health Canada and the Canadian Food Inspection Agency jointly oversee rendered ingredient safety with streamlined veterinary feed registration. Ontario pet food manufacturers source increasingly from Prairie Provinces rendering infrastructure.
Mexico
Northern border states cattle slaughter capacity feeds cross-border plasma fractionation demand from Texas processors. Mexico's Federal Commission for the Protection against Sanitary Risk (COFEPRIS) regulates imported rendered ingredients with harmonized standards to FDA guidelines. Sonora and Chihuahua packing clusters supply raw material to southwestern US rendering facilities.
North America Plasma Powder Market Competitive Landscape
Global rendering majors compete with regional protein specialists across feedstock security and spray-drying precision. Market structure tilts toward integrated processors with captive slaughterhouse relationships, fragmenting among commodity plasma blenders and premium fractionators. Three archetypes dominate: vertically integrated meatpackers with rendering divisions, independent rendering operators with multi-species sourcing, and specialty plasma fractionators serving laboratory research. Capacity expansion and direct supply contracting with pet food manufacturers represent the dominant competitive vectors.
Within the integrated meatpacker tier, Smithfield Foods, Inc. exemplifies captive supply advantages through pork processing operations reducing third-party feedstock dependency. Darling Ingredients Inc. anchors the independent rendering archetype with multi-facility networks spanning the United States and Canada. APC Inc. occupies the specialty fractionator position with long-term Midwestern packing plant contracts securing consistent high-protein plasma production.
| Leading Market Players |
|---|
| Darling Ingredients Inc. |
| APC Inc. |
| Proliant Biologicals |
| Rocky Mountain Biologicals |
| Smithfield Foods, Inc. |
| Boyd Specialties |
| Sonac USA LLC |
| IQI Trusted Petfood Ingredients |
| American Protein Corporation |
| Others |
Pricing and Supply Chain Analysis
Immunoglobulin assay technician scarcity across Nebraska and Iowa widens pricing-tier spreads, as qualified analytical chemists command salary premiums that compress margins in standard-grade plasma while specialty-grade producers pass labor costs downstream.
Pricing Analysis
Certificate-of-analysis bundling separates premium plasma contracts from unbundled commodity transactions, with spray-dried high-protein variants commanding substantial markups over granulated alternatives due to sub-5-percent moisture guarantees. Price differentiation rests on FDA Center for Veterinary Medicine compliance tier and captive supply verification, with direct-contracting pet food manufacturers showing lowest price sensitivity and mass-market feed blenders absorbing cost compression from plant protein substitutes. Pricing pressure intensifies in mid-tier formulations as fermented yeast isolates displace plasma in palatability systems.
Supply Chain Analysis
Refrigerated transport costs from slaughterhouse to rendering facility anchor feedstock economics, with blood spoilage risk forcing collection radius constraints that concentrate processing in Iowa, Nebraska, and Kansas corridors. Raw material flows draw from bovine and porcine packing plants, with centrifugation equipment and spray-drying infrastructure as critical processing dependencies. Supply chain vulnerability centers on single-region concentration of slaughter capacity within 300 miles of Omaha. Distribution runs through direct captive contracts with Mars Petcare and Nestlé Purina procurement teams, disintermediating traditional regional ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America plasma powder market operates as a cost-of-compliance story, where FDA Center for Veterinary Medicine immunoglobulin documentation requirements create a barrier-to-entry moat favoring processors with validated electronic chain-of-custody systems.
For Market Incumbents: Extend backward integration into captive blood collection at Alberta and Saskatchewan packing plants to secure lower-compliance-cost feedstock. Fortify spray-drying precision capabilities against specialty plasma competitors while absorbing legacy equipment retrofit costs through long-term Nestlé Purina and Mars Petcare contracts. Plant protein substitution in mid-tier pet food represents the primary margin threat requiring premium-tier migration. For New Entrants and Emerging Players: Launch via laboratory research specialty plasma distribution to exploit tenfold price tolerance differentials over commodity feed channels. Target Massachusetts and California academic procurement offices with custom-fractionated immunoglobulin isolates for cell culture media. White space concentrates in protein-free plasma for biomedical coating manufacturers and diagnostic reagent production. For Investors and Strategic Acquirers: The window for entry favors specialty fractionators with validated cold chain documentation and GMP-compliant infrastructure. Long-term viability hinges on regulatory data transparency capabilities rather than commodity scale. Watch for EPA Clean Air Act enforcement divergence between Iowa-Nebraska and Kansas-Missouri corridors as capacity relocation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Blood Collection | Smithfield Foods reduces third-party feedstock dependency through pork processing operations. |
| Spray-Drying Precision Equipment Upgrade | APC Inc. secures FDA Center for Veterinary Medicine compliance through batch-to-batch consistency. |
| Laboratory Research Specialty Plasma Launch | Proliant Biologicals captures high-margin immunoglobulin fractions for cell culture media. |
| Canadian Prairie Rendering Expansion | Darling Ingredients leverages lower Health Canada compliance costs versus US counterparts. |
| Direct Supply Contracting with Pet Food Manufacturers | Nestlé Purina procurement teams disintermediate regional ingredient brokers in Kansas. |
Research Methodology
Independent corroboration across rendering facility operators, pet food manufacturer procurement leads, and veterinary nutritionists underwrites the qualitative findings in this study. Primary interviews with FDA Center for Veterinary Medicine compliance officers, USDA Food Safety and Inspection Service inspectors, and EPA Clean Air Act permit administrators combined with secondary validation from SEC 10-K filings, customs trade data, and state-level feed ingredient registration databases. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in plasma powder forecasting. Segmentation dimensions span protein concentration tier, end-use application, form specification, and geographic production cluster. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment incorporate weaning piglet diet reformulation rates and spray-dried form adoption curves as industry-specific inputs.
Regulatory enforcement divergence, plant protein substitution acceleration, and slaughter capacity regionalization are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Cathode Materials Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
Graphite Materials Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
2D Materials Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Silica Aerogel Market