
 Anisotropic Conductive Films (ACF) Market | 2026-2036
Anisotropic Conductive Films (ACF) Market Size, Share, and Industry Trends Forecast 2026-2036
Anisotropic Conductive Films (ACF) Market Outlook
IEC 61215 qualification for photovoltaic module interconnects is redrawing supplier eligibility across adjacent electronics bonding sectors. Dexerials Corporation leverages its polymer synthesis capabilities to sustain dominance in display-grade ACF formulations. 3M Company anchors North American supply through fluoropolymer-backed conductive tape architectures. Resonac Holdings Corporation differentiates via integrated resin and particle manufacturing across Japan and Southeast Asia.
Anisotropic conductive films are adhesive polymer matrices loaded with precisely spaced conductive particles that enable unidirectional electrical connectivity under compression while maintaining lateral insulation, typically formulated with epoxy or acrylic bases containing nickel-gold coated polymer spheres at 3-10 micron diameters. These materials bond driver integrated circuits to display glass substrates in flat-panel manufacturing, replacing solder interconnects in heat-sensitive assemblies. Sheet-format ACF dominates display assembly applications where reel-to-reel processing demands dimensional stability, while paste variants capture emerging semiconductor packaging lines requiring dot-dispense precision. Thermal curing technology leads volume deployment in automotive sensor modules where outgassing tolerance is stringent, though UV curing is displacing incumbent methods in LED packaging for faster cycle throughput.
RoHS and REACH frameworks in Europe restrict cadmium and lead content in conductive particle metallization, forcing reformulation of legacy nickel-gold systems toward copper-silver alloys. Japan's METI enforces JIS standards for automotive electronics reliability that cascade into ACF qualification protocols for tier-one suppliers. FDA device-grade requirements in the United States impose biocompatibility testing on medical device interconnect films, creating a parallel certification track. Stakeholders must monitor divergence between regional material restrictions and end-use qualification timelines to avoid stranded inventory across overlapping supply chains.
Market Dynamics
Flexible OLED manufacturing in smartphones and tablets is compressing bonding cycle times and tightening particle alignment tolerances, forcing adhesive formulators to reconcile thermal expansion mismatches between driver ICs and glass substrates.
Growth Catalysts
- Display miniaturization:Foldable smartphone panels require ultra-fine pitch interconnects below 30 microns, expanding ACF deployment in hinge-flex circuits and curved-edge bonding.
- REACH compliance deadlines:European ECHA restrictions on cadmium and lead in conductive particle metallization are accelerating copper-silver alloy adoption across export-oriented supply chains.
- Automotive sensor module assembly:Camera and lidar manufacturers in Germany and Japan specify thermal-cure ACF for outgassing-sensitive optical packages.
Market Restraints
- Conductive particle supply concentration:Nickel-gold coated polymer sphere production clusters in South Korea and Japan, creating single-source vulnerability for non-integrated formulators.
- Acrylic resin price volatility:Petrochemical feedstock fluctuations directly compress margins for display-grade adhesive matrices.
- Reflow solder substitution limits:High-current power modules above 5A still require metallic interconnects, capping ACF addressable market in automotive power electronics.
Strategic Opportunities
- Medical device interconnects:FDA biocompatibility testing protocols for implantable electronics create premium certification tracks for epoxy-based films with documented cytotoxicity profiles.
- Chiplet packaging integration:Heterogeneous integration architectures converge microbump and ACF bonding in 2.5D interposers, opening paste-format dispensing lines.
- India electronics manufacturing:PLI scheme incentives for semiconductor assembly and display fabrication are attracting ACF qualification programs for domestic smartphone production.
Industry Challenges
- JIS automotive reliability certification:METI-enforced thermal cycling and humidity testing protocols extend qualification timelines to 18-24 months for tier-one supplier approval.
- Particle dispersion uniformity:Maintaining 3-10 micron sphere distribution across 500mm+ sheet widths demands capital-intensive coating equipment with sub-micron precision controls.
- Legacy solder infrastructure displacement:Display assembly lines must reconfigure compression bonding stations and rework protocols, creating transition friction for established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anisotropic Conductive Films (ACF) Market |
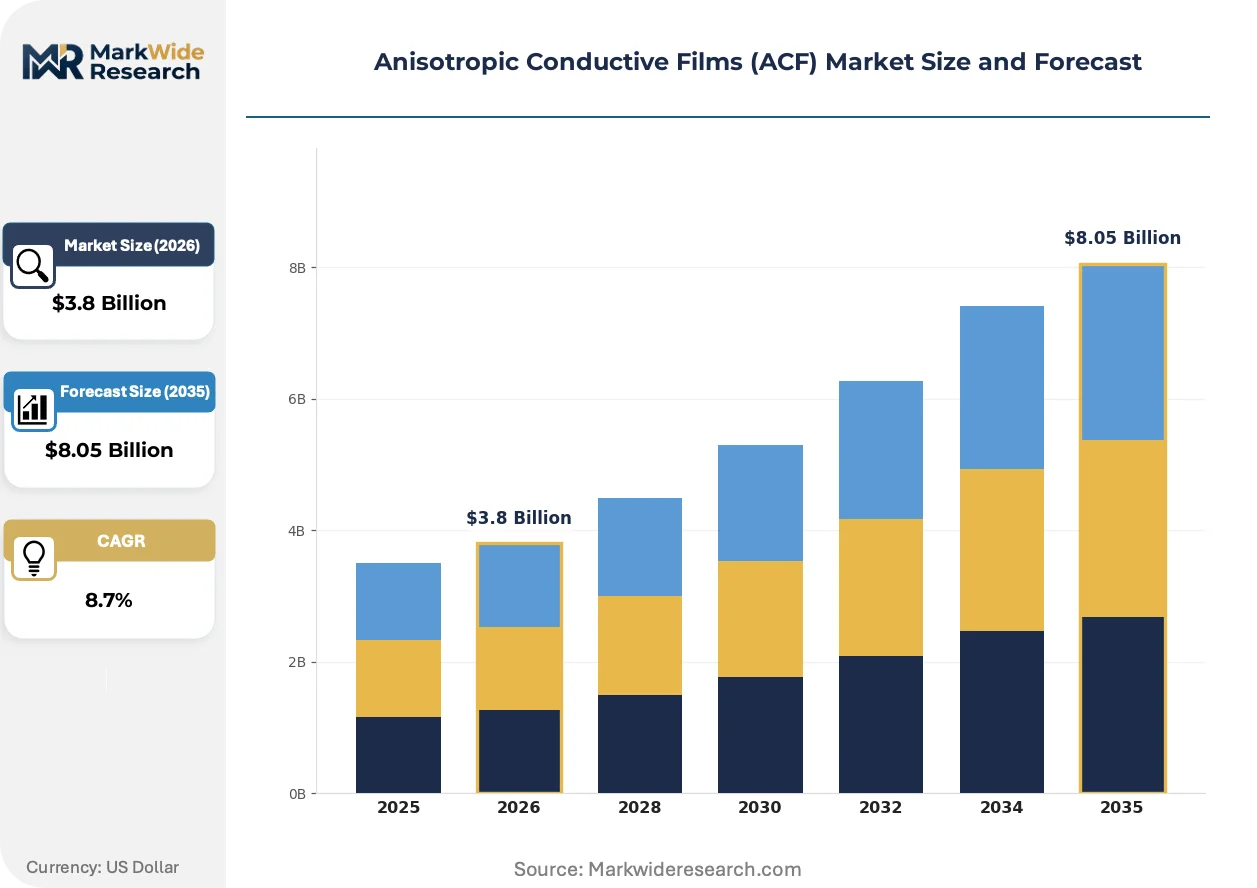
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Sheet, Tape, Paste Application: Display Assembly, Sensor Assembly, LED Packaging, Semiconductor Packaging End User: Consumer Electronics, Automotive, Aerospace, Medical Devices Technology: Thermal Curing, UV Curing, Solvent-Based, Non-Conductive Adhesive |
| Companies Covered | Dexerials Corporation, 3M Company, Resonac Holdings Corporation, Showa Denko Materials, Henkel AG & Co. KGaA, Hitachi Chemical, SunRay Scientific, H&S High-Tech Corporation, PVA TePla America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anisotropic Conductive Films (ACF) Market Strategic Shifts
UV-curable adhesive chemistries and particle metallurgy advances are compressing process windows while expanding ACF applicability beyond traditional display bonding into semiconductor packaging and automotive sensor modules.
Photoinitiator-accelerated epoxy formulations are displacing thermal-cure systems in LED backlight assembly lines. Display manufacturers in Taiwan and China adopt these chemistries to cut bonding cycle times from 15 seconds to under 5 seconds. The shift is compressing capital equipment footprints and enabling reel-to-reel processing for mini-LED matrix bonding.
RoHS and REACH frameworks in Europe restrict cadmium and lead content in conductive particle metallization. Formulators are reformulating legacy nickel-gold systems toward copper-silver alloys with documented biocompatibility profiles. Medical device manufacturers in Germany and Switzerland now specify these compliant films for diagnostic equipment interconnects.
Contract manufacturers are consolidating procurement around qualified material suppliers with integrated resin and particle capabilities. Tier-one display assemblers in South Korea now require backward integration certificates from ACF vendors. The concentration is visible in Seoul and Suwon, where Samsung and LG Display operations enforce single-source qualification for high-volume production lines.
Anisotropic Conductive Films (ACF) Market Segmentation
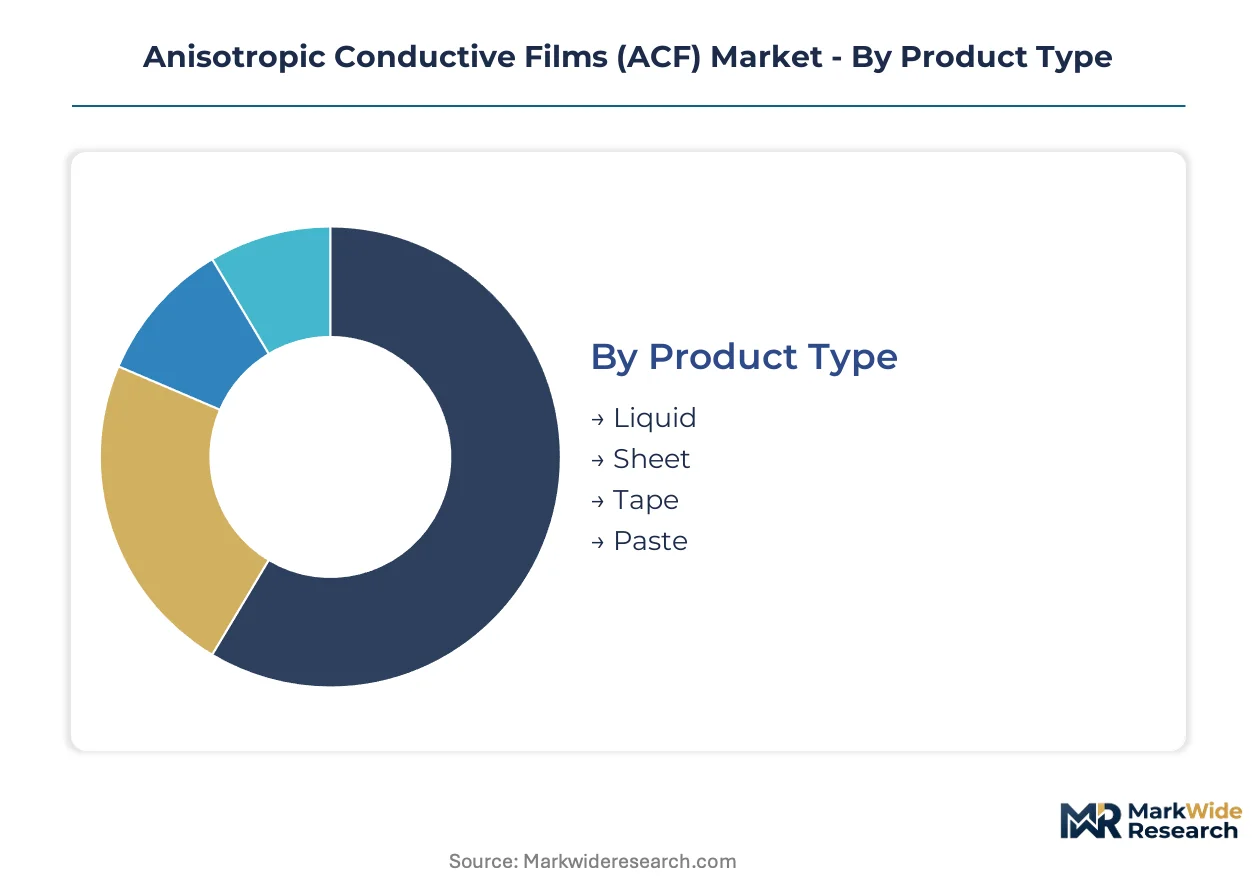
ACF segmentation reflects divergent manufacturing economics across display, semiconductor, and automotive bonding lines. Form factor and curing chemistry determine capital equipment compatibility and process throughput, while end-use qualification tiers create distinct margin architectures.
Product Type:
Sheet formats command premium positioning in high-volume display lines where dimensional stability justifies material cost, while liquid and paste variants compete on dispensing precision in emerging semiconductor packaging.
- Sheet:Continuous-roll polymer substrates with pre-dispersed conductive particles enable reel-to-reel processing in smartphone panel assembly. Samsung Display and LG Display operations in South Korea specify sheet ACF for foldable OLED hinge circuits where compression uniformity is critical.
- Paste:Dot-dispense formulations target chiplet packaging and microbump interconnects in 2.5D interposers. Taiwan Semiconductor Manufacturing qualification programs are expanding paste adoption for heterogeneous integration where precise volume control replaces sheet lamination.
- Liquid:Screen-printable formulations serve legacy LCD repair operations and cost-sensitive LED backlight assembly in China.
- Tape:Pressure-sensitive variants capture temporary bonding and rework applications in automotive sensor module prototyping.
The dominant share belongs to Sheet, while Paste is closing the gap fastest.
Application:
Display bonding generates the deepest volume pools, though semiconductor packaging is rewriting qualification requirements and supplier eligibility.
- Display Assembly:Driver IC-to-glass substrate bonding in smartphones, tablets, and televisions constitutes the foundational ACF use case. Ultra-fine pitch requirements below 30 microns in foldable panels are compressing particle alignment tolerances and forcing adhesive reformulation.
- Semiconductor Packaging:Microbump and interposer bonding in advanced packaging architectures. Intel and AMD chiplet roadmaps are integrating ACF alongside solder microbumps, creating hybrid interconnect specifications.
- Sensor Assembly:Camera module and lidar package bonding in German and Japanese automotive supply chains. Thermal-cure epoxies dominate here for outgassing control in optical paths.
- LED Packaging:Mini-LED and micro-LED matrix bonding for backlight and direct-view displays. UV-curable formulations are displacing thermal cure to cut cycle times from 15 seconds to under 5 seconds.
Display Assembly retains volume leadership, though Semiconductor Packaging is expanding most quickly as heterogeneous integration architectures mature.
End User:
Consumer electronics absorbs the majority of material throughput, yet automotive and medical qualification tracks offer superior margin protection through certification barriers.
- Consumer Electronics:Smartphone, tablet, and television manufacturing in South Korea, China, and Vietnam. Flexible OLED adoption in foldable devices is tightening particle pitch requirements and accelerating copper-silver alloy particle migration.
- Automotive:Camera, lidar, and radar module assembly subject to METI JIS reliability standards. German manufacturers specify thermal-cure ACF for optical package outgassing tolerance.
- Medical Devices:Diagnostic and implantable electronics requiring FDA biocompatibility certification. Swiss and German device manufacturers specify epoxy-based films with documented cytotoxicity profiles.
- Aerospace:Satellite and avionics interconnects demanding extended temperature range performance. Volume remains constrained by qualification timelines and program-specific specifications.
Consumer Electronics dominates material consumption, while Medical Devices is gaining share fastest through premium pricing for certified formulations.
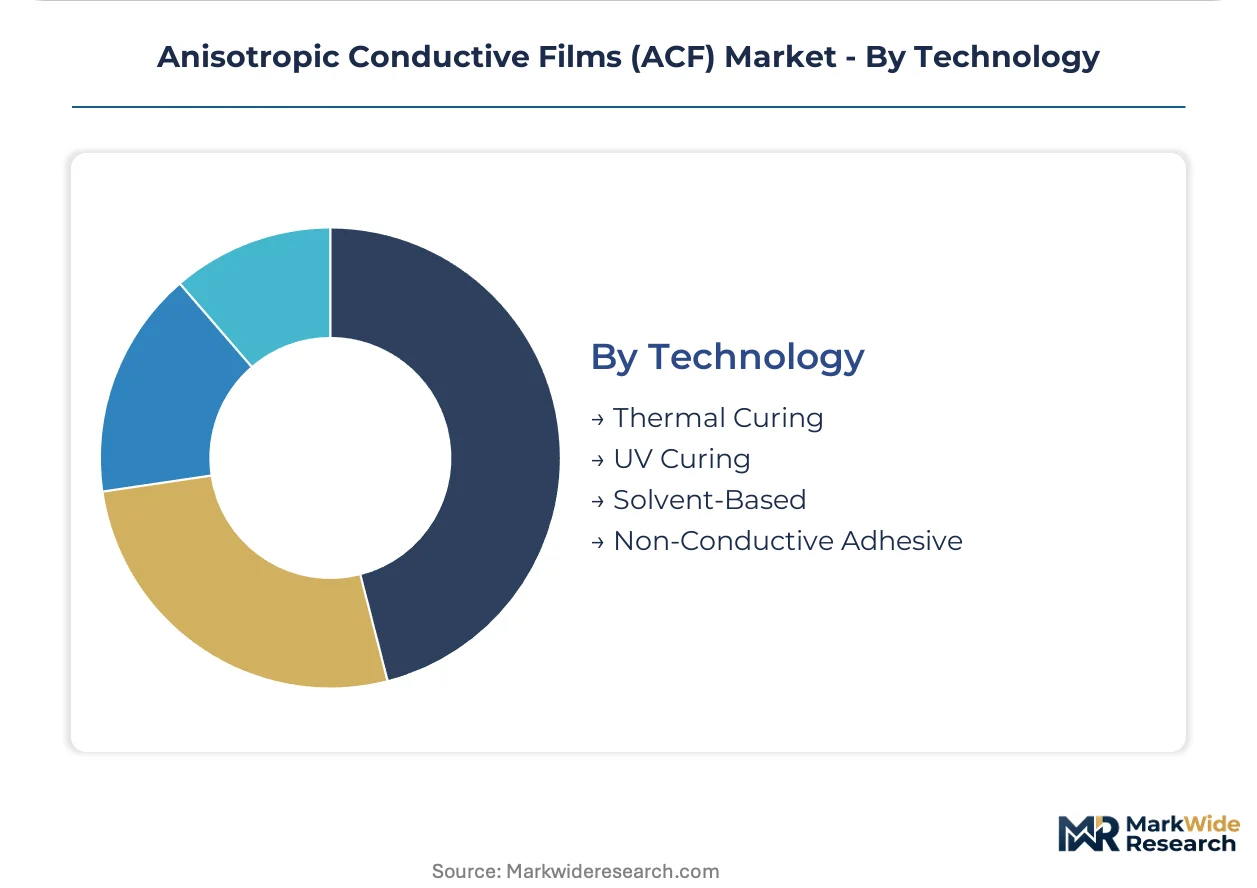
Technology:
Thermal curing anchors installed capacity, though UV acceleration is compressing process economics in throughput-sensitive LED and display lines.
- Thermal Curing:Epoxy-based systems cured at elevated temperatures deliver the highest reliability for automotive and aerospace applications. German and Japanese tier-one suppliers specify thermal cure for sensor modules where outgassing tolerance is stringent.
- UV Curing:Photoinitiator-accelerated formulations enable sub-5-second bonding cycles. Taiwan and China display manufacturers are converting LED backlight lines to UV cure for reel-to-reel throughput gains.
- Solvent-Based:Legacy formulations retaining niche position in cost-sensitive repair operations and developing market LCD assembly.
- Non-Conductive Adhesive:Purely mechanical bonding alternatives competing in applications where electrical connectivity is achieved through separate interconnect layers.
Thermal Curing holds the dominant share, while UV Curing is climbing the fastest as display manufacturers prioritize capital efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and METI-backed cluster development in Japan are redrawing ACF procurement geography as formulators chase qualification timelines in emerging electronics manufacturing zones.
South Korea
Samsung Display and LG Display operations in Seoul and Suwon drive sheet-format ACF consumption for foldable OLED hinge circuits. MFDS medical device regulations create parallel certification tracks for epoxy-based films in diagnostic equipment. Gyeonggi-do province hosts the densest concentration of conductive particle coating facilities serving smartphone panel assembly lines.
Japan
METI enforces JIS standards for automotive electronics reliability that cascade into 18-24 month ACF qualification protocols for tier-one suppliers. Chubu region polymer synthesis specialists supply resin matrices to display manufacturers across Asia. Nagoya-based automotive sensor module assemblers specify thermal-cure formulations for outgassing-sensitive optical packages.
China
MIIT dual carbon goals accelerate UV-curable adhesive adoption in LED backlight manufacturing to cut energy-intensive thermal cure cycles. Pearl River Delta contract manufacturers consolidate procurement around qualified suppliers with backward integration certificates. Shenzhen and Dongguan mini-LED matrix bonding lines convert to sub-5-second photoinitiator-accelerated processing.
United States
FDA biocompatibility testing protocols for implantable electronics create premium certification tracks for medical device interconnect films. EPA restrictions on volatile organic compounds in solvent-based formulations push adhesive formulators toward epoxy systems. Arizona and Texas semiconductor packaging facilities evaluate paste-format ACF for heterogeneous integration architectures.
Germany
ECHA REACH restrictions on cadmium and lead in conductive particle metallization force copper-silver alloy reformulation across export-oriented supply chains. Bavarian automotive camera and lidar manufacturers specify thermal-cure ACF for optical package outgassing tolerance. Munich-based tier-one suppliers enforce JIS-equivalent reliability testing for sensor module interconnects.
Anisotropic Conductive Films (ACF) Market Competitive Environment
Listed leaders compete with private specialists across integrated resin and particle manufacturing capabilities. The vendor base stratifies between diversified chemical conglomerates with captive polymer synthesis and focused adhesive formulators sourcing raw materials externally. Three archetypes dominate: integrated resin-particle manufacturers, fluoropolymer-backed tape specialists, and regional paste-format dispensers. Competitive moves concentrate on backward integration into conductive sphere production and qualification program consolidation around single-source certificates.
Among Japan-based integrated manufacturers, Dexerials Corporation and Resonac Holdings Corporation exemplify the resin-particle integration archetype, while 3M Company anchors North American supply through diversified materials science capabilities. These three entities occupy positions across distinct technology vectors—display-grade sheet formulations, semiconductor packaging pastes, and fluoropolymer-backed architectures—reflecting how geographic clustering and manufacturing scale shape competitive positioning in qualification-intensive segments.
| Leading Market Players |
|---|
| Dexerials Corporation |
| 3M Company |
| Resonac Holdings Corporation |
| Showa Denko Materials |
| Henkel AG & Co. KGaA |
| Hitachi Chemical |
| SunRay Scientific |
| H&S High-Tech Corporation |
| PVA TePla America |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization above 85% at South Korean conductive particle coating facilities compresses margin buffers for non-integrated formulators while reinforcing price floors for backward-integrated suppliers. This scale dynamic concentrates procurement leverage among Samsung Display and LG Display operations, which enforce single-source qualification certificates that amplify supplier switching costs.
Pricing Analysis
Certification level creates the primary spread between automotive JIS-grade thermal-cure formulations and commodity LED backlight materials. Three-tier pricing structure across medical-grade, automotive-grade, and consumer-grade levels reflects documentation burden and testing timeline differentials. Cost compression in display-grade sheet formats is intensifying because acrylic resin feedstock volatility transfers directly to adhesive matrix costs. Contract manufacturers in Vietnam and India exhibit highest price sensitivity, while German automotive tier-one suppliers prioritize outgassing tolerance over unit economics.
Supply Chain Analysis
South Korea and Japan anchor conductive particle coating capacity, with Gyeonggi-do province hosting the densest concentration of nickel-gold and copper-silver sphere production. Resin matrix supply draws from Chubu region polymer synthesis specialists and Chinese petrochemical feedstock corridors. Single-source vulnerability concentrates in 3-10 micron coated polymer sphere production, where equipment with sub-micron precision controls requires capital-intensive deployment. Distribution runs through qualified material suppliers with integrated resin and particle capabilities, consolidating around backward integration certificates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible OLED manufacturing disruption and REACH compliance deadlines are compressing qualification timelines while expanding addressable applications beyond traditional display bonding.
For Market Incumbents: Consolidate backward integration into conductive sphere production to defend against acrylic resin price volatility and particle supply concentration risks. Capture emerging medical device certification tracks by investing in FDA biocompatibility documentation for epoxy-based films. Expand capacity in Gyeonggi-do or Chubu regions to maintain proximity to Samsung Display and LG Display procurement clusters. For New Entrants and Emerging Players: Lead with paste-format dispensing precision targeting chiplet packaging lines at Taiwan Semiconductor Manufacturing qualification programs. Exploit underpenetrated India electronics manufacturing zones where PLI scheme incentives are attracting domestic smartphone production. Position UV-curable formulations for Shenzhen mini-LED matrix bonding lines converting from thermal cure cycles. For Investors and Strategic Acquirers: Integrated resin-particle manufacturers with documented JIS automotive reliability certification represent the most defensible acquisition profile. Long-term viability hinges on qualification program consolidation and single-source certificate accumulation over the projection horizon. Monitor divergence between regional material restrictions and end-use qualification timelines as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Sphere Production | Captive supply of nickel-gold and copper-silver coated polymer spheres insulates margin compression from feedstock volatility. |
| FDA Biocompatibility Certification Investment | Medical-grade epoxy formulations with documented cytotoxicity profiles command premium positioning in German and Swiss diagnostic equipment. |
| UV-Curable Formulation Platform Development | Photoinitiator-accelerated systems enable sub-5-second bonding cycles for Taiwan and China LED backlight manufacturing. |
| India PLI Scheme Qualification Program | Domestic smartphone production incentives in India electronics manufacturing zones attract ACF vendor certification investments. |
| JIS Automotive Reliability Certification | METI-enforced thermal cycling protocols extend tier-one supplier approval timelines while creating certification barriers. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with adhesive formulators, display procurement managers, and automotive tier-one supplier quality directors; and secondary validation through customs trade data, SEC filings of listed chemical conglomerates, and METI JIS standard documentation. Primary fieldwork centered on South Korea, Japan, and China manufacturing clusters. Bottom-up and top-down triangulation reconciled particle coating capacity estimates with downstream display assembly demand.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application, end user, and curing technology dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included foldable OLED panel production ramps, REACH compliance deadline impacts on conductive particle metallization, and heterogeneous integration adoption curves in semiconductor packaging.
The analysis sits within stated boundaries; outcomes outside sustained flexible display manufacturing expansion and regulatory compliance timeline adherence would require recalibration. Forecasts reflect assumptions regarding acrylic resin feedstock stability, particle dispersion equipment availability, and automotive sensor module qualification program progression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Wood Foam Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Artificial Marble Products Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Extracellular Matrix Proteins Market