
 US and Canada Helium Gas Market | 2026-2036
US and Canada Helium Gas Market Size, Share, and Industry Trends Forecast 2026-2036
US and Canada Helium Gas Market Outlook
Buyer concentration among semiconductor fabricators and space launch operators is decoupling from traditional healthcare and party-balloon segments. North American Helium Inc. leverages its Saskatchewan acreage to supply cryogenic-grade helium directly to chip foundries. Air Products and Chemicals, Inc. sustains long-term offtake agreements with NASA and commercial spaceports across the US Gulf Coast. Linde plc anchors its position through backward integration into the BLM helium pipeline system and downstream liquid helium logistics.
Helium gas is an inert, non-flammable noble gas with a boiling point of minus 268.9 degrees Celsius, extracted primarily from natural gas reservoirs where radioactive decay of uranium and thorium generates alpha particles that capture electrons to form helium nuclei. Its primary industrial purpose centers on extreme cryogenics, superconducting magnet cooling, inert atmosphere shielding, and leak detection in high-value manufacturing. Liquid helium dominates margin pools due to the energy-intensive liquefaction process and specialized transport requirements, while cryogenics leads application growth driven by MRI scanner installations and quantum computing R&D. Gaseous helium retains volume leadership in welding and lifting applications, though compressed helium cylinders face substitution pressure from argon blends in certain fabrication settings.
FAA regulations governing helium-transporting vehicles and OSHA workplace exposure standards shape product packaging and handler certification requirements across both countries. The US Bureau of Land Management's helium stewardship transition and Canada's CNSC oversight of radioactive-source helium extraction jointly determine field development timelines and investment certainty. Stakeholders must monitor BLM pipeline auction mechanics and Saskatchewan provincial royalty frameworks to calibrate upstream commitment levels against downstream contract durations.
Market Dynamics
The US Bureau of Land Management's helium reserve privatization is restructuring supply access, forcing downstream buyers to negotiate directly with private field operators rather than federal auctions.
Growth Catalysts
- Semiconductor cryogenics:Chip foundries in Texas and Arizona are expanding helium offtake for superconducting magnet cooling in EUV lithography systems, with new fabrication plants under construction driving volume commitments.
- FAA commercial space launch licensing:Expanded approvals for orbital and suborbital operations along the Gulf Coast are multiplying helium demand for rocket propellant pressurization and purge systems.
- Saskatchewan field development:Provincial royalty frameworks incentivizing helium extraction from nitrogen-rich gas reservoirs are attracting upstream investment to anchor North American supply diversification.
Market Restraints
- Feedstock concentration:Over half of North American helium derives from the Hugoton-Panhandle field spanning Kansas, Oklahoma and Texas, creating single-source vulnerability for cryogenic-grade supply.
- Natural gas pricing volatility:Helium extraction economics tie directly to methane market conditions, squeezing margins when benchmark Henry Hub prices collapse below field breakeven thresholds.
- Argon substitution in welding:Fabrication shops in the US Midwest are blending argon-carbon dioxide mixtures for TIG welding applications, compressing gaseous helium cylinder volumes in non-critical shielding uses.
Strategic Opportunities
- Quantum computing R&D clusters:National laboratories and private ventures in Colorado and Illinois are scaling dilution refrigerator helium consumption, creating premium-grade demand pockets with long-term contract potential.
- BLM pipeline auction mechanics:New private ownership of federal helium infrastructure enables negotiated transport tariffs rather than mandated pricing, allowing logistics providers to structure differentiated service tiers.
- Medical imaging replacement cycle:MRI scanner installations across Canadian provinces are accelerating as healthcare infrastructure ages, concentrating liquid helium demand in Ontario, Quebec and British Columbia hospital networks.
Industry Challenges
- Cryogenic logistics certification:DOT hazardous materials endorsements and OSHA workplace exposure training requirements are constraining qualified driver availability for liquid helium tanker operations.
- Field-to-fab integration timelines:Saskatchewan greenfield projects face protracted CNSC radioactive-source permitting for helium extraction, delaying first production against firm semiconductor customer delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Canada Helium Gas Market |
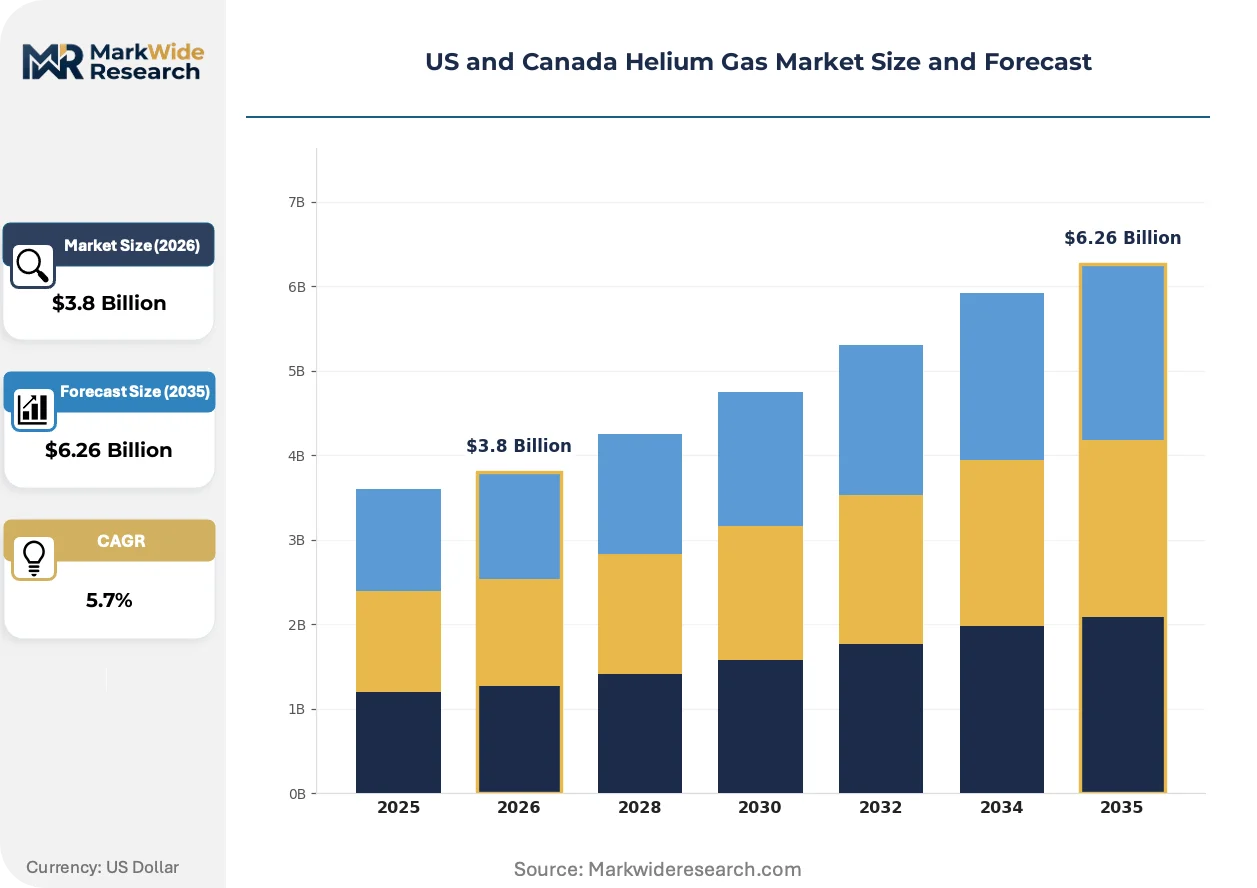
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Helium, Gaseous Helium, Helium Blends, Compressed Helium End Use Industry: Healthcare, Electronics, Aerospace, Defense Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets Application: Cryogenics, Leak Detection, Welding, Lifting |
| Companies Covered | North American Helium Inc., First Helium Inc., Pulsar Helium, Desert Mountain Energy, Helium Evolution, Air Liquide, Air Products and Chemicals, Inc., Linde plc, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Canada Helium Gas Market Strategic Shifts
Helium recovery and recycling infrastructure is overtaking once-through consumption models, with closed-loop systems now mandatory for cost containment in high-volume industrial settings.
Membrane separation technology is overtaking cryogenic distillation for gaseous helium purification at mid-scale facilities, cutting energy intensity by half while enabling on-site recycling at semiconductor fabrication plants. Foundries in Oregon and New Mexico are installing these systems to reclaim purge gas. The shift is compressing reliance on liquid helium deliveries for non-cryogenic process steps.
OSHA's revised workplace exposure standards for inert gases are tightening handler certification requirements across US manufacturing and research facilities. The rule changes mandate refresher training every three years rather than five, elevating compliance costs for employers with large helium cylinder inventories. Academic and national laboratory end-users in the Northeast are consolidating vendor relationships to offload certification liability.
Direct long-term contracting is displacing spot market purchases among MRI service providers and semiconductor fabricators, with buyers seeking five-to-ten-year supply security. This pattern concentrates procurement leverage among multi-site hospital networks and foundry operators with predictable consumption profiles. The shift is most pronounced in Texas and California, where consumption scale justifies dedicated field offtake negotiations.
US and Canada Helium Gas Market Segmentation
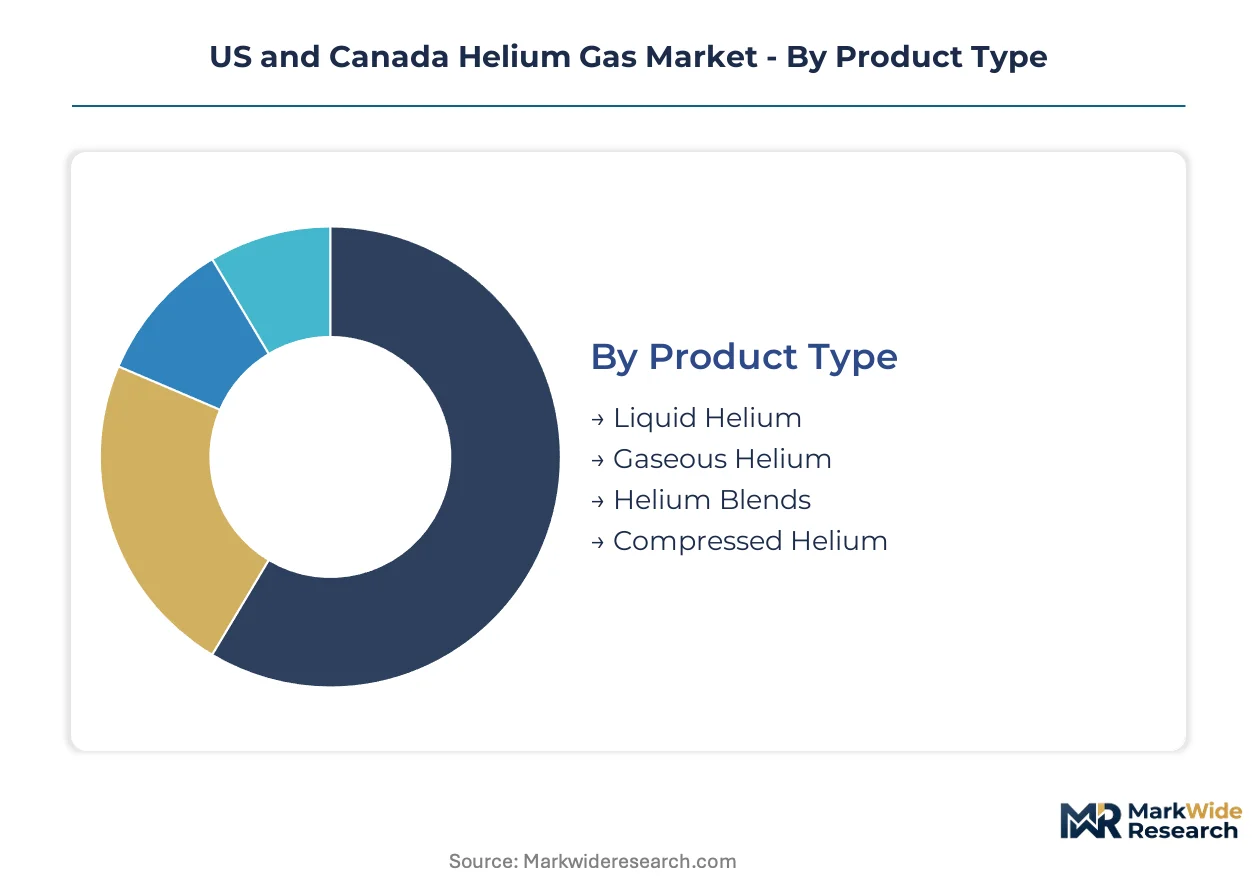
Helium gas segmentation reveals divergent margin profiles across physical states and application intensities. Product form determines logistics infrastructure requirements, while end-use concentration shapes contract duration and pricing power.
Product Type:
Liquid helium commands premium pricing due to energy-intensive liquefaction and specialized cryogenic transport, while gaseous helium dominates volume throughput through simpler cylinder logistics.
- Liquid Helium:Ultra-low temperature fluid at minus 268.9 degrees Celsius requiring vacuum-insulated tanker transport. Demand concentrates in Texas and Arizona semiconductor foundries where EUV lithography superconducting magnets require continuous cryogenic cooling. Supply security concerns are driving long-term direct contracts with Saskatchewan field developers.
- Gaseous Helium:Compressed gas stored in high-pressure cylinders or tube trailers for industrial distribution. Consumption clusters along the US Gulf Coast at NASA facilities and commercial spaceports for rocket propellant pressurization and purge operations. FAA transport regulations govern cylinder fleet certification.
- Helium Blends:Binary and ternary mixtures with argon or nitrogen calibrated for specific shielding atmospheres. Welding shops in the US Midwest utilize argon-helium blends for enhanced arc stability on aluminum alloys.
- Compressed Helium:High-pressure cylinder packaging for laboratory and small-scale industrial users. Academic institutions in Colorado and Illinois maintain inventories for quantum computing dilution refrigerator servicing.
Mature deployment sits with Gaseous Helium. Newer deployment is concentrated in Liquid Helium as semiconductor fabrication scales.
End Use Industry:
Customer type determines procurement sophistication, with institutional buyers negotiating multi-year supply agreements against spot-market participants.
- Healthcare:MRI scanner magnet cooling and respiratory therapy applications. Hospital networks in Ontario, Quebec and British Columbia are accelerating liquid helium offtake as Canadian healthcare infrastructure ages and scanner replacement cycles intensify.
- Electronics:Semiconductor fabrication, fiber optic manufacturing, and display panel production. Chip foundries in Texas and Arizona are the fastest-expanding demand segment as EUV lithography deployment multiplies superconducting magnet cooling requirements.
- Aerospace:Rocket propulsion pressurization, purge systems, and leak detection. FAA-licensed commercial spaceports along the Gulf Coast are multiplying launch frequency and helium consumption per mission.
- Defense:Surveillance balloon programs, missile systems testing, and naval applications. Procurement flows through federal supply schedules with stringent traceability requirements.
Procurement sophistication peaks in Electronics. Contract fragmentation persists in Healthcare.
Distribution Channel:
Channel selection reflects buyer scale and consumption predictability, with large-volume users bypassing intermediaries.
- Direct Sales:Field-to-fab contracts between Saskatchewan producers and semiconductor foundries. These agreements specify cryogenic-grade purity standards and dedicated tanker allocation.
- Distributors:Regional gas specialists managing cylinder exchange programs for welding shops and smaller manufacturers. OSHA handler certification requirements are constraining qualified distributor capacity.
- Online Sales:E-commerce platforms for laboratory-grade cylinder orders and specialty gas mixtures. Academic and research end-users in the Northeast are consolidating purchases through vendor-managed inventory portals.
- Retail Outlets:Consumer-facing party balloon and recreational lifting gas sales. This channel faces volume pressure as helium conservation campaigns reduce non-essential consumption.
Channel power concentrates in Direct Sales. Distributors retain relevance in fragmented geographic pockets.
Application:
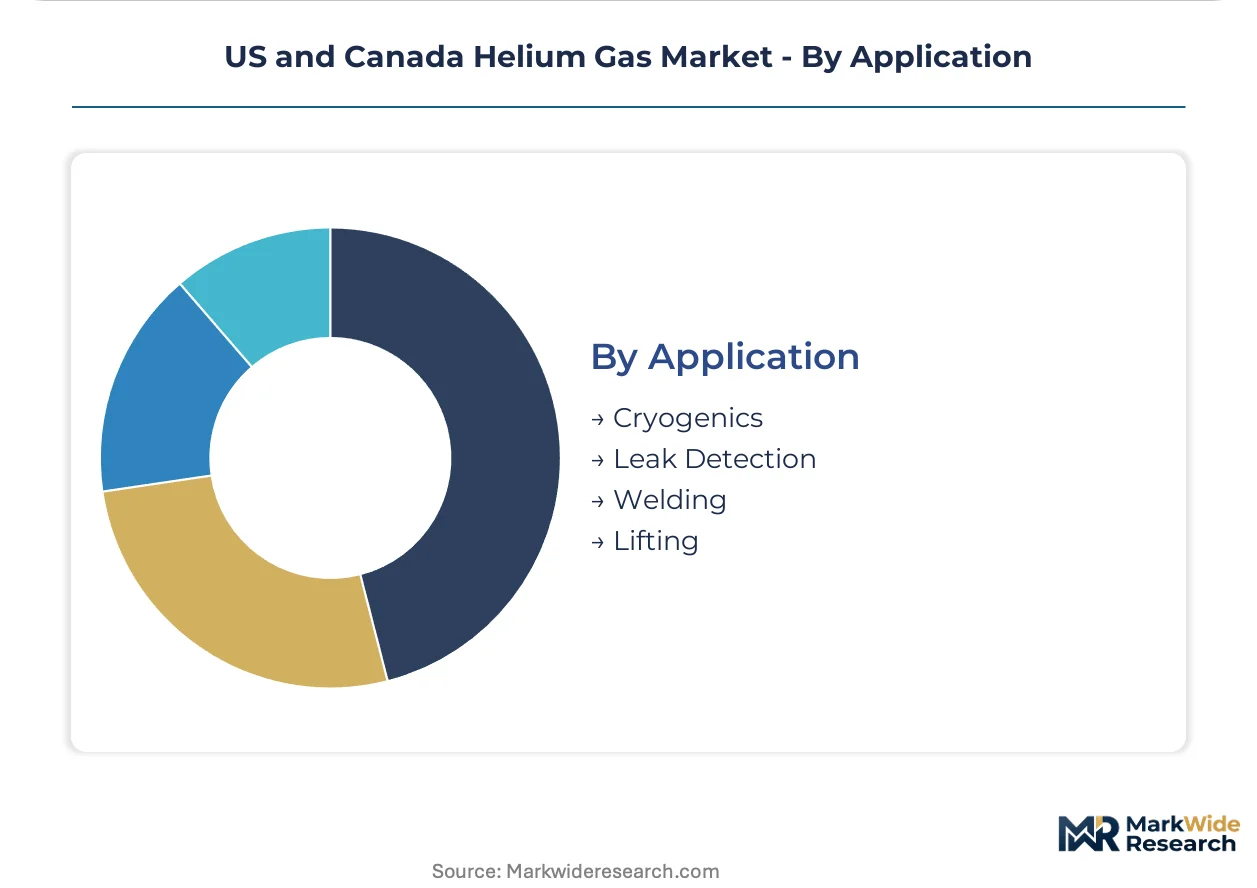
Application segmentation separates high-value cryogenic uses from commodity lifting and shielding functions.
- Cryogenics:Superconducting magnet cooling for MRI, particle accelerators, and quantum computing research. National laboratories in Colorado and Illinois are scaling dilution refrigerator helium consumption for quantum R&D clusters.
- Leak Detection:Mass spectrometer tracer gas for vacuum system integrity testing. Semiconductor fabrication plants deploy helium leak detection for chamber qualification and process tool maintenance.
- Welding:Inert atmosphere shielding for TIG and MIG processes. Argon substitution is compressing helium market share in non-critical fabrication applications across the US Midwest.
- Lifting:Buoyant gas for weather balloons, aerostats, and parade floats. Defense surveillance programs sustain institutional demand despite recreational segment contraction.
Technology intensity peaks in Cryogenics. Price sensitivity dominates in Welding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundries and space launch operators concentrate helium demand in Texas, Arizona, and the US Gulf Coast, while Canadian healthcare networks anchor liquid helium consumption in Ontario and Quebec. Saskatchewan's nitrogen-rich gas reservoirs are emerging as a strategic supply source for cryogenic-grade helium.
United States
EUV lithography deployment at Texas and Arizona chip foundries multiplies superconducting magnet cooling requirements. FAA commercial space launch licensing along the Gulf Coast expands helium demand for rocket propellant pressurization. Houston anchors downstream logistics infrastructure serving NASA facilities and private spaceports.
Canada
Aging MRI scanner replacement cycles across Ontario, Quebec, and British Columbia hospital networks concentrate liquid helium demand. Saskatchewan provincial royalty frameworks incentivize helium extraction from nitrogen-rich reservoirs. North American Helium Inc. leverages Saskatchewan acreage to supply cryogenic-grade helium directly to semiconductor customers.
Saskatchewan
Provincial helium extraction incentives attract upstream investment to diversify North American supply away from Kansas-Oklahoma-Texas concentration. CNSC radioactive-source permitting governs field development timelines for helium extraction from geological formations. Swift Current and Kindersley sub-regions host active drilling programs targeting nitrogen-rich gas reservoirs.
Texas
Hugoton-Panhandle field production sustains cryogenic-grade helium supply for domestic semiconductor and aerospace demand. OSHA workplace exposure standards and DOT hazardous materials endorsements shape handler certification requirements for liquid helium logistics. Dallas-Fort Worth serves as distribution hub for cylinder and tube trailer operations across the Southwest.
Arizona
New semiconductor fabrication capacity under construction drives long-term helium offtake commitments for EUV lithography cooling systems. State economic development incentives for advanced manufacturing attract chip foundry investment with embedded helium supply requirements. Phoenix metro fabrication clusters negotiate direct field contracts bypassing traditional distributor channels.
US and Canada Helium Gas Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue Saskatchewan greenfield development and direct field-to-fab contracting. The market structure concentrates among integrated industrial gas majors with captive pipeline access and specialized cryogenic logistics capabilities. Three archetypes dominate: upstream field operators with Saskatchewan acreage, integrated industrial gas suppliers with BLM pipeline connectivity, and downstream distributors managing cylinder exchange programs. Competitive moves center on backward integration into helium extraction assets and long-term direct contracting with semiconductor foundries.
Within the integrated industrial gas tier, Air Products and Chemicals, Inc. and Linde plc occupy positions defined by pipeline infrastructure access and liquid helium logistics scale. North American Helium Inc. exemplifies the upstream-focused archetype leveraging Saskatchewan reservoir access. These three entities represent contrasting strategic positions: pipeline-integrated majors, field-developing specialists, and diversified industrial gas incumbents.
| Leading Market Players |
|---|
| North American Helium Inc. |
| First Helium Inc. |
| Pulsar Helium |
| Desert Mountain Energy |
| Helium Evolution |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Linde plc |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up field operators in Saskatchewan and Kansas-Oklahoma-Texas are consolidating upstream acreage to tighten supply discipline and sustain cryogenic-grade helium premiums against volatile natural gas benchmarks.
Pricing Analysis
Volume leadership sits with gaseous helium through compressed cylinder distribution, while liquid helium captures disproportionate margins via energy-intensive liquefaction and vacuum-insulated tanker logistics. Three-tier pricing structure across cryogenic-grade, industrial-grade, and balloon-grade purity levels separates semiconductor foundry contracts from welding shop cylinder exchanges. Pricing pressure stems from argon substitution in non-critical TIG welding across the US Midwest, compressing industrial-grade helium spreads. Electronics fabricators exhibit the least price sensitivity due to EUV lithography magnet cooling requirements, while party-balloon retailers face maximum substitution elasticity.
Supply Chain Analysis
Domestic-content mandates under the US Bureau of Land Management's helium stewardship transition are reshaping sourcing patterns toward North American field development. Supply concentrates in the Hugoton-Panhandle field spanning Kansas, Oklahoma, and Texas, with Saskatchewan nitrogen-rich reservoirs emerging as diversification anchors. Raw material dependencies include natural gas feedstock, cryogenic liquefaction equipment, and DOT-certified tanker fleets. Single-source vulnerability runs through the Kansas-Oklahoma-Texas concentration for cryogenic-grade output. Distribution runs through direct field-to-fab contracts for semiconductor foundries and cylinder exchange programs for fragmented welding and laboratory end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where OSHA's triennial handler certification refresh and DOT hazardous materials endorsements create barrier-to-entry moats for logistics providers with qualified driver pools.
For Market Incumbents: Anchor supply security through backward integration into Saskatchewan greenfield development and captive BLM pipeline tariff negotiations. Defensive moves center on long-term direct contracting with Texas and Arizona semiconductor foundries to lock volume against emerging field operators, plus certification infrastructure investment to absorb OSHA compliance liability from fragmented distributor networks. For New Entrants and Emerging Players: E-commerce platforms for laboratory-grade cylinder orders offer the most penetrable route into academic and national laboratory end-users in Colorado and Illinois. White-space targets include quantum computing R&D clusters scaling dilution refrigerator consumption and Canadian hospital networks accelerating MRI replacement cycles. Go-to-market positioning emphasizes vendor-managed inventory portals consolidating Northeast academic purchases. For Investors and Strategic Acquirers: Distressed-cycle entries favor upstream field operators with Saskatchewan acreage and CNSC permitting progress when natural gas pricing volatility squeezes extraction economics. Long-term viability hinges on cryogenic-grade purity capabilities and direct semiconductor foundry relationships. The signal to watch is BLM pipeline auction mechanics shifting from mandated to negotiated tariffs as private ownership crystallizes transport cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Saskatchewan Extraction | Captures cryogenic-grade helium supply security for Texas and Arizona foundry commitments. |
| Long-term Direct Contracting with Semiconductor Fabricators | Locks volume and pricing power through five-to-ten-year field-to-fab agreements. |
| Cryogenic Logistics Certification Infrastructure | Absorbs OSHA triennial refresh liability and DOT endorsement constraints constraining competitor capacity. |
| Membrane Separation Technology Deployment | Enables on-site helium recycling at Oregon and New Mexico foundries, compressing liquid delivery dependence. |
| BLM Pipeline Tariff Negotiation | Structures differentiated service tiers as federal infrastructure transitions to private ownership. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cryogenic logistics directors, semiconductor procurement leads, BLM pipeline operators, Saskatchewan field developers, and MRI service technicians. Secondary sources incorporated US Bureau of Land Management auction records, FAA commercial space launch licensing databases, OSHA enforcement data, Canadian CNSC permitting timelines, and SEC 10-K disclosures from industrial gas majors. Bottom-up field production estimates triangulated against top-down end-use consumption models across semiconductor, healthcare, and aerospace segments.
Data-stream reconciliation across supply-side field development timelines and demand-side fabrication plant construction schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included physical state (liquid, gaseous, blends), end-use industry (electronics, healthcare, aerospace, defense), and distribution channel (direct sales, distributors, online platforms). CAGRs derived from production capacity buildout curves and offtake contract durations. Industry-specific forecast inputs encompassed EUV lithography deployment rates at Texas and Arizona foundries and FAA-licensed launch frequency along the Gulf Coast.
The model holds under stable BLM privatization timelines and Saskatchewan permitting progress; deviation in CNSC radioactive-source approval delays or Henry Hub price collapse would shift field development economics. Forecasts reflect documented assumptions regarding semiconductor fabrication construction schedules and MRI scanner replacement cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
Global Argon Market
Industrial Gases
Global Helium Gas Market
Industrial Gases
Syngas Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
Gas Sampling Line Market