
 Aluminum Plates and Sheet Coils Market | 2026-2036
Aluminum Plates and Sheet Coils Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Plates and Sheet Coils Market Outlook
Smelter electrician and rolling mill technician shortages across Europe and North America is reorganizing capacity expansion timelines for western producers. Novelis leverages captive recycling streams to sustain margin stability amid volatile LME pricing. Hindalco Industries anchors South Asian supply through backward integration into alumina refining and captive power. Norsk Hydro competes on certified low-carbon primary metal, differentiating its Norwegian hydropower-based output.
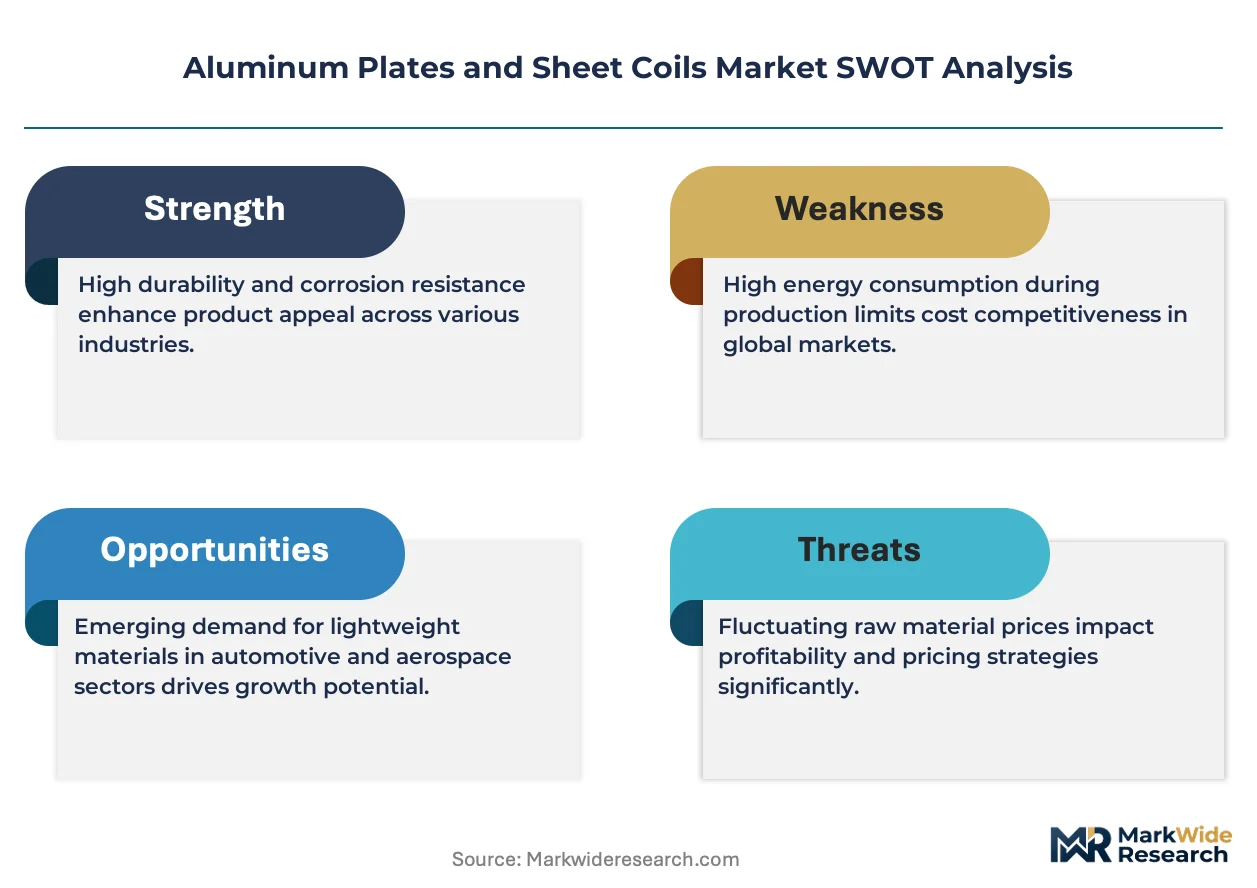
Aluminum plates and sheet coils are flat-rolled aluminum products manufactured through hot and cold rolling of cast slabs or continuous cast strip, typically spanning 0.2 mm to 150 mm in thickness and alloyed with magnesium, silicon, or zinc to achieve specific strength, corrosion resistance, and formability profiles. These products serve as critical inputs for structural components, thermal management systems, and barrier packaging where weight reduction and recyclability carry premium value. Sheets and plates for automotive OEMs represent the fastest-expanding consumption pool as crashworthiness specifications tighten and OEMs pursue multi-material body architectures. Medium-gauge coil for construction cladding remains the most mature revenue segment, with margin pools concentrating in painted and anodized finish types where application-specific certification creates pricing power.
The EU Green Deal and associated CBAM framework shape import competitiveness for Chinese and Gulf-origin metal, while EPA emissions rules under the US Inflation Reduction Act steer domestic buyers toward verified low-carbon supply. China's MIIT dual carbon targets and GB standards for building materials are accelerating scrap-based production and constraining new smelter approvals. Stakeholders must monitor how carbon accounting methodologies evolve across these jurisdictions, as scope-three emissions disclosure requirements will soon determine contract eligibility for major automotive and aerospace purchasing programs.
Market Dynamics
Automotive OEMs are accelerating aluminum sheet adoption for electric vehicle body-in-white structures as crashworthiness standards tighten and multi-material architectures become mandatory for range optimization.
Growth Catalysts
- EU Green Deal CBAM:Carbon border adjustments on imported primary aluminum are redirecting European automotive procurement toward verified low-carbon domestic and Norwegian hydropower-based supply chains.
- Electric vehicle platform scaling:Dedicated EV architectures from manufacturers in China and Germany are consuming medium-gauge coil at volumes that reshape rolling mill order books.
- Closed-loop recycling mandates:China's MIIT dual carbon targets and GB standards for building materials are accelerating scrap-based production and constraining new smelter approvals.
Market Restraints
- LME price volatility:Primary aluminum input costs swing with energy market disruptions, compressing rolling margins for non-integrated producers dependent on spot metal purchases.
- Smelter concentration in China:Over half of global primary capacity sits within Chinese state-backed entities, creating geopolitical supply risk for Western fabricators.
- Steel cost competitiveness:Advanced high-strength steel alloys retain cost advantage in non-structural automotive applications where weight reduction carries lower premium value.
Strategic Opportunities
- India domestic EV supply chain:Localized aluminum sheet production for two-wheeler and passenger EV platforms remains underdeveloped relative to projected demand curves.
- US Inflation Reduction Act credits:EPA emissions rules and domestic content bonuses steer automotive buyers toward verified low-carbon North American supply.
- Thermal management convergence:Battery pack cooling plates and heat exchanger stock represent emerging high-value applications where alloy specification creates pricing power.
Industry Challenges
- Rolling mill technician scarcity:Skilled operator pipelines in Germany, Norway, and the US Midwest are insufficient to staff announced capacity expansions.
- Automotive qualification timelines:OEM crashworthiness certification cycles for new alloy grades extend 18-36 months, locking out speculative capacity investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Plates and Sheet Coils Market |
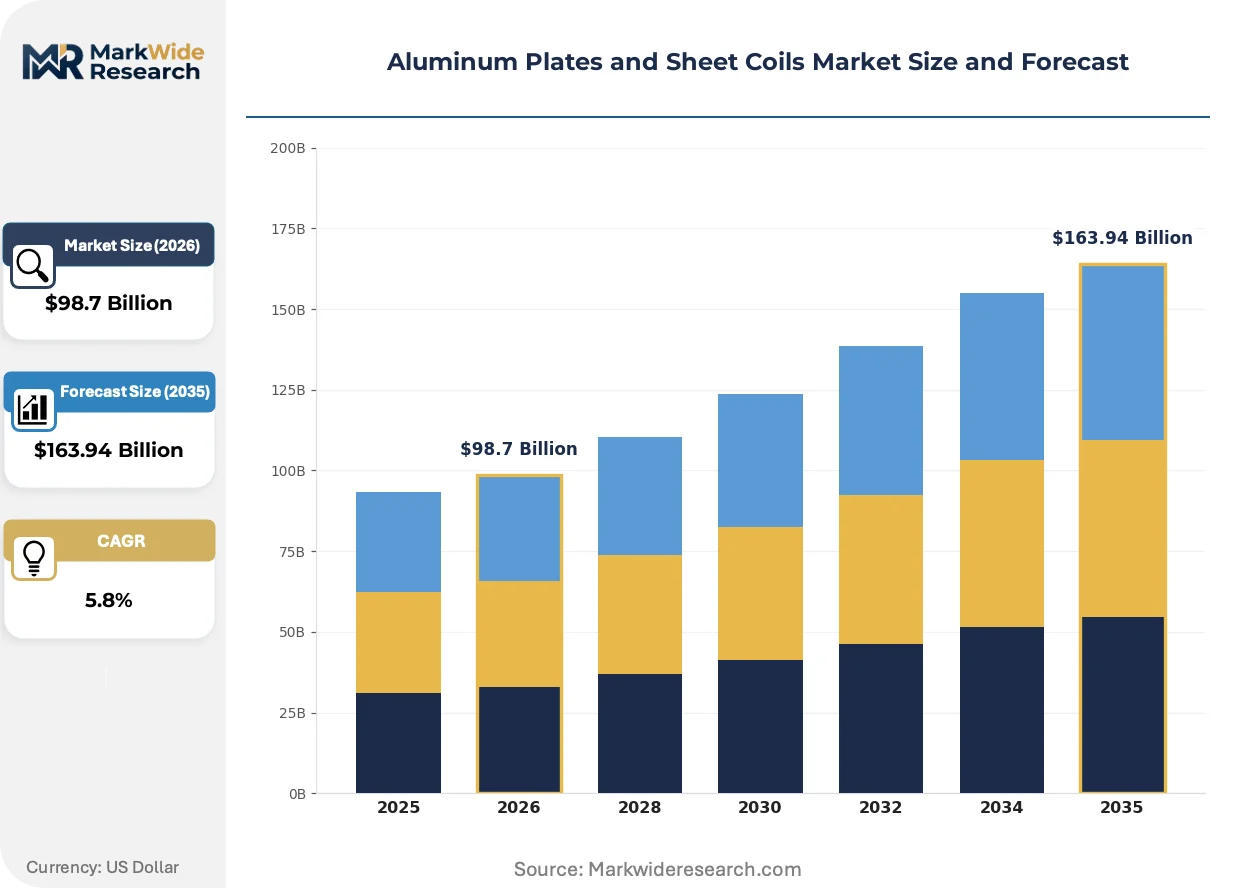
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Sheets, Foils, Strips End User: Aerospace, Automotive OEMs, Construction, Packaging Thickness: Thin, Medium, Heavy, Ultra-Heavy Finish Type: Anodized, Mill Finish, Painted, Coated |
| Companies Covered | Novelis, Arconic, Constellium, Hindalco Industries, Alcoa Corporation, Norsk Hydro, China Hongqiao Group, UACJ Corporation, Aluminum Corporation of China (Chinalco), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Plates and Sheet Coils Market Strategic Shifts
Process metallurgy and carbon accounting are converging to redefine competitive advantage in flat-rolled aluminum, with differentiation shifting from alloy specification to verified emissions intensity and closed-loop material provenance.
Novel continuous casting formats are displacing conventional DC-cast slab routes for thin-gauge automotive and packaging applications. European and Japanese OEMs have qualified these formats for non-structural body panels and thermal management components. The technology is displacing capital-intensive hot rolling capacity requirements and enabling faster product development cycles for tier-two suppliers.
REACH authorization and the EU F-Gas Regulation are tightening emissions disclosure requirements across the aluminum value chain. Industrial consequence includes mandatory scope-three reporting for automotive and aerospace purchasing programs. German and French OEMs are now contractually excluding high-carbon primary metal from body-in-white supply agreements.
Automotive buyers are consolidating supplier panels and demanding integrated recycling services alongside virgin material supply. Tier-one fabricators in Michigan and Bavaria are responding with on-site scrap processing and direct alloy returns to OEM stamping plants. This pattern is most visible in battery enclosure and structural component supply where material traceability carries regulatory weight.
Aluminum Plates and Sheet Coils Market Segmentation
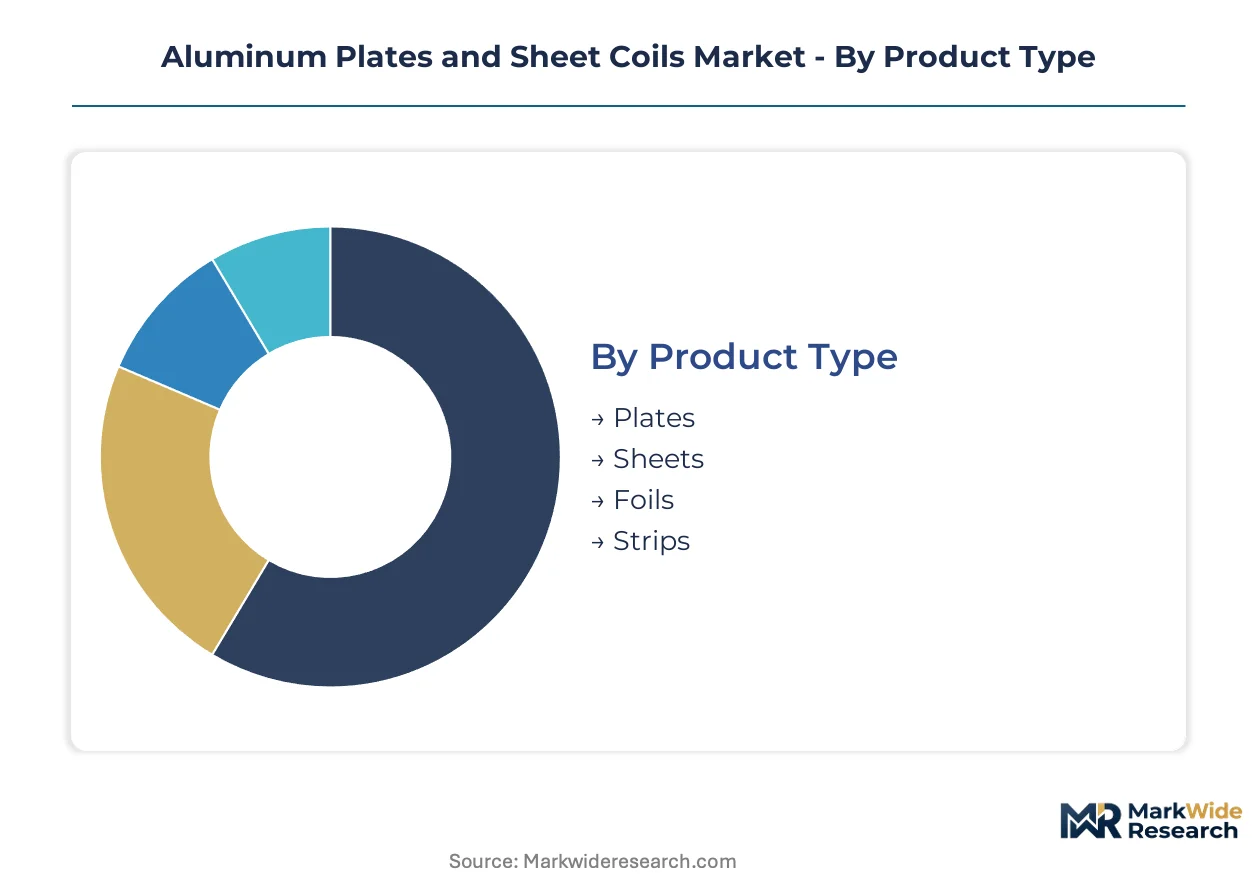
Aluminum plates and sheet coils serve heterogeneous industrial requirements where alloy specification, gauge tolerance, and surface finish determine contract eligibility. Segmentation reveals how margin pools concentrate in certified grades for regulated end-uses while commodity gauges compete on logistics and working capital efficiency.
Product Type:
REACH authorization and EPA emissions rules under the US Inflation Reduction Act create divergent compliance burdens across product formats, with thin-gauge coil facing stricter scope-three disclosure requirements than thick plate.
- Plates:Cast and rolled slabs exceeding 6 mm thickness deliver structural integrity for aerospace wing ribs, marine hull sections, and heavy equipment frames. Demand concentrates in German and French aerospace clusters where DNV and EASA certification timelines extend procurement cycles. The EU Green Deal's carbon border adjustments favor Norwegian hydropower-based primary input for these high-specification grades.
- Sheets:Hot-rolled and cold-finished flat products spanning 0.2-6 mm enable automotive body-in-white stampings, construction cladding, and appliance enclosures. Chinese EV manufacturers in Shenzhen and Hefei are reshaping order books as localized supply chains displace imported coil. MIIT dual carbon targets accelerate scrap-based production for this segment.
- Foils:Cold-rolled stock below 0.2 mm serves barrier packaging and battery separator substrates where surface cleanliness and pinhole control carry premium pricing.
- Strips:Narrow-width coil formats feed continuous processing lines for heat exchanger fins and transformer windings with tight dimensional tolerances.
Sheets handle the majority of throughput; plates are climbing the fastest on share as aerospace order backlogs rebuild and defense procurement accelerates.
End User:
Customer procurement power varies sharply across end-use categories, with automotive OEMs demanding integrated recycling services while construction specifiers prioritize inventory availability over technical partnership.
- Aerospace:Airframe manufacturers and tier-one aerostructures suppliers specify 2xxx and 7xxx series alloys with lot-traceable mechanical properties and NDT certification. Boeing and Airbus qualification cycles lock suppliers into decade-long supply agreements with penalty clauses for specification deviations.
- Automotive OEMs:Dedicated EV architectures from BYD, Tesla, and Volkswagen consume medium-gauge 5xxx and 6xxx series coil for battery enclosures and body-side stampings where crashworthiness ratings determine platform adoption.
- Construction:Building envelope contractors source painted and anodized coil for curtain wall and roofing applications where regional fire codes and wind load standards create specification fragmentation.
- Packaging:Beverage can makers and flexible packaging converters run high-speed forming lines that prioritize gauge consistency and lacquer adhesion over alloy sophistication.
Automotive OEMs command the deepest supplier relationships; aerospace is gaining share fastest as production rates recover and narrow-body backlog extends.
Thickness:
Capital equipment intensity and rolling mill configuration determine competitive positioning by gauge, with thin-gauge specialists operating continuous casters that displace conventional hot rolling investment.
- Thin:Sub-1 mm gauges serve electronics chassis, food packaging, and HVAC components where surface quality and dimensional precision outweigh strength requirements. Japanese and South Korean appliance manufacturers in Osaka and Gwangju specify these grades with tight camber tolerances.
- Medium:1-6 mm coil dominates automotive structural applications and general fabrication where formability and weldability balance cost. German and US Midwest stamping plants consume this gauge range at volumes that determine rolling mill campaign planning.
- Heavy:6-25 mm plate supports mold tooling, pressure vessels, and transportation equipment where through-thickness properties and ultrasonic test certification create supplier stickiness.
- Ultra-Heavy:Gauges exceeding 25 mm serve nuclear containment, offshore platform, and defense armor applications with alloy development programs funded by national procurement agencies.
Medium gauge handles the majority of throughput; ultra-heavy is expanding most quickly as energy security investments accelerate pressure vessel and naval construction.
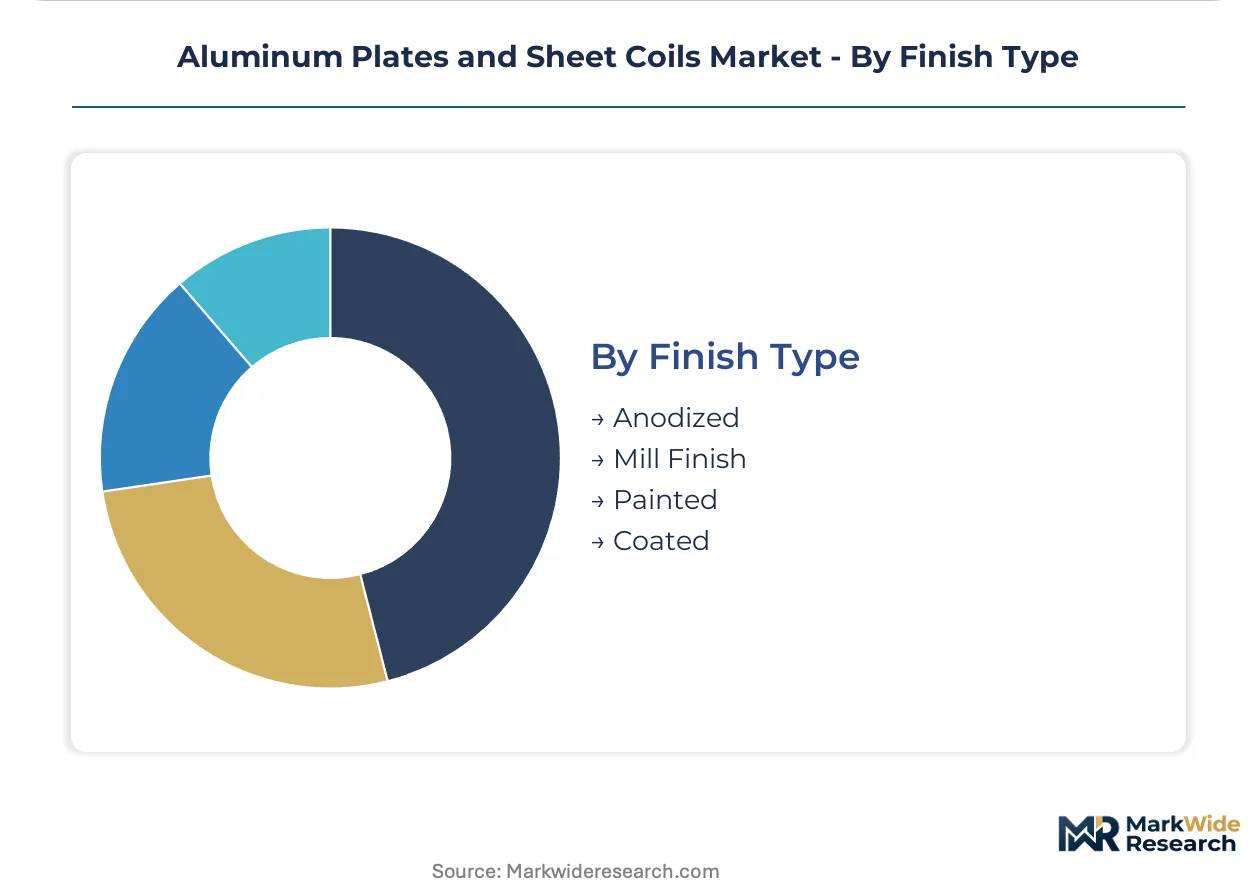
Finish Type:
Surface treatment creates the final pricing tier where application-specific certification and aesthetic specification separate premium suppliers from commodity rollers.
- Anodized:Electrochemical surface conversion builds wear-resistant oxide layers for architectural facades, consumer electronics, and medical equipment where color consistency and corrosion resistance carry specification weight. Munich and Milan building codes increasingly mandate anodized cladding for public structures.
- Mill Finish:As-rolled surfaces without secondary treatment serve industrial fabrication and subsequent coating operations where downstream processors control final appearance. This segment competes primarily on logistics reliability and inventory positioning.
- Painted:Coil-coated products with PVDF or polyester systems deliver color-matched building envelopes and appliance panels where warranty terms and chalking resistance determine supplier selection.
- Coated:Lubricant, conversion coating, or laminated film applications enable subsequent forming operations and temporary corrosion protection for automotive and electronics supply chains.
Mill finish handles the majority of throughput; anodized is gaining share fastest as green building certification programs expand architectural specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon targets and GB standards are reshaping production economics in China, while EU Green Deal CBAM mechanisms redirect European procurement toward verified low-carbon supply chains. Rolling mill capacity expansions in India and Southeast Asia are attempting to capture demand from localized EV manufacturing clusters.
China
Shenzhen and Hefei EV manufacturers are consuming medium-gauge coil at volumes that reshape rolling mill order books. MIIT dual carbon targets and GB standards for building materials accelerate scrap-based production while constraining new smelter approvals. Domestic fabricators in the Yangtze River Delta are scaling closed-loop recycling to serve BYD and Tesla supplier parks.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify certified low-carbon aluminum for body-in-white stampings as crashworthiness standards tighten. EU Green Deal CBAM redirects procurement toward Norwegian hydropower-based primary metal. The Stuttgart industrial cluster hosts qualification programs for new alloy grades serving dedicated EV architectures.
United States
Michigan stamping plants consume medium-gauge coil for battery enclosures and structural components at volumes determining rolling mill campaign planning. EPA emissions rules under the Inflation Reduction Act steer automotive buyers toward verified low-carbon North American supply. The Midwest industrial corridor faces technician shortages that delay announced capacity expansions.
India
Localized aluminum sheet production for two-wheeler and passenger EV platforms remains underdeveloped relative to projected demand curves. BIS standards and PLI scheme incentives are accelerating domestic rolling mill investments. Gujarat and Maharashtra industrial zones are attracting backward-integrated producers seeking captive alumina refining and power supply.
Norway
Hydropower-based primary smelting delivers certified low-carbon metal that commands premium positioning in European automotive and aerospace supply chains. EEA alignment with EU Green Deal CBAM mechanisms preserves market access for Norwegian exports. The Sunndal and Årdal production clusters supply German and French OEMs with scope-three-compliant material.
Aluminum Plates and Sheet Coils Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that competes on alloy specification and regional logistics. The market structure reflects concentration among backward-integrated producers with captive smelting and recycling assets, alongside independent rollers dependent on spot metal purchases. Two strategic archetypes dominate: hydropower-based low-carbon primary specialists and scrap-integrated rolling mill operators with closed-loop customer returns. Competitive moves center on automotive qualification timelines and carbon certification investments rather than price-based volume capture.
Among integrated multinationals, Novelis exemplifies the scrap-recycling archetype through captive stream utilization, while Norsk Hydro occupies a position anchored to Norwegian hydropower-based primary output. Hindalco Industries represents the emerging-market integrated model with backward control over alumina and power inputs. These three entities illustrate how geographic resource endowments and recycling infrastructure differentiate positioning amid volatile LME pricing environments.
| Leading Market Players |
|---|
| Novelis |
| Arconic |
| Constellium |
| Hindalco Industries |
| Alcoa Corporation |
| Norsk Hydro |
| China Hongqiao Group |
| UACJ Corporation |
| Aluminum Corporation of China (Chinalco) |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal CBAM certification gates both supply qualification and price differentiation simultaneously, separating Norwegian hydropower-based metal from Chinese and Gulf-origin imports through carbon intensity verification that commands measurable premiums in German and French automotive procurement.
Pricing Analysis
Geographic price spreads between Norwegian hydropower-based primary metal and Chinese coal-powered output exceed the cost of carbon border adjustments, creating arbitrage windows for certified low-carbon supply. Three-tier pricing structure across premium certified-low-carbon, standard domestic-European, and economy imported-Chinese grades dominates contract structures. Pricing pressure stems from LME volatility feeding through spot metal purchases for non-integrated rollers. Construction specifiers exhibit highest price sensitivity; aerospace and automotive OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Just-in-time coil delivery dominates automotive stamping plants in Michigan and Bavaria, while strategic stockpiling of primary ingot persists among Chinese state-backed smelters managing MIIT dual carbon compliance timelines. Supply concentrates in China, Norway, and Russia for primary metal; Germany, the United States, and Japan for rolling mill capacity. Raw material flows draw from bauxite mining in Guinea and Australia, alumina refining in China and India, and scrap collection networks across Europe and North America. Single-source vulnerability from Chinese state-backed smelter concentration creates geopolitical risk for Western fabricators. Distribution runs through mill-direct contracts for automotive OEMs and distributor networks for construction and general fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform scaling constitutes a high-growth disruption as dedicated architectures from BYD and Volkswagen consume medium-gauge coil volumes that reshape rolling mill economics and force qualification timeline compression.
For Market Incumbents: Secure automotive qualification pipelines by accelerating alloy development programs for battery enclosure crashworthiness standards. Lock in closed-loop recycling contracts with OEM stamping plants to defend margin stability against LME volatility. Prioritize technician training partnerships with German and US Midwest technical institutes to staff announced capacity expansions.
For New Entrants and Emerging Players: Lead with India domestic EV supply chain localization where BIS standards and PLI scheme incentives create favorable entry conditions. Target two-wheeler and passenger EV platform aluminum sheet production in Gujarat and Maharashtra industrial zones. Build backward integration into captive alumina refining and power supply to compete with Hindalco's cost structure.
For Investors and Strategic Acquirers: EU Green Deal CBAM implementation reshapes the acquisition landscape by privileging assets with verified low-carbon primary metal or scrap-integrated rolling capacity. Long-term viability favors producers with hydropower-based smelting or closed-loop recycling infrastructure over spot-metal-dependent rollers. Monitor scope-three emissions disclosure mandates from German and French OEMs as the signal to watch for contract eligibility inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Alloy Qualification Acceleration | Compresses 18-36 month OEM certification cycles to capture EV platform ramp timing. |
| Closed-Loop Recycling Integration | Enables Novelis-style margin stability through captive scrap streams and direct OEM returns. |
| Low-Carbon Primary Certification Investment | Positions Norsk Hydro-style Norwegian hydropower output for EU CBAM premium capture. |
| India Rolling Mill Capacity Buildout | Captures underdeveloped domestic EV sheet demand in Gujarat and Maharashtra zones. |
| Technician Training Pipeline Development | Addresses Germany and US Midwest operator scarcity delaying expansion timelines. |
Study Parameters
The analysis maps flat-rolled aluminum product categories, each validated through rolling mill operations directors, automotive OEM platform engineers, and construction procurement managers. Primary interviews with tier-one fabricator supply chain heads and secondary validation through LME price databases, customs trade flows, and MIIT policy filings anchor the assessment. Bottom-up demand modeling across EV battery enclosure, aerospace wing rib, and building cladding applications triangulates with top-down smelter capacity and rolling mill output benchmarks.
Consistency checks against external trade data and producer output disclosures validate volume and value outputs across the projection horizon. Segmentation dimensions include product type, end-use industry, thickness gauge, and surface finish specification. CAGRs derive from rolling mill order book analysis and OEM platform production schedules. Forecast inputs incorporate MIIT dual carbon target implementation pace and EU CBAM carbon border adjustment mechanisms.
Forecasts assume regulatory continuity in EU Green Deal CBAM and MIIT dual carbon regimes; material policy shifts would require re-modeling of import competitiveness and domestic production incentives. Practitioners should keep alternative scenarios live as automotive OEM scope-three disclosure requirements and Chinese smelter approval constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Welding Market
Metals
Crude Steel Market
Metals
Finished Steel Products Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Nickel Powder Plating Market
Metals
High Purity Lead Market
Metals
High Purity Boron Market
Metals
Colloidal Metal Particles Market
Metals
Iron Ore Market
Metals
Neodymium Market
Metals
Tantalum and Niobium Material Market
Metals
Aluminum Welding Wires Market
Metals
Global Duplex Stainless Steel Market
Metals
Beryllium Market
Metals
North America and Europe Metal Powder Market
Metals
Stainless Steel 400 Series Market