
 Global Synthetic Diamond Market | 2026-2036
Global Synthetic Diamond Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic Diamond Market Outlook
The EU Green Deal is expanding the addressable market for low-carbon synthetic diamonds by tightening embodied-carbon thresholds on imported industrial materials. De Beers Group (Element Six) leverages its integrated CVD growth facilities to supply defense-qualified thermal management substrates. Zhongnan Diamond Co., Ltd. anchors global HPHT grit production through captive graphite supply and furnace scale. Diamond Foundry differentiates via renewable-energy-powered growth chambers serving North American jewelry designers.
Synthetic diamonds are crystalline carbon structures engineered through high-pressure high-temperature (HPHT) or chemical vapor deposition (CVD) processes, typically achieving Mohs hardness of 10 and thermal conductivity exceeding copper. HPHT diamonds dominate abrasive and cutting-tool applications where fracture toughness governs tool life, while CVD diamond plates capture expanding share in semiconductor heat spreaders and optical windows due to purity control at the parts-per-billion level. Quantum computing represents an emerging application vector where nitrogen-vacancy centers in synthetic diamond enable room-temperature qubit operation.
The EPA regulates synthetic diamond manufacturing emissions under Clean Air Act Title V permitting, while China's MEE enforces GB standards on industrial carbon feedstock sourcing. ISO 18323 and FTC Jewelry Guides jointly constrain marketing claims, forcing verifiable provenance documentation across distribution channels. Stakeholders must track evolving conflict-mineral disclosure rules and quantum-computing export-control lists to anticipate demand inflections and qualification barriers.
Market Dynamics
Semiconductor fabricators are embedding synthetic diamond substrates in power electronics at accelerating rates, compressing thermal management supply chains and redirecting capital from legacy ceramic solutions toward CVD growth capacity.
Growth Catalysts
- EU Green Deal embodied-carbon thresholds:Import restrictions on high-carbon industrial materials are redirecting procurement toward low-carbon HPHT and CVD production pathways certified under REACH compliance frameworks.
- Quantum computing nitrogen-vacancy centers:Synthetic diamond enables room-temperature qubit operation, pulling defense and research funding into precision growth infrastructure for ultra-pure substrates.
- Henan province HPHT cluster concentration:Captive graphite supply and scaled furnace operations in central China anchor global abrasive-grade grit production, compressing unit economics for cutting-tool applications.
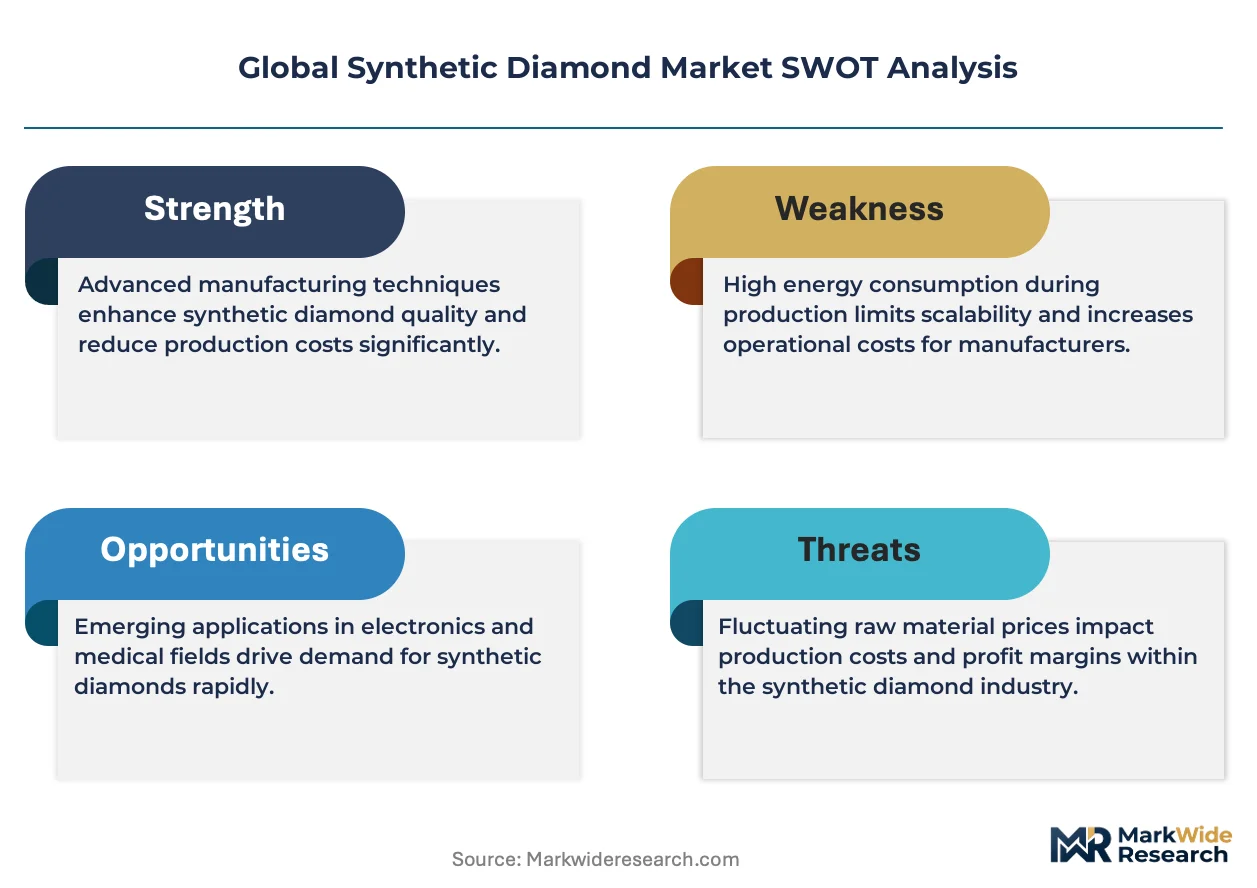
Market Restraints
- Energy input cost volatility:HPHT synthesis requires sustained electrical loads exceeding 1,500°C furnace operation, exposing producers to grid pricing fluctuations and carbon-offset liability.
- Feedstock concentration in synthetic graphite:High-purity carbon precursor supply concentrates among Chinese electrode manufacturers, creating single-source vulnerability for non-integrated growers.
- CVD deposition rate limitations:Growth rates below 10 microns per hour constrain wafer-scale production economics, limiting penetration beyond niche thermal management and optical applications.
Strategic Opportunities
- India jewelry manufacturing expansion:Surat cutting and polishing clusters are integrating CVD rough supply to bypass traditional mined-diamond import dependencies, creating captive downstream demand.
- Defense-qualified thermal substrate qualification:NATO member nations are establishing domestic CVD growth capacity to secure heat-spreader supply chains for radar and electronic warfare systems.
- Renewable-energy-powered growth chambers:Hydroelectric and geothermal-powered facilities in Iceland and the Pacific Northwest are capturing premium pricing for zero-carbon provenance documentation.
Industry Challenges
- Parts-per-billion purity certification timelines:Semiconductor substrate qualification requires 18-24 month validation cycles against SEMI standards, locking working capital in inventory before revenue recognition.
- Cross-border dual-use export controls:Quantum-grade synthetic diamond faces emerging restrictions under Wassenaar Arrangement classifications, complicating international shipment of nitrogen-vacancy center substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic Diamond Market |
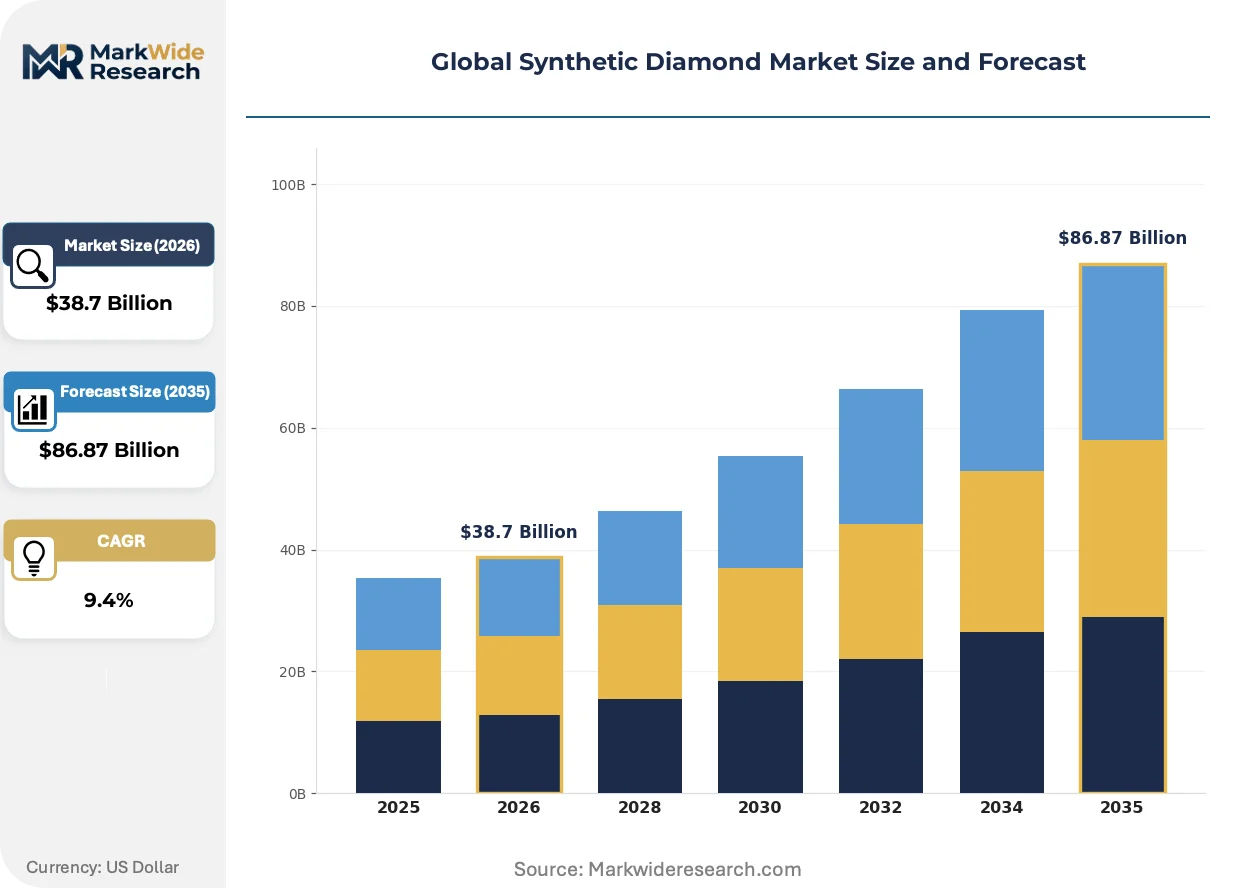
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CVD Diamonds, HPHT Diamonds, Polycrystalline Diamonds, Nanodiamonds Application: Cutting Tools, Thermal Management, Optical Components, Electronics Manufacturing, Quantum Computing End User: Tool Manufacturers, Semiconductor Fabricators, Jewelry Designers, Research Institutes, Defense Contractors Distribution Channel: Direct Sales, Online Marketplaces, Authorized Dealers, Industrial Suppliers, Specialty Retailers |
| Companies Covered | Sumitomo Electric Industries, Ltd., Hyperion Materials & Technologies, De Beers Group (Element Six), Diamond Foundry, Orbray Co., Ltd., Zhongnan Diamond Co., Ltd., Zhengzhou Sino-Crystal Diamond Co., Ltd., Diamond Elements Pvt. Ltd., Henan Huanghe Whirlwind Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic Diamond Market Strategic Shifts
Production technology diffusion is fragmenting geographic concentration while regulatory frameworks restructure competitive qualification requirements across end-use verticals.
Chemical vapor deposition is decentralizing thermal management substrate supply away from incumbent ceramic and metal-matrix composite suppliers. Data-center operators and electric-vehicle inverter manufacturers are qualifying CVD diamond heat spreaders for 800V architectures and high-density compute racks. This technology shift is compressing incumbent supply chains while enabling new entrants with renewable-powered growth facilities to capture premium positioning.
REACH authorization requirements for industrial carbon feedstock sourcing are tightening traceability documentation across EU import channels. Manufacturers must now certify graphite precursor provenance and processing energy intensity to maintain market access. CVD producers with integrated renewable power and closed-loop gas recycling are securing preferential procurement status from German and French automotive Tier-1 suppliers.
Direct long-term contracting between synthetic diamond growers and end-use fabricators is displacing spot-market rough trading in semiconductor-grade segments. Wafer manufacturers in Japan and South Korea are signing 3-5 year offtake agreements specifying purity thresholds and volume ramps. This contracting pattern concentrates volume with qualified suppliers while marginalizing traders and secondary polishers in high-specification categories.
Global Synthetic Diamond Market Segmentation
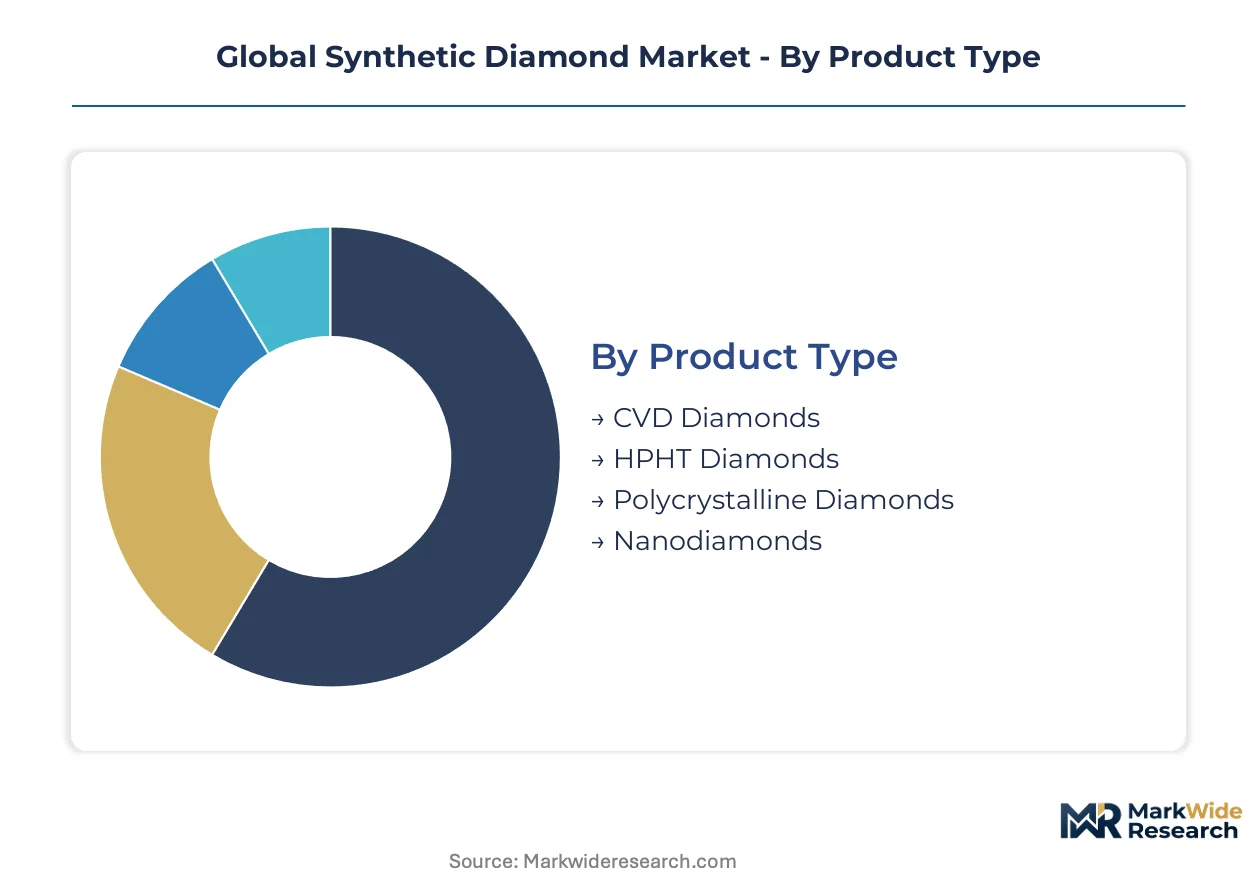
Synthetic diamond producers face divergent qualification hurdles across product grades and end-use specifications. Segmentation reveals where capital concentrates versus where margins compress under technological and regulatory pressure.
Product Type:
HPHT volumes dominate abrasive applications while CVD commands semiconductor-grade premiums.
- HPHT Diamonds:High-pressure high-temperature synthesis produces grit and single-crystal stones with controlled nitrogen content for cutting-tool durability. Demand concentrates in Henan province furnace clusters serving Chinese and Indian tool manufacturers facing REACH embodied-carbon documentation requirements.
- CVD Diamonds:Chemical vapor deposition grows ultra-pure plates with parts-per-billion impurity levels for thermal spreaders and optical windows. Semiconductor fabricators in Japan and South Korea are locking in multi-year offtake agreements for 800V power electronics substrates.
- Polycrystalline Diamonds:Sintered diamond aggregates bonded to tungsten carbide substrates deliver fracture resistance for oil and gas drilling inserts.
- Nanodiamonds:Detonation-synthesized particles below 10 nanometers enable drug delivery vectors and polishing slurries for silicon wafer planarization.
Today's leader: HPHT Diamonds. Tomorrow's challenger: CVD Diamonds.
Application:
Industrial abrasion generates volume while quantum and thermal applications capture speculative premium positioning.
- Thermal Management:CVD diamond heat spreaders achieve thermal conductivity exceeding 2,000 W/mK for gallium nitride power amplifiers and data-center processors. Electric-vehicle inverter manufacturers in Germany are qualifying diamond substrates for 800V architectures under automotive reliability standards.
- Quantum Computing:Nitrogen-vacancy centers in synthetic diamond enable room-temperature qubit operation, pulling defense research funding from DARPA and EU Quantum Flagship programs into precision growth infrastructure.
- Cutting Tools:Polycrystalline diamond inserts dominate non-ferrous machining and stone quarrying operations across Brazilian and Indian mining corridors.
- Optical Components:Diamond windows transmit from ultraviolet through far-infrared for high-power laser systems and spectroscopy instruments.
- Electronics Manufacturing:Diamond-coated electrodes and thermal interfaces serve RF device packaging and high-frequency radar modules.
Cutting Tools anchor current revenue. Quantum Computing offers the steepest expansion trajectory if export-control barriers resolve.
End User:
Semiconductor fabricators impose the longest qualification cycles while jewelry channels drive spot-price volatility.
- Semiconductor Fabricators:Wafer manufacturers in Taiwan and South Korea enforce 18-24 month SEMI validation protocols for substrate purity, locking working capital before revenue recognition.
- Defense Contractors:NATO member nations are establishing domestic CVD capacity to secure heat-spreader supply chains for electronic warfare systems under Wassenaar Arrangement compliance.
- Tool Manufacturers:Cutting-tool producers in Germany and Japan source HPHT grit for indexable inserts and wire-drawing dies.
- Jewelry Designers:North American and European brands are certifying renewable-energy-grown stones for zero-carbon provenance marketing.
- Research Institutes:National laboratories in Switzerland and Australia procure nitrogen-vacancy substrates for quantum sensing and magnetometry experiments.
Semiconductor Fabricators set the purity benchmark. Defense Contractors are forcing geographic capacity redistribution.
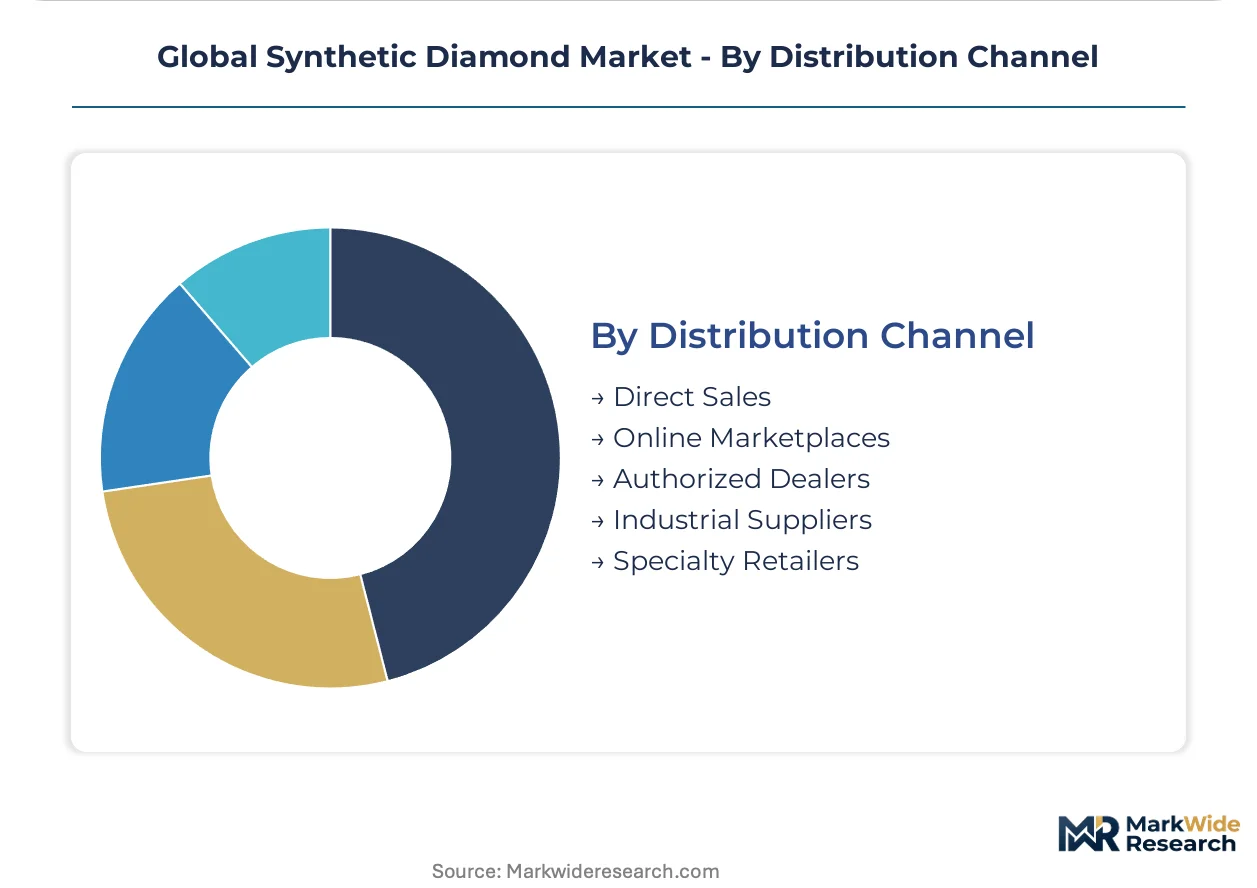
Distribution Channel:
Direct contracting displaces spot trading in high-specification grades while industrial suppliers handle commoditized grit.
- Direct Sales:Long-term offtake agreements between growers and end-use fabricators specify purity thresholds, volume ramps, and exclusivity clauses for semiconductor-grade supply.
- Industrial Suppliers:Distributors aggregate HPHT abrasive grit from Chinese producers for tool manufacturers seeking just-in-time inventory management.
- Online Marketplaces:Digital platforms connect jewelry designers with certified growers for custom-cut stones with blockchain traceability documentation.
- Authorized Dealers:Regional representatives manage technical qualification support for optical and thermal management substrate sales.
- Specialty Retailers:Gemological laboratories and boutique jewelers serve consumer markets with grading reports and provenance verification.
Direct Sales commands the premium tier. Industrial Suppliers handle volume flows with compressed margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
General Electric pioneered synthetic diamond production in the 1950s, scaling HPHT technology for industrial abrasives before Asian manufacturers built furnace clusters that now dominate global grit supply. Production geography has since fragmented across renewable-powered CVD facilities, defense-qualified substrate foundries, and jewelry-grade growth chambers.
China
Henan province hosts the world's densest concentration of HPHT furnace operations, with Zhengzhou-area producers supplying abrasive-grade grit to Indian tool manufacturers. China's MEE enforces GB standards on industrial carbon feedstock sourcing, tightening traceability documentation for export channels. The Zhengzhou National Superhard Materials Industrial Base anchors captive graphite supply chains that compress unit economics for cutting-tool applications.
United States
Defense contractors in California and Massachusetts are qualifying domestic CVD substrates for radar and electronic warfare thermal management under DARPA-funded programs. The EPA regulates manufacturing emissions through Clean Air Act Title V permitting, adding compliance overhead for growth facilities. Diamond Foundry operates renewable-energy-powered growth chambers in the Pacific Northwest, supplying North American jewelry designers with zero-carbon provenance documentation.
Japan
Wafer manufacturers in Tokyo and Osaka enforce 18-24 month SEMI validation protocols for semiconductor-grade diamond substrates, locking working capital before revenue recognition. METI coordinates quantum-computing research funding that pulls precision growth infrastructure development. The Chubu region around Nagoya concentrates optical component fabricators qualifying diamond windows for high-power laser systems.
Germany
Automotive Tier-1 suppliers in Bavaria and Baden-Württemberg are certifying CVD diamond heat spreaders for 800V electric-vehicle inverter architectures. REACH authorization requirements tighten traceability documentation across EU import channels, favoring producers with integrated renewable power. Stuttgart-area engineering clusters coordinate thermal management substrate qualification with semiconductor fabricators in Dresden.
India
Surat's cutting and polishing clusters are integrating CVD rough supply to bypass traditional mined-diamond import dependencies, creating captive downstream demand. The country's national gem and jewelry regulator enforces hallmarking standards that synthetic producers must navigate for domestic market access. Gujarat's diamond processing corridor now hosts technical facilities qualifying lab-grown stones for export to North American and European jewelry channels.
Global Synthetic Diamond Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent qualification requirements. HPHT furnace operators in central China anchor abrasive-grade supply through scaled graphite integration, while CVD specialists in North America and Europe capture semiconductor-grade premiums through purity certification. The market structures around three archetypes: integrated materials conglomerates with captive growth capacity, pure-play synthetic diamond specialists, and diversified hard-materials suppliers extending into superabrasives. Dominant competitive moves include multi-year offtake contracting with semiconductor fabricators and geographic capacity expansion to satisfy defense-qualified thermal substrate demand.
Within the integrated conglomerate tier, Sumitomo Electric Industries, Ltd. and De Beers Group (Element Six) exemplify backward integration into precision growth infrastructure. Among Chinese furnace operators, Zhongnan Diamond Co., Ltd. and Henan Huanghe Whirlwind Co., Ltd. occupy positions anchored to Henan province's graphite supply chains. At the specialist end, Diamond Foundry represents the renewable-energy-powered growth chamber archetype serving provenance-sensitive jewelry channels.
| Leading Market Players |
|---|
| Sumitomo Electric Industries, Ltd. |
| Hyperion Materials & Technologies |
| De Beers Group (Element Six) |
| Diamond Foundry |
| Orbray Co., Ltd. |
| Zhongnan Diamond Co., Ltd. |
| Zhengzhou Sino-Crystal Diamond Co., Ltd. |
| Diamond Elements Pvt. Ltd. |
| Henan Huanghe Whirlwind Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Graphite electrode price indices cascading from Chinese furnace clusters compress HPHT abrasive-grade margins while amplifying premiums for CVD semiconductor substrates. REACH-compliant feedstock documentation adds certification-layer costs that stratify pricing tiers across EU import channels.
Pricing Analysis
Long-term offtake contracting dominates semiconductor-grade segments, separating multi-year volume commitments from spot-market rough trading. Price differentiation rests on SEMI purity certification and renewable-energy provenance documentation. Cost compression in abrasive-grade HPHT grit intensifies because Henan furnace operators compete on unit economics for Indian tool manufacturers. Jewelry designers prove least price-sensitive, absorbing premiums for blockchain-traceable, zero-carbon stones.
Supply Chain Analysis
Direct-to-fabricator channels handle semiconductor substrate demand, while industrial suppliers aggregate HPHT grit for just-in-time tool manufacturing. Supply concentrates in China, the United States, and Germany. Raw material dependencies include high-purity synthetic graphite, methane feedstock for CVD reactors, and tungsten carbide substrates for polycrystalline bonding. Single-source vulnerability in Chinese electrode manufacturers exposes non-integrated growers to feedstock disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Green Deal carbon-border adjustments impose cost premiums on imported materials that renewable-powered Nordic and Pacific Northwest facilities avoid.
For Market Incumbents: Deploy multi-year offtake contracting to lock semiconductor fabricators into exclusivity clauses before Japanese and South Korean wafer manufacturers qualify alternative suppliers. Deepen backward integration into captive graphite processing to neutralize Henan feedstock concentration risk. CVD deposition rate limitations threaten margin expansion unless R&D investment accelerates wafer-scale economics. For New Entrants and Emerging Players: Launch via renewable-energy-powered growth chambers serving provenance-sensitive jewelry channels in North America and Europe. Defense-qualified thermal substrate demand in NATO member nations offers penetrable white space with qualification barriers that filter out commodity competitors. Direct digital marketplace access bypasses incumbent distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with CVD specialists possessing SEMI-validated purity infrastructure and renewable power integration. Long-term viability over the coming decade hinges on quantum-computing nitrogen-vacancy center demand materializing beyond research procurement. Watch Wassenaar Arrangement export-control amendments as inflection signals for defense-grade substrate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Feedstock | Henan province furnace operators secure captive supply chains against electrode price volatility. |
| SEMI Purity Certification Investment | Japanese wafer manufacturers enforce 18-24 month validation protocols that filter unqualified suppliers. |
| Renewable Energy Growth Chamber Deployment | Icelandic and Pacific Northwest facilities capture EU Green Deal premium pricing for zero-carbon provenance. |
| Defense Substrate Qualification Program | NATO electronic warfare thermal management requirements redistribute geographic capacity toward domestic suppliers. |
| Direct Long-term Offtake Contracting | German automotive Tier-1 suppliers lock volume commitments specifying 800V inverter architecture thresholds. |
Study Parameters
Multiple input streams — primary interviews with HPHT furnace operators, CVD growth specialists, semiconductor procurement officers, and jewelry channel distributors — were reconciled against secondary validation from SEC filings, customs trade databases, and SEMI standards documentation. Bottom-up capacity modeling across Henan province clusters and top-down demand segmentation from wafer manufacturers were triangulated to constrain volume estimates.
Historical capacity expansion patterns were cross-referenced against panel input from equipment suppliers and graphite precursor distributors across the analysis window. Segmentation dimensions modeled include synthesis method, purity grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from installed growth chamber capacity ramps and qualification timeline compression in semiconductor substrate segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Wassenaar Arrangement export-control expansion or breakthrough CVD deposition rate improvements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Silver Nanowires Market
Advanced Materials
Graphite Materials Market
Advanced Materials
Global High Performance Thermoplastics Market
Advanced Materials
Borophene Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
2D Materials Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Flexible Bio-Foams Market