
 Polyurethane Powder Coatings Market | 2026-2036
Polyurethane Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Powder Coatings Market Outlook
Skilled formulation chemist availability is collapsing across Western coating hubs, forcing manufacturers to relocate technical centers or automate batch development. Akzo Nobel N.V. leverages its European R&D footprint to sustain proprietary resin synthesis capabilities. PPG Industries Inc. anchors North American supply through captive distribution networks. BASF SE differentiates via backward integration into aliphatic isocyanate feedstocks.
Polyurethane powder coatings are thermosetting polymer systems comprising hydroxyl-functional polyester resins crosslinked with blocked isocyanate curing agents, typically applied via electrostatic spray at film builds of 50-120 microns to deliver mar resistance and UV durability on metal substrates. Thermosetting grades dominate volume owing to their superior chemical resistance and lower cure energy profiles versus thermoplastic alternatives. The automotive end-user segment leads value contribution, while the protective application category records the fastest expansion as infrastructure corrosion budgets tighten globally.
EPA NESHAP standards in the United States, REACH in Europe, and China's MEE emission controls collectively mandate VOC reduction timelines that directly accelerate solvent-based coating displacement. CE marking under the EU Construction Products Regulation further gates market access for building and construction applications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode margin pools.
Market Dynamics
Automotive OEMs in Germany and China are accelerating solvent-to-powder conversion under tightening VOC mandates, compressing formulation development cycles and reshaping resin procurement patterns across tiered supply bases.
Growth Catalysts
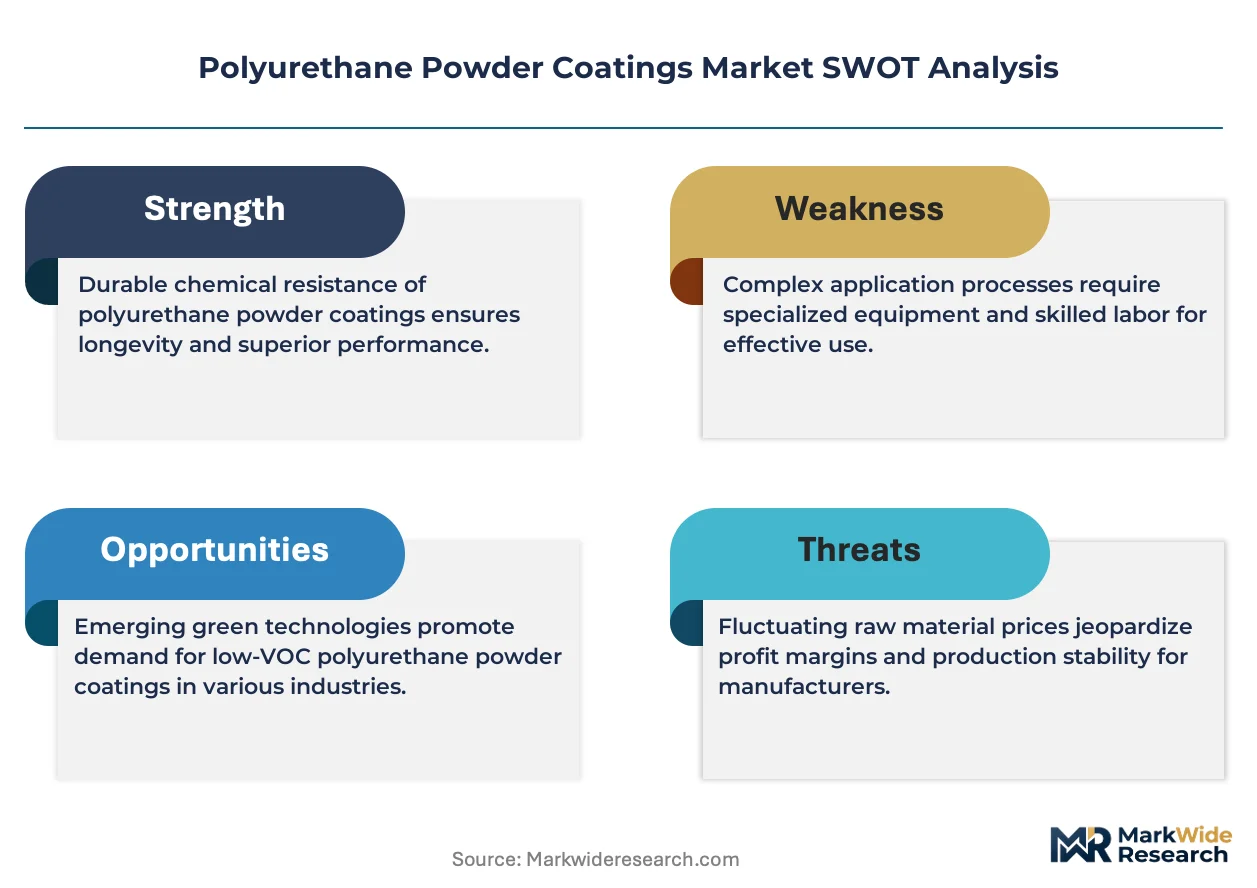
- REACH Phase-In Substances:ECHA's expanding restricted substance list forces coating reformulation across European manufacturing bases, directly benefiting zero-VOC polyurethane powder systems in appliance and furniture export clusters.
- Blocked Isocyanate Curing:Advances in low-temperature cure chemistry enable coating of heat-sensitive substrates, opening automotive interior and plastic component applications previously reserved for liquid systems.
- East China Industrial Corridor:Concentrated appliance and furniture manufacturing in Jiangsu and Zhejiang provinces drives bulk thermosetting grade procurement, creating demand density that justifies localized resin synthesis investments.
Market Restraints
- Aliphatic Isocyanate Concentration:Feedstock supply concentrates among specialized chemical producers in Germany and Japan, exposing formulators to input cost volatility and allocation risk during supply disruptions.
- Capital-Intensive Application Infrastructure:Electrostatic spray booths and recovery systems require significant upfront investment, limiting adoption among small-to-mid metal fabricators serving fragmented construction and agricultural equipment markets.
- Thermoplastic Substitution in Flexible Applications:TPU-based liquid coatings retain performance advantages on elastomeric substrates, constraining polyurethane powder penetration in sealing and gasket applications.
Strategic Opportunities
- India PLI Scheme for White Goods:Production-linked incentives for domestic appliance manufacturing create localized demand for durable exterior finishes, with import substitution mandates favoring regional coating suppliers.
- UV-Curable Hybrid Systems:Convergence of traditional thermal cure with UV-initiated polymerization enables dual-cure processing, reducing energy consumption and line footprint for high-throughput automotive suppliers.
- Protective Infrastructure Corrosion Budgets:Tightened maintenance spending on bridges, pipelines, and offshore structures elevates lifecycle cost analysis, positioning high-performance polyurethane powders against conventional epoxy alternatives.
Industry Challenges
- Formulation Chemist Scarcity:Western coating hubs face collapsing availability of skilled resin synthesis specialists, forcing manufacturers to automate batch development or relocate technical centers to Asia-Pacific education corridors.
- CE Marking Timeline Compression:EU Construction Products Regulation certification requirements for building and construction applications create extended approval cycles that delay market entry and consume R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Powder Coatings Market |
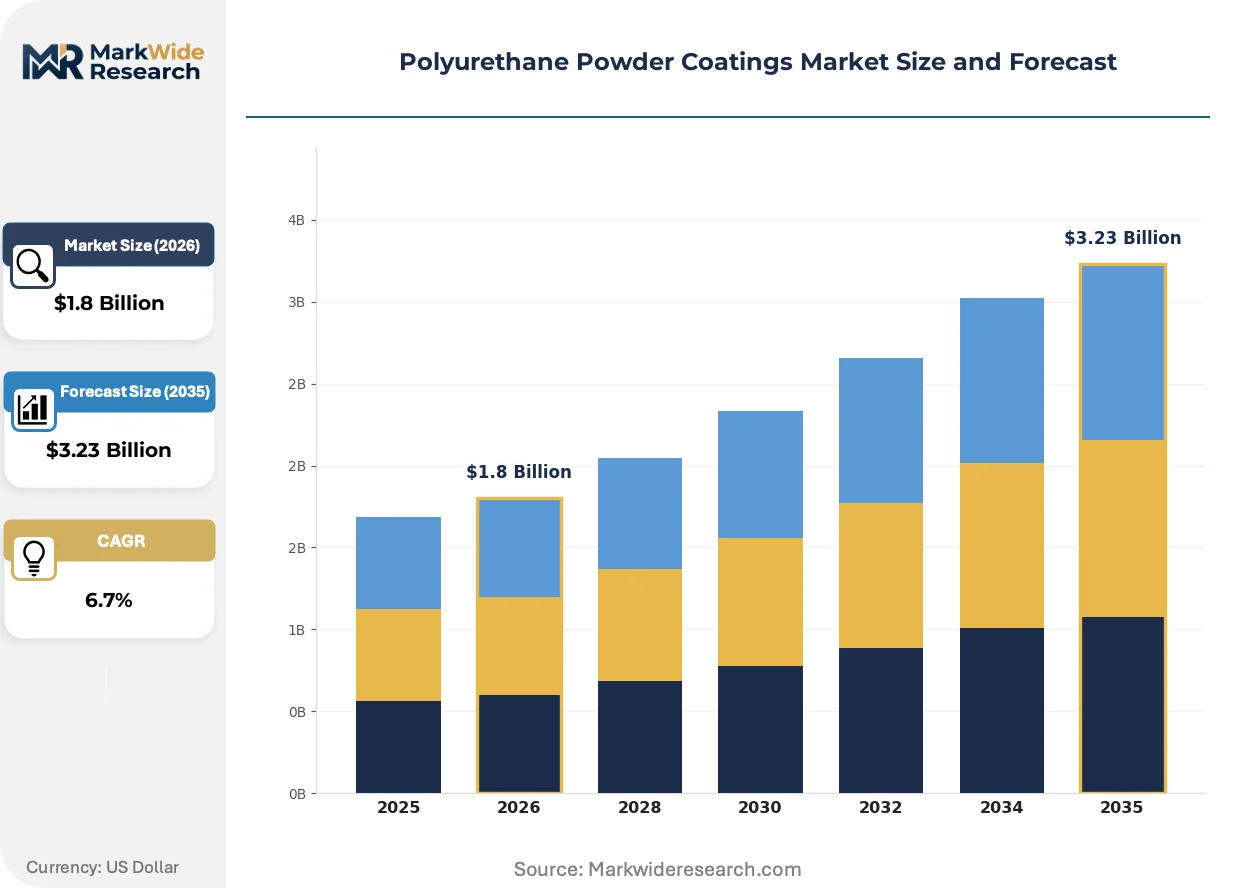
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting, Thermoplastic, Hybrid, Reactive End User: Automotive, Furniture, Appliances, Building & Construction Application: Industrial, Decorative, Protective, Electrical Distribution Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | Akzo Nobel N.V., Axalta Coating Systems, PPG Industries Inc., The Sherwin Williams Company, Jotun, BASF SE, The Dow Chemical Company, Kansai Paint Co., Ltd., Asian Paints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Powder Coatings Market Strategic Shifts
Low-temperature cure technologies and digital color-matching systems are compressing production lead times while regulatory alignment across major economies standardizes performance specifications for cross-border supply chains.
Superdurable polyester resin technology is fragmenting established market tiers by enabling thinner film builds with equivalent weathering performance. Tier-one automotive suppliers in Germany and China are adopting these grades for exterior trim components, reducing material consumption per unit while extending warranty coverage. The technology is fragmenting traditional volume-premium segmentation by placing high-performance characteristics within mid-tier pricing bands.
China's MEE emission controls and dual carbon goals are mandating VOC reduction timelines that accelerate solvent-based coating displacement across manufacturing bases. Industrial facilities in the Yangtze River Delta face stepped compliance deadlines that compress capital allocation decisions for application equipment upgrades. Appliance exporters targeting European markets are responding with preemptive powder line conversions to secure CE marking under the EU Construction Products Regulation.
Consolidated procurement by multinational automotive OEMs is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Tier-one coating buyers in Germany and China now specify outcome-based performance guarantees rather than input-based specifications, transferring formulation risk to resin suppliers. This pattern is most visible in exterior trim programs where single-source agreements cover multi-year platform lifecycles across geographically dispersed assembly plants.
Polyurethane Powder Coatings Market Segmentation
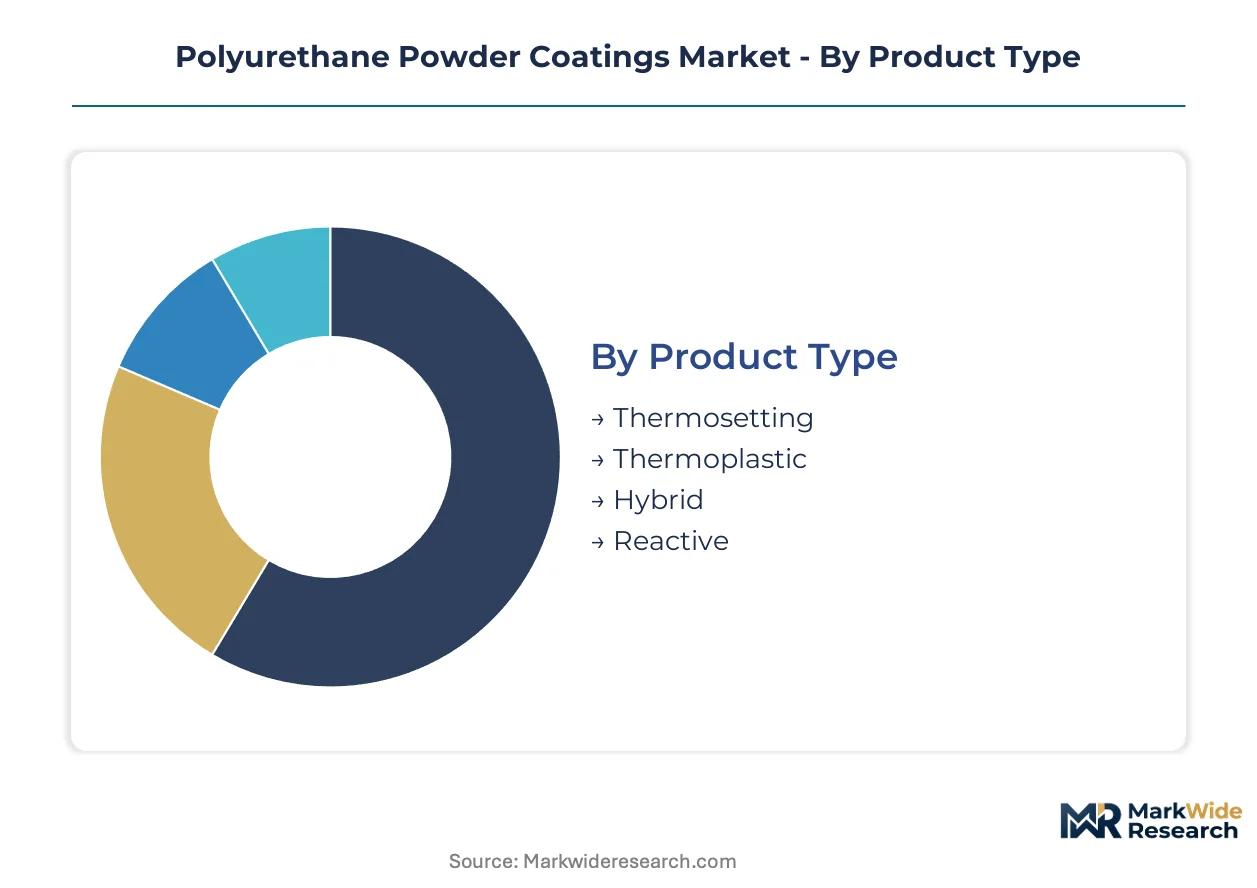
Segmentation in polyurethane powder coatings reveals how formulation chemistry, cure mechanisms, and substrate compatibility determine channel access and margin capture. Distinct product architectures serve divergent thermal budgets and durability requirements across automotive, appliance, and infrastructure end-uses.
Product Type:
Channel-mix patterns diverge sharply: thermosetting grades move through direct mill-to-plant contracts, while thermoplastic and hybrid systems rely more heavily on distributor networks for fragmented metal fabrication customers.
- Thermosetting:Hydroxyl-functional polyester resins crosslinked with blocked isocyanate curing agents deliver superior chemical resistance and lower cure energy profiles. Demand concentrates in East China's Jiangsu and Zhejiang provinces, where appliance and furniture export clusters drive bulk procurement under tightening MEE emission controls.
- Thermoplastic:Linear polyurethane chains without crosslinking enable re-melt and repair characteristics suited to flexible substrates. Automotive interior applications in Germany are adopting these grades for plastic component coating where low-temperature processing protects heat-sensitive base materials.
- Hybrid:Combines epoxy and polyurethane chemistries to balance cost and performance for general industrial metal finishing.
- Reactive:Two-component systems with separated resin and hardener for specialized high-performance applications requiring extended pot life.
By volume, thermosetting leads. By growth pace, hybrid formulations are climbing the fastest as mid-tier manufacturers seek REACH-compliant alternatives to solvent-based epoxies.
End User:
Cost-tier stratification separates specification-grade automotive programs from price-sensitive furniture coating, with appliance manufacturers occupying a mid-tier position demanding both durability and scale economics.
- Automotive:Exterior trim components require superdurable polyester technology with 50-120 micron film builds for mar resistance and UV durability. OEMs in Germany and China are compressing supplier qualification cycles and specifying outcome-based performance guarantees across multi-year platform lifecycles.
- Furniture:Metal office and residential furniture demands decorative finishes with moderate weathering performance. Export-oriented manufacturers in China's Yangtze River Delta are preemptively converting powder lines to secure CE marking under the EU Construction Products Regulation.
- Appliances:Washing machines, refrigerators, and air conditioning units require corrosion-resistant exterior finishes. India's PLI scheme for white goods is creating localized demand with import substitution mandates favoring regional coating suppliers.
- Building & Construction:Architectural metalwork and structural steel applications face extended CE marking approval cycles that delay market entry and consume R&D resources.
By volume, furniture leads. By margin expansion, automotive is gaining share fastest as tier-one suppliers unbundle technical service from material supply contracts.
Application:
Customer-type concentration shapes supply relationships: multinational OEMs consolidate procurement through direct mill contracts, while fragmented metal fabricators in construction and agriculture equipment rely on distributor stocking programs.
- Industrial:Heavy machinery, agricultural equipment, and material handling systems require abrasion-resistant finishes. Capital-intensive electrostatic spray infrastructure limits adoption among small-to-mid fabricators serving these fragmented markets.
- Decorative:Color-matched architectural and consumer product finishes demand precise batch consistency and rapid reformulation capability. Digital color-matching systems are compressing production lead times for specification-driven projects.
- Protective:Bridges, pipelines, and offshore structures face tightened maintenance budgets elevating lifecycle cost analysis. This segment is expanding most quickly as infrastructure corrosion spending redirects toward high-performance polyurethane powders against conventional epoxy alternatives.
- Electrical:Insulation and environmental protection for switchgear, transformers, and motor housings requires dielectric strength combined with thermal conductivity.
By volume, industrial leads. By growth pace, protective applications are climbing the fastest.
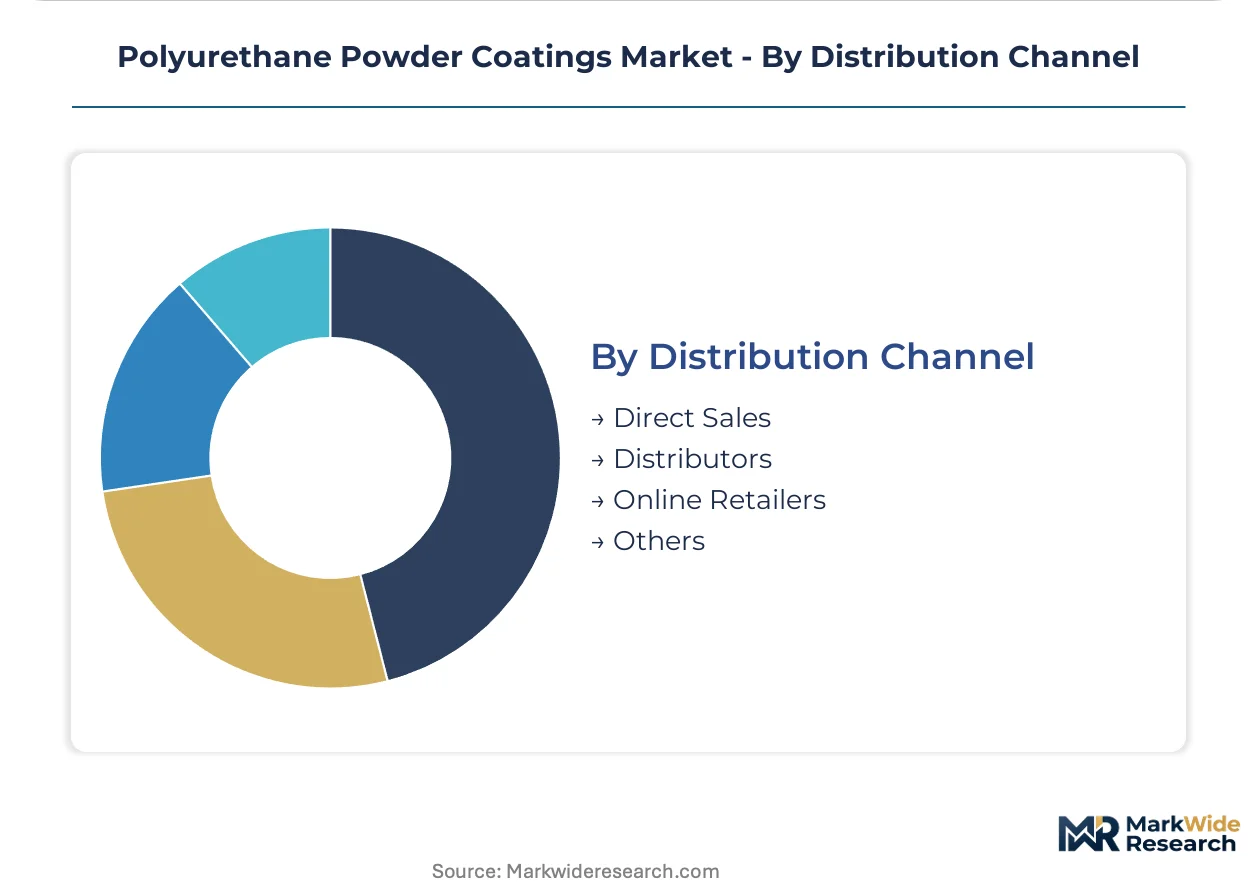
Distribution Channel:
Supply concentration in aliphatic isocyanate feedstocks—centering on specialized chemical producers in Germany and Japan—forces channel intermediaries to manage allocation risk and input cost volatility through forward stocking arrangements.
- Direct Sales:Mill-to-plant relationships dominate high-volume thermosetting procurement for automotive and appliance OEMs. These arrangements now specify outcome-based performance guarantees rather than input-based specifications, transferring formulation risk to resin suppliers.
- Distributors:Regional stocking points serve fragmented metal fabrication customers lacking capital for captive application infrastructure. Inventory carrying costs and technical service requirements compress margins in this channel.
- Online Retailers:Emerging channel for small-batch decorative and repair coatings, constrained by hazardous material shipping regulations and color-matching limitations.
- Others:Includes cooperative purchasing arrangements and specification house intermediaries for architectural projects.
By volume, direct sales leads. By channel expansion, distributors are gaining share fastest as mid-tier manufacturers seek localized technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Germany and China favor superdurable automotive exterior grades, while India's appliance sector drives mid-tier thermosetting procurement under localized production incentives.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify outcome-based performance guarantees for exterior trim programs. REACH Phase-In substance restrictions from ECHA force reformulation across coating supply bases. Stuttgart's tier-one supplier cluster compresses qualification cycles for multi-year platform contracts spanning dispersed assembly plants.
China
Appliance and furniture exporters in Jiangsu and Zhejiang provinces drive bulk thermosetting procurement. MEE emission controls and dual carbon goals mandate stepped VOC reduction timelines across Yangtze River Delta manufacturing bases. Shanghai's industrial corridor justifies localized resin synthesis investments through demand density from export-oriented metal finishing operations.
United States
Protective infrastructure applications on bridges and pipelines redirect corrosion budgets toward high-performance polyurethane powders. EPA NESHAP standards accelerate solvent-based coating displacement across heavy fabrication sectors. Gulf Coast petrochemical infrastructure and Midwest agricultural equipment manufacturing concentrate demand for abrasion-resistant industrial finishes.
India
The PLI scheme for white goods creates localized demand for durable appliance exterior finishes. Import substitution mandates under domestic manufacturing incentives favor regional coating suppliers over import-dependent formulators. Gujarat and Maharashtra industrial corridors attract capital for captive powder coating lines serving refrigerator and washing machine assembly operations.
Japan
Specialized aliphatic isocyanate production concentrates among feedstock suppliers serving precision coating formulators. METI industrial standards govern performance specifications for automotive and electrical insulation applications. Chubu region chemical manufacturing maintains captive supply relationships with domestic powder coating specialists.
Polyurethane Powder Coatings Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with concentration in aliphatic isocyanate feedstocks and proprietary resin synthesis capabilities determining margin capture. The upper tier commands direct mill-to-plant relationships with automotive OEMs, while mid-tier players compete through distributor networks for fragmented metal fabrication demand. Strategic archetypes include backward-integrated feedstock controllers, formulation specialists with captive R&D footprints, and regional distributors managing allocation risk through forward stocking. Dominant competitive moves center on automation of batch development to offset formulation chemist scarcity and geographic relocation of technical centers toward Asia-Pacific education corridors.
Among integrated chemical conglomerates, BASF SE exemplifies the backward-integrated archetype through captive aliphatic isocyanate production, while Akzo Nobel N.V. occupies a position within the European R&D-anchored specialist tier. PPG Industries Inc. represents the North American direct-sales model with mill-to-plant contract structures. These three entities illustrate how feedstock control, regional technical presence, and channel configuration stratify competitive positioning across automotive specification-grade and general industrial volume segments.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| PPG Industries Inc. |
| The Sherwin Williams Company |
| Jotun |
| BASF SE |
| The Dow Chemical Company |
| Kansai Paint Co., Ltd. |
| Asian Paints |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day resin synthesis lead times in Western coating hubs concentrate pricing power among aliphatic isocyanate suppliers in Germany and Japan, compressing margin pools for formulators lacking captive feedstock production or forward stocking arrangements with tier-one automotive OEMs.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational automotive OEMs and integrated resin suppliers, locking in volume commitments across multi-year platform lifecycles. Pricing stratifies across premium, standard, and economy tiers based on superdurable certification grade and geographic delivery cost to dispersed assembly plants. Cost compression in mid-tier furniture coatings is intensifying because REACH-compliant reformulation expenses transfer to formulators without corresponding price recovery mechanisms. Small-to-mid metal fabricators serving construction and agricultural equipment markets exhibit highest price sensitivity due to capital constraints on electrostatic spray infrastructure.
Supply Chain Analysis
Inventory carrying costs for aliphatic isocyanate feedstocks concentrate supply risk among specialized chemical producers in Germany, Japan, and select US Gulf Coast facilities. Formulation chemistry draws from blocked isocyanate curing agents, hydroxyl-functional polyester resins, and superdurable polyester resin technologies. Single-source vulnerability in aliphatic isocyanate production exposes formulators to allocation risk during supply disruptions. Distribution runs through direct mill-to-plant contracts for automotive and appliance OEMs, with regional distributors managing forward stocking for fragmented metal fabrication customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyurethane powder coating incumbents face substitution pressure from UV-curable liquid systems and TPU-based flexible coatings, requiring defensive positioning around low-temperature cure capabilities and regulatory compliance bundling.
For Market Incumbents: Shield formulation expertise through automation of batch development to offset collapsing skilled chemist availability across Western coating hubs. Deepen backward integration into aliphatic isocyanate feedstocks or secure captive supply agreements with German and Japanese producers to mitigate allocation risk during disruptions. Prioritize CE marking investment for building and construction applications to preempt extended approval cycle delays.
For New Entrants and Emerging Players: Technical service unbundling from material supply contracts creates white-space opportunity for regional distributors offering localized color-matching and rapid reformulation support to mid-tier appliance manufacturers in India's Gujarat and Maharashtra corridors. Target protective infrastructure applications on bridges and pipelines where lifecycle cost analysis elevates polyurethane powder positioning against epoxy alternatives. Pursue import substitution mandates under India's PLI scheme for white goods as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory tailwind play because REACH Phase-In substance restrictions and China's MEE emission controls structurally accelerate solvent-to-powder conversion regardless of macroeconomic cycles. Acquisition targets should display backward integration into aliphatic isocyanate feedstocks or proprietary low-temperature cure chemistry. Monitor stepped VOC compliance deadlines in the Yangtze River Delta as the signal for capital allocation acceleration among export-oriented manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive aliphatic isocyanate production insulates formulators from German and Japanese supplier allocation risk. |
| Low-Temperature Cure Development | Enables penetration of automotive interior plastic components previously reserved for liquid coating systems. |
| Regional Technical Center Relocation | Shifts R&D footprint toward Asia-Pacific education corridors to address Western formulation chemist scarcity. |
| CE Marking Pre-Certification | Accelerates market entry for building and construction applications under EU Construction Products Regulation. |
| Direct Mill-to-Plant Contracting | Locks in multi-year volume commitments with tier-one automotive OEMs specifying outcome-based performance guarantees. |
Study Parameters
Cross-validation between primary interviews with coating formulation chemists, automotive OEM procurement directors, appliance manufacturing plant managers, and regional distribution channel partners anchors the qualitative findings, while secondary validation draws from ECHA restricted substance notifications, EPA NESHAP compliance databases, China MEE emission control filings, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up demand modeling triangulates against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis on feedstock cost volatility and regulatory timeline acceleration frames the forecast confidence intervals across thermosetting, thermoplastic, hybrid, and reactive product architectures, with end-use segmentation spanning automotive exterior trim, appliance exterior finishes, furniture metal coating, and protective infrastructure applications. CAGRs derive from regression analysis of historical coating displacement patterns and projected solvent-to-powder conversion rates under tightening VOC mandates. Industry-specific inputs include aliphatic isocyanate capacity utilization rates and superdurable polyester resin technology adoption curves.
Underlying assumptions cover sustained REACH enforcement stringency and China's dual carbon goal compliance trajectories, with deviation risk concentrated in feedstock supply disruptions from German and Japanese producers or accelerated thermoplastic liquid coating substitution in flexible substrate applications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Spain Automotive OEM Coatings Market
Coatings
High Performance Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
CVD Coating Technology Market
Coatings
Europe Coil Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Asia-Pacific Flat Glass Coating Market
Coatings
Gelcoat Market
Coatings
Coated Casing Market
Coatings
North America Thermal Spray Market
Coatings
North America Polyimide Coating Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Global Hydrophobic Coating Market