
 Global Glass Filled Nylon Market | 2026-2036
Global Glass Filled Nylon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Filled Nylon Market Intelligence
Engineering-grade specification tiers is collapsing the gap between commodity polyamide and high-performance alternatives. BASF SE leverages its integrated caprolactam chain to sustain cost-competitive supply of PA66 glass filled grades across European automotive programs. Lanxess anchors its position through specialized halogen-free flame-retardant formulations targeting electrical component applications. Ascend Performance Materials dominates North American supply of adiponitrile-based PA66 compounds, controlling upstream feedstock access that competitors cannot readily replicate.
Glass filled nylon denotes polyamide resins reinforced with chopped or milled glass fibers, typically loaded at 10-50% by weight to achieve tensile strengths exceeding 150 MPa and heat deflection temperatures above 240°C, serving industries that require metal replacement with corrosion-resistant, moldable thermoplastics. PA66 Glass Filled leads volume due to its established performance credentials in automotive under-hood and powertrain applications where thermal aging resistance proves critical. PA6 Glass Filled occupies the fastest-expanding tier as appliance manufacturers and industrial machinery producers accept slightly lower heat performance in exchange for processing economics and broader supply availability.
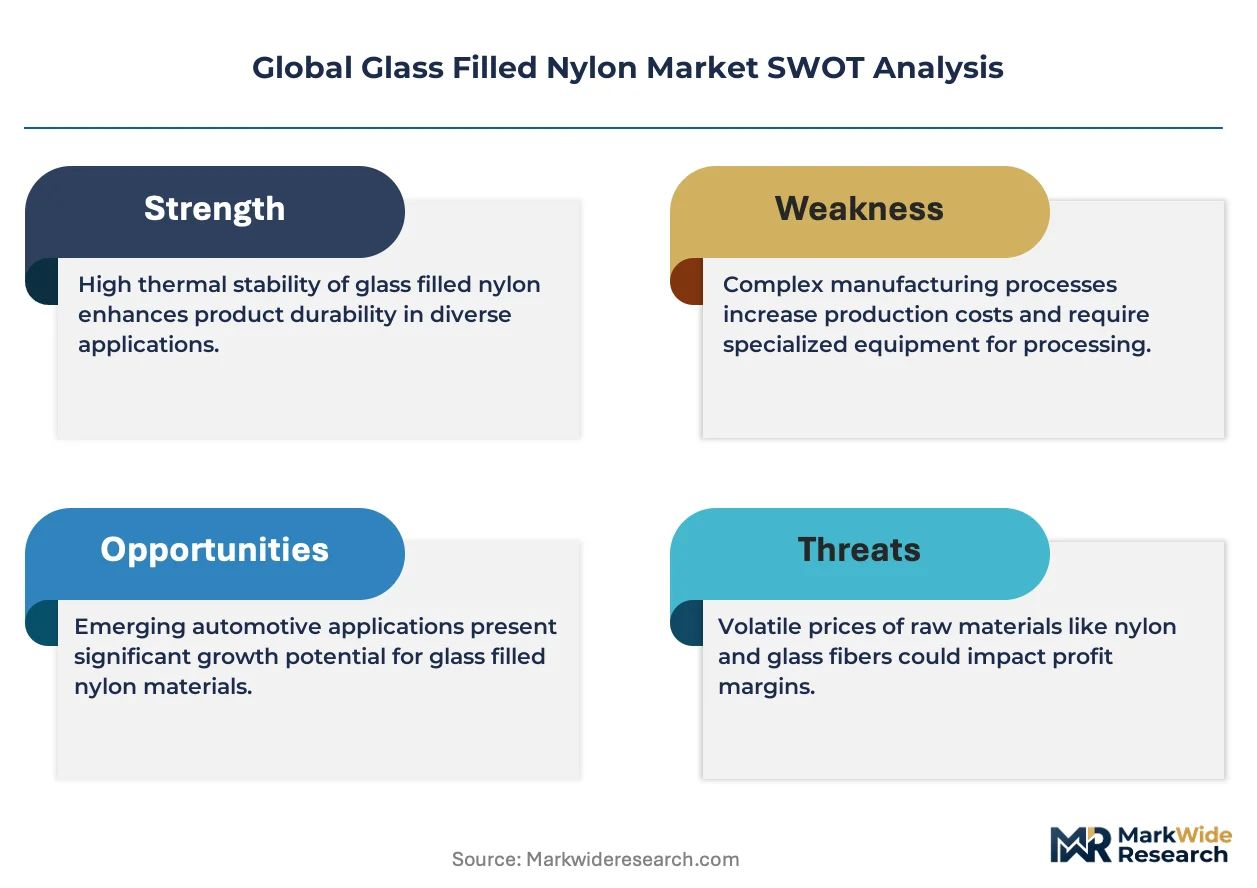
EPA regulations on per- and polyfluoroalkyl substances constrain certain lubricant and mold-release additives used in glass filled nylon compounding, forcing reformulation investments across US-based producers. REACH authorization requirements under ECHA oversight restrict specific flame-retardant chemistries in European electrical component applications, redirecting R&D toward phosphorus-based and mineral alternatives. China's GB standards and MIIT directives on new energy vehicle material specifications establish domestic content benchmarks that shape supplier qualification for battery housing and thermal management components. Stakeholders must monitor how diverging regional chemical compliance frameworks reshape formulation portfolios and determine which compounders can maintain cross-border product registrations without duplicative development costs.
Market Dynamics
Automotive electrification programs are compressing development cycles for thermal management components, forcing compounders to validate new glass-reinforced grades against battery housing specifications before traditional metal-to-plastic conversion timelines mature.
Growth Catalysts
- EPA material standards:Tightening permissible additive chemistries under evolving EPA frameworks is accelerating reformulation toward halogen-free flame-retardant systems in US electrical component supply chains.
- China domestic compounding:Concentrated capacity expansion around Shanghai and Guangdong is serving both local appliance manufacturers and export-oriented automotive Tier-1 suppliers with integrated resin-to-compound operations.
- Metal replacement engineering:Heat deflection targets above 240°C in powertrain modules are pulling PA66 glass filled grades into transmission covers and oil pan applications previously reserved for aluminum castings.
Market Restraints
- Adiponitrile supply concentration:North American feedstock control by integrated producers limits second-tier compounder access to cost-competitive PA66 base resin during capacity tightness.
- REACH authorization timelines:ECHA oversight of specific flame-retardant chemistries is forcing European electrical component producers into extended qualification cycles for phosphorus-based alternatives.
- Long-fiber thermoplastic substitution:Direct long-fiber injection molding compounds are capturing structural automotive applications where glass filled nylon previously dominated load-bearing brackets.
Strategic Opportunities
- India appliance manufacturing:BIS certification requirements and domestic production incentives under PLI schemes are creating qualified supplier status for glass-reinforced polyamide in washing machine and air conditioner structural components.
- Battery housing thermal management:New energy vehicle specifications under China's MIIT directives are establishing material benchmarks for flame-retardant grades in module enclosures and coolant manifolds.
- Recycled content mandates:EU Green Deal circular economy requirements are opening formulation space for post-industrial glass fiber recovery streams in non-critical automotive interior applications.
Industry Challenges
- Cross-border registration duplication:Divergent chemical compliance frameworks between EPA, REACH, and China's GB standards are forcing compounders to maintain parallel formulation portfolios without volume scaleback benefits.
- Compounding equipment retrofit:Twin-screw extruder investments for specialized halogen-free flame-retardant processing are concentrating capex among integrated producers with captive resin supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Filled Nylon Market |
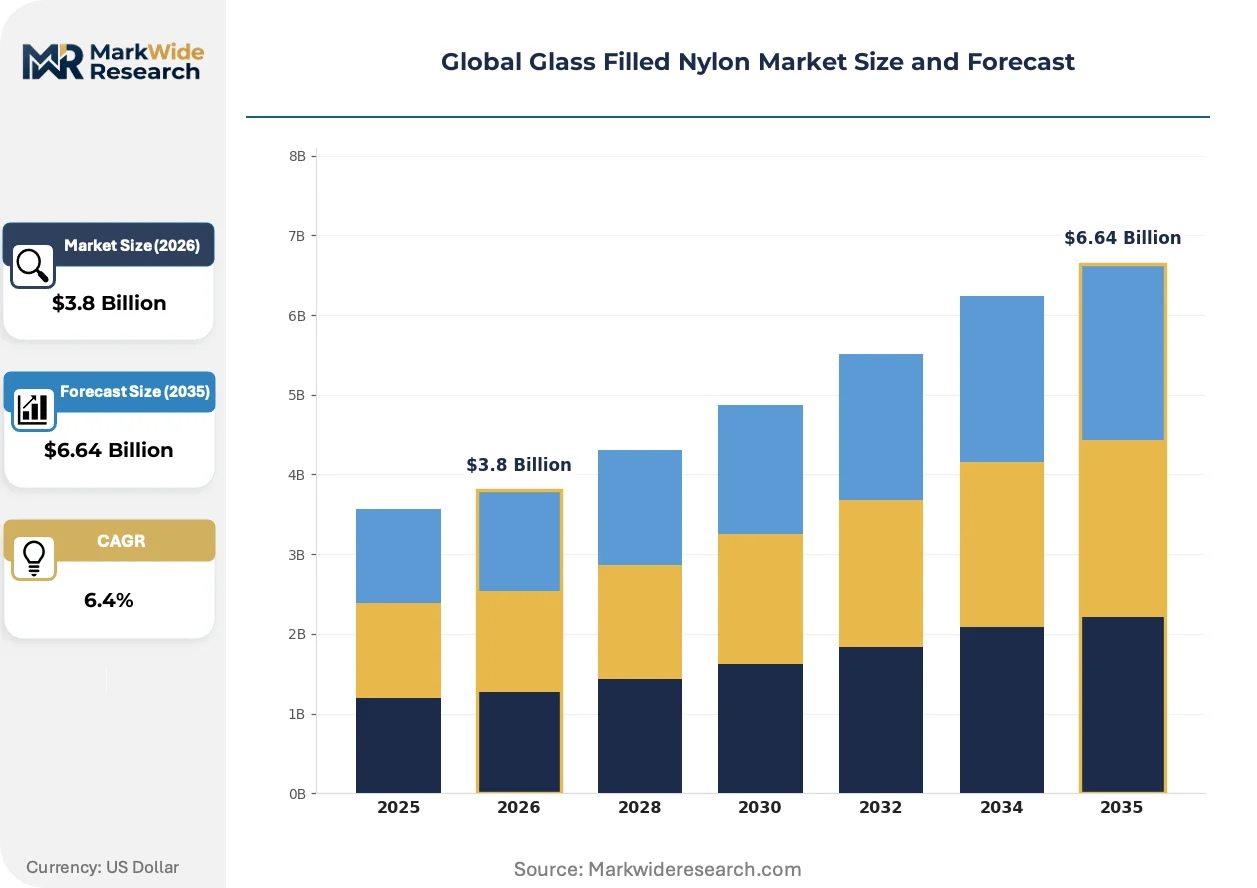
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA6 Glass Filled, PA66 Glass Filled, PA11 Glass Filled, PA12 Glass Filled, PA46 Glass Filled Form: Granules, Pellets, Powder, Laminates, Films Application: Electrical Components, Consumer Products, Industrial Machinery, Sporting Goods, Aerospace Parts End User Industry: Electronics Manufacturing, Construction Equipment, Consumer Electronics, Automotive Tier-1 Suppliers, Sports Equipment Producers |
| Companies Covered | BASF SE, Lanxess, Asahi Kasei Corporation, Ascend Performance Materials, Arkema, SABIC, Evonik Industries, Ensinger, Royal DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Filled Nylon Market Strategic Shifts & Innovations
Formulation science is pivoting toward multi-functional additive packages that simultaneously address thermal aging, flame retardancy, and process stability, collapsing the traditional sequential development sequence for engineered polyamides.
Hybrid reinforcement systems combining chopped glass with mineral fillers are decomposing the established performance hierarchy between standard 30% glass filled grades and premium high-heat alternatives. Appliance manufacturers in Southeast Asia are specifying these intermediate tiers for washing machine tubs and dryer housings where heat requirements sit below automotive thresholds. The resulting specification compression is eroding price premiums for legacy high-performance grades without full thermal certification.
REACH authorization requirements under ECHA oversight are redirecting flame-retardant development away from halogenated systems toward phosphorus-nitrogen synergists and mineral hydrate alternatives. Electrical connector producers face reformulation timelines that exceed typical automotive program launch windows. German automotive supply chains are responding by pre-qualifying multiple compounder sources to avoid single-supplier dependency during transition periods.
Consolidated procurement contracts spanning resin, compounding, and color concentrate are displacing fragmented multi-vendor arrangements in major appliance OEMs. Direct material cost transparency is replacing traditional distributor markups in negotiations with qualified compounders. This channel compression is most visible in China's domestic appliance sector, where Haier and Midea are consolidating glass filled nylon supply under single-source technical partnership frameworks.
Global Glass Filled Nylon Market Segmentation
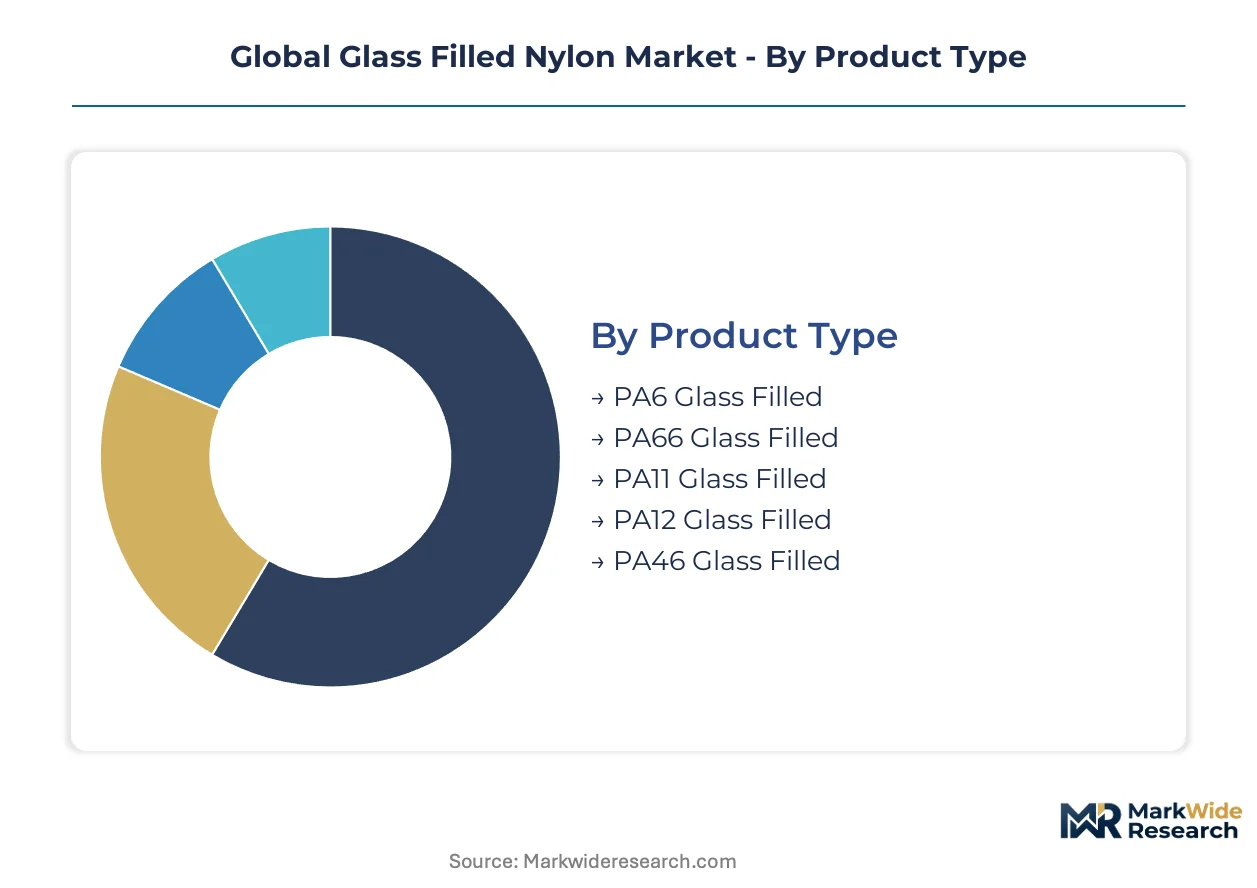
Glass filled nylon markets fragment across polymer chemistry, physical form, and downstream application requirements. Each segmentation dimension carries distinct channel economics and qualification barriers that reshape supplier positioning.
Product Type:
Channel mix varies sharply by base polymer chemistry, with automotive programs favoring integrated resin-to-compound supply while appliance procurement runs through distributor networks.
- PA6 Glass Filled:Polyamide 6 base resin offers lower melt viscosity and broader supply availability than higher-performance alternatives. Appliance manufacturers in China and Southeast Asia specify this grade for washing machine tubs and air conditioner housings where processing economics outweigh marginal thermal performance gaps.
- PA66 Glass Filled:Superior heat deflection temperature above 240°C and thermal aging resistance anchor automotive under-hood applications. Adiponitrile feedstock concentration limits second-tier compounder access, channeling volume through integrated producers with captive PA66 resin supply.
- PA11 Glass Filled:Bio-based castor oil feedstock serves niche applications requiring renewable content credentials and chemical resistance.
- PA12 Glass Filled:Lower moisture absorption suits precision electrical connectors and fuel system components.
- PA46 Glass Filled:Highest thermal performance tier targets powertrain modules and electric motor housings in electrified vehicles.
PA66 Glass Filled dominates installed base. PA6 Glass Filled is where expansion concentrates.
Form:
Physical form selection tracks equipment investment and downstream processing method, with extrusion-grade pellets commanding volume leadership over specialized formats.
- Granules:Standard extrusion and injection molding feedstock format. Tier-1 automotive suppliers in Germany and Japan specify granules for direct feeding into twin-screw compounding lines with integrated color concentrate addition.
- Pellets:Precision-cut cylindrical form enables consistent feeding in high-speed packaging machinery. Appliance OEMs in China's Pearl River Delta prefer pellets for automated material handling systems in washing machine and dryer production.
- Powder:Rotational molding and coating applications require controlled particle size distribution.
- Laminates:Compression molding preforms serve structural aerospace and industrial applications.
- Films:Thin-gauge extrusion targets electrical insulation and flexible circuit substrates.
Granules capture the highest shipment volumes. Pellets are climbing the fastest in specification intensity.
Application:
Application-driven segmentation reveals divergent performance thresholds, with electrical components demanding flame-retardant certification while industrial machinery prioritizes wear resistance.
- Electrical Components:Connectors, circuit breakers, and relay housings require halogen-free flame-retardant formulations meeting UL94 V-0 ratings. REACH authorization timelines under ECHA oversight are forcing European producers into extended qualification cycles for phosphorus-based alternatives.
- Industrial Machinery:Gears, bearings, and structural housings substitute for metal in corrosive environments. Mining equipment manufacturers in Australia specify glass-reinforced grades for conveyor components exposed to abrasive dust and moisture cycling.
- Consumer Products:Power tool housings and appliance structural parts balance impact resistance with surface finish quality.
- Sporting Goods:Bicycle components and ski bindings leverage high stiffness-to-weight ratios.
- Aerospace Parts:Interior cabin components and secondary structural elements require FAA-compliant flame and smoke toxicity certification.
Electrical Components command formulation premiums. Industrial Machinery offers the steepest expansion trajectory.
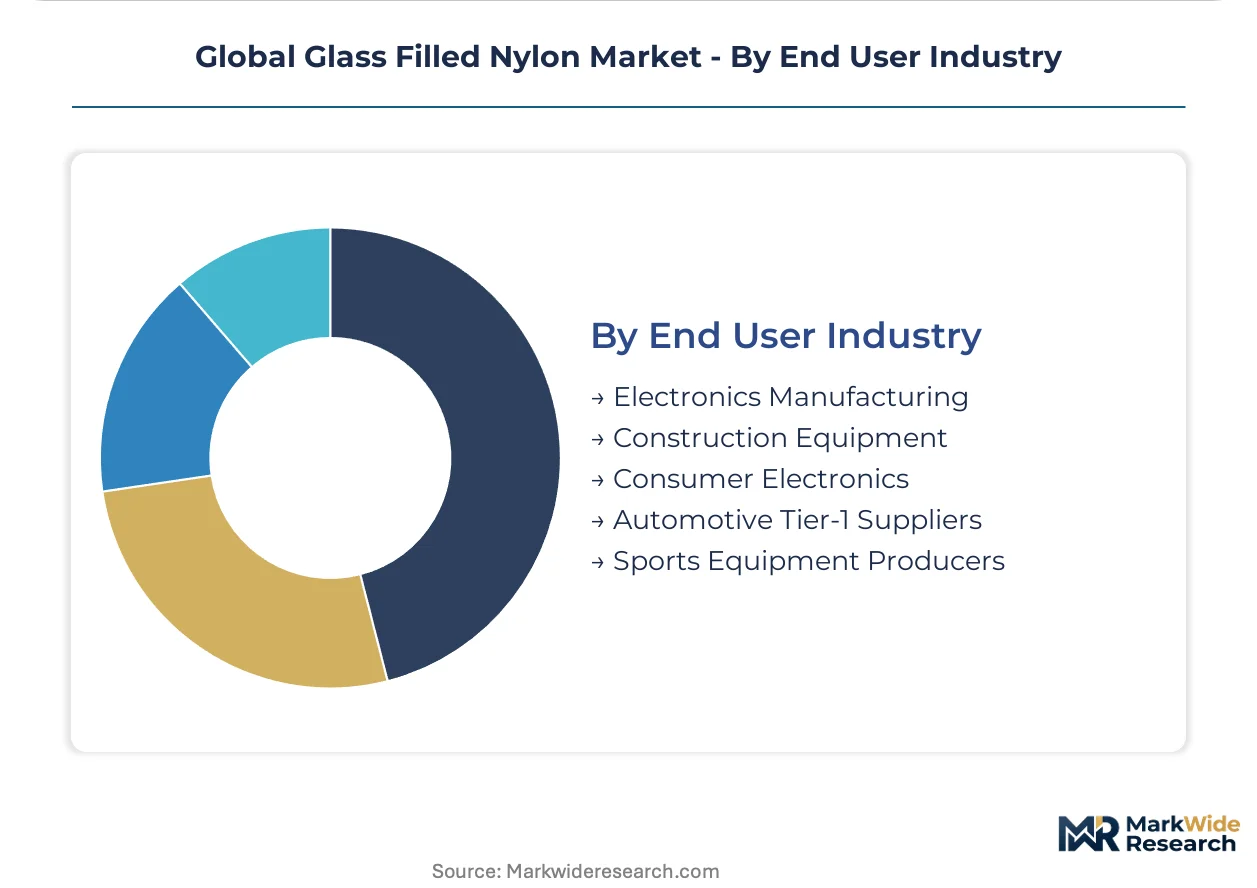
End User Industry:
End-user concentration shapes technical service requirements, with automotive programs demanding resident engineering support while construction equipment runs through distributor technical sales.
- Automotive Tier-1 Suppliers:Under-hood powertrain and thermal management components drive the most demanding material specifications. Battery housing programs for new energy vehicles under China's MIIT directives are establishing flame-retardant grade benchmarks for module enclosures.
- Electronics Manufacturing:Connector and housing producers in Taiwan and South Korea specify tight dimensional tolerance grades for miniaturized devices.
- Construction Equipment:Hydraulic component housings and cab structural parts substitute for cast metal.
- Consumer Electronics:Laptop chassis and smartphone internal frames require thin-wall moldability.
- Sports Equipment Producers:Cycling and winter sports manufacturers specify high-modulus grades for load-bearing structures.
Automotive Tier-1 Suppliers anchor volume concentration. Electronics Manufacturing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated resin-to-compound operations cluster in three distinct geographies where automotive and appliance demand intersect with feedstock access. Each concentration point faces divergent regulatory timelines that reshape formulation portfolios.
United States
Automotive Tier-1 suppliers around Detroit and the Southeast are validating glass-reinforced grades for battery housing specifications under NHTSA electrification guidelines. EPA constraints on per- and polyfluoroalkyl substances are forcing reformulation of lubricant additives in compounding operations. Ascend Performance Materials anchors adiponitrile-based PA66 supply from its integrated Gulf Coast facilities.
Germany
BASF SE leverages its Ludwigshafen caprolactam chain to serve European automotive programs with cost-competitive PA66 grades. REACH authorization timelines under ECHA oversight are extending qualification cycles for phosphorus-based flame-retardant alternatives in electrical connector applications. The Rhine-Neckar cluster concentrates twin-screw compounding capacity for halogen-free formulations.
China
Domestic compounding capacity around Shanghai and Guangdong serves both local appliance manufacturers and export-oriented automotive supply chains. MIIT directives on new energy vehicle material specifications establish domestic content benchmarks for battery housing components. Haier and Midea are consolidating glass filled nylon procurement under single-source technical partnerships.
Japan
Asahi Kasei Corporation and other integrated producers supply precision-grade compounds to electronics manufacturers in the Kanto region. METI industrial standards shape qualification requirements for automotive under-hood applications. Miniaturized connector producers in Tokyo-Osaka corridors specify tight dimensional tolerance grades.
India
Appliance manufacturing expansion under PLI schemes is creating qualified supplier status for glass-reinforced polyamide in washing machine and air conditioner structural components. BIS certification requirements filter compounder entry into domestic supply chains. Gujarat and Maharashtra industrial corridors are attracting compounding investments to serve white goods OEMs.
Global Glass Filled Nylon Market Key Industry Players
Concentration sits with integrated petrochemical groups controlling upstream adiponitrile and caprolactam supply. Three archetypes define competitive positioning: resin-integrated compounders with captive feedstock, specialized flame-retardant formulators, and regional distributors with technical service capabilities. Dominant moves include backward integration into base resin production and twin-screw extruder investments for halogen-free processing.
Among European resin-integrated producers, BASF SE exemplifies the archetype of cost-competitive supply through vertical control of the caprolactam chain. Lanxess occupies a position within the specialized formulation tier, anchoring halogen-free flame-retardant development for electrical component applications. Ascend Performance Materials represents North American feedstock concentration, with its adiponitrile-based operations limiting second-tier compounder access during capacity tightness.
| Leading Market Players |
|---|
| BASF SE |
| Lanxess |
| Asahi Kasei Corporation |
| Ascend Performance Materials |
| Arkema |
| SABIC |
| Evonik Industries |
| Ensinger |
| Royal DSM |
| Others |
Cost & Logistics Intelligence
PA6 glass filled grades displacing PA66 in appliance applications simultaneously shifts compounding capacity toward China and compresses price premiums for legacy high-heat formulations. This substitution dynamic concentrates supply geography around Shanghai and Guangdong while forcing integrated producers to defend margin structures through captive adiponitrile access.
Pricing Analysis
REACH authorization timelines dictate the pricing tier structure across European electrical component supply chains. Three-tier pricing structure across premium, standard, and economy levels separates UL94 V-0 certified halogen-free grades from industrial machinery specifications and commodity appliance grades. Cost compression in standard-tier PA6 compounds is intensifying because Chinese domestic compounding capacity has eliminated distributor markups in consolidated procurement contracts. Appliance OEMs in China's Pearl River Delta exhibit highest price sensitivity, while automotive Tier-1 suppliers anchored by German and Japanese programs accept premium positioning for thermal aging certification.
Supply Chain Analysis
Inventory buffers for adiponitrile-based PA66 resin have compressed to six-to-eight week cycles, exposing compounders to feedstock volatility from Gulf Coast production disruptions. Supply concentrates in the United States, Germany, and China, with raw material dependencies centering on caprolactam, adiponitrile, and chopped glass fiber feedstocks. Single-source vulnerability sits with Ascend Performance Materials' control of North American adiponitrile supply, which limits second-tier compounder access during capacity tightness. Distribution runs through integrated resin-to-compound operations for automotive programs, while appliance procurement channels through technical partnership frameworks with qualified compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification mandates from China's MIIT and EPA frameworks in the United States are compressing qualification timelines for flame-retardant thermal management grades, creating a high-growth disruption window for compounders with validated battery housing specifications.
For Market Incumbents: Shield formulation portfolios from REACH authorization delays by pre-qualifying multiple phosphorus-based flame-retardant sources across European electrical connector programs. Deepen backward integration into caprolactam supply through Ludwigshafen-style integrated production chains, and secure resident engineering contracts with Detroit-based Tier-1 suppliers validating battery housing grades under NHTSA guidelines. For New Entrants and Emerging Players: Technical service gaps in India's PLI-scheme appliance manufacturing corridor offer qualified supplier status for BIS-certified glass-reinforced polyamide in washing machine structural components. Target Gujarat and Maharashtra industrial corridors with localized compounding investments, and penetrate through direct technical partnerships with white goods OEMs seeking to consolidate fragmented distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized flame-retardant formulators with validated halogen-free certifications. Long-term viability over the next decade hinges on cross-border registration capabilities that avoid duplicative development costs under divergent EPA, REACH, and GB standards. Monitor MIIT directive updates on new energy vehicle material specifications as the critical signal for battery housing grade demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Ascend Performance Materials' Gulf Coast facilities anchor North American PA66 supply security against feedstock volatility. |
| Halogen-Free Formulation Certification | Lanxess's phosphorus-nitrogen synergist investments capture REACH-compliant electrical connector market share from legacy brominated systems. |
| Regional Compounding Capacity Expansion | Shanghai and Guangdong integrated operations serve both domestic appliance OEMs and export-oriented automotive supply chains. |
| Technical Partnership Consolidation | Haier and Midea's single-source frameworks displace fragmented distributor markups with direct material cost transparency. |
| Post-Industrial Glass Fiber Recovery | EU Green Deal circular economy requirements open formulation space for recycled content in non-critical automotive interior applications. |
Research Approach
Operator-level perspectives from compounding plant managers, automotive Tier-1 procurement leads, appliance OEM technical directors, and distribution channel partners anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, SEC 10-K filings, ACC and Cefic industry reports, and MIIT directive documentation. Bottom-up volume estimates triangulated against top-down macroeconomic indicators across polymer chemistry, application, and regional production hub segmentation.
Sensitivity analysis tested forecast robustness against adiponitrile supply disruption scenarios and REACH authorization timeline extensions. The analytical framework modeled volume and value outputs across the projection horizon by grade tier, end-use industry, physical form, and regional regulatory cluster. CAGRs derived from regression analysis of historical price-volume relationships, with industry-specific inputs including battery housing content per electric vehicle and appliance OEM procurement consolidation rates.
Underlying assumptions cover sustained automotive electrification program commitments and stable adiponitrile feedstock availability, with deviation risk concentrated in EPA per- and polyfluoroalkyl substance enforcement intensity and ECHA authorization timeline delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
North America Plasma Powder Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Reinforcement Materials Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Global Diamond-Like Carbon (DLC) Market
Advanced Materials
Graphite Materials Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
US Graphene Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Global Electrochromic Materials Market
Advanced Materials
Europe Graphene Market