
 High Nickel Cathode Materials Market | 2026-2036
High Nickel Cathode Materials Market Size, Share, and Industry Trends Forecast 2026-2036
High Nickel Cathode Materials Market Foresight
Korean cathode producers is shifting capacity toward nickel-rich formulations to secure European automotive supply contracts. LG Chem leverages integrated refining partnerships to lock in nickel sulfate feedstock. POSCO Future M anchors its expansion on pyrometallurgical precursor capabilities in Pohang. Samsung SDI competes through proprietary single-crystal NMC technology that extends cycle life.
High nickel cathode materials are lithium-ion battery cathodes containing nickel concentrations exceeding 60% by metal content, typically formulated as NMC811 or NCA to maximize energy density above 200 mAh/g for electric vehicle applications. These materials undergo co-precipitation and solid-state calcination to achieve layered oxide structures that stabilize capacity retention during fast charging. NMC811 leads volume shipments among product types as automakers prioritize range extension over cobalt-heavy alternatives. Battery Manufacturing dominates application demand, though Grid Storage is gaining traction as utilities seek higher energy density for stationary systems. Powder form commands the largest share, yet Coated variants are expanding as producers address surface degradation in high-voltage operation.
The EU Battery Regulation mandates recycled content thresholds and supply chain due diligence, compelling producers to reconfigure sourcing networks toward compliant jurisdictions. EPA tailpipe standards and NHTSA fuel economy rules in the United States accelerate OEM demand for nickel-dense cells that improve pack-level efficiency. China's MEE enforces emissions caps on nickel refining that constrain raw material availability for non-integrated cathode makers. Stakeholders must monitor regulatory divergence between carbon border adjustments and domestic content incentives as these frameworks reshape qualification requirements for battery supply contracts.
Market Dynamics
The transition from NMC622 to NMC811 and NCA chemistries is compressing cobalt demand while amplifying nickel sulfate procurement intensity across cathode supply chains. This compositional shift is restructuring feedstock sourcing networks and refining capacity allocation decisions.
Growth Catalysts
- EPA tailpipe standards:US OEMs are accelerating nickel-dense cell qualification to meet fleet-average emissions mandates, pulling forward cathode procurement timelines.
- Single-crystal NMC technology:Korean battery makers are deploying proprietary crystalline architectures that extend cycle life above 4,000 cycles, enabling extended-range EV platforms.
- Pohang precursor cluster:South Korea's pyrometallurgical concentration is attracting integrated cathode investments that reduce logistics costs to European automotive customers.
Market Restraints
- Nickel sulfate price volatility:MHP and mixed hydroxide feedstock costs fluctuate with Indonesian nickel pig iron export policies, compressing cathode maker margins.
- EU Battery Regulation due diligence:Supply chain auditing requirements for cobalt and nickel origin are extending qualification timelines by 12-18 months for non-integrated producers.
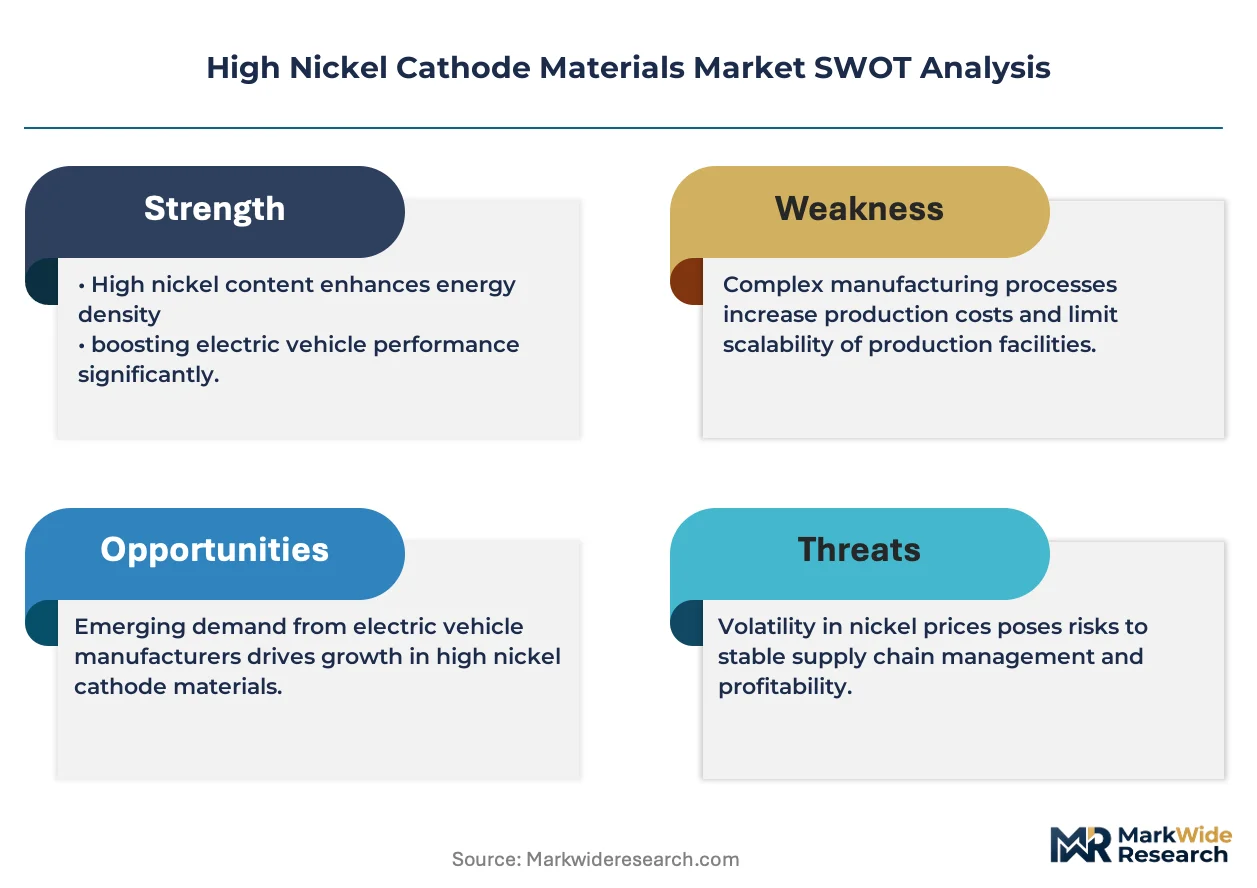
- Thermal runaway sensitivity:NMC811's lower thermal stability versus LFP is constraining adoption in commercial vehicle segments with extreme duty cycles.
Strategic Opportunities
- Grid storage deployment:Utility-scale battery projects are specifying high-nickel cathodes for energy density-critical containerized systems in California and Texas.
- IR domestic content credits:US cathode production incentives are attracting Korean and Japanese producers to establish North American precursor facilities.
- Recycled nickel feedstock:Black mass refining capabilities in Europe are creating compliant circular supply channels for EU Battery Regulation recycled content thresholds.
Industry Challenges
- Calcination energy costs:Solid-state sintering of layered oxides requires sustained temperatures above 800°C, exposing producers to natural gas price spikes.
- Surface coating IP:Proprietary alumina and titania coating patents held by Japanese material houses are creating licensing friction for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Nickel Cathode Materials Market |
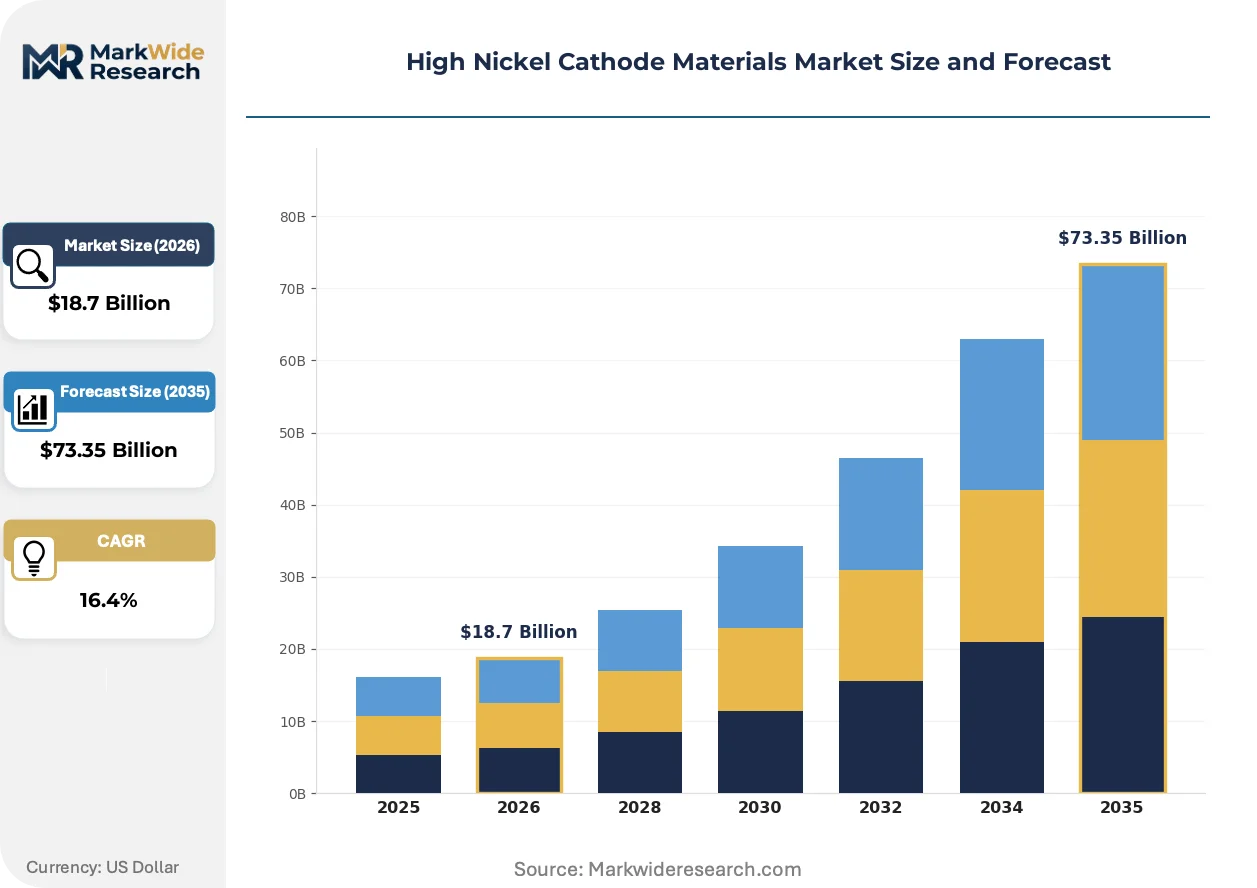
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NMC811, NMC622, NCA, LCO End User: Electronics, Automotive, Energy Storage, Aerospace Form: Powder, Coated, Pellet, Sheet Application: Battery Manufacturing, Electric Vehicles, Portable Devices, Grid Storage |
| Companies Covered | LG Chem, Contemporary Amperex Technology Co. Limited, Samsung SDI, POSCO Future M, Umicore, BASF, Sumitomo Metal Mining Co., Ltd., SK Innovation, EcoPro BM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Nickel Cathode Materials Market Shifts & Advancements
High-nickel cathode manufacturing is pivoting from cost-driven scale toward precision-controlled microstructure engineering that governs cycle stability and fast-charge acceptance.
Single-crystal NMC synthesis is rewriting performance benchmarks for automotive applications. This architecture eliminates grain boundaries that fracture during lithium intercalation, extending calendar life. European OEMs are qualifying single-crystal variants for 800V platforms. The technology is compressing the competitive window for polycrystalline alternatives in premium EV segments.
EU Battery Regulation carbon footprint disclosure rules are mandating granular emissions accounting across mining, refining, and active material production stages. Cathode producers must now document scope 3 emissions from Indonesian nickel laterite processing through European precursor manufacturing. Korean integrated suppliers are responding by securing renewable power purchase agreements for Pohang and Gwangyang refining operations.
Automotive cell procurement is consolidating around multi-year offtake agreements with volume-commitment clauses and price-adjustment mechanisms tied to nickel sulfate indices. Tier 1 battery makers are displacing spot-market purchasing for cathode active materials. This contractual shift is most visible in South Korea, where SK Innovation and Samsung SDI have locked Korean cathode suppliers into five-year supply frameworks indexed to London Metal Exchange nickel futures.
High Nickel Cathode Materials Market Segmentation
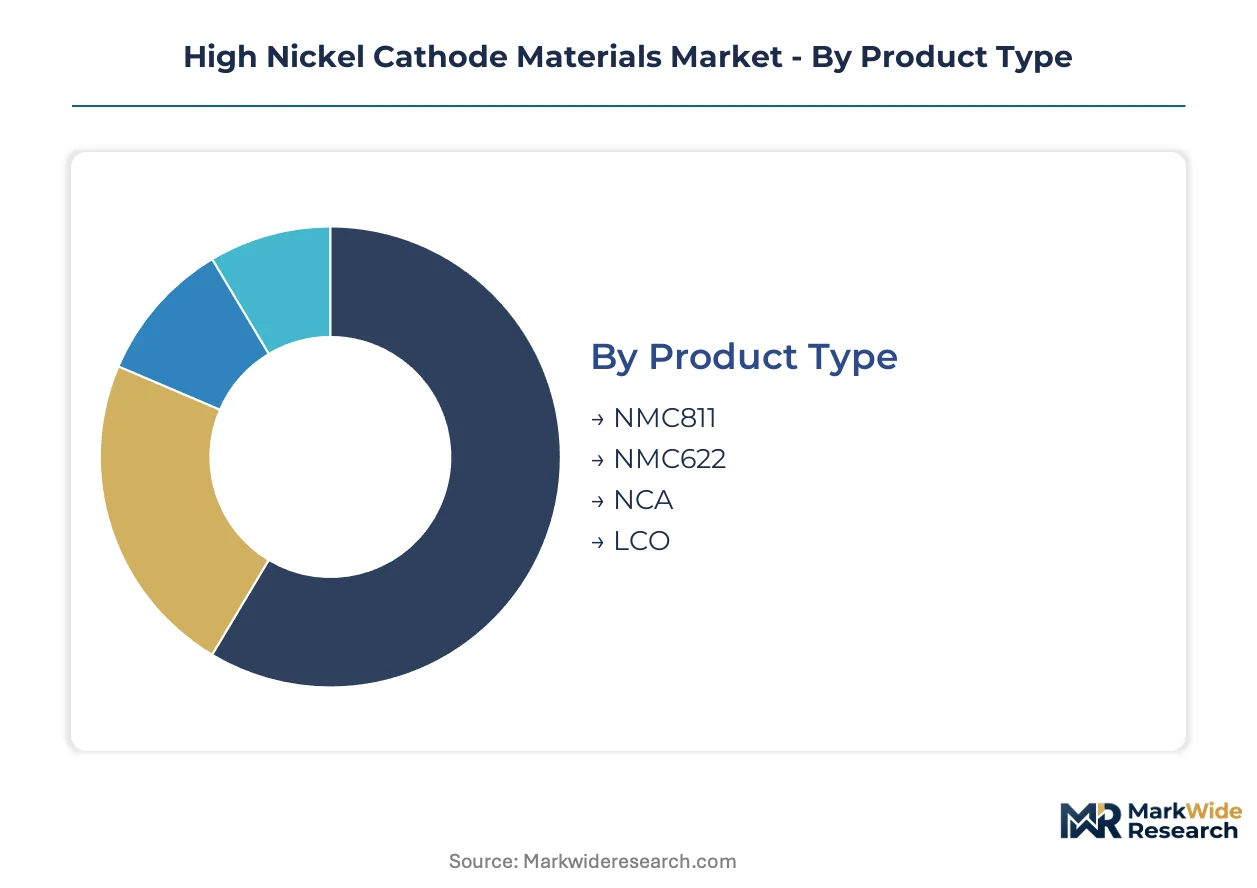
High nickel cathode materials fragment across chemistry, end-use, and physical form dimensions. Each segmentation axis carries distinct margin structures, qualification timelines, and supply chain configurations that reshape procurement strategies for battery makers.
Product Type:
Chemistry selection separates buyers by energy density requirements and thermal stability tolerance.
- NMC811:Nickel-manganese-cobalt oxide with 80% nickel content delivers specific capacity above 200 mAh/g. Automotive OEMs in South Korea and Germany are locking in multi-year offtake agreements for this chemistry to power 800V EV platforms demanding maximum range.
- NCA:Nickel-cobalt-aluminum oxide formulations achieve comparable energy density with reduced manganese content. Tesla's cylindrical cell procurement and Panasonic's Nevada operations anchor demand concentration for NCA variants in North American EV production.
- NMC622:Moderate nickel content offers transitional thermal stability for commercial vehicle applications.
- LCO:Lithium cobalt oxide serves premium electronics segments where energy density trumps cost sensitivity.
Volume sits with NMC811; growth tilts toward NCA as cylindrical cell architectures expand beyond Tesla's supplier base.
End User:
Customer type determines pricing tolerance, certification rigor, and contract duration.
- Automotive:Tier 1 battery makers impose qualification protocols exceeding 18 months. Korean cathode producers POSCO Future M and LG Chem are expanding Pohang and Gwangyang capacity to meet European automotive carbon footprint disclosure rules under EU Battery Regulation.
- Energy Storage:Utility-scale developers prioritize cycle life over energy density. California and Texas grid projects are specifying high-nickel cathodes for containerized battery systems where space constraints dominate site economics.
- Electronics:Smartphone and laptop manufacturers favor established LCO and NMC622 chemistries with proven supply chains.
- Aerospace:Satellite and electric aviation applications demand ultra-high reliability with conservative derating protocols.
Contract value concentrates in Automotive; margin expansion is steepest in Energy Storage as developers accept premium pricing for certified low-carbon material.
Form:
Physical presentation governs handling economics and surface modification requirements.
- Powder:Unprocessed active material dominates current shipments. Samsung SDI and SK Innovation in South Korea receive bulk powder for in-house electrode coating lines that integrate with their proprietary binder and conductive additive recipes.
- Coated:Surface-treated variants with alumina or titania layers mitigate interfacial degradation during high-voltage operation. Japanese material houses hold blocking patents on specific coating architectures, creating licensing friction for new entrants targeting European premium EV contracts.
- Pellet:Pre-pressed forms suit specialty research and pilot-scale battery assembly.
- Sheet:Cast electrode sheets serve niche prototyping and medical device applications.
Throughput remains highest for Powder; value capture is climbing fastest for Coated as cell makers outsource surface engineering to capture yield improvements.
Application:
Use case defines performance thresholds and regulatory exposure.
- Electric Vehicles:Pack-level efficiency mandates push nickel content toward theoretical limits. EPA tailpipe standards and NHTSA fuel economy rules in the United States accelerate OEM qualification of NMC811 and NCA cells for fleet compliance.
- Grid Storage:Stationary systems tolerate lower energy density in exchange for extended calendar life. Texas ERCOT market participants are deploying high-nickel cathodes in 4-hour duration battery plants where container footprint costs exceed active material premiums.
- Battery Manufacturing:Cell makers consume cathode materials across all chemistries for diverse customer portfolios.
- Portable Devices:Consumer electronics demand stable supply chains with minimal qualification overhead.
Shipment volume aggregates in Electric Vehicles; adoption velocity is accelerating most sharply in Grid Storage as utilities revise procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel laterite deposits anchor raw material flows for cathode supply chains. Processing capacity concentrates in East Asia and Europe as battery makers seek qualified feedstock. Regulatory frameworks in major economies are reconfiguring investment patterns across refining and precursor stages.
China
NMC811 cell demand from domestic automotive OEMs drives cathode procurement volumes. MEE emissions caps on nickel refining constrain raw material availability for non-integrated producers. The Yangtze River Delta hosts precursor manufacturing clusters serving battery makers with integrated refining partnerships.
South Korea
SK Innovation and Samsung SDI anchor demand concentration for nickel-rich formulations. Korean producers leverage pyrometallurgical capabilities in Pohang to reduce logistics costs for European automotive contracts. The Gwangyang refining complex is expanding renewable power purchase agreements to meet EU Battery Regulation carbon disclosure requirements.
Germany
European OEM qualification protocols for 800V EV platforms pull NMC811 procurement timelines forward. EU Battery Regulation mandates recycled content thresholds and supply chain due diligence for cobalt and nickel origin. The country's industrial regions host precursor qualification facilities serving automotive cell supply contracts.
United States
EPA tailpipe standards and NHTSA fuel economy rules accelerate OEM demand for nickel-dense cells. IRA domestic content credits attract Korean and Japanese producers to establish North American precursor facilities. Texas ERCOT market participants deploy high-nickel cathodes in utility-scale battery projects where container footprint costs dominate site economics.
Japan
Japanese material houses hold blocking patents on alumina and titania coating architectures for surface-treated cathode variants. METI industrial policy supports domestic precursor capabilities amid supply chain reconfiguration pressures. The country's battery material sector focuses on licensing arrangements for European premium EV contract qualification.
High Nickel Cathode Materials Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated refining and precursor capabilities to capture margin upstream. The market structure concentrates around Korean and Chinese suppliers with captive nickel sulfate access. Three archetypes dominate: integrated chemical conglomerates with refining assets, specialized cathode material houses, and battery makers with backward integration into active material production. Capacity expansion and strategic partnerships constitute the primary competitive vectors as producers secure offtake agreements with volume-commitment clauses.
Within the integrated chemical tier, LG Chem and POSCO Future M exemplify producers leveraging captive refining partnerships to lock in feedstock security. Contemporary Amperex Technology Co. Limited anchors the battery-maker-integrated archetype, representing the vertical control model where cell production drives cathode procurement strategy. These three entities collectively illustrate how geographic proximity to nickel processing and automotive customer concentration shapes competitive positioning across the supply chain.
| Leading Market Players |
|---|
| LG Chem |
| Contemporary Amperex Technology Co. Limited |
| Samsung SDI |
| POSCO Future M |
| Umicore |
| BASF |
| Sumitomo Metal Mining Co., Ltd. |
| SK Innovation |
| EcoPro BM |
| Others |
Supply & Pricing Matrix
Captive refining partnerships in Indonesia and South Korea anchor both feedstock security and pricing power for cathode producers serving European automotive contracts under EU Battery Regulation carbon disclosure mandates.
Pricing Analysis
Long-term offtake agreements bundle volume commitments with technical qualification support, leaving spot-market procurement unbundled and exposed to nickel sulfate index volatility. Three-tier pricing structure across premium, standard, and economy levels separates single-crystal NMC variants certified for 800V platforms from polycrystalline grades and transitional NMC622 formulations. Cost compression in standard-tier cathodes is intensifying because Indonesian nickel pig iron export policies amplify MHP feedstock price swings. Grid storage developers show least price sensitivity, accepting premiums for certified low-carbon material, while commercial vehicle OEMs remain most constrained by thermal stability requirements that limit chemistry options.
Supply Chain Analysis
Black mass refining flows from European battery recycling operations are creating compliant circular feedstock channels that bypass Indonesian laterite dependency. Raw material sourcing draws from Indonesian nickel laterite mines, South Korean pyrometallurgical refineries in Pohang and Gwangyang, and Chinese precursor manufacturing clusters in the Yangtze River Delta. Single-source vulnerability concentrates in Indonesian nickel processing policy shifts that constrain MHP availability. Distribution runs through integrated battery maker cathode production lines in South Korea and China, with European qualification facilities serving automotive cell supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation constructs a cost-of-compliance moat that favors integrated producers with documented scope 3 emissions control, raising qualification barriers for non-captive feedstock buyers.
For Market Incumbents: Deepen pyrometallurgical precursor capabilities in Pohang to lock in European automotive supply contracts. Secure renewable power purchase agreements for Gwangyang refining operations to meet EU Battery Regulation carbon footprint disclosure thresholds. Expand single-crystal NMC capacity before polycrystalline alternatives lose premium EV segment qualification windows.
For New Entrants and Emerging Players: IRA domestic content credits in the United States open a window for North American precursor facility investments serving Korean and Japanese battery maker expansion. Target grid storage applications in California and Texas where container footprint economics override thermal stability concerns. Pursue black mass refining partnerships in Europe to secure compliant recycled nickel feedstock for EU Battery Regulation recycled content thresholds.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated cathode material houses with captive nickel sulfate access and automotive qualification track records. Long-term viability favors producers with backward integration into Indonesian laterite processing or European black mass refining. Monitor EPA tailpipe standard stringency and NHTSA fuel economy rule revisions as demand inflection indicators for nickel-dense cell procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Refining | Captive MHP processing in Indonesia insulates margins from export policy volatility. |
| Single-Crystal NMC Capacity Expansion | Proprietary crystalline architectures extend cycle life above 4,000 cycles for 800V platforms. |
| European Black Mass Refining Partnership | Recycled nickel feedstock satisfies EU Battery Regulation recycled content mandates. |
| Renewable Power Purchase Agreements | Clean energy sourcing for Pohang and Gwangyang operations meets carbon disclosure rules. |
| North American Precursor Facility Investment | IRA domestic content credits attract Korean producers to establish US manufacturing presence. |
Research Methodology
Document review covered SEC filings from cathode material producers, EU Battery Regulation technical documentation, and Indonesian mining policy records, complemented by interviews with battery maker procurement directors, nickel refinery operations managers, automotive platform engineers, and utility-scale storage developers. Secondary validation drew from London Metal Exchange nickel futures data, Yangtze River Delta industrial cluster reports, and Pohang-Gwangyang refining capacity disclosures. Bottom-up cathode shipment estimates triangulated against top-down electric vehicle production forecasts.
Segment-level outputs across chemistry type, end-use application, and physical form dimensions were generated using a demand-cascade framework that maps OEM platform requirements to cathode procurement specifications. CAGRs were derived from production capacity buildout schedules, qualification timeline assumptions, and regulatory compliance cost trajectories. Key inputs included nickel sulfate price index correlations, single-crystal versus polycrystalline yield differentials, and grid storage project development pipelines in ERCOT and CAISO markets.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for layered oxide cathode demand. Forecasts reflect assumptions regarding EU Battery Regulation enforcement timing and Indonesian nickel export policy continuity. Practitioners should monitor EPA tailpipe standard revisions, NHTSA fuel economy rule updates, and Chinese MEE emissions cap adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Magnetic Shielding Sheets Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Corundum Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Global Core Materials Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Wood Foam Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Reinforcement Materials Market