
 Thermal Conductive Material Market | 2026-2036
Thermal Conductive Material Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Conductive Material Market Intelligence
Premium thermal conductive formulations is decoupling from commodity-grade metal pastes on the basis of thermal conductivity thresholds and reliability certification. Dow Inc. leverages its silicone chemistry platform to anchor supply relationships with semiconductor foundries. Henkel AG & Co. KGaA differentiates through adhesive-thermal hybrid formulations that occupy niches in automotive power module assembly. SABIC competes with engineered polymer compounds that sustain performance across extended temperature cycling.
Thermal conductive materials are engineered substances designed to transfer heat efficiently between interfacing surfaces, typically exhibiting thermal conductivity values ranging from 1 W/m·K for filled polymers to over 400 W/m·K for liquid metal alloys, and they serve the essential industrial purpose of preventing thermal failure in densely packaged electronic and electromechanical systems. Thermal Interface Material leads product type demand because chip-to-heat-spreader gaps require compliant, high-conductivity layers that dominate bill-of-materials value in server and AI accelerator builds. Liquid Metal represents the fastest-growing form factor as gallium-based alloys displace traditional pastes in enthusiast and data center cooling solutions where thermal resistance minimization commands price premiums.
The EPA enforces restrictions on volatile organic compound emissions from solvent-based thermal coatings, while REACH regulates the registration and hazard communication of specialty fillers including boron nitride and aluminum oxide nanoparticles. China's MEE implements discharge standards that raise manufacturing costs for carbon-intensive thermal material production, indirectly favoring lower-carbon graphene and synthetic graphite alternatives. Stakeholders must monitor how evolving semiconductor export controls and carbon border adjustments reshape raw material sourcing strategies and regional manufacturing footprints.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are driving thermal interface material specifications upward as chip power densities breach thermal design power thresholds above 500 watts per package.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:The framework tightens thermal management requirements for data center infrastructure, forcing upgrades to high-conductivity interface materials in hyperscale facilities across Germany and the Netherlands.
- AI accelerator packaging:Chiplet architectures from NVIDIA and AMD generate concentrated heat fluxes that demand liquid metal and phase-change materials for reliable operation.
- East Asian manufacturing concentration:Taiwan's TSMC and South Korea's Samsung Foundry anchor procurement volumes that validate new thermal material formulations before global rollout.
Market Restraints
- Gallium supply concentration:China controls roughly 95% of global gallium refining capacity, exposing liquid metal alloy producers to export restriction risks and price volatility.
- REACH registration burdens:ECHA's substance evaluation process for boron nitride and aluminum oxide nanoparticles extends time-to-market for European thermal material launches by 18-24 months.
- Silicone thermal stability ceiling:Conventional silicone-based gap fillers degrade above 200°C, limiting deployment in silicon carbide power modules for electric vehicle inverters.
Strategic Opportunities
- India's PLI scheme for semiconductors:The production-linked incentive program attracts packaging and testing facilities to Gujarat and Karnataka, creating localized thermal material demand without established supplier relationships.
- Automotive power module integration:800V EV architectures from BYD and Hyundai Motor Group require thermal interface materials that survive 10,000+ temperature cycles between -40°C and 175°C.
- Graphene-synthetic graphite hybrids:These formulations bypass carbon-intensive production methods favored by China's MEE discharge standards while matching metal-paste conductivity at lower weight.
Industry Challenges
- Reliability certification timelines:JEDEC-standard thermal cycling tests for automotive qualification demand 1,000+ hours per validation cycle, compressing product development windows.
- Cross-functional thermal design expertise:Packaging engineers must simultaneously optimize electrical, mechanical, and thermal interfaces, creating talent scarcity in semiconductor foundries.
- Legacy paste removal protocols:Data center operators face operational disruption when retrofitting liquid metal solutions due to incompatible cleaning chemistries and rework procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Conductive Material Market |
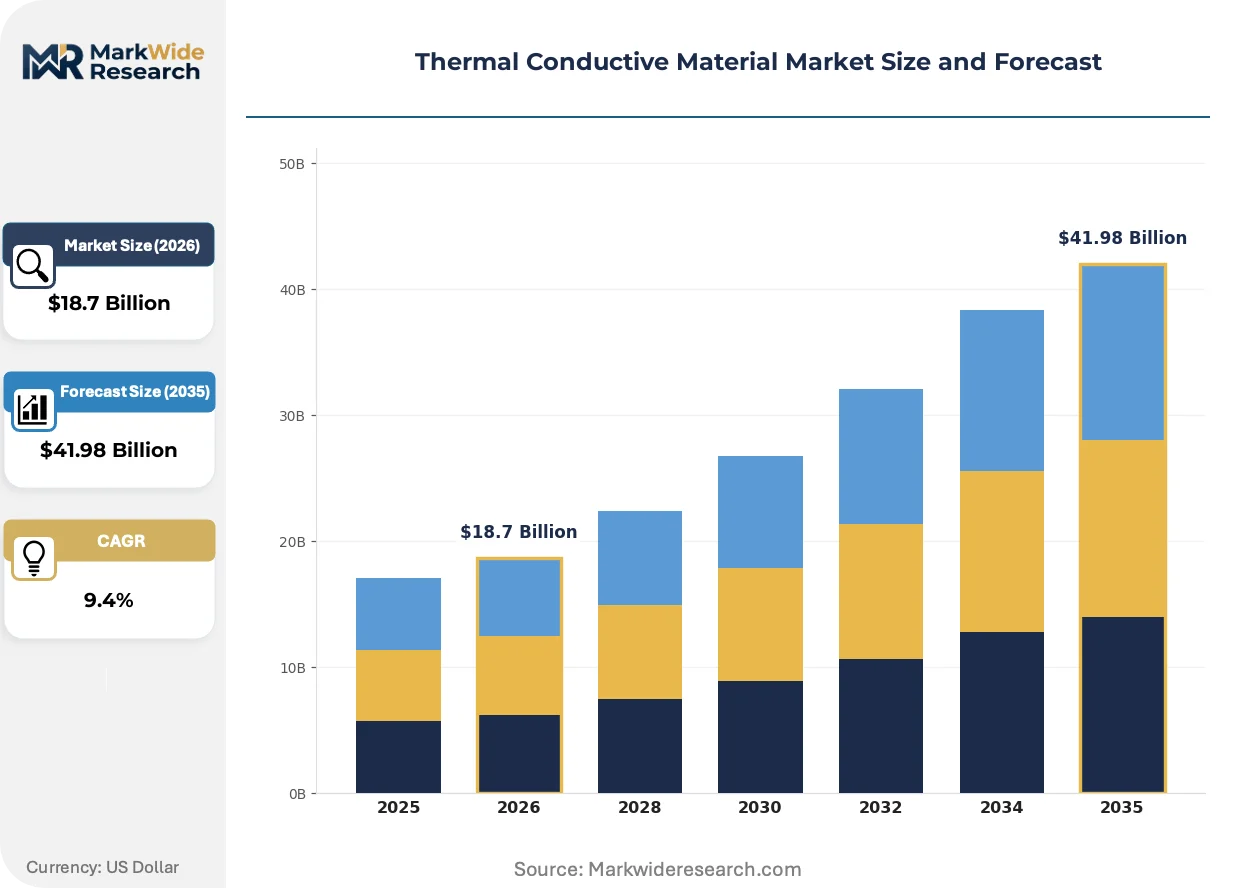
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Interface Material, Graphene, Metal Foam, Liquid Metal End User: Electronics, Automotive, Aerospace, Power Generation Application: Heat Sinks, Thermal Pads, Cooling Solutions, Manage Heat Flow Form: Sheet, Paste, Coating, Composite |
| Companies Covered | 3M Company, Dow Inc., Henkel AG & Co. KGaA, Honeywell International Inc., Celanese Corporation, SABIC, DuPont, Covestro AG, DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Conductive Material Market Strategic Shifts & Innovations
Material science breakthroughs are fragmenting thermal management architectures away from monolithic heat spreaders toward distributed, conformal cooling layers embedded at multiple packaging levels.
Sintered silver thermal interface materials are decentralizing thermal management responsibility from system-level heat sinks to die-level attachment layers. Automotive power module manufacturers in Germany and Japan are adopting silver sintering for silicon carbide MOSFETs at production scale. This shift compresses thermal resistance budgets and enables double-sided cooling geometries previously impractical with solder or polymer alternatives.
China's MEE discharge standards for carbon-intensive chemical production are tightening compliance costs for traditional alumina-filled silicone manufacturing. The regulations indirectly subsidize graphene and synthetic graphite supply chains through differential enforcement intensity. Thermal material producers are relocating carbon-black and metal-oxide mixing operations to Vietnam and Malaysia to maintain cost position.
Hyperscale cloud operators are consolidating thermal material specifications across server generations to compress supplier qualification overhead. Microsoft and Google now mandate single-source thermal interface materials validated for five-year deployment horizons. This concentration rewards formulation suppliers with proven reliability databases while marginalizing specialty material startups lacking field history.
Thermal Conductive Material Market Segmentation
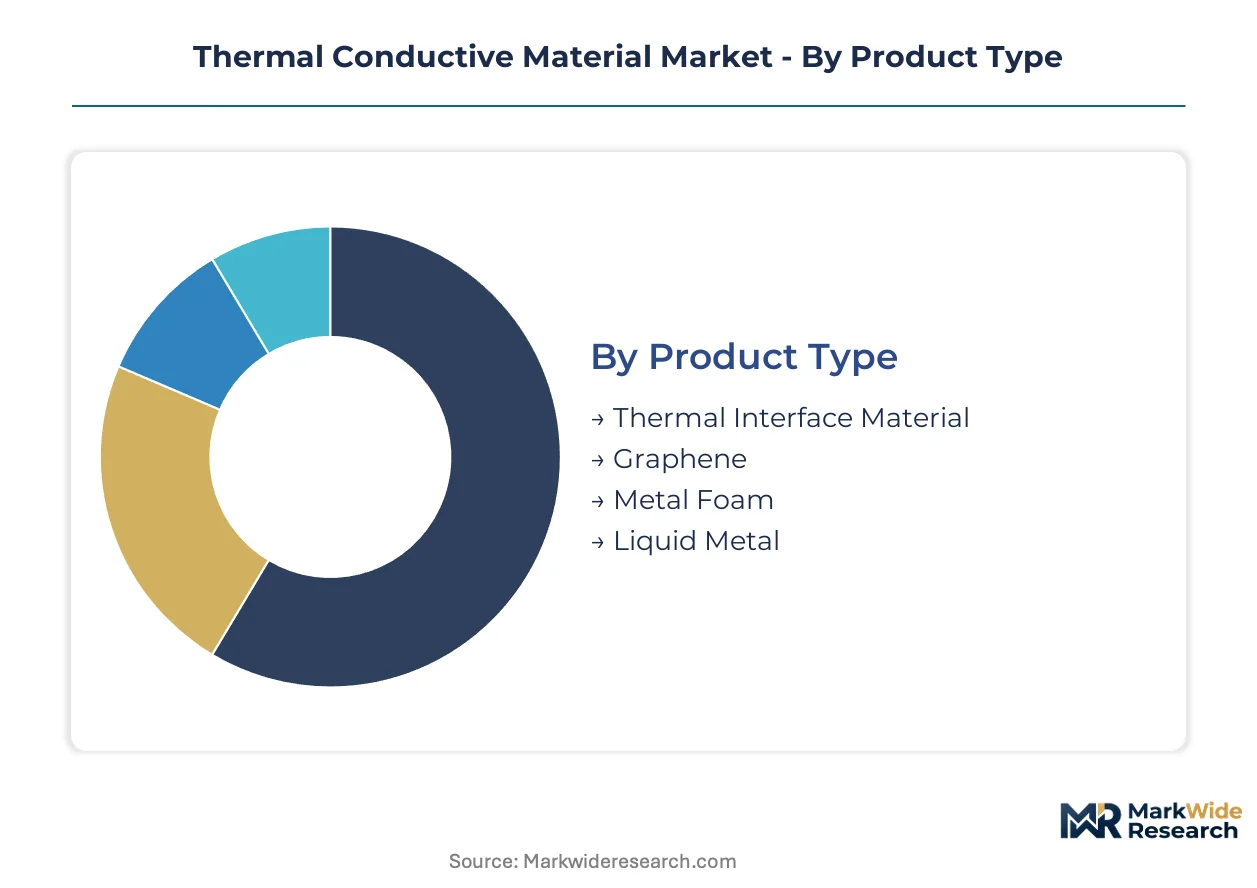
Thermal conductive materials fragment across four critical dimensions that determine procurement specifications, certification requirements, and margin structures. Product type and end-user segmentation reveal the strongest divergence between commodity-grade formulations and performance-critical applications where thermal resistance thresholds command substantial price premiums.
Product Type:
Volume concentration clusters in polymer-based gap fillers, while premium capture belongs to metallic and carbon allotrope formulations that breach thermal conductivity ceilings above 50 W/m·K.
- Thermal Interface Material:Polymer matrices loaded with ceramic or metal fillers dominate server and consumer electronics procurement. Taiwan's TSMC and South Korea's Samsung Foundry validate new formulations before global foundry adoption, anchoring specification-setting power in East Asian packaging clusters.
- Liquid Metal:Gallium-based eutectic alloys achieve thermal conductivity exceeding 70 W/m·K, displacing traditional pastes in AI accelerator and enthusiast cooling where thermal resistance minimization justifies material costs. China's control of global gallium refining creates supply vulnerability for Western formulators.
- Graphene:Exfoliated and CVD-grown variants offer anisotropic conductivity paths for flexible electronics and conformal cooling layers. Synthetic production methods align with China's MEE discharge standards, favoring domestic Chinese suppliers.
- Metal Foam:Open-cell aluminum and copper structures serve phase-change heat spreaders and thermal energy storage systems. Automotive battery thermal management in Germany and Japan drives qualification programs for crash-safe foam geometries.
Mature deployment sits with Thermal Interface Material. Newer deployment is concentrated in Liquid Metal.
End User:
Application requirements diverge sharply between consumer electronics tolerating moderate thermal cycling and automotive power modules demanding 10,000+ temperature excursions without degradation.
- Electronics:Semiconductor packaging, data center infrastructure, and mobile devices consume the largest material volumes. NVIDIA and AMD chiplet architectures generate concentrated heat fluxes above 500 watts per package, forcing specification upgrades across server generations.
- Automotive:800V EV inverters and silicon carbide power modules require materials surviving -40°C to 175°C cycling. BYD and Hyundai Motor Group procurement validates thermal interface materials for 15-year vehicle lifespans.
- Aerospace:Satellite thermal control and avionics cooling demand outgassing-compliant formulations with extreme temperature stability. NASA and ESA qualification protocols extend development timelines substantially.
- Power Generation:Renewable inverter stations and grid-scale battery storage create demand for fire-resistant thermal management. Utility procurement emphasizes 25-year operational warranties over upfront material costs.
Specification maturity concentrates in Electronics. Accelerated qualification activity is expanding fastest in Automotive.
Application:
Functional role determines material form factor selection, with passive heat spreading solutions commanding lower margins than active cooling integration requiring system-level thermal design expertise.
- Heat Sinks:Aluminum and copper extrusions bonded with thermal interface layers remain the dominant thermal management architecture. Hyperscale cloud operators consolidate specifications across server generations to compress supplier qualification overhead.
- Thermal Pads:Compressible silicone or acrylic sheets fill irregular gaps between heat-generating components and heat spreaders. Thickness tolerance requirements below 0.1mm separate premium from commodity supply tiers.
- Cooling Solutions:Liquid cold plates and immersion cooling systems integrate thermal materials at fluid-interface boundaries. Microsoft and Google mandate single-source materials validated for five-year deployment horizons.
- Manage Heat Flow:Distributed thermal vias, heat pipes, and vapor chambers transport heat across complex geometries. Smartphone and laptop manufacturers drive miniaturization of these embedded thermal pathways.
Standardized procurement dominates Heat Sinks. Custom engineering intensity is climbing fastest in Cooling Solutions.
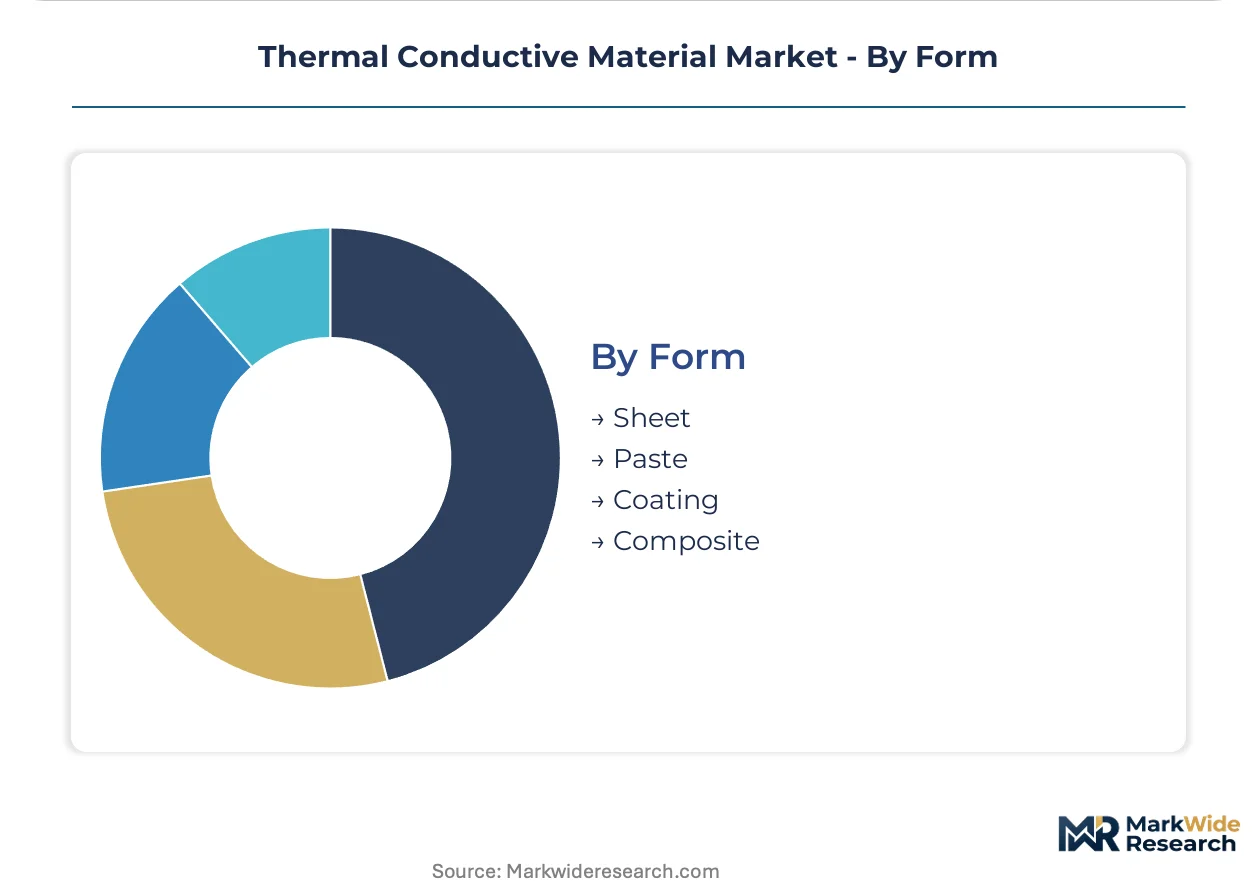
Form:
Manufacturing process compatibility and application automation requirements segment form factor selection, with sheet and paste formats serving high-volume electronics assembly while coatings and composites address specialized geometries.
- Sheet:Die-cut thermal pads and graphite sheets enable automated pick-and-place assembly in consumer electronics. Roll-to-roll processing achieves lowest per-unit costs at million-unit production scales.
- Paste:Screen-printable and dispensable formulations dominate semiconductor packaging. Sintered silver pastes are decentralizing thermal management to die-level attachment in automotive silicon carbide modules.
- Coating:Sprayable and dip-coated thermal layers conform to complex three-dimensional surfaces. REACH registration burdens for solvent-based formulations extend European time-to-market.
- Composite:Molded and machined thermal structures integrate conductive fillers with structural polymers. Electric vehicle battery modules drive demand for flame-retardant composite thermal barriers.
High-volume manufacturing favors Sheet. Performance-critical applications are migrating fastest toward Paste.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors thermal material procurement volumes, with Taiwan's packaging foundries validating formulations before global semiconductor adoption. Foundry concentration in East Asia creates specification-setting power that ripples through supplier relationships worldwide.
United States
Hyperscale cloud operators in Northern Virginia and Oregon drive demand for liquid metal and phase-change materials in AI accelerator servers. The EPA enforces volatile organic compound restrictions on solvent-based thermal coatings, raising compliance costs for domestic formulators. Austin and Phoenix semiconductor packaging facilities are expanding procurement of sintered silver pastes for advanced chiplet architectures.
China
Dual carbon goals and MEE discharge standards are tightening energy-efficiency requirements for data center thermal management systems. The country's control of global gallium refining creates supply leverage for liquid metal alloy production. Yangtze River Delta electronics manufacturing clusters in Suzhou and Shanghai are consolidating thermal interface material specifications across multiple foundry customers.
Germany
Automotive power module manufacturers in Bavaria and Baden-Württemberg are adopting sintered silver thermal materials for 800V silicon carbide inverters. The EU Green Deal tightens thermal management mandates for hyperscale data centers in Frankfurt and Berlin. ECHA's REACH registration process extends time-to-market for boron nitride nanoparticle formulations by 18-24 months.
South Korea
Samsung Foundry and SK Hynix are driving thermal interface material specifications upward as chip power densities exceed 500 watts per package. The country's national industrial policy supports domestic thermal material suppliers through packaging ecosystem investments. Pyeongtaek and Hwaseong semiconductor complexes validate new formulations before global rollout to memory and logic customers.
Japan
Automotive suppliers in Aichi Prefecture and Kansai region demand thermal materials surviving 10,000+ temperature cycles for silicon carbide power modules. METI energy-efficiency standards pressure data center operators toward high-conductivity interface materials. Tokyo and Osaka packaging houses are qualifying graphene-synthetic graphite hybrids for next-generation mobile device thermal management.
Thermal Conductive Material Market Key Industry Players
Premium-margin players sit above commodity-margin players across thermal conductivity thresholds and reliability certification tiers. The market structure fragments between silicone chemistry specialists, adhesive-thermal hybrid formulators, and engineered polymer compounders. Three archetypes dominate: diversified chemical conglomerates leveraging platform chemistry, mid-cap adhesive specialists occupying automotive niches, and materials science innovators commercializing carbon allotrope formulations. Competitive moves concentrate on backward integration into specialty filler supply and strategic partnerships with semiconductor foundries for co-development validation.
Among diversified chemical conglomerates, 3M Company and Dow Inc. exemplify platform-chemistry players anchoring supply relationships through silicone and fluoropolymer expertise. Henkel AG & Co. KGaA occupies a position within the adhesive-thermal hybrid tier, representing specialists that bridge mechanical bonding and thermal management functions. SABIC sits within the engineered materials archetype, with its polymer compound expertise sustaining performance across extended temperature cycling demands. These three players illustrate how geographic origin and corporate structure map to competitive positioning: Minnesota-based 3M and Michigan-based Dow represent North American diversified chemistry, Düsseldorf-headquartered Henkel exemplifies European adhesive specialization, and Riyadh-controlled SABIC represents Middle Eastern petrochemical-backed materials science.
| Leading Market Players |
|---|
| 3M Company |
| Dow Inc. |
| Henkel AG & Co. KGaA |
| Honeywell International Inc. |
| Celanese Corporation |
| SABIC |
| DuPont |
| Covestro AG |
| DSM |
| Others |
Cost & Logistics Intelligence
Backward integration into specialty filler production anchors competitive positioning for thermal material formulators, with captive boron nitride and synthetic graphite operations insulating margin structures from raw material volatility while commanding premium pricing from semiconductor foundries.
Pricing Analysis
Value-based pricing anchored to thermal resistance reduction outcomes dominates premium tiers, with liquid metal formulations commanding substantial premiums based on watts-per-square-centimeter thermal flux performance. Three-tier pricing structure across premium, standard, and economy levels separates JEDEC-qualified automotive grades from consumer electronics commodity pastes. Cost compression in silicone-based gap fillers is intensifying because Chinese MEE discharge standards raise manufacturing compliance burdens. Automotive power module manufacturers exhibit lowest price sensitivity, prioritizing 10,000-cycle reliability certification over per-unit material costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Microsoft and Google, while distribution partners serve fragmented electronics assembly houses across Taiwan and South Korea. Raw material sourcing draws from China's gallium refining concentration, Japan's synthetic graphite production, and Germany's engineered polymer expertise. Single-source vulnerability concentrates in gallium supply chains, with China's export restriction authority exposing Western liquid metal producers to supply disruption. Distribution runs through semiconductor packaging foundries that validate formulations before global tier-one adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing captive control over boron nitride nanoparticle synthesis to secure formulation consistency and pricing power.
For Market Incumbents: Deepen backward integration into specialty filler production to defend margin position against emerging graphene-synthetic graphite hybrid suppliers. Secure long-term offtake agreements with Taiwan packaging foundries before India's PLI scheme matures competing demand clusters. Prioritize JEDEC automotive qualification investments to maintain tier-one status as silicon carbide power module specifications tighten. For New Entrants and Emerging Players: Direct-to-OEM digital sales channels bypass established distribution relationships in India's Gujarat and Karnataka semiconductor packaging corridors. Target automotive aftermarket thermal retrofit applications where legacy paste removal protocols create service revenue attachment opportunities. Lead with graphene-synthetic graphite formulations that align with China's MEE discharge standards to differentiate from carbon-intensive incumbent supply chains. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified chemical conglomerates seeking thermal management platform expansion. Five-to-ten-year viability favors formulators with validated reliability databases spanning multiple semiconductor foundry relationships. Monitor gallium export restriction announcements as inflection indicators for liquid metal supply chain restructuring and alternative formulation R&D acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Fillers | Captive boron nitride production insulates margin structures from Chinese supply volatility. |
| JEDEC Automotive Qualification Investment | 15-year reliability certification unlocks silicon carbide power module procurement from BYD and Hyundai. |
| Long-term Foundry Partnership Agreement | TSMC and Samsung co-development validation accelerates global specification adoption. |
| Graphene-Synthetic Graphite Formulation Launch | Lower-carbon production methods align with EU Green Deal and China's MEE discharge standards. |
| India PLI Scheme Manufacturing Footprint | Gujarat and Karnataka packaging facilities create localized supply without established incumbent relationships. |
Research Approach
Multi-period observation of thermal conductivity specification trajectories and foundry procurement volumes anchored the trend analysis, supplemented by interviews with semiconductor packaging engineers, automotive power module procurement leads, thermal material R&D directors, and hyperscale data center infrastructure planners. Secondary validation drew from EPA volatile organic compound enforcement records, ECHA REACH registration databases, China's MEE discharge standard filings, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up formulation demand modeling and top-down electronics manufacturing output estimates were triangulated to cross-check segment projections.
Segment-weighting across product type, end-user industry, application function, and geographic manufacturing cluster shaped the analytical framework throughout the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating chip power density trajectories above 500 watts per package and automotive 800V inverter adoption curves. Industry-specific forecast inputs included JEDEC thermal cycling test duration requirements and gallium supply concentration risk adjustments.
The model holds under stable semiconductor capital expenditure and gallium trade flow conditions; deviation in export restriction severity or foundry buildout pace would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Global Core Materials Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Curable Materials Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
2D Materials Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Global High Performance Thermoplastics Market