
 2D Materials Market | 2026-2036
2D Materials Market Size, Share, and Industry Trends Forecast 2026-2036
2D Materials Market Intelligence
The shift from pure research applications toward industrial-scale use in electronics and energy storage is realigning the market's commercial focus. Graphenea specializes in high-purity graphene production for advanced electronics research. Sixth Element Materials leverages its scale to supply bulk graphene oxide for industrial composites. Haydale Graphene Industries differentiates through its plasma functionalization technology, tailoring materials for specific end-user requirements.
2D materials are crystalline solids consisting of a single layer of atoms. These materials, such as graphene with its unique hexagonal lattice structure, exhibit extraordinary electronic, thermal, and mechanical properties at the nanoscale. Graphene remains the dominant material type due to extensive research, but transition metal dichalcogenides (TMDCs) represent the fastest-growing segment for optoelectronics. Production methods are bifurcated, with Chemical Vapor Deposition (CVD) favored for high-quality electronics and liquid phase exfoliation used for bulk composite applications.
The commercialization path for 2D materials is governed by chemical substance regulations like the EU's REACH and the US EPA's TSCA framework. These bodies require extensive toxicological data before approving new materials for industrial use, influencing development timelines and costs. Future market penetration depends on the industry's ability to establish standardized characterization protocols under frameworks like ISO/IEC to ensure material consistency and quality for mass production.
Market Dynamics
The central dynamic shaping the 2D materials market is the bifurcation of production technologies. High-purity, electronics-grade materials rely on capital-intensive Chemical Vapor Deposition (CVD), while industrial composites utilize lower-cost liquid phase exfoliation, creating distinct value chains.
Growth Catalysts
- Next-Generation Electronics:Demand from manufacturers in China and South Korea for flexible displays, high-speed transistors, and transparent conductive films provides a primary commercial pull for high-quality graphene and TMDCs.
- Energy Storage Advancements:The use of graphene as a conductive additive in lithium-ion battery electrodes and supercapacitors enhances charging speeds and cycle life, aligning with electrification initiatives in the automotive and grid storage sectors.
- TMDC Optoelectronics:Transition metal dichalcogenides represent the fastest-growing material segment, driven by unique light-emitting properties essential for developing next-generation photodetectors, LEDs, and valleytronics devices.
Market Restraints
- Production Scalability and Cost:Achieving large-area, defect-free monolayer films via Chemical Vapor Deposition remains technically challenging and expensive, limiting economic viability for many mass-market electronics applications beyond high-end niches.
- Regulatory Hurdles:Chemical registration frameworks, including the EU's REACH and the US EPA's TSCA, require extensive and costly toxicological data before new 2D materials can be approved for industrial use, delaying commercialization.
- Lack of Standardization:The absence of globally accepted ISO or IEC protocols for material characterization creates inconsistency in quality and performance, eroding buyer confidence and complicating supply chain management for mass production.
Strategic Opportunities
- Functionalization Services:Offering tailored surface functionalization of 2D materials, such as through plasma treatment, creates high-margin opportunities by tuning material properties for specific end-user applications in composites, coatings, and inks.
- Biomedical Applications:High surface area and unique electronic properties make 2D materials ideal for developing ultra-sensitive biosensors for disease diagnostics and targeted drug delivery systems, representing a high-value niche market.
- Standardized Industrial Grades:Developing and marketing certified material grades for specific industries like aerospace or automotive composites can build trust and streamline adoption by guaranteeing performance specifications for safety-critical applications.
Industry Challenges
- Semiconductor Integration:Integrating atomically thin materials into existing silicon-based CMOS fabrication workflows without introducing contamination or structural defects presents a significant technical hurdle for semiconductor manufacturers.
- Quality Control Consistency:Ensuring batch-to-batch reproducibility of material properties like flake size, layer count, and purity is a major operational challenge, particularly when sourcing from multiple suppliers using different production methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2D Materials Market |
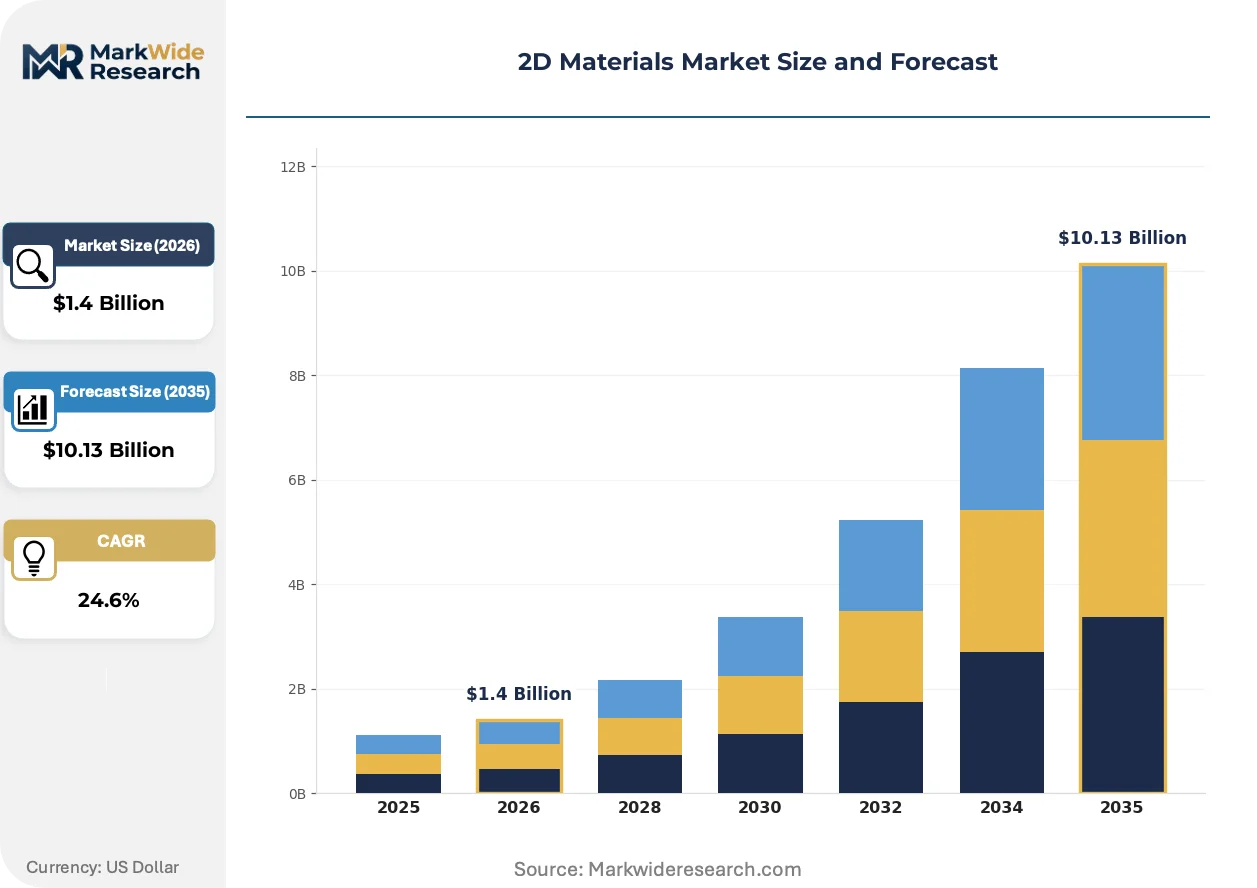
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $10.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphene, Transition Metal Dichalcogenides, Hexagonal Boron Nitride, Black Phosphorus, Silicene Application: Electronics, Energy Storage, Sensors, Catalysis, Photonics Production Method: Chemical Vapor Deposition, Mechanical Exfoliation, Liquid Phase Exfoliation, Molecular Beam Epitaxy, Chemical Synthesis End User Industry: Semiconductor Firms, Energy Companies, Research Institutes, Chemical Manufacturers, Electronics Manufacturers |
| Companies Covered | Thomas Swan & Co, XG Sciences, Graphenea, Sixth Element Materials, Haydale Graphene Industries, NanoXplore, Versarien, 2D Semiconductors, ACS Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2D Materials Market Strategic Shifts & Innovations
The market's evolution is defined by the push to translate laboratory breakthroughs into industrial-scale, economically viable products. This transition hinges on process innovations that improve material consistency and lower the cost of integration into existing manufacturing systems.
Plasma Functionalization Gains Traction in Composites
Plasma functionalization is a process that modifies the surface chemistry of 2D materials to enhance their compatibility with host matrices. Manufacturers of industrial composites for the aerospace and automotive sectors are adopting this technology to improve stress transfer and bonding. This targeted modification is absorbing the performance variability inherent in bulk graphene and graphene oxide, creating more reliable and predictable industrial additives.
REACH Compliance Shapes Market Entry Strategy
The European Union's REACH regulation governs the registration of all chemical substances, including novel 2D materials. Its framework mandates the submission of extensive toxicological and ecotoxicological data to the European Chemicals Agency (ECHA) prior to commercial sale. This requirement forces material developers to invest heavily in safety testing, often leading them to form consortia to share the high costs of data generation for market access.
Demand Shifts to Application-Specific Formulations
End-users are moving away from purchasing raw 2D material powders and toward procuring application-ready formulations. This shift disrupts the traditional commodity supply model, favoring suppliers who can deliver pre-dispersed inks, functionalized polymer masterbatches, or conductive films. The trend is most prominent in the electronics manufacturing hubs of South Korea and Taiwan, where device makers require drop-in solutions that integrate seamlessly with established production lines.
2D Materials Market Segmentation
Understanding the 2D materials market requires a granular view of its diverse segments, each presenting unique technological demands and commercial opportunities. This detailed segmentation analysis illuminates the various material compositions, application areas, manufacturing processes, and end-user industries driving market evolution. Differentiation across these categories is critical for strategic market positioning.
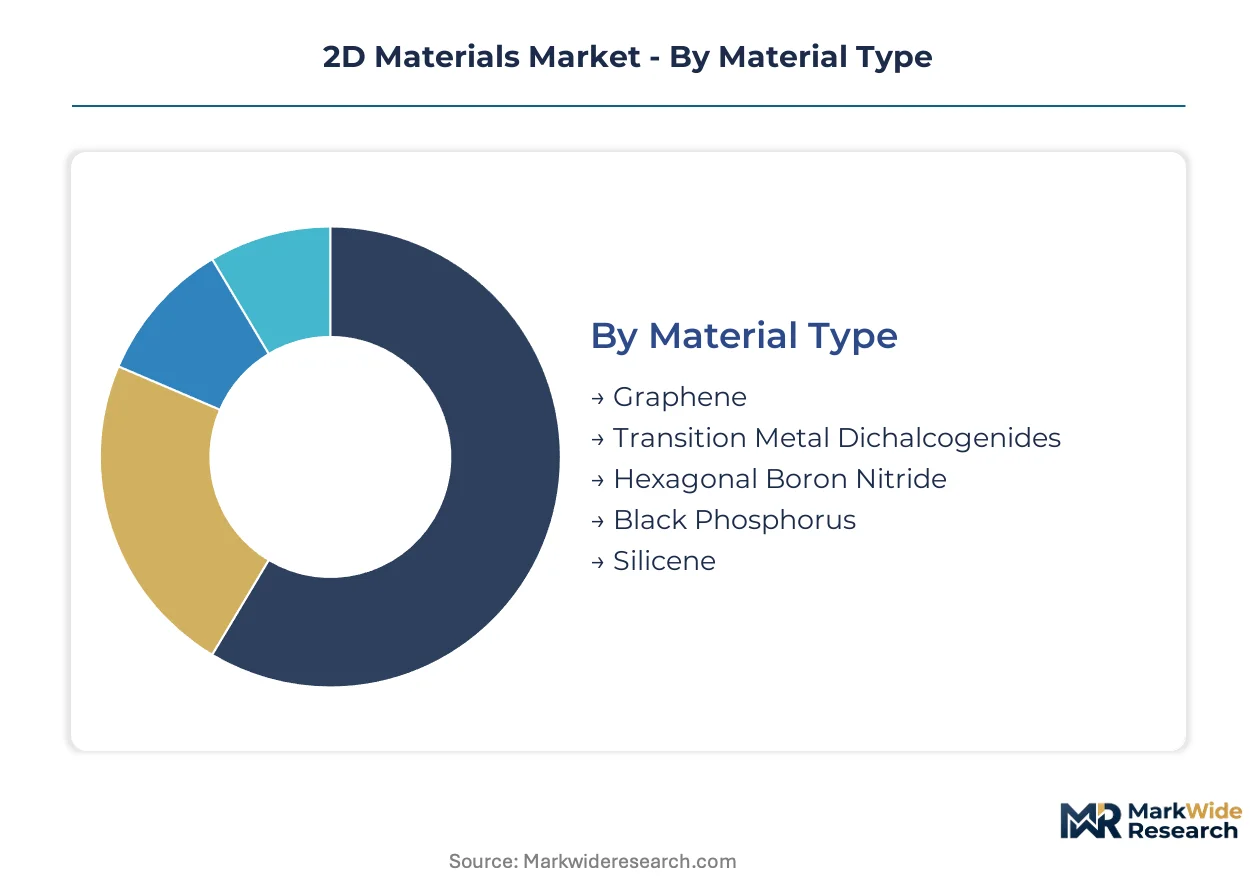
Material Type:
The array of 2D material types spans a spectrum from highly standardized bulk materials to highly customized, research-grade specialties, each requiring distinct production and characterization protocols.
- Graphene:This carbon allotrope, a single layer of atoms in a hexagonal lattice, offers exceptional electrical and thermal conductivity. Demand concentrates in China and South Korea for flexible display components and high-speed transistor development.
- Transition Metal Dichalcogenides:TMDCs comprise a metal atom layer between two chalcogen atom layers, exhibiting tunable band gaps for optoelectronic devices. Their unique light-matter interaction drives demand in emerging photodetector and LED applications within European R&D centers.
- Hexagonal Boron Nitride:Known as 'white graphene,' hBN provides an excellent dielectric substrate for high-frequency electronics.
- Black Phosphorus:This material offers a direct, tunable band gap, attractive for infrared photodetectors and next-gen field-effect transistors.
- Silicene:A 2D allotrope of silicon, silicene holds promise for integration with existing silicon-based semiconductor technology.
Leading the category by volume: Graphene. Growing fastest: Transition Metal Dichalcogenides.
Application:
Application segments reflect varying cost tolerances and performance requirements, from high-value, performance-critical electronics to cost-sensitive industrial additives.
- Electronics:This segment encompasses flexible displays, high-frequency transistors, and transparent conductive films, leveraging 2D materials' superior electrical properties. Manufacturers in South Korea and Taiwan drive demand for high-purity graphene and TMDCs in advanced device fabrication.
- Energy Storage:2D materials enhance lithium-ion batteries and supercapacitors by improving electrode conductivity and ion transport, extending cycle life. Automotive and grid storage sectors in Germany and Japan integrate graphene as a performance additive for electrification.
- Sensors:High surface area and unique electronic properties enable ultra-sensitive biosensors and environmental monitoring devices.
- Catalysis:2D materials offer enhanced catalytic activity and selectivity due to high surface-to-volume ratio in chemical production.
- Photonics:This segment utilizes optical properties of 2D materials for light emission, detection, and modulation in communication systems.
The largest volume of 2D materials flows into Electronics, while Energy Storage demonstrates the steepest expansion trajectory.
Production Method:
Production methods demonstrate varying degrees of supply chain concentration, ranging from highly specialized, capital-intensive processes to more distributed, bulk manufacturing techniques.
- Chemical Vapor Deposition:CVD produces high-quality, large-area monolayer films by depositing gaseous precursors onto a substrate, essential for advanced electronics. Research and manufacturing hubs in the US and Germany invest heavily in CVD for semiconductor integration and flexible displays.
- Liquid Phase Exfoliation:This method disperses bulk layered materials in a solvent, producing flakes suitable for composite additives and conductive inks due to its scalability. Industrial chemical manufacturers in India and Brazil adopt LPE for cost-effective, high-volume graphene oxide production.
- Mechanical Exfoliation:A laboratory-scale technique, yielding high-purity, defect-free flakes for fundamental research in academic settings.
- Molecular Beam Epitaxy:MBE enables precise layer-by-layer growth of ultra-high purity films under vacuum, critical for quantum computing research.
- Chemical Synthesis:Various chemical routes produce different 2D materials, often used for specific functionalization or composite integration.
The dominant method for high-volume production is Liquid Phase Exfoliation, with Chemical Vapor Deposition showing significant growth in specialized electronics niches.
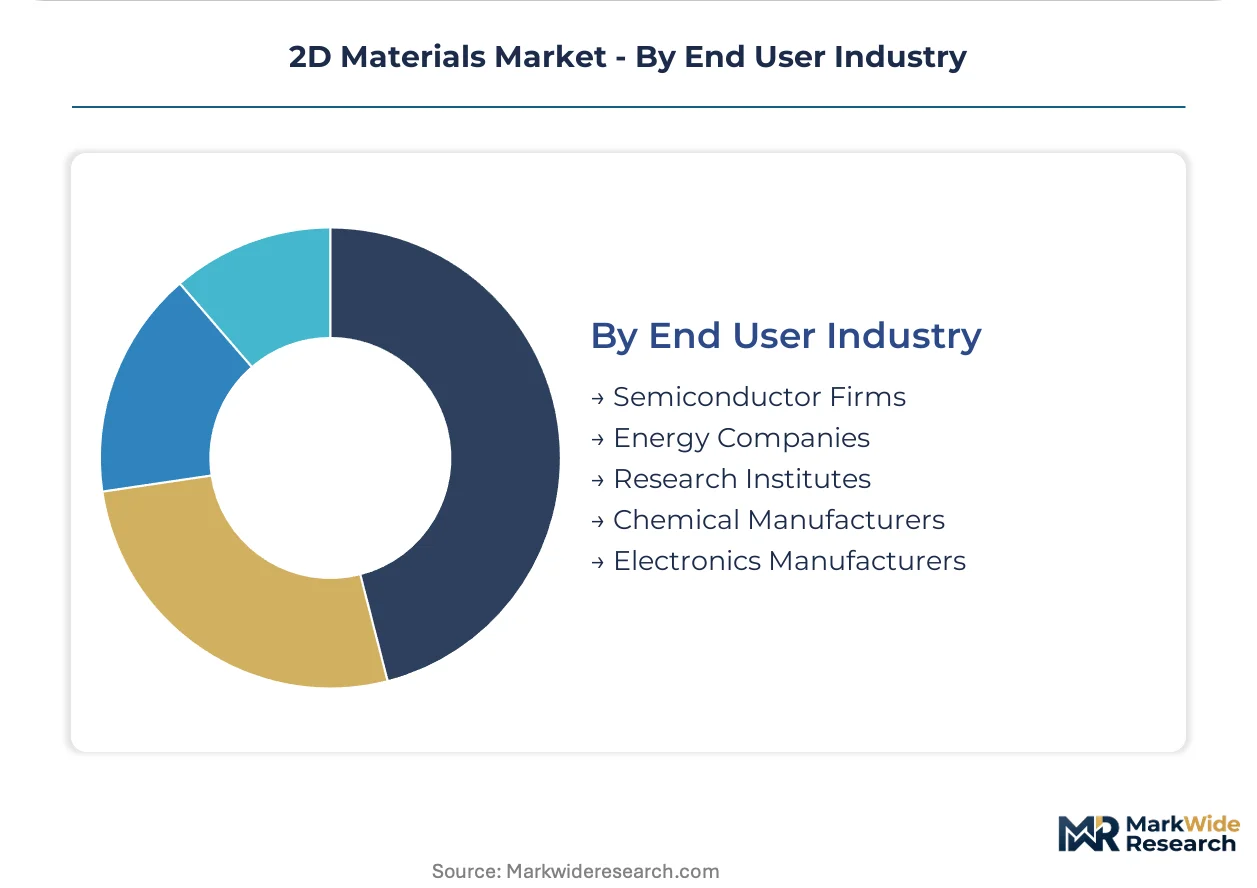
End User Industry:
End-user industries are distinguished by their specific technical demands and regulatory environments, influencing material specifications and required certifications.
- Semiconductor Firms:These companies integrate 2D materials into next-generation chips, transistors, and memory devices, requiring ultra-high purity and precise integration. Players in Taiwan and the US drive demand for defect-free monolayer films for advanced CMOS compatibility.
- Electronics Manufacturers:This segment utilizes 2D materials for flexible displays, transparent electrodes, and thermal management solutions in consumer electronics. Manufacturers in South Korea and Japan seek application-ready formulations and conductive inks for seamless integration.
- Energy Companies:These firms deploy 2D materials in battery electrodes, supercapacitors, and fuel cells for enhanced performance.
- Research Institutes:Academic and government laboratories conduct fundamental studies and prototype development for novel 2D applications.
- Chemical Manufacturers:These companies incorporate 2D materials as additives in polymers, coatings, and catalysts for improved properties.
The largest consumer base resides within Electronics Manufacturers, while Semiconductor Firms are rapidly expanding their material procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen Special Economic Zone in China drives significant concentration in the 2D materials market, particularly for advanced electronics manufacturing. This region, along with other global innovation hubs, leverages strategic investments and technological advancements to foster material development and application. Regional market dynamics are shaped by varying regulatory landscapes, industrial priorities, and technological readiness across key geographies.
China
Manufacturers in China drive substantial demand for flexible displays and high-speed transistors, utilizing high-quality graphene and TMDCs. The country's dual carbon goals incentivize the integration of 2D materials into energy storage solutions for electric vehicles. The Yangtze River Delta region, including cities like Shanghai and Nanjing, serves as a major hub for advanced electronics manufacturing and material innovation.
South Korea
Advanced device fabrication and flexible display technologies in South Korea create a strong pull for high-purity 2D materials. Government initiatives support R&D in next-generation semiconductors and display technologies, encouraging material innovation. The Seoul Capital Area, with its dense concentration of electronics manufacturers and research institutions, leads in integrating 2D materials into consumer devices.
United States
Semiconductor firms in the United States require ultra-high purity 2D materials for integrating into next-generation chips and quantum computing research. The US EPA's TSCA framework influences development timelines, requiring extensive toxicological data for new material approval. Silicon Valley, California, remains a primary hub for semiconductor innovation and advanced material research.
Germany
Germany's automotive industry drives demand for 2D materials as conductive additives in lithium-ion batteries and supercapacitors for electrification initiatives. European REACH regulations mandate comprehensive safety testing, impacting market entry strategies for novel materials. Bavaria, particularly Munich and Dresden, hosts significant automotive R&D centers and materials science institutes.
Japan
Electronics manufacturers in Japan seek application-ready formulations of 2D materials for transparent electrodes and thermal management solutions. The Ministry of Economy, Trade and Industry (METI) supports advanced materials research and industrial applications. The Kansai region, including Osaka and Kyoto, is a key area for electronics manufacturing and energy storage technology development.
2D Materials Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. The market exhibits a clear differentiation between high-purity material providers targeting niche electronics and bulk suppliers focusing on industrial composites. Strategic archetypes include specialized material developers, bulk producers, and functionalization service providers. Dominant competitive moves involve capacity expansion for bulk materials and technology licensing for specialized applications.
Specialists in high-purity materials, such as Graphenea, exemplify the focus on advanced electronics research and development. Sixth Element Materials occupies a position among bulk graphene oxide suppliers, catering to industrial composite applications due to its scale. Haydale Graphene Industries, with its plasma functionalization technology, represents providers tailoring materials for specific end-user requirements, creating high-margin opportunities.
| Leading Market Players |
|---|
| Thomas Swan & Co |
| XG Sciences |
| Graphenea |
| Sixth Element Materials |
| Haydale Graphene Industries |
| NanoXplore |
| Versarien |
| 2D Semiconductors |
| ACS Material |
| Others |
Cost & Logistics Intelligence
Chemical Vapor Deposition (CVD) advancements are reshaping cost economics for high-purity 2D materials, simultaneously concentrating supply in specialized manufacturing hubs. This transition impacts pricing power as demand for next-generation electronics intensifies.
Pricing Analysis
Lead-time-driven pricing dominates the high-purity 2D materials market, where advanced electronics manufacturers pay a premium for rapid delivery of defect-free films. The primary pricing model is per-unit transactional, heavily influenced by quality grade and certification level, such as ISO/IEC compliance. Pricing softness affects bulk graphene oxide due to increased Liquid Phase Exfoliation capacity. Semiconductor firms exhibit the lowest price sensitivity for ultra-high purity materials, while industrial composite manufacturers are most sensitive to cost.
Supply Chain Analysis
Workforce availability and specialized expertise in China and South Korea anchor the global supply concentration for advanced 2D materials production. The supply chain relies heavily on precursor chemicals like methane and metal halides, along with high-purity graphite for graphene production. Single-source vulnerability for rare TMDC precursors presents a structural risk. Downstream distribution runs through specialized material distributors and direct sales channels to large electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 2D materials market is largely supply-constrained, particularly for high-quality, defect-free monolayer films. Limited large-scale Chemical Vapor Deposition (CVD) capacity props pricing for advanced electronics applications.
For Market Incumbents: Deploy strategic partnerships with semiconductor firms to co-develop integration solutions, mitigating the threat of silicon-based CMOS workflow incompatibility. Consolidate smaller material producers to gain intellectual property and scale for bulk graphene oxide, addressing margin pressure from increased competition in industrial composites. Expand certification investment under ISO/IEC protocols to ensure consistent material quality.
For New Entrants and Emerging Players: Capture niche opportunities in biomedical applications by developing ultra-sensitive biosensors for disease diagnostics. Target the rapidly expanding TMDC optoelectronics segment within European R&D centers, focusing on specialized photodetectors. The most penetrable segment remains application-specific formulations for device makers in Taiwan. A direct sales model, emphasizing technical support and rapid prototyping for specific end-user requirements, provides a viable go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized material functionalization providers given the increasing demand for application-ready formulations. Long-term viability favors companies with established regulatory compliance pathways under REACH and TSCA frameworks. Target acquisition archetypes include vertically integrated developers possessing proprietary CVD technology for high-purity electronics. The signal to watch is widespread adoption of standardized characterization protocols, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for CVD Films | Addresses the bottleneck in high-purity, large-area 2D material production for advanced electronics. |
| Investment in Plasma Functionalization | Enhances material compatibility and performance for industrial composites in automotive and aerospace sectors. |
| Consortia for Regulatory Compliance | Shares the high cost of toxicological data generation required by EU REACH and US EPA TSCA frameworks. |
| Development of Application-Ready Formulations | Meets demand from electronics manufacturers in South Korea and Taiwan for seamless integration into production lines. |
| Standardization of Material Characterization | Builds buyer confidence and streamlines supply chain management for mass production across industries. |
Research Approach
Document review covered academic journals, patent filings, and regulatory submissions to ECHA and EPA, complemented by interviews with industry experts. We engaged R&D directors, procurement leads from semiconductor firms, material scientists, and regulatory affairs specialists. This approach combined primary insights with secondary validation, utilizing both bottom-up and top-down triangulation for robust data synthesis.
Historical market data was cross-referenced against expert panel input to construct the forecast framework. We modeled segmentation across material type, application, production method, and end-user industry, including regional regulatory compliance. Compound Annual Growth Rates were derived through regression analysis of historical trends and projected technological adoption rates across the analysis window. Key inputs included R&D spending in optoelectronics and capital expenditure for CVD equipment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and breakthrough production methods. These forecasts reflect documented assumptions regarding commercialization timelines and material cost reductions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Cathode Active Material Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Global Graphene Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Europe Graphene Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Advanced Polymer Composites Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Global Diamond-Like Carbon (DLC) Market