
 Graphite Materials Market | 2026-2036
Graphite Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Graphite Materials Market Foresight
The widening purity gap between battery-grade synthetic graphite and industrial amorphous material is repositioning procurement hierarchies across the value chain. SGL Carbon leverages captive needle coke supply and vertical integration into specialty electrodes to sustain margin capture in premium tiers. GrafTech International anchors its position through manufacturing scale and long-term graphite electrode supply agreements with steel producers. Resonac Holdings Corporation differentiates via advanced carbon material R&D spanning semiconductor and energy storage applications.
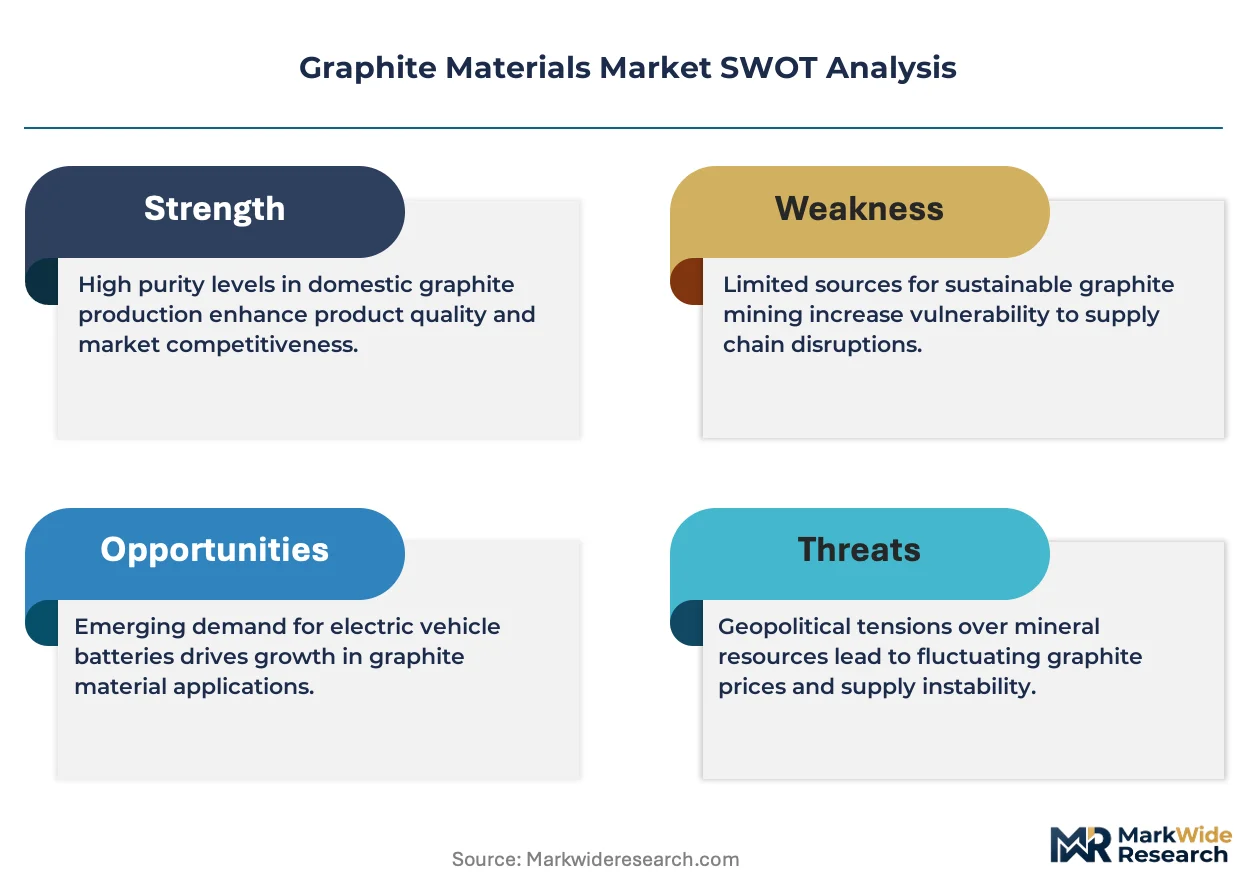
Graphite materials encompass crystalline and non-crystalline carbon allotropes with layered hexagonal atomic structure, typically processed to purities exceeding 99.95% for battery anodes through thermal treatment and chemical leaching sequences. Synthetic graphite dominates volume allocation for lithium-ion battery anodes where intercalation capacity and cycle stability prove critical, while natural graphite retains cost advantages in refractory linings for steelmaking furnaces. The high purity grade segment commands disproportionate margin pools as energy storage end users impose stricter impurity thresholds on suppliers. Expanded graphite occupies a specialized niche in thermal management composites for electronics and aerospace fireproofing systems.
China's SAMR enforces GB standards for graphite product classification and export licensing, directly constraining supply availability for international battery manufacturers. The EU Battery Regulation mandates supply chain due diligence and recycled content thresholds that reshape qualification requirements for graphite entering European cell production. EPA oversight in the United States governs emissions from graphite purification facilities, elevating compliance costs for domestic synthetic production. Stakeholders must monitor evolving carbon border adjustment mechanisms and purity certification protocols to secure qualified supply positions.
Market Dynamics
The battery-grade purity threshold is compressing supplier margins while concentrating procurement authority among integrated anode material producers. China's export licensing regime and the EU Battery Regulation's carbon footprint rules are forcing qualification system overhauls across the value chain.
Growth Catalysts
- EU Battery Regulation mandates:Carbon footprint disclosure and recycled content thresholds are reshaping supplier qualification criteria for graphite entering European cell production facilities.
- Electric vehicle anode demand:Battery manufacturers are expanding synthetic graphite procurement to meet production schedules for lithium-ion cell assembly lines.
- Shandong-Fujian corridor concentration:China's integrated anode material production clusters are capturing disproportionate volume allocation through captive needle coke-to-anode supply chains.
Market Restraints
- Needle coke supply concentration:Petroleum needle coke feedstock availability constrains synthetic graphite expansion, with supply controlled by limited refinery upgrade capacity.
- EPA emissions compliance:Purification facility oversight in the United States elevates domestic production costs relative to Chinese thermal treatment operations.
- SAMR export licensing:China's State Administration for Market Regulation constrains international availability through GB standard enforcement and controlled export quotas.
Strategic Opportunities
- Semiconductor thermal management:Advanced carbon material R&D is opening specialty graphite applications in chip packaging and heat spreader substrates.
- Recycled content mandates:The EU Battery Regulation's due diligence requirements create first-mover advantage for suppliers with verified circular material flows.
- Carbon border adjustment positioning:Early compliance with emerging carbon border mechanisms secures qualified supply positions for European automotive cell producers.
Industry Challenges
- Purification capex intensity:Achieving 99.95% battery-grade purity requires thermal treatment and chemical leaching sequences with substantial facility investment requirements.
- Impurity threshold certification:Energy storage end users are imposing stricter qualification timelines, compressing supplier onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphite Materials Market |
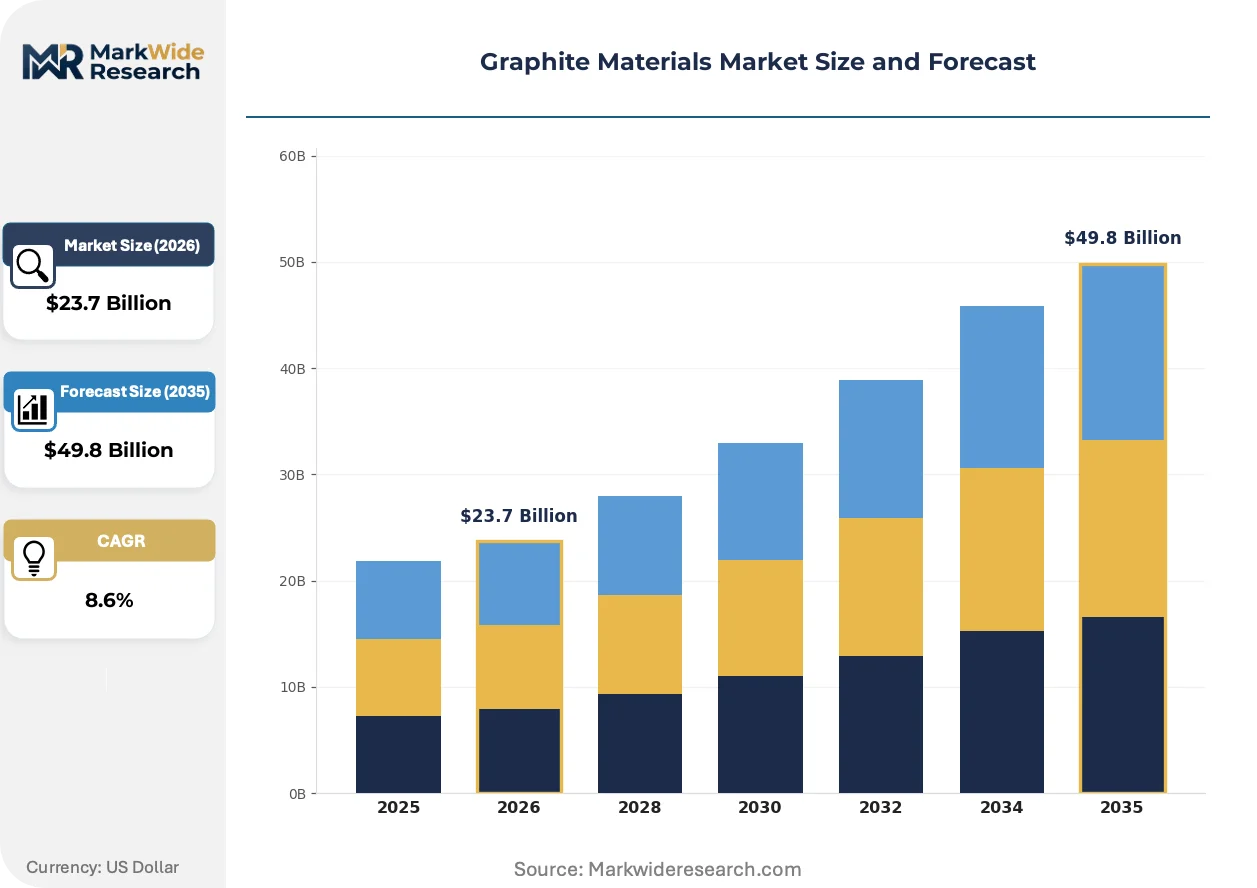
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Graphite, Synthetic Graphite, Expanded Graphite, Amorphous Graphite Application: Batteries, Refractories, Lubricants, Composites Grade: High Purity, Medium Purity, Low Purity, Industrial Grade End User: Aerospace, Automotive Components, Electronics, Energy Storage |
| Companies Covered | Shanshan Co., Resonac Holdings Corporation, SGL Carbon, GrafTech International, BTR New Material Group Co., Ltd., Imerys, Asbury Carbons, Tokai Carbon Co., Ltd., Syrah Resources Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphite Materials Market Shifts & Advancements
Synthetic graphite processing is undergoing purification capability expansion while regulatory compliance systems are embedding carbon accounting directly into procurement workflows.
Spheronization and surface coating technologies for synthetic graphite anodes are electrifying the competitive landscape. Battery cell manufacturers are adopting these processed materials at accelerating rates to achieve intercalation capacity targets. The technology is electrifying margin capture toward producers with captive coating capabilities and away from unprocessed material traders.
The EU Battery Regulation's supply chain due diligence mandates are restructuring qualification protocols. Cell producers must now document carbon intensity and recycled content across upstream tiers. European automotive OEMs and their cell suppliers are most affected, driving accelerated supplier audits and contract renegotiations.
Direct contracting between battery manufacturers and graphite processors is displacing merchant market transactions. Tier-one cell producers are securing multi-year offtake agreements with anode material specialists, bypassing traditional distributors. This pattern concentrates most visibly in China's integrated production corridors and among Korean cell manufacturers securing qualified supply.
Graphite Materials Market Segmentation
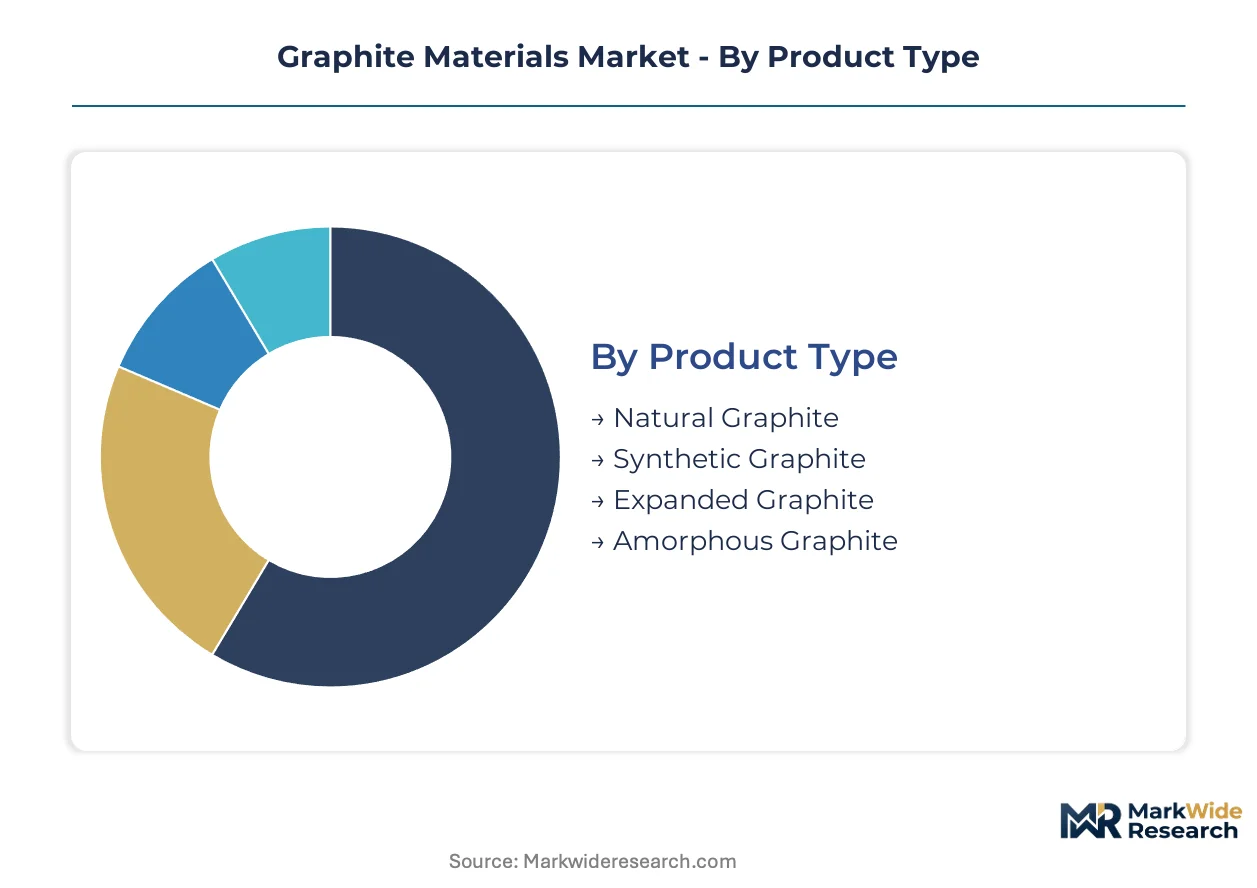
Purity thresholds and integration depth determine margin capture across graphite material categories. Battery-grade specifications compress supplier economics while industrial applications sustain volume throughput.
Product Type:
Integration depth varies sharply — synthetic graphite demands full vertical processing chains while natural material reaches end-users through simpler beneficiation routes.
- Synthetic Graphite:Petroleum needle coke feedstock undergoes graphitization at temperatures exceeding 2800°C to achieve crystalline structure. Battery manufacturers in China's Shandong-Fujian corridors consume the majority of high-purity output for lithium-ion anodes, constrained by EPA emissions compliance in alternative supply geographies.
- Natural Graphite:Flake and vein deposits require mechanical concentration and thermal purification to reach battery-grade thresholds. Mozambique and Madagascar operations feed refractory and lubricant demand, though spherical processing investments are redirecting volumes toward energy storage applications.
- Expanded Graphite:Intercalation compounds exfoliate under thermal shock to produce worm-like structures for fireproofing and thermal interface materials.
- Amorphous Graphite:Microcrystalline deposits serve foundry coatings and brake linings where crystalline perfection offers no performance advantage.
Synthetic graphite leads volumes today; expanded graphite is gaining share fastest in thermal management applications.
Application:
Cost tier separation runs from premium battery anodes through commodity refractory linings.
- Batteries:Lithium-ion cell anodes demand 99.95% purity with tightly controlled particle size distribution and surface area specifications. Korean and Chinese cell manufacturers specify spheronized and coated synthetic material, disqualifying unprocessed feedstock from merchant markets.
- Refractories:Steelmaking furnace linings and crucibles consume large-flake natural graphite where thermal shock resistance outweighs purity requirements. Magnesia-carbon brick formulations in electric arc furnaces anchor steady demand despite cyclical steel production.
- Lubricants:Colloidal graphite suspensions and dry film coatings serve high-temperature and vacuum environments where hydrocarbon lubricants fail.
- Composites:Polymer-matrix formulations incorporate graphite for electrical conductivity and electromagnetic shielding in automotive and electronics housings.
Battery applications command the steepest price premiums; refractories provide the most stable demand baseline through steel cycle volatility.
Grade:
Customer type stratification separates qualified battery suppliers from industrial commodity traders.
- High Purity:Thermal treatment and chemical leaching sequences remove sulfur, ash, and metallic impurities below 500 ppm thresholds. EU Battery Regulation carbon footprint disclosure requirements now overlay technical specifications, filtering supplier pools for European automotive cell producers.
- Medium Purity:Partial purification serves aluminum smelting electrodes and specialty carbon products where moderate conductivity suffices.
- Low Purity:Basic beneficiation meets foundry and friction material specifications without thermal upgrading investment.
- Industrial Grade:Run-of-mine or minimally processed material fills lowest-value applications with minimal quality assurance overhead.
High purity dominates revenue concentration; medium purity is expanding most quickly as aluminum sector demand firms.
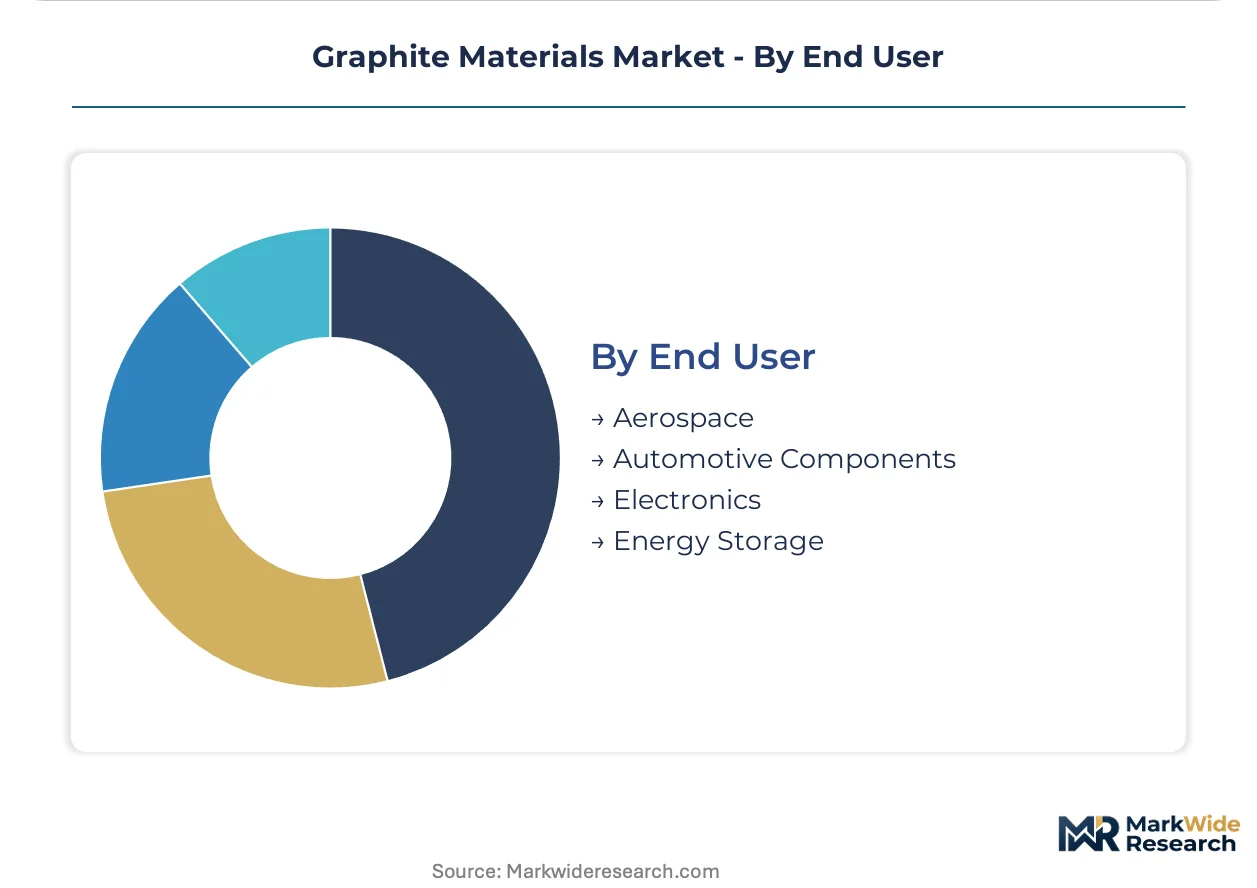
End User:
Maturity differentiation separates established aerospace procurement from emerging energy storage qualification cycles.
- Energy Storage:Grid-scale battery installations and electric vehicle production lines drive the most aggressive procurement expansion. Cell manufacturers impose 18-24 month qualification timelines that freeze out unproven suppliers regardless of price positioning.
- Automotive Components:Brake linings, gaskets, and seals consume consistent graphite volumes with long-term supply agreements and limited specification evolution.
- Electronics:Thermal interface materials and semiconductor processing equipment utilize specialty graphite grades with exacting purity and dimensional stability requirements.
- Aerospace:Fireproofing composites and ablative heat shields demand certified material traceability through extended supply chains.
Automotive components lead established volumes; energy storage is climbing the fastest as gigafactory construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in carbon material processing and battery chemistry concentrate in coastal Chinese provinces, Germany's industrial belt, and the US Great Lakes region, anchoring graphite purification and anode manufacturing capacity.
China
Shandong and Fujian provinces host integrated needle coke-to-anode production corridors supplying Korean and domestic cell manufacturers. SAMR enforces GB standards and export licensing that constrains international availability of battery-grade material. Qingdao and Xiamen processing clusters are expanding spheronization capacity to capture premium pricing from qualified automotive supply chains.
United States
Great Lakes region refineries and Ohio Valley processing facilities face EPA emissions compliance costs that elevate domestic synthetic graphite production economics relative to Asian imports. The Inflation Reduction Act domestic content provisions are redirecting procurement toward qualified North American suppliers. Michigan and Tennessee anode material plants are scaling purification throughput to serve Detroit-area automotive cell factories.
Germany
Rhineland industrial corridors sustain specialty carbon electrode production for European steel and aluminum sectors. EU Battery Regulation carbon footprint disclosure rules are filtering supplier qualification for graphite entering Saarland and Bavaria cell production facilities. SGL Carbon's Meitingen operations anchor captive needle coke integration into premium electrode tiers.
Japan
Kansai and Chubu regions concentrate advanced carbon material R&D for semiconductor thermal management and energy storage applications. METI industrial policy supports domestic purification capacity as supply chain resilience measures. Osaka and Nagoya-based processors are qualifying spherical natural graphite from African feedstock for battery anode specifications.
South Korea
Seoul Capital Area cell manufacturers are securing multi-year synthetic graphite offtake agreements through direct processor contracting rather than merchant markets. MFDS and trade ministry oversight coordinates strategic material stockpiling for energy security. Pohang steelworks sustain electrode demand while Gwangju-area anode specialists expand coating capabilities.
Graphite Materials Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the graphite materials value chain. The supplier base concentrates around integrated anode material specialists, captive needle coke refiners, and merchant purification operators. Three archetypes dominate: vertically integrated battery-grade processors, specialty carbon electrode manufacturers, and diversified mining-to-material conglomerates. Competitive dynamics center on multi-year offtake contracting and purification capacity expansion rather than price competition alone.
Among Japanese industrial conglomerates, Resonac Holdings Corporation and Tokai Carbon Co., Ltd. occupy positions spanning semiconductor and energy storage carbon applications. SGL Carbon exemplifies the European specialty electrode archetype with German-engineered material systems. Chinese specialists including Shanshan Co. and BTR New Material Group Co., Ltd. anchor the integrated anode material tier through Shandong-Fujian corridor concentration. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Shanshan Co. |
| Resonac Holdings Corporation |
| SGL Carbon |
| GrafTech International |
| BTR New Material Group Co., Ltd. |
| Imerys |
| Asbury Carbons |
| Tokai Carbon Co., Ltd. |
| Syrah Resources Limited |
| Others |
Supply & Pricing Matrix
Petroleum needle coke spot indices cascade through synthetic graphite value chains, compressing margins at unprocessed material tiers while amplifying capture for spheronized and coated anode suppliers serving qualified automotive cell producers.
Pricing Analysis
Processed-versus-unprocessed material splits dominate contract structures. Battery-grade synthetic graphite with spheronization and carbon coating commands premium positioning against uncoated merchant feedstock. Price differentiation rests on EU Battery Regulation carbon footprint certification and SAMR export licensing compliance. Cost compression in standard-grade industrial material is intensifying because Chinese thermal treatment operations undercut EPA-regulated domestic purification. Unqualified merchant traders face acute price sensitivity; integrated anode specialists with captive coating capabilities demonstrate lowest sensitivity due to long-term offtake anchoring.
Supply Chain Analysis
Direct-to-cell-manufacturer channels handle tier-one battery producer demand, displacing traditional distributor networks. Supply concentrates in China's Shandong-Fujian corridor, South Korea's Seoul Capital Area, and Japan's Kansai region. Feedstock draws from petroleum needle coke refineries, spherical natural graphite processing facilities, and recycled carbon material streams. Single-source vulnerability concentrates in Chinese export licensing chokepoints controlling battery-grade purity material flows. Distribution runs through multi-year offtake agreements rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's carbon footprint disclosure mandate compounds procurement complexity into sustained demand for qualified graphite suppliers.
For Market Incumbents: Deepen captive needle coke integration and expand spheronization capacity in China's Shandong-Fujian corridor to defend against Korean cell manufacturers' direct processor contracting. Secure SAMR export license pre-qualification ahead of quota allocation cycles. Carbon border adjustment mechanism positioning represents the priority defensive lever. For New Entrants and Emerging Players: The EU Battery Regulation in Europe opens a window for recycled content verification services and circular material flow certification. Target medium-purity aluminum smelting electrode segments where qualification timelines compress faster than battery-grade anode cycles. Pursue joint qualification partnerships with established anode material specialists to bypass 18-24 month cell manufacturer onboarding. For Investors and Strategic Acquirers: Consolidation pressure builds where purification capex intensity and regulatory compliance overhead outstrip unintegrated merchant operator returns. Five-to-ten year viability favors processors with backward integration into needle coke or forward integration into coated anode supply. Monitor SAMR export license issuance volumes as inflection signal for Chinese supply availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke | Captive feedstock supply insulates margin capture against petroleum refinery upgrade capacity constraints. |
| Spheronization and Coating Capacity Expansion | Surface treatment capabilities qualify material for Korean and Chinese tier-one cell manufacturer specifications. |
| EU Battery Regulation Compliance Certification | Carbon footprint disclosure documentation secures qualified supplier status for European automotive OEMs. |
| Recycled Graphite Material Flow Verification | Circular content credentials align with EU recycled content thresholds reshaping procurement criteria. |
| Long-term Offtake Agreement Structuring | Direct cell manufacturer contracts displace merchant market exposure and stabilize revenue visibility. |
Research Methodology
Multiple input streams — primary interviews with anode material procurement directors, graphite purification facility engineers, and cell manufacturer supply chain managers; secondary validation through customs trade databases, SEC filings of listed electrode producers, and SAMR regulatory bulletins — were reconciled through bottom-up volume triangulation against top-down market sizing.
Historical shipment data was cross-referenced against executive panel input to model expansion trajectories across the projection horizon. Segmentation dimensions included purity grade tier, end-use application, and regional production hub cluster. CAGRs were derived from elasticity-adjusted demand modeling incorporating electric vehicle production schedules and steelmaking cycle indicators.
Revisions become necessary when SAMR export license allocations tighten, EPA emissions rules expand, or needle coke refinery capacity additions stall beyond projected timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Global Core Materials Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
2D Materials Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Europe Graphene Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Advanced Polymer Composites Market