
 Global Polymer Nanomembrane Market | 2026-2036
Global Polymer Nanomembrane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymer Nanomembrane Market Foresight
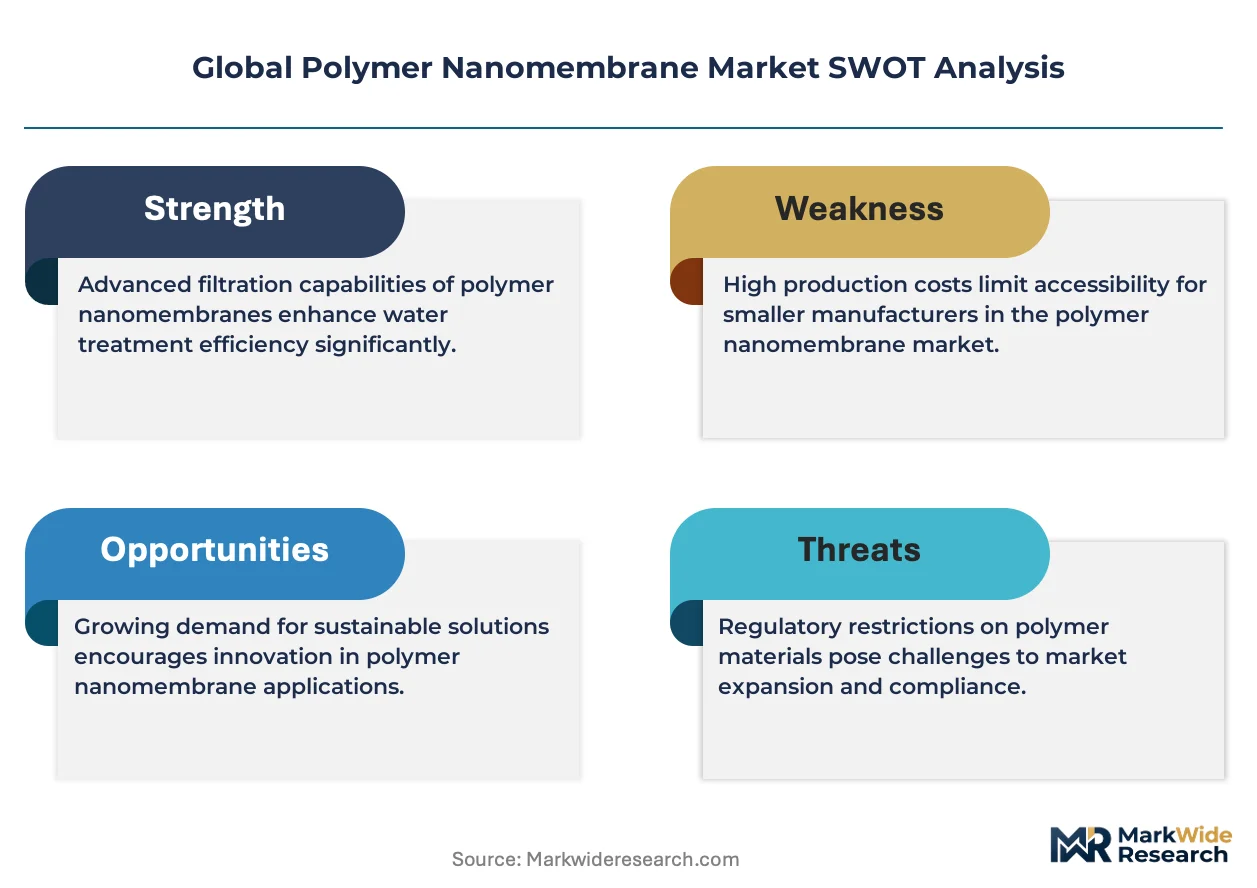
Multi-source procurement for high-performance polymer precursors is consolidating as membrane fabricators reduce dependency on single specialty-chemical suppliers. Toray Industries anchors Japanese domestic supply chains through captive polymer spinning capabilities. Koch Separation Solutions leverages its hollow-fiber manufacturing scale to compete in North American municipal water contracts. DuPont de Nemours sustains technology leadership in fluoropolymer nanomembranes for aggressive chemical separations.
Polymer nanomembranes are ultrathin selective barriers, typically 10–1000 nanometers thick, engineered from synthetic polymers such as polyvinylidene fluoride or polyethersulfone via electrospinning or interfacial polymerization to achieve precise molecular cutoffs for liquid and gas separation. Their primary commercial purpose is to deliver high flux and selectivity with reduced energy consumption versus conventional membrane systems. Phase inversion dominates current manufacturing throughput due to its scalability for water treatment applications, while layer-by-layer assembly commands premium positioning in pharmaceutical purification where Angstrom-level thickness control justifies higher unit economics. Electrospinning occupies a growing niche in research laboratory procurement despite slower commercial throughput.
The US EPA's Long-Term 2 Enhanced Surface Water Treatment Rule and the EU's F-Gas Regulation shape membrane material selection by restricting certain fluorinated chemistries while mandating pathogen removal thresholds that favor nanoscale pore architectures. China's MEE enforces industrial wastewater discharge limits that directly drive upgrades from microfiltration to nanofiltration systems in chemical processing corridors. Stakeholders must monitor regulatory divergence between jurisdictions where fluoropolymer restrictions tighten in Europe but persist in Asian industrial applications, forcing portfolio segmentation by geography rather than unified global product lines.
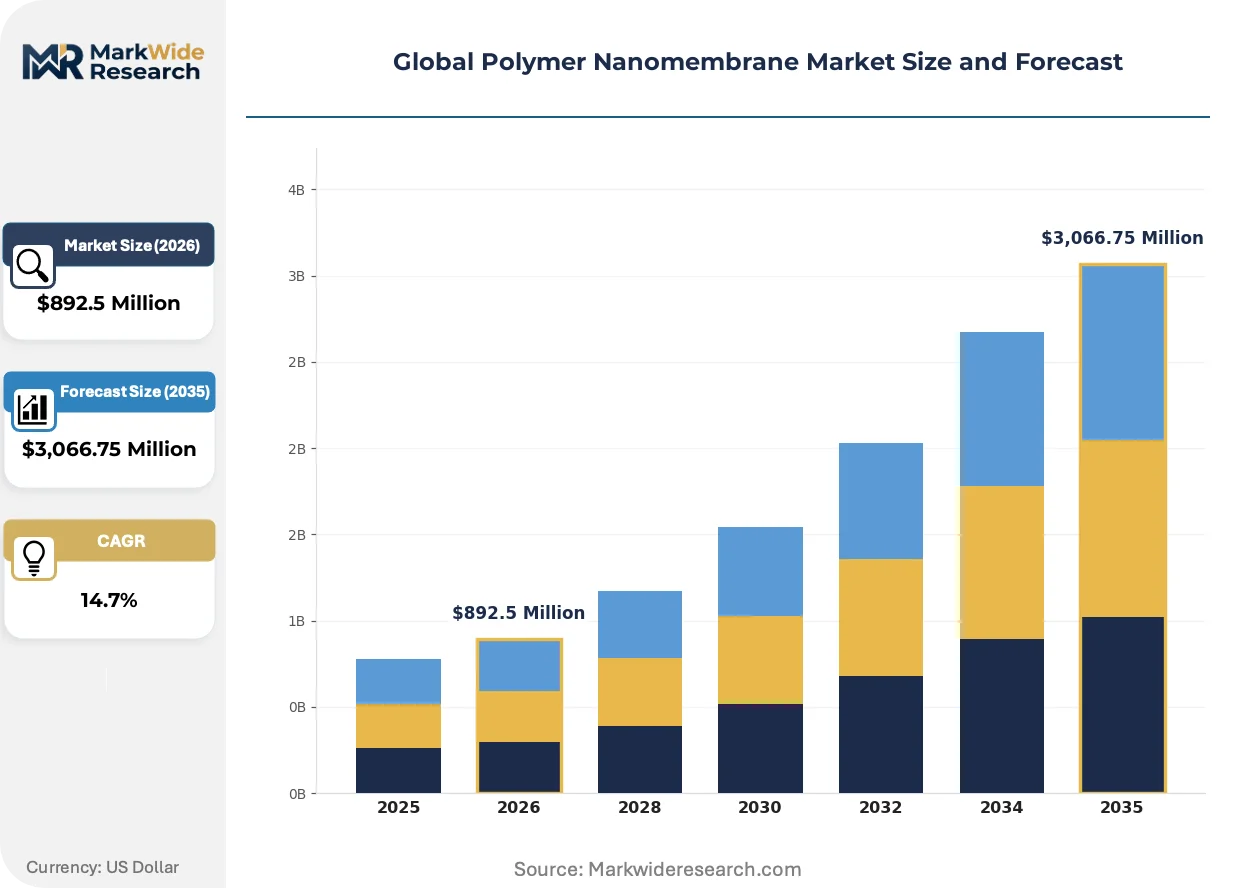
Market Dynamics
Water utilities in China's industrial corridor cities are accelerating nanofiltration deployment to meet MEE discharge mandates, compressing upgrade cycles from microfiltration systems and reshaping supplier qualification requirements across municipal procurement frameworks.
Growth Catalysts
- MEE Wastewater Standards:China's Ministry of Ecology and Environment enforces industrial discharge limits that mandate nanofiltration upgrades in chemical processing corridors. Municipal utilities in Tianjin and Shanghai have issued consecutive tender waves for high-performance membrane systems.
- Desalination Expansion:Water stress in India's pharmaceutical clusters drives membrane procurement for process water purification. Facilities in Hyderabad and Ahmedabad are retrofitting reverse osmosis trains with nanofiltration pretreatment stages.
- Electrospinning Maturation:Laboratory-scale manufacturing advances are reducing defect densities in nanofiber membranes. Research institutions in Germany and Japan are transferring pilot-line protocols to contract manufacturers for pharmaceutical validation batches.
Market Restraints
- Fluorinated Polymer Feedstock Volatility:PVDF precursor prices fluctuate with refrigerant market dynamics and F-Gas Regulation phase-down schedules in Europe. Membrane fabricators face margin compression when hedging specialty fluoropolymer inventories.
- Single-Source Concentration Risk:High-performance polyethersulfone resin production concentrates among three European specialty chemical suppliers. Asian membrane manufacturers remain dependent on imported granulate for consistent molecular weight distribution.
- Layer-by-Layer Throughput Ceiling:Angstrom-level thickness control via sequential deposition achieves precision at 10-20% of phase-inversion output rates. Pharmaceutical applications absorb limited commercial volume despite premium pricing.
Strategic Opportunities
- Brazilian Industrial Wastewater:ANVISA pharmaceutical manufacturing guidelines and state-level environmental enforcement in São Paulo and Rio de Janeiro create demand for validated nanofiltration skids. Local system integrators seek technology licensing partnerships.
- Hydrogen Purification Convergence:Polymer nanomembranes are integrating with pressure swing adsorption and cryogenic separation trains for green hydrogen conditioning. Electrolyzer OEMs in Germany and South Korea are qualifying membrane modules for moisture and ionic impurity removal.
- EU Green Deal Procurement Incentives:Public tender scoring criteria increasingly weight lifecycle carbon footprint and circular material content. Membrane suppliers with verified recycling pathways for fluoropolymer substrates gain preferential positioning in Dutch and Danish municipal contracts.
Industry Challenges
- Interfacial Polymerization Scale-Up Expertise:Thin-film composite formation requires precise control of aqueous-organic interface stability across meter-wide production lines. Technical talent with simultaneous competence in polymer chemistry and continuous-process engineering commands premium compensation and retention risk.
- Multi-Jurisdiction Certification Timelines:Drinking water contact approvals from EPA, NSF International, and individual EU member state health authorities operate on non-harmonized review schedules. Product launches delay 18-24 months when targeting simultaneous US and European municipal qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymer Nanomembrane Market |
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $3,066.75 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinylidene Fluoride, Polyethersulfone, Polysulfone, Nylon, Cellulose Acetate Technology: Electrospinning, Phase Inversion, Layer-by-Layer Assembly, Interfacial Polymerization, Track Etching Application: Water Treatment, Gas Separation, Food & Beverage Processing, Pharmaceutical Purification, Chemical Processing End User: Membrane Manufacturers, Research Laboratories, Water Utilities, Food Processors, Chemical Plants |
| Companies Covered | DuPont de Nemours, Inc., Toray Industries, Inc., Koch Separation Solutions, Pall Corporation, Alfa Laval, Nitto Denko Corporation, Synder Filtration, Inc., Pentair, Sumitomo Electric Fine Polymer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymer Nanomembrane Market Shifts & Advancements
Membrane manufacturing is bifurcating between commodity water treatment scale and precision pharmaceutical customization, with process innovation determining which fabricators capture margin in each tier.
Block copolymer self-assembly is expanding into sub-10-nanometer pore architecture fabrication for precise molecular weight cutoffs. Biopharmaceutical downstream processing teams in Switzerland and Massachusetts are qualifying these membranes for monoclonal antibody concentration steps. The technology is expanding into applications previously reserved for chromatography resins, compressing capital intensity for multi-product facilities.
The EU's F-Gas Regulation restricts hydrofluorocarbon production volumes that share feedstock chains with PVDF polymerization. Membrane suppliers are reformulating barrier layers with partially fluorinated alternatives or shifting to polyethersulfone backbones for non-aggressive separations. German chemical processing hubs show fastest adaptation, driven by Bundesimmissionsschutzgesetz enforcement alignment with EU-wide phase-down schedules.
Buyers in municipal water utilities are consolidating membrane procurement under ten-year performance-based service contracts. Original equipment manufacturers in North America and Australia are displacing component sales with full-system availability guarantees. This restructuring concentrates vendor selection authority among engineering-procurement-construction firms with balance-sheet capacity to underwrite long-term performance risk.
Global Polymer Nanomembrane Market Segmentation
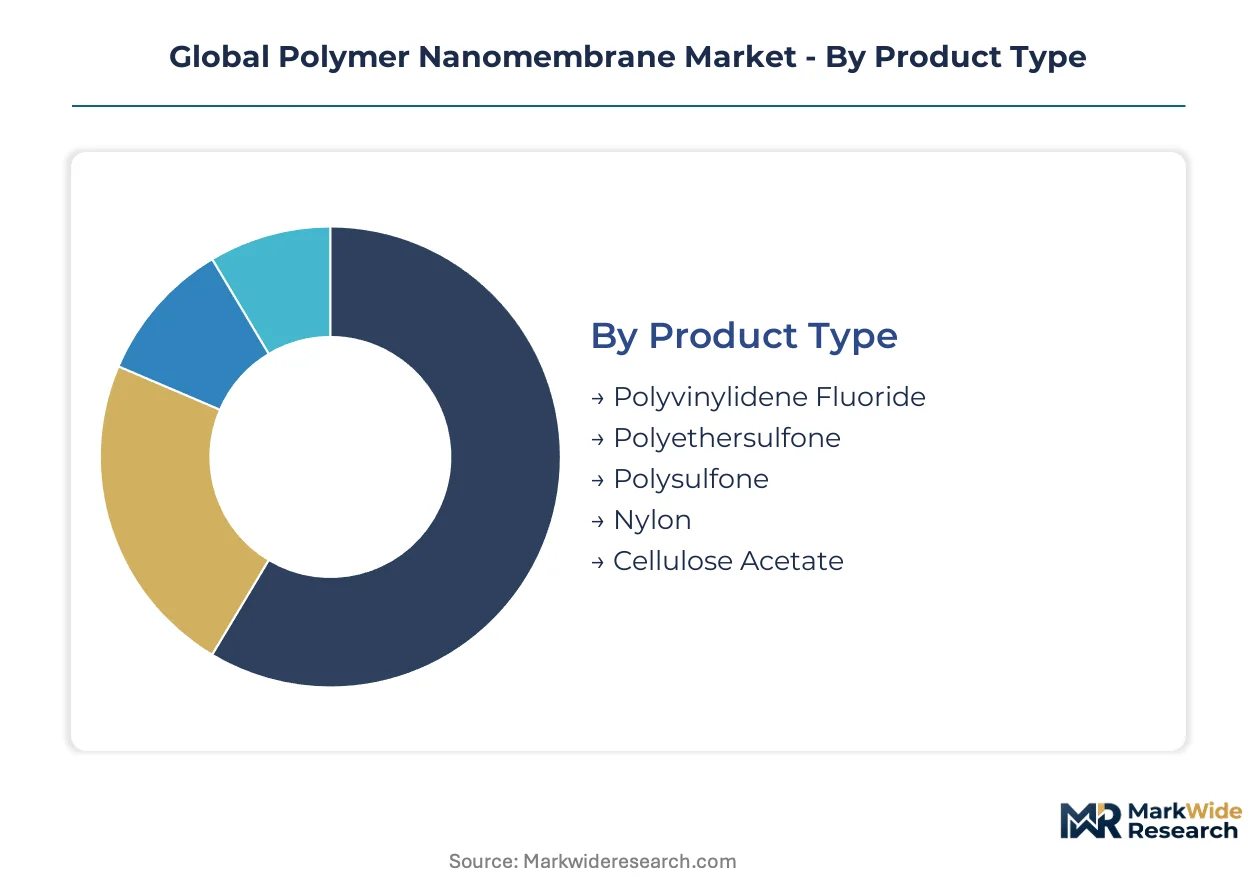
Polymer nanomembrane markets fragment across material chemistry, fabrication method, and end-use intensity. Each dimension carries distinct margin structures and qualification barriers that reshape supplier positioning.
Product Type:
Volume production concentrates in fluorinated polymers for aggressive separations, while premium positioning shifts toward sulfone-based alternatives amid regulatory pressure.
- Polyvinylidene Fluoride:PVDF dominates chemical processing and membrane bioreactor applications due to thermal stability and mechanical strength. China's MEE discharge mandates in Tianjin and Shanghai are accelerating procurement of PVDF nanofiltration modules for industrial wastewater.
- Polyethersulfone:Hydrophilic surface chemistry and broad pH tolerance position PES for pharmaceutical purification and food-grade separations. India's pharmaceutical clusters in Hyderabad and Ahmedabad are retrofitting RO trains with PES nanofiltration pretreatment stages.
- Polysulfone:Cost-competitive backbone for ultrafiltration membranes with established supply chains.
- Nylon:Hydrophilic character suits aqueous filtration in laboratory and analytical applications.
- Cellulose Acetate:Biodegradable option gaining traction in single-use and disposable membrane formats.
Mature deployment sits with PVDF in municipal and industrial water. Newer deployment is concentrated in PES for biopharmaceutical downstream processing.
Technology:
Manufacturing throughput separates scalable water treatment methods from precision pharmaceutical fabrication.
- Phase Inversion:Dominant commercial throughput for water treatment membranes via immersion precipitation. German chemical processing hubs leverage phase-inversion PVDF hollow fibers for Bundesimmissionsschutzgesetz-compliant effluent treatment.
- Layer-by-Layer Assembly:Angstrom-level thickness control via sequential polyelectrolyte deposition achieves precision for monoclonal antibody concentration. Swiss biopharmaceutical downstream processing teams are qualifying these membranes to compress capital intensity versus chromatography resins.
- Electrospinning:Nanofiber architectures with high porosity-to-surface-area ratios.
- Interfacial Polymerization:Thin-film composite formation for reverse osmosis and nanofiltration skins.
- Track Etching:Cylindrical pore geometry for precise particle and cell separations.
Phase inversion anchors volume production for water utilities. Layer-by-layer assembly commands steepest expansion trajectory in pharmaceutical validation batches.
Application:
End-use intensity spans commodity municipal contracts to validated pharmaceutical skids with tenfold margin differentials.
- Water Treatment:Municipal desalination and industrial wastewater reuse represent the largest procurement volume. Dutch and Danish utilities are scoring lifecycle carbon footprint in tender criteria under EU Green Deal procurement incentives.
- Pharmaceutical Purification:Downstream processing for monoclonal antibodies and sterile filtration commands premium unit economics. Massachusetts biopharmaceutical facilities are adopting block copolymer self-assembly membranes for molecular weight cutoff precision.
- Gas Separation:Hydrogen conditioning and carbon capture applications.
- Food & Beverage Processing:Dairy concentration and beverage clarification with sanitary design requirements.
- Chemical Processing:Solvent recovery and aggressive media separations.
Water treatment absorbs manufacturing scale. Pharmaceutical purification is gaining share fastest as validation protocols mature.
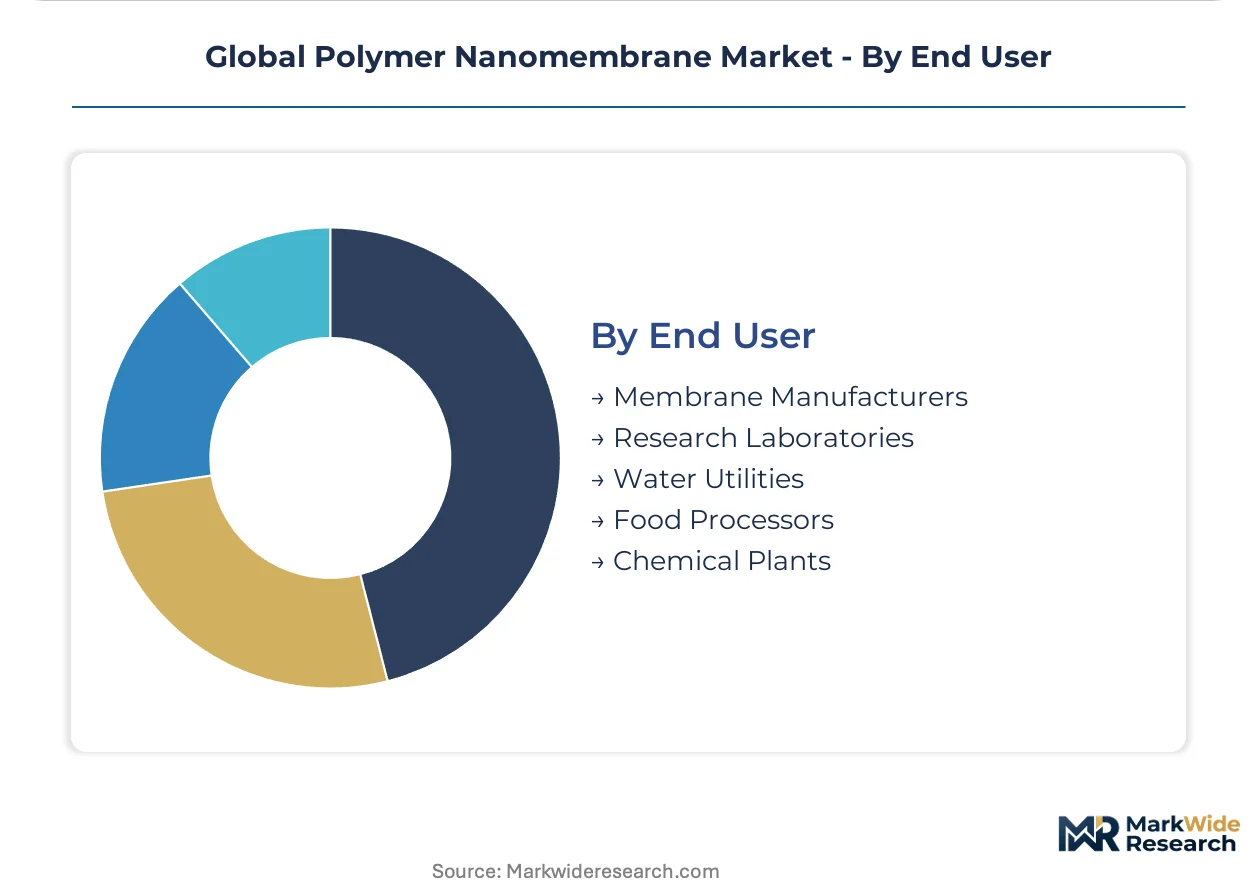
End User:
Procurement authority is consolidating under engineering-procurement-construction firms with balance-sheet capacity for performance guarantees.
- Water Utilities:Ten-year performance-based service contracts are displacing component sales in North America and Australia. Municipal procurement frameworks in São Paulo and Rio de Janeiro are creating demand for validated nanofiltration skids under ANVISA-aligned state enforcement.
- Membrane Manufacturers:Original equipment producers integrating nanomembrane layers into module and system assemblies.
- Research Laboratories:Pilot-line protocol development for technology transfer to contract manufacturers.
- Food Processors:Dairy and beverage facilities with sanitary membrane requirements.
- Chemical Plants:Process intensification and solvent recovery operations.
Water utilities anchor long-term contract structures. Research laboratories are concentrating newest deployment for pilot-scale validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial demand for polymer nanomembranes concentrates in chemical processing corridors and pharmaceutical clusters across four major economies. Each geography presents distinct regulatory drivers and procurement patterns that reshape supplier positioning.
China
Tianjin and Shanghai municipal utilities are issuing consecutive tender waves for high-performance membrane systems to meet MEE discharge mandates. The Ministry of Ecology and Environment enforces industrial wastewater limits that compress upgrade cycles from microfiltration to nanofiltration. Chemical processing corridors in the Yangtze River Delta are retrofitting effluent treatment trains with PVDF nanofiltration modules.
Germany
Bundesimmissionsschutzgesetz enforcement aligns with EU F-Gas Regulation phase-down schedules, accelerating reformulation of barrier layers away from fully fluorinated chemistries. Chemical processing hubs in North Rhine-Westphalia and Baden-Württemberg are adopting phase-inversion PVDF hollow fibers for compliant effluent treatment. The EU Green Deal weights lifecycle carbon footprint in Dutch and Danish municipal tender scoring, extending to German procurement frameworks.
United States
The EPA's Long-Term 2 Enhanced Surface Water Treatment Rule mandates pathogen removal thresholds that favor nanoscale pore architectures in municipal systems. North American engineering-procurement-construction firms are consolidating membrane procurement under ten-year performance-based service contracts. Original equipment manufacturers are displacing component sales with full-system availability guarantees.
India
Water stress in pharmaceutical clusters drives membrane procurement for process water purification. Facilities in Hyderabad and Ahmedabad are retrofitting reverse osmosis trains with nanofiltration pretreatment stages. State-level environmental enforcement in Maharashtra and Gujarat creates demand for validated nanofiltration skids in chemical processing applications.
Brazil
ANVISA pharmaceutical manufacturing guidelines and state-level environmental enforcement in São Paulo and Rio de Janeiro create demand for validated nanofiltration skids. Local system integrators are seeking technology licensing partnerships to serve industrial wastewater treatment requirements. The southeastern industrial corridor presents procurement opportunities for membrane suppliers with established validation protocols.
Global Polymer Nanomembrane Market Competitive Landscape
Capacity expansion dominates the current landscape as membrane fabricators scale phase-inversion throughput for water treatment contracts. The vendor base separates into three tiers: integrated chemical conglomerates with captive polymer spinning, specialized membrane module assemblers, and regional system integrators. Strategic archetypes include fluoropolymer technology leaders, hollow-fiber manufacturing specialists, and pharmaceutical validation partners. M&A activity and geographic licensing agreements represent the dominant competitive moves as firms secure regional qualification pathways.
Among Japanese fabricators, Toray Industries anchors domestic supply chains through integrated polymer production capabilities. DuPont de Nemours exemplifies the fluoropolymer technology archetype for aggressive chemical separations. Koch Separation Solutions occupies a position among North American specialists leveraging manufacturing scale for municipal water contracts.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Toray Industries, Inc. |
| Koch Separation Solutions |
| Pall Corporation |
| Alfa Laval |
| Nitto Denko Corporation |
| Synder Filtration, Inc. |
| Pentair |
| Sumitomo Electric Fine Polymer, Inc. |
| Others |
Supply & Pricing Matrix
Performance-grade bifurcation between pharmaceutical validation tiers and municipal commodity contracts shapes both margin structures and procurement network configurations across polymer nanomembrane markets. China's MEE discharge mandates compress upgrade cycles in Tianjin and Shanghai, forcing fabricators to segment pricing architectures by certification burden while maintaining dual-qualified resin streams for fluoropolymer and sulfone backbones.
Pricing Analysis
Volume production anchors the commodity water treatment tier where phase-inversion PVDF hollow fibers compete on unit economics, while layer-by-layer assembly commands premium positioning in monoclonal antibody concentration applications with tenfold margin multiples. Price differentiation rests on NSF International drinking water contact approvals versus pharmaceutical GMP validation protocols, with Dutch and Danish municipal tenders under EU Green Deal scoring criteria weighting lifecycle carbon footprint as a secondary pricing modifier. Cost compression in the commodity tier intensifies as Asian membrane manufacturers expand phase-inversion capacity, while pharmaceutical buyers show limited price sensitivity given downstream product value concentration. Contract-based long-term offtake agreements dominate municipal procurement, displacing spot component sales with ten-year performance guarantees underwritten by engineering-procurement-construction firms.
Supply Chain Analysis
Dual-sourcing requirements for high-performance polyethersulfone resin now mandate qualification across at least two of the three European specialty chemical suppliers, with Asian membrane fabricators hedging molecular weight distribution consistency through inventory pre-positioning. Raw material dependencies center on fluoropolymer precursors tied to refrigerant feedstock chains, polyethersulfone granulate for hydrophilic surface chemistry, and electrospun nanofiber mat substrates for pharmaceutical validation batches. Single-source concentration risk in European PES production creates tariff exposure vulnerability as regional trade frameworks shift. Distribution runs through original equipment manufacturers integrating nanomembrane layers into module assemblies, with system integrators in Brazil and India seeking technology licensing partnerships to bypass direct resin procurement complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from regulatory compliance burdens and multi-jurisdiction certification timelines is forcing sub-scale fabricators toward acquisition or exit, concentrating vendor selection authority among balance-sheet-capable engineering-procurement-construction consortia.
For Market Incumbents: Cement technology leadership in fluoropolymer nanomembranes through captive polymer spinning capabilities that insulate margin from PVDF precursor volatility tied to refrigerant market dynamics. Expand phase-inversion capacity in German chemical processing hubs to capture Bundesimmissionsschutzgesetz-aligned upgrade demand, while investing in block copolymer self-assembly R&D to defend against chromatography resin substitution in monoclonal antibody concentration applications. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in Germany open a window for partially fluorinated barrier layer formulations and polyethersulfone backbone alternatives that bypass incumbent fluoropolymer supply chain lock-in. Target Brazilian industrial wastewater treatment under ANVISA-aligned state enforcement in São Paulo and Rio de Janeiro, where local system integrators lack validated nanofiltration skid capabilities. Pursue technology licensing partnerships rather than direct manufacturing scale-up to minimize capital intensity and certification timeline exposure. For Investors and Strategic Acquirers: Re-rating potential sits with hollow-fiber manufacturing specialists given hydrogen purification convergence with electrolyzer OEM qualification programs in Germany and South Korea. Long-term viability favors fabricators with demonstrated multi-jurisdiction certification velocity across EPA, NSF International, and EU member state health authority review schedules. Watch electrospinning pilot-line protocol transfers from German and Japanese research institutions to contract manufacturers as an inflection indicator for pharmaceutical validation batch commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursor Production | Toray Industries anchors Japanese supply chains through captive PVDF spinning capabilities that reduce feedstock volatility exposure. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA and EU Drinking Water Directive approvals compress 18-24 month launch timelines for municipal qualification. |
| Pharmaceutical Validation Partnership | Swiss biopharmaceutical downstream processing teams qualify layer-by-layer membranes to displace chromatography resin capital intensity. |
| Hydrogen Purification Module Qualification | German and South Korean electrolyzer OEMs integrate nanomembranes with pressure swing adsorption trains for moisture removal. |
| EU Green Deal Circular Material Pathway | Dutch and Danish municipal tender scoring rewards verified fluoropolymer substrate recycling programs with preferential positioning. |
Research Methodology
Document review covered EPA enforcement actions, ECHA substance restriction dossiers, and MEE discharge standard publications, complemented by interviews with membrane fabrication plant managers, pharmaceutical downstream processing directors, municipal procurement officers at Dutch water utilities, and specialty chemical resin procurement leads. Secondary validation drew from customs trade data for fluoropolymer precursor flows, SEC 10-K filings for integrated chemical conglomerates, and Bundesimmissionsschutzgesetz implementation guidance. Bottom-up capacity assessments across phase-inversion and layer-by-layer manufacturing lines were triangulated against top-down demand modeling from water utility tender databases and pharmaceutical facility retrofit announcements.
Segment-level projections across material chemistry, fabrication technology, and end-use intensity were generated through driver-linked elasticity modeling over the projection horizon. The analytical framework incorporated PVDF and PES grade tier differentiation, municipal versus pharmaceutical buyer archetypes, and regional regulatory cluster divergence as core segmentation dimensions. CAGRs were derived from installed base turnover rates, MEE mandate compliance deadlines, and EU F-Gas Regulation phase-down schedules. Industry-specific inputs included electrospinning defect density reduction curves from German and Japanese pilot-line protocols, and hollow-fiber manufacturing scale coefficients from North American municipal contract specifications.
The model assumes a particular technology adoption path; alternative pathways for block copolymer self-assembly membrane commercialization would alter the outlook if Angstrom-level thickness control achieves phase-inversion throughput parity. Forecasts reflect assumptions regarding MEE enforcement consistency, F-Gas Regulation phase-down adherence, and pharmaceutical validation protocol maturation. A model refresh is warranted upon material change in hydrogen purification membrane qualification velocity with electrolyzer OEMs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Membrane Filters Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Nafion Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Membrane Filter Cartridge Market