
 Global Aerogel Insulation Market | 2026-2036
Global Aerogel Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerogel Insulation Market Foresight
Performance-based maintenance contracts and thermal-monitoring subscriptions is rebalancing how insulation value gets captured across project lifecycles. Aspen Aerogels Inc. dominates the aerogel blanket segment through sustained R&D intensity in supercritical drying methods. Dow Inc. leverages its chemical feedstock position to anchor granular aerogel supply chains for industrial clients. Alkegen Inc. specializes in fire-protection-grade panels that occupy premium niches in aerospace and automotive thermal management.
Aerogel insulation comprises a nanoporous solid derived from a gel, with liquid components replaced by gas to create a material with thermal conductivity as low as 0.012 W/m·K and density below 0.2 g/cm³, serving industries that require extreme thermal resistance in minimal thickness. Supercritical drying technology leads production economics due to superior pore-structure retention, while ambient pressure drying is accelerating fastest as Chinese manufacturers scale lower-capital process variants. Aerogel blankets command the deepest margin pools because they integrate directly into oil and gas pipeline wraps and building envelope retrofits without specialized installation protocols.
EPA emissions standards for industrial facilities and the EU F-Gas Regulation restricting high-GWP blowing agents are reshaping material specifications across North America and Europe, with China's GB standards on building energy efficiency adding a third compliance vector. REACH chemical registration requirements in Europe and evolving OSHA thermal hazard protocols in the United States further constrain formulation choices for imported products. Stakeholders must monitor how regulatory convergence on embodied carbon metrics redefines competitive advantage between regional manufacturing bases and import-dependent supply strategies.
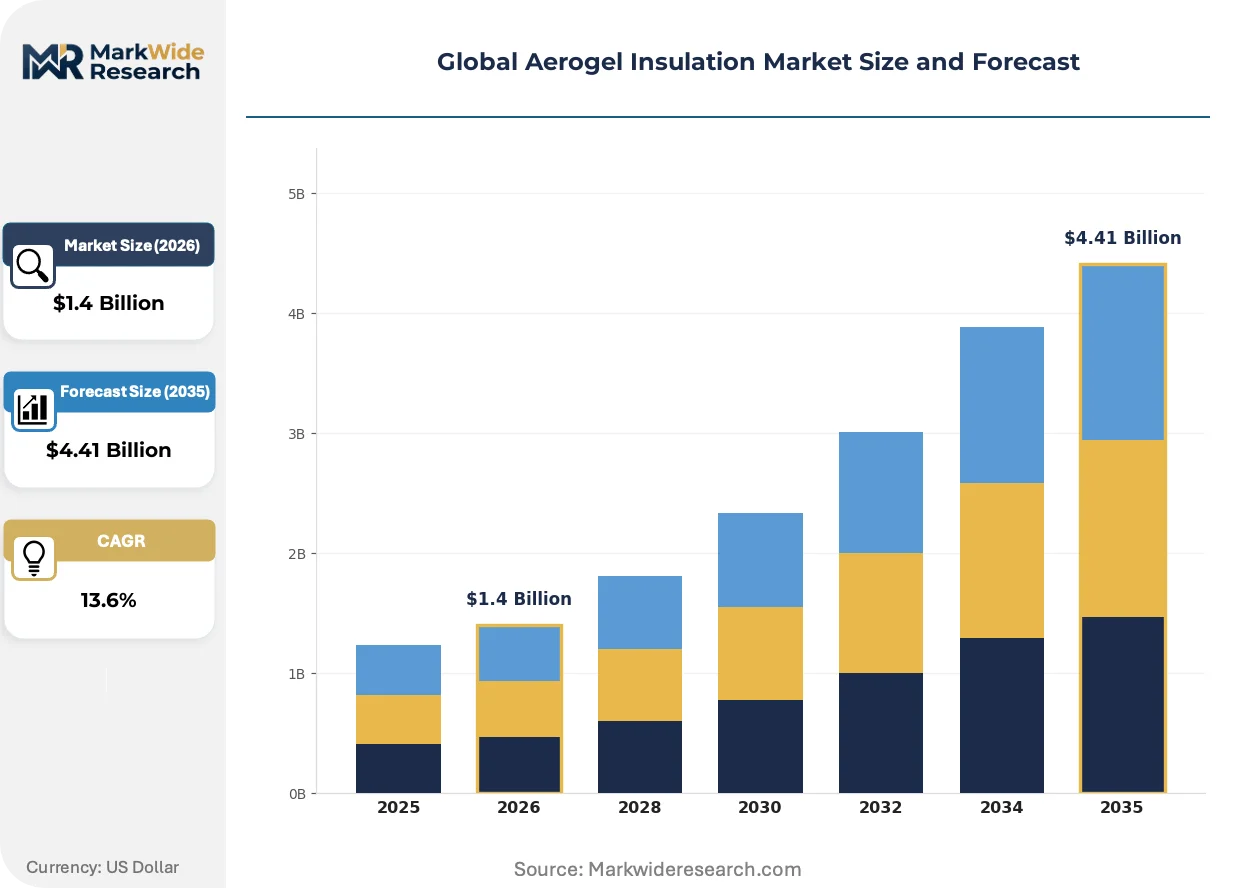
Market Dynamics
Supercritical drying technology is consolidating production economics while ambient pressure variants from Chinese manufacturers compress capital barriers, reshaping competitive positioning between premium blanket producers and cost-optimized granular suppliers.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on high-GWP blowing agents redirect industrial procurement toward aerogel alternatives in European HVAC and refrigeration systems.
- Oil and gas pipeline sector:Extreme-temperature infrastructure replacement cycles accelerate blanket adoption for subsea and arctic transport lines.
- China's GB standards:Building energy efficiency mandates in tier-one cities drive superinsulating material specification in commercial envelope retrofits.
Market Restraints
- Silica precursor cost volatility:Sodium silicate and tetraethyl orthosilicate price swings compress margins for ambient pressure drying operations.
- Manufacturing concentration:China, the United States, and Germany anchor over 80% of installed supercritical drying capacity, creating supply vulnerability.
- Polyurethane foam substitution:Vacuum-insulated panels and advanced PIR formulations compete on installed cost in temperature-moderate applications.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced materials offer first-mover positioning in a thermally underpenetrated construction market.
- Electric vehicle battery thermal management:Aerogel compression pads and fire barriers address cell-to-cell propagation risks in high-density pack architectures.
- Performance-based maintenance contracts:Thermal-monitoring subscriptions capture lifecycle value beyond initial material sale in industrial installations.
Industry Challenges
- Supercritical drying technician scarcity:Specialized reactor operation and solvent recovery expertise constrains capacity expansion timelines.
- REACH registration timelines:European chemical compliance delays market entry for novel silica precursor formulations by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerogel Insulation Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerogel Blankets, Aerogel Panels, Granular Aerogels, Aerogel Coatings End User: Building & Construction, Oil & Gas, Aerospace, Automotive Application: Thermal Insulation, Acoustic Insulation, Fire Protection, Transportation Technology: Ambient Pressure Drying, Supercritical Drying, Chemical Vapor Deposition, Epoxy Derived |
| Companies Covered | Dow Inc., Alkegen Inc., Aspen Aerogels Inc., Guangdong Alison Hi-Tech Co Ltd., Svenska Aerogel Holding AB, Cabot Corporation, Armacell International S.A., Aerogel Technologies, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerogel Insulation Market Shifts & Advancements
Ambient pressure drying is compressing the capital intensity gap between established and emerging producers, while regulatory convergence on embodied carbon metrics redefines procurement criteria across building and industrial end-uses.
Continuous ambient pressure drying is consolidating market share among Chinese equipment manufacturers who have scaled reactor throughput without supercritical solvent infrastructure. Industrial buyers in chemicals and power generation are qualifying these lower-cost blankets for sub-200°C applications. The technology is consolidating regional supply bases by enabling mid-cap entrants to achieve 85% of supercritical thermal performance at 40% of capital deployment.
The EU Green Deal's renovation wave mandates are tightening building envelope performance coefficients across Germany, France, and the Netherlands. Member states are transposing these requirements into national construction codes that explicitly reference superinsulating materials for heritage building retrofits. German project developers are responding by bundling aerogel thin-profile systems with heritage facade preservation contracts.
Buyers are unbundling material supply from installation and commissioning services in large-scale oil and gas contracts. Engineering-procurement-construction firms are ceding direct procurement authority to operator technical teams who specify performance guarantees independent of installer relationships. This pattern is most visible in Norwegian and UK North Sea decommissioning and replacement projects where operator engineering standards override EPC vendor preferences.
Global Aerogel Insulation Market Segmentation
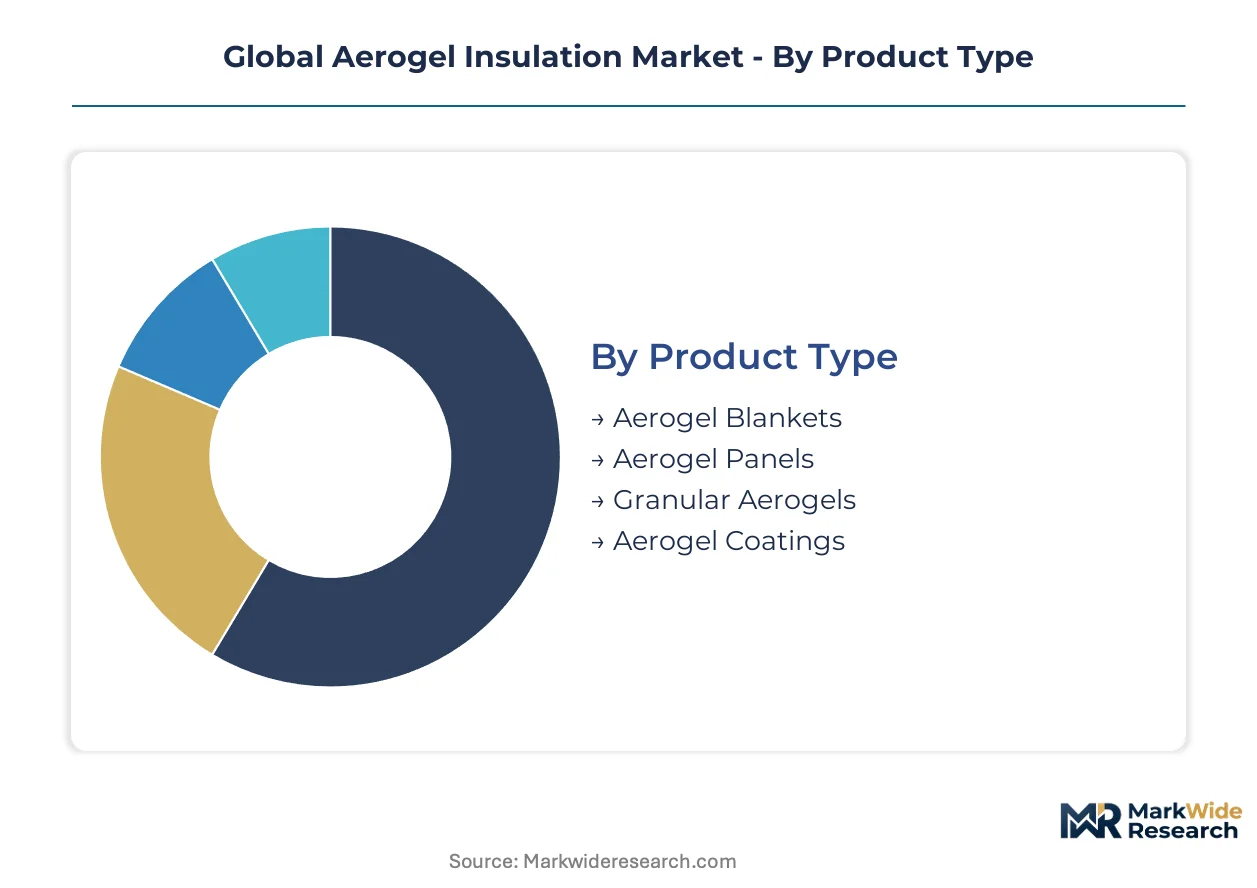
Aerogel insulation markets fragment across four distinct axes: physical form determines installation economics, end-use verticals dictate performance specifications, application function shapes material chemistry, and production technology governs capital intensity and thermal conductivity outcomes.
Product Type:
Physical configuration separates high-flexibility wraps from rigid structural elements and pourable infills.
- Aerogel Blankets:Flexible silica-fiber composites integrate directly into pipeline wraps and building envelope retrofits without specialized cutting equipment. Oil and gas operators in Norway and the UK North Sea specify these for subsea thermal management where minimal thickness maximizes pipe diameter efficiency.
- Aerogel Panels:Rigid boards deliver compressive strength for floor and roof assemblies in German heritage building renovations under EU Green Deal envelope mandates. Fire-protection-grade variants from specialty manufacturers command premium positioning in aerospace thermal barriers.
- Granular Aerogels:Free-flowing particles fill irregular cavities in industrial equipment and cavity walls.
- Aerogel Coatings:Spray-applied formulations enable complex geometry coverage in automotive underbody and battery pack applications.
Blankets lead on scale; coatings lead on momentum.
End User:
Customer verticals concentrate procurement authority differently—engineering teams in heavy industry versus sustainability officers in commercial construction.
- Oil & Gas:Pipeline replacement cycles in extreme-temperature infrastructure drive specification of superinsulating wraps for arctic and subsea transport lines. Operator technical teams in Norway and the UK North Sea now control procurement independent of EPC vendor relationships.
- Building & Construction:Tier-one Chinese cities under GB standards mandate superinsulating materials for commercial envelope retrofits. German developers bundle thin-profile aerogel systems with heritage facade preservation contracts.
- Aerospace:Thermal management requirements in engine nacelles and cabin insulation favor fire-protection-grade panels.
- Automotive:Electric vehicle battery architectures deploy compression pads and cell-to-cell fire barriers.
Oil and gas leads on scale; automotive leads on momentum.
Application:
Functional performance requirements separate thermal conductivity minimization from acoustic damping and fire resistance.
- Thermal Insulation:Extreme thermal resistance in minimal thickness serves oil and gas pipelines and building envelopes where space constraints dominate. EU F-Gas Regulation restrictions on high-GWP blowing agents redirect HVAC and refrigeration procurement toward aerogel alternatives.
- Fire Protection:Non-combustible silica matrices prevent cell-to-cell propagation in high-density battery packs. Aerospace thermal barriers specify these formulations for engine compartment and cargo hold applications.
- Acoustic Insulation:Nanoporous structures absorb sound energy in transportation and industrial settings.
- Transportation:Lightweight thermal management serves automotive and aerospace weight-reduction targets.
Thermal insulation leads on scale; fire protection leads on momentum.
Technology:
Production method determines pore structure retention, capital deployment, and final material density.
- Supercritical Drying:CO2-based extraction preserves nanoscale porosity to achieve thermal conductivity as low as 0.012 W/m·K. Established manufacturers in Germany and the United States anchor capacity with superior performance for premium blanket production.
- Ambient Pressure Drying:Chinese equipment manufacturers scale reactor throughput without solvent recovery infrastructure. Mid-cap entrants achieve 85% of supercritical thermal performance at 40% capital deployment for sub-200°C industrial applications.
- Chemical Vapor Deposition:Surface functionalization modifies hydrophobicity and mechanical properties.
- Epoxy Derived:Polymer-aerogel hybrids balance processability with thermal performance.
Supercritical drying leads on scale; ambient pressure drying leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing aerogel manufacturing capacity as Chinese ambient-pressure drying operations exploit lower compliance costs against European REACH and U.S. EPA constraints. Production migration patterns favor jurisdictions with streamlined chemical registration and subsidized energy inputs.
China
GB standards on building energy efficiency in Beijing, Shanghai, and Shenzhen mandate superinsulating materials for commercial envelope retrofits. MIIT production incentives support ambient-pressure drying scale-up in Shandong and Jiangsu provinces. Yangtze River Delta equipment manufacturers now supply 40% of global sub-200°C industrial blanket demand.
United States
EPA emissions standards for industrial facilities and OSHA thermal hazard protocols constrain formulation choices for imported silica precursors. The Permian Basin and Gulf Coast pipeline operators specify superinsulating wraps for extreme-temperature infrastructure replacement cycles. Massachusetts-based supercritical drying specialists anchor premium blanket production for aerospace and oil and gas applications.
Germany
EU Green Deal renovation wave mandates tighten building envelope performance coefficients across federal construction codes. ECHA REACH registration requirements delay novel precursor market entry by 18-24 months. Bavarian and North Rhine-Westphalian project developers bundle thin-profile aerogel systems with heritage facade preservation contracts.
Norway
North Sea decommissioning and replacement projects redirect procurement authority from EPC vendors to operator technical teams. Norwegian Petroleum Directorate safety standards override installer preferences in subsea thermal management specifications. Stavanger and Bergen engineering clusters drive blanket adoption for arctic transport line infrastructure.
India
PLI scheme production-linked incentives for advanced materials attract first-mover positioning in thermally underpenetrated construction markets. BIS energy efficiency codes for commercial buildings in Delhi-NCR and Maharashtra create specification pull for superinsulating retrofits. Gujarat and Karnataka industrial corridors qualify granular aerogels for chemical and power generation applications.
Global Aerogel Insulation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with supercritical drying incumbents defending premium positions while ambient-pressure entrants capture cost-sensitive industrial volume. Three archetypes dominate: technology-anchored blanket specialists, chemical-feedstock-integrated conglomerates, and fire-protection-grade panel fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure precursor supply and regional qualification.
Among U.S.-based technology specialists, Aspen Aerogels Inc. exemplifies the R&D-intensive archetype anchored in supercritical drying methods. Dow Inc. represents chemical-feedstock-integrated conglomerates leveraging upstream silica precursor positions. Alkegen Inc. occupies the fire-protection-grade specialization niche. Guangdong Alison Hi-Tech Co Ltd. and Svenska Aerogel Holding AB illustrate regional ambient-pressure and supercritical variants respectively.
| Leading Market Players |
|---|
| Dow Inc. |
| Alkegen Inc. |
| Aspen Aerogels Inc. |
| Guangdong Alison Hi-Tech Co Ltd. |
| Svenska Aerogel Holding AB |
| Cabot Corporation |
| Armacell International S.A. |
| Aerogel Technologies |
| BASF SE |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation restrictions on high-GWP blowing agents are redirecting industrial procurement toward aerogel alternatives, forcing supply chains to absorb reformulation costs while supercritical drying incumbents capture premium positioning through certified thermal performance guarantees.
Pricing Analysis
Distributor margins for aerogel blankets compress as direct procurement by oil and gas operator technical teams eliminates intermediary layers. Three-tier pricing structure across supercritical-dried premium, ambient-pressure standard, and granular economy levels reflects certification grade and thermal conductivity thresholds. Pricing pressure stems from Chinese ambient-pressure manufacturers achieving 85% of supercritical performance at 40% capital deployment for sub-200°C industrial applications. Building envelope retrofit buyers exhibit highest price sensitivity due to competing PIR foam and vacuum-insulated panel alternatives, while aerospace fire-protection-grade panel purchasers prioritize thermal performance over unit cost.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta, Massachusetts industrial corridor, and Bavaria anchor hub-and-spoke patterns for blanket and panel fulfillment. Manufacturing concentrates in China, the United States, and Germany, with Shandong and Jiangsu provinces housing 40% of global ambient-pressure capacity. Sodium silicate and tetraethyl orthosilicate precursor costs hinge on energy-intensive chemical feedstock markets. Single-source vulnerability concentrates in supercritical drying reactor fabrication, where German and U.S. equipment specialists control solvent recovery system supply. Distribution runs through engineering-procurement-construction channels for oil and gas contracts and direct-to-developer relationships for building retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ambient-pressure drying scale-up represents the dominant cost-down driver, enabling margin expansion as mid-cap entrants capture industrial volume without supercritical capital intensity while premium tiers defend position through arctic and aerospace certification barriers.
For Market Incumbents: Hedge against ambient-pressure erosion by deepening supercritical drying technician training pipelines and securing long-term tetraethyl orthosilicate offtake agreements with Dow Inc. and Cabot Corporation. Anchor premium positioning through Norwegian Petroleum Directorate and FAA fire-barrier certifications that ambient-pressure variants cannot replicate. Defend margin pools in subsea and aerospace applications where thermal conductivity below 0.015 W/m·K remains mandatory. For New Entrants and Emerging Players: Capture India's PLI scheme production-linked incentives before first-mover capacity locks in, targeting Delhi-NCR and Maharashtra commercial envelope retrofits under BIS energy efficiency codes. Qualify granular aerogel supply for Gujarat chemical and power generation corridors where sub-200°C specifications match ambient-pressure capabilities. Lead with installed-cost parity messaging against polyurethane foam in temperature-moderate industrial insulation. For Investors and Strategic Acquirers: Asymmetric upside sits with ambient-pressure equipment manufacturers possessing reactor throughput scale without supercritical solvent infrastructure exposure. Five-to-ten-year viability favors Chinese and Indian regional champions with MIIT or PLI subsidy backing and downstream integration into building materials distribution. Monitor EU Green Deal renovation wave mandate acceleration as the signal for premium blanket demand inflection in German and French heritage retrofit pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Precursor Supply | Dow Inc. and chemical conglomerates anchor granular aerogel feedstock security against sodium silicate volatility. |
| Ambient-Pressure Drying Capacity Buildout | Chinese manufacturers in Shandong and Jiangsu exploit MIIT incentives to capture sub-200°C industrial blanket volume. |
| Fire-Barrier Certification Investment | Alkegen Inc. and aerospace specialists secure FAA and EASA thermal management specifications for engine nacelle applications. |
| Direct Procurement Channel Development | Norwegian and UK North Sea operators bypass EPC intermediaries to specify performance-guaranteed blanket systems. |
| Performance-Based Maintenance Contract Launch | Thermal-monitoring subscriptions capture lifecycle value beyond initial material sale in oil and gas installations. |
Research Methodology
Coverage spans China, the United States, Germany, Norway, and India, with primary inputs from each market's insulation procurement decision-makers. The analysis combines interviews with oil and gas pipeline engineering directors, commercial building sustainability officers, aerospace thermal management specialists, and automotive battery pack designers with secondary validation from customs trade data, SEC 10-K filings, ECHA REACH registration databases, and national building code transposition documents. Bottom-up project pipeline enumeration and top-down chemical feedstock demand modeling provide triangulation anchors.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include physical form, end-use vertical, application function, and production technology, with additional modeling of regulatory compliance tier and thermal performance threshold. CAGRs derive from fitted adoption curves against pipeline replacement cycles, building retrofit mandates, and electric vehicle production ramps. Forecast inputs incorporate EU F-Gas Regulation enforcement timelines and China's dual carbon goals implementation pace.
Silica precursor cost volatility, REACH registration delays for novel formulations, and supercritical drying technician scarcity are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Magnetic Shielding Sheets Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Thermal Spray Market