
 Europe Graphene Market | 2026-2036
Europe Graphene Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Graphene Market Insights
REACH compliance is consolidating the cost-of-entry calculus for graphene producers seeking European market access. Applied Graphene Materials leverages its UK-based manufacturing to navigate registration complexities. Graphenea anchors its position through specialized CVD graphene films for research and semiconductor prototyping. Versarien competes via thermal management solutions targeting aerospace and defense procurement channels.
Graphene consists of a single atomic layer of sp2-bonded carbon atoms arranged in a hexagonal lattice, with electron mobility exceeding 200,000 cm2/V·s and tensile strength surpassing 130 GPa, enabling its primary function as a multifunctional additive for conductivity, mechanical reinforcement, and thermal dissipation across industrial applications. Graphene nanoplatelets dominate volume shipments due to lower production costs and established dispersion protocols in polymer matrices. Battery materials represents the fastest-growing application segment as cell manufacturers substitute carbon black with graphene conductive networks to reduce internal resistance. Coatings as an end-use industry maintains mature demand patterns focused on corrosion protection for marine and infrastructure assets.
EMA, ECHA, and the EU Green Deal collectively shape graphene commercialization pathways through chemical safety registration, nanomaterial classification protocols, and embedded carbon accounting requirements. ECHA's evolving guidance on nanoform substance evaluation directly impacts registration costs and data requirements for graphene oxide and reduced graphene oxide variants. Stakeholders must monitor forthcoming delegated acts under the EU AI Act that could classify certain graphene-based sensor outputs as high-risk applications, altering qualification pathways for wearable and environmental monitoring devices.
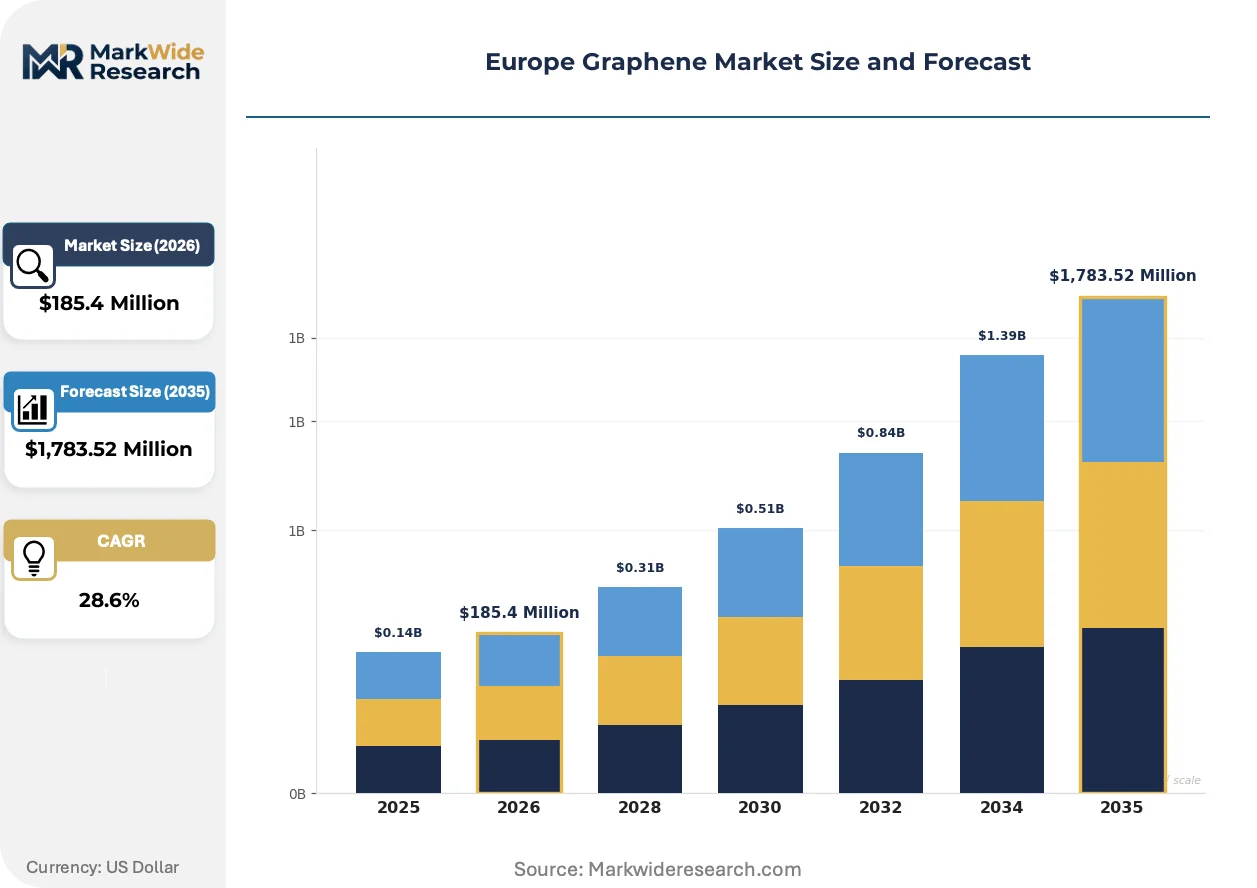
Market Dynamics
EU Green Deal industrial decarbonization mandates are compressing substitution timelines for carbon-intensive materials, forcing battery manufacturers and coatings producers to accelerate graphene adoption in conductive networks and corrosion-resistant formulations.
Growth Catalysts
- Battery Materials Substitution:Cell manufacturers in Germany are replacing carbon black with graphene conductive networks to reduce internal resistance in lithium-ion architectures. EMA guidelines on nanomaterial safety are clarifying qualification pathways for anode integration.
- REACH Registration Consolidation:The EU's chemical safety framework is raising cost-of-entry barriers that favor established producers with completed dossiers. This is concentrating supply among registrants with validated nanoform data packages.
- Printed Electronics Demand:Graphene ink production hubs in the Netherlands are scaling output to serve flexible circuit and sensor manufacturers. Specialized CVD film capacity is expanding to meet semiconductor prototyping orders.
Market Restraints
- Production Cost Volatility:Graphite feedstock prices fluctuate with battery anode demand from China, compressing margin structures for graphene nanoplatelet producers dependent on exfoliation routes.
- Technical Dispersion Limits:Achieving uniform graphene distribution in high-viscosity polymer matrices remains inconsistent across batch scales, limiting mechanical reinforcement claims in automotive composites.
- ECHA Nanoform Uncertainty:Evolving guidance on substance evaluation for graphene oxide variants is extending registration timelines and inflating toxicology study costs for new market entrants.
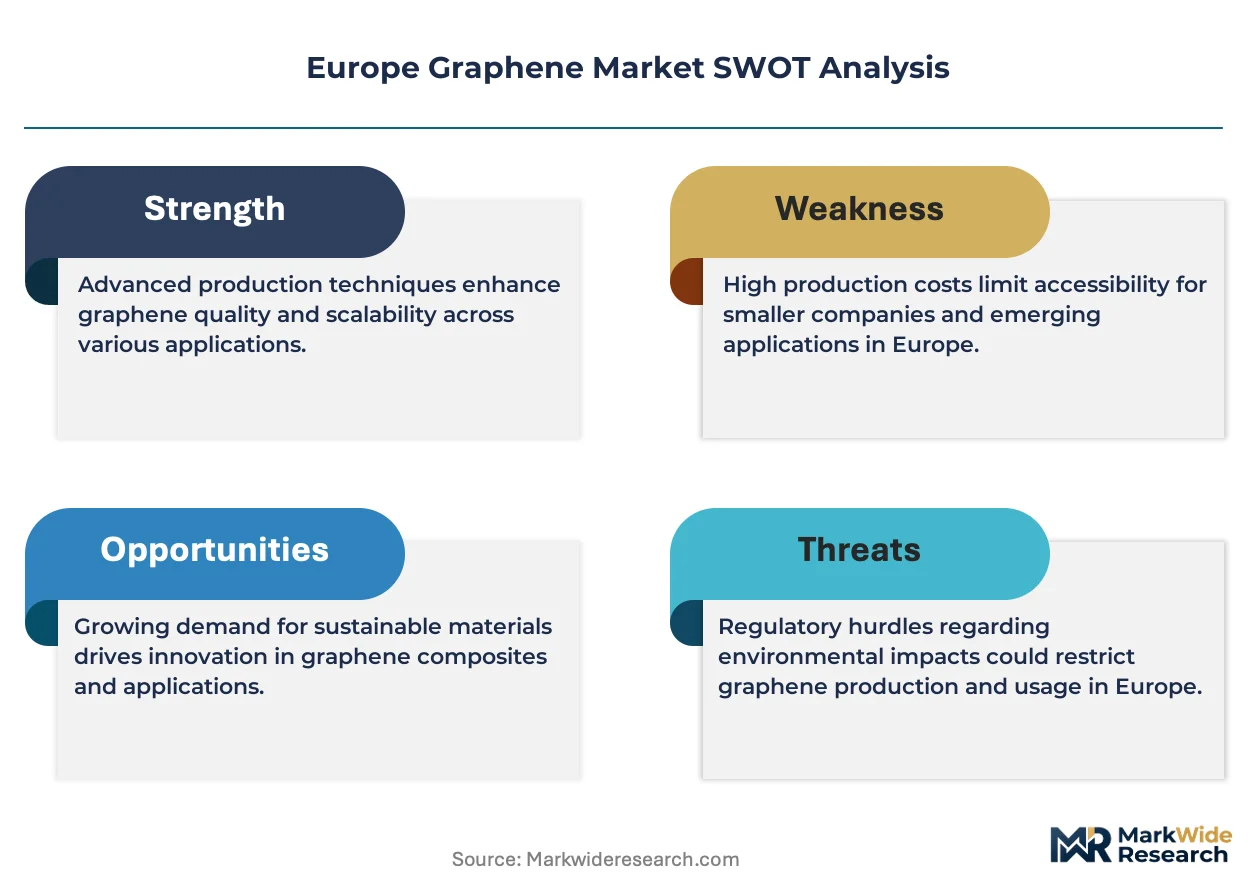
Strategic Opportunities
- Thermal Management Applications:Aerospace and defense procurement channels in France and the UK are qualifying graphene-enhanced heat spreaders for satellite and avionics cooling systems.
- CSRD Carbon Accounting:The EU's corporate sustainability reporting directive is creating preference for graphene additives that enable lightweighting and embedded emissions reduction in transport equipment.
- Wearable Sensor Convergence:Graphene-based flexible sensors are integrating with printed electronics platforms for health monitoring devices, with qualification pathways pending under the EU AI Act's high-risk classification framework.
Industry Challenges
- Specialized Synthesis Talent Scarcity:Chemical vapor deposition technicians and dispersion formulation chemists command premium compensation in the Netherlands and Germany, constraining capacity expansion timelines.
- Standardization Fragmentation:Competing definitions of graphene layer count and defect density between ISO, IEC, and national metrology institutes are delaying procurement specifications for industrial buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Graphene Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,783.52 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphene Oxide, Reduced Graphene Oxide, Graphene Nanoplatelets, Graphene Film End Use Industry: Electronics, Energy Storage, Composites, Coatings Form: Powder, Dispersion, Film, Coating Application: Conductive Inks, Battery Materials, Thermal Management, Sensors |
| Companies Covered | Applied Graphene Materials, Versarien, Graphenea, OCSiAl, NanoXplore, Haydale Graphene Industries, Thomas Swan & Co., First Graphene, Directa Plus, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Graphene Market Trends and Innovations
Production methodologies and regulatory frameworks are simultaneously evolving, creating competitive advantage for producers who synchronize manufacturing scale-up with emerging compliance requirements.
Electrochemical exfoliation of graphite is decentralizing graphene supply by enabling smaller-batch, lower-capex production closer to end-use clusters. Regional battery manufacturers in Poland and Hungary are adopting modular exfoliation units to reduce transport costs and import dependencies. This distributed model is compressing the traditional concentration of supply among large-scale chemical vapor deposition operators.
ECHA's evolving guidance on nanoform substance evaluation is tightening data requirements for graphene oxide and reduced graphene oxide variants. Registration costs for new entrants are rising as toxicology and ecotoxicology study portfolios expand. Producers with existing REACH dossiers are leveraging this friction to defend market position against unregistered imports.
Qualification-driven procurement is displacing specification-based purchasing in marine coatings and infrastructure applications. Buyers in Norway and Denmark now require third-party corrosion performance certification before contract award, shifting competitive emphasis from price to validated service-life data. This behavioral change favors producers with established testing relationships with classification societies.
Europe Graphene Market Segmentation
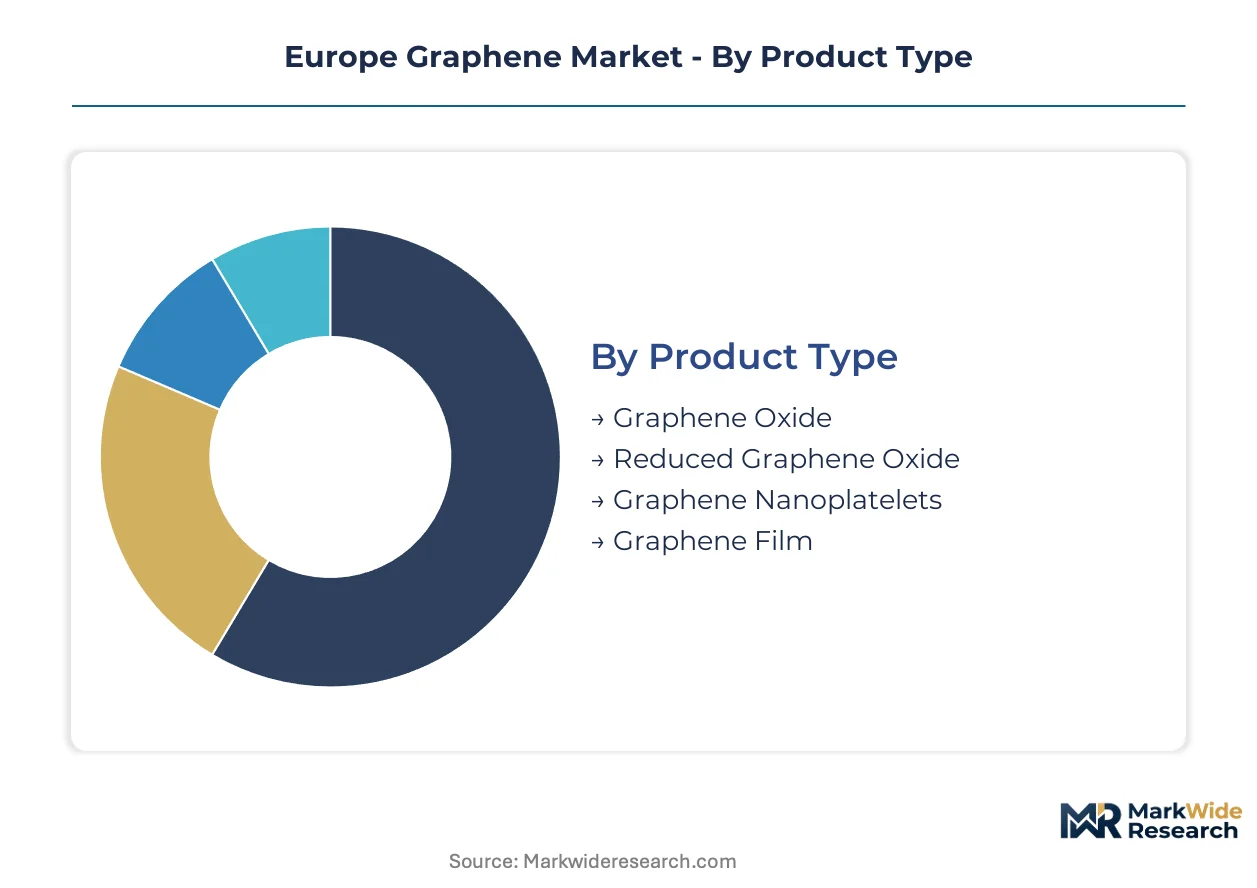
Segmentation in the Europe Graphene Market reveals how material form and integration depth determine commercial viability across battery anodes, printed electronics, and corrosion-resistant coatings. Producers must align product specifications with end-use processing requirements and ECHA nanoform registration obligations.
Product Type:
Integration depth varies sharply across product types, with standalone films commanding qualification-intensive procurement and nanoplatelets embedding anonymously into bulk matrices.
- Graphene Nanoplatelets:These multi-layer carbon structures stack 5-10 nanometers thick with lateral dimensions reaching 50 microns. Battery manufacturers in Germany substitute carbon black with nanoplatelet conductive networks to reduce internal resistance in lithium-ion cells. REACH registration costs favor established producers with validated nanoform dossiers.
- Graphene Film:Single to few-layer CVD-grown sheets achieve electron mobility exceeding 100,000 cm²/V·s. Semiconductor prototyping labs in the Netherlands and UK purchase specialized films for flexible transistor development, with procurement gated by ISO defect density specifications.
- Graphene Oxide:Oxygen-functionalized sheets disperse readily in aqueous solutions for ink formulations. Research institutions in Spain and Italy drive demand for printable sensor substrates.
- Reduced Graphene Oxide:Chemically or thermally deoxygenated derivatives restore conductivity for composite reinforcement. Automotive suppliers in France evaluate rGO-enhanced polymers for lightweight structural components.
Graphene Nanoplatelets lead volumes today; Graphene Film is gaining share fastest.
End Use Industry:
Application maturity determines margin structures, with energy storage commanding premium pricing for qualified materials and coatings competing on validated service-life data.
- Energy Storage:Cell manufacturers scale graphene-enhanced anodes and conductive additives across Poland and Hungary. EU Green Deal decarbonization mandates compress substitution timelines for carbon-intensive battery components.
- Electronics:Printed circuit and flexible display producers in the Netherlands integrate graphene inks for transparent conductive layers. ECHA nanoform guidance shapes qualification pathways for wearable device integration.
- Composites:Aerospace and automotive Tier 1s in France and the UK qualify graphene-reinforced thermoplastics for weight reduction targets under CSRD carbon accounting rules.
- Coatings:Marine and infrastructure asset owners in Norway and Denmark require third-party corrosion certification before contract award, displacing price-based procurement.
Coatings generates the steadiest revenue base; Energy Storage shows the steepest expansion trajectory.
Form:
Supply chain configuration determines geographic sourcing patterns, with dispersions and films requiring proximity to formulation expertise while powders ship cost-effectively across borders.
- Powder:Dry nanoplatelet aggregates suit high-shear compounding into polymer masterbatches. Compounders in Germany and Belgium maintain siloed inventory for just-in-time automotive supply chains.
- Dispersion:Pre-dispersed graphene in solvent or aqueous vehicles eliminates exfoliation variability for ink formulators. Dutch production hubs serve printed electronics clusters with customized viscosity grades.
- Film:CVD-grown sheets on copper substrates transfer to target polymers or ceramics for thermal management. UK-based Applied Graphene Materials and Spanish CVD operators compete on defect density specifications.
- Coating:Ready-to-apply graphene-enhanced paints and primers target marine and infrastructure maintenance. Norwegian classification society certification requirements filter supplier qualification.
Powder dominates shipment volumes; Dispersion formats are climbing fastest.
Application:
Functional performance requirements segment the market between conductivity-driven and thermal-driven specifications, with regulatory qualification intensity varying by end-use risk classification.
- Battery Materials:Graphene conductive networks replace carbon black in anode and cathode formulations. German cell manufacturers scale orders under EMA nanomaterial safety guidelines clarifying integration protocols.
- Conductive Inks:Screen-printable and inkjet-compatible formulations serve flexible circuit and RFID antenna production. Netherlands-based Graphenea anchors supply for research-to-production transitions.
- Thermal Management:Heat spreader and interface materials target satellite avionics and data center cooling. French aerospace procurement channels qualify graphene-enhanced solutions for orbital thermal cycling.
- Sensors:Flexible strain, gas, and biosensors integrate with printed electronics platforms. EU AI Act high-risk classification pending for certain wearable health monitoring outputs.
Battery Materials anchors current demand; Thermal Management applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graphene's European commercialization traces to Manchester's 2004 isolation breakthrough, with industrial scaling subsequently concentrating in Germany's battery corridor and the Netherlands' printed electronics clusters.
Germany
Cell manufacturers in Bavaria and Baden-Württemberg scale graphene-enhanced anode orders under EMA nanomaterial safety protocols. The KBA enforces battery component qualification standards that compress substitution timelines for carbon-intensive materials. Stuttgart's automotive supply chain integrates conductive additives for lightweight structural composites.
United Kingdom
Applied Graphene Materials leverages Manchester-derived expertise to navigate REACH registration complexities for thermal management exports. The UK Research and Innovation agency funds CVD capacity expansion for semiconductor prototyping applications. Cambridge's electronics cluster drives demand for specialized few-layer films in flexible transistor development.
Netherlands
Graphene ink production hubs in Eindhoven and Randstad scale output for printed circuit and RFID antenna manufacturers. ECHA's evolving nanoform guidance shapes qualification costs for dispersion formulators serving wearable device integration. Dutch compounders customize viscosity grades for just-in-time electronics supply chains.
France
Aerospace procurement channels in Île-de-France and Provence-Alpes-Côte d'Azur qualify graphene-enhanced heat spreaders for satellite thermal cycling applications. ANSM monitors nanomaterial safety in health monitoring sensor deployments. Toulouse's avionics sector drives specification development for orbital cooling systems.
Spain
Research institutions in Madrid and Catalonia purchase graphene oxide for printable sensor substrate development under CSRD carbon accounting frameworks. Spanish CVD operators compete on defect density specifications against UK-based film producers. Barcelona's materials science cluster anchors southern European demand for flexible electronics prototyping.
Europe Graphene Market Competitive Landscape
The competitive structure tilts toward specialized material form producers with completed REACH dossiers. Established registrants leverage ECHA nanoform data requirements to defend position against unregistered imports. Three archetypes dominate: CVD film specialists, nanoplatelet compounders, and dispersion formulators. Capacity expansion and strategic technology licensing represent the dominant competitive moves as producers synchronize manufacturing scale-up with evolving compliance obligations.
Within the CVD film specialist tier, Graphenea and Applied Graphene Materials occupy positions exemplifying qualification-intensive procurement for semiconductor prototyping. Among UK-based fabricators, Versarien and Haydale Graphene Industries represent thermal management and dispersion formulation archetypes respectively. Thomas Swan & Co. anchors the chemical synthesis segment. OCSiAl exemplifies scale-driven production architecture for industrial additive supply.
| Leading Market Players |
|---|
| Applied Graphene Materials |
| Versarien |
| Graphenea |
| OCSiAl |
| NanoXplore |
| Haydale Graphene Industries |
| Thomas Swan & Co. |
| First Graphene |
| Directa Plus |
| Others |
Pricing and Supply Chain Analysis
Electrochemical exfoliation of graphite is decentralizing European graphene supply by enabling smaller-batch, lower-capex production closer to end-use clusters in Poland and Hungary. This production-method transition simultaneously compresses cost structures for regional battery manufacturers and fragments pricing power away from large-scale chemical vapor deposition operators.
Pricing Analysis
Unbundled graphene nanoplatelet powders trade at substantial discounts to dispersion and film formats that bundle formulation expertise. Price differentiation rests on REACH registration status and ECHA nanoform dossier completeness, with qualified materials commanding premiums. Cost compression in unregistered powder tiers is intensifying because Polish and Hungarian manufacturers deploy modular exfoliation units. Battery anode producers exhibit the highest price sensitivity, while semiconductor prototyping labs show minimal elasticity for specialized CVD films.
Supply Chain Analysis
Workforce scarcity for chemical vapor deposition technicians and dispersion formulation chemists in the Netherlands and Germany is constraining capacity expansion timelines. Supply concentrates in the United Kingdom, Germany, and the Netherlands, with raw material dependencies on high-purity graphite feedstock, copper substrates for CVD growth, and specialty solvents for dispersion. Single-source vulnerability runs through Chinese graphite anode supply chains serving battery manufacturers. Distribution runs through direct technical sales to qualified buyers rather than commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Graphene Market functions as a regulatory compounder where ECHA nanoform registration timelines and REACH dossier completeness determine competitive survival. The EU Green Deal's embedded carbon accounting mandates are accelerating material substitution decisions across transport and energy storage applications.
For Market Incumbents: To counter unregistered import pressure from Asian producers, prioritize backward integration into graphite feedstock processing and expand specialized CVD capacity in the United Kingdom. Defend market position by leveraging completed REACH dossiers to extend registration cost barriers for new entrants targeting battery and coatings segments. For New Entrants and Emerging Players: The premium-to-economy price gap in graphene nanoplatelet powders creates white-space opportunity for mid-tier qualification. Target thermal management applications in French aerospace procurement channels where incumbent concentration remains lowest. Enter through joint development agreements with printed electronics formulators in the Netherlands seeking qualified dispersion partners. For Investors and Strategic Acquirers: Valuations sit cheapest among electrochemical exfoliation specialists with modular production architectures serving regional battery corridors. Long-term viability hinges on synchronization with EU Green Deal decarbonization enforcement and CSRD carbon accounting adoption. Monitor ECHA delegated acts under the EU AI Act as the inflection signal for wearable sensor qualification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | Validates nanoform data packages for ECHA registration, excluding unregistered competitors from EU market access. |
| Modular Exfoliation Deployment | Reduces transport costs and import dependencies for Polish and Hungarian battery manufacturers. |
| Specialized CVD Capacity Expansion | Captures semiconductor prototyping demand from Cambridge and Eindhoven electronics clusters. |
| Joint Development with Formulators | Secures embedded supply positions in Netherlands-based printed electronics value chains. |
| Third-Party Corrosion Certification | Qualifies coating products for Norwegian and Danish marine procurement requiring classification society validation. |
Research Methodology
Coverage spans Germany, the United Kingdom, the Netherlands, France, and Spain, with primary inputs from each national graphene production cluster. The analysis combines structured interviews with CVD fabrication technicians, dispersion formulation chemists, battery cell procurement managers, and marine coatings specification engineers with secondary validation from ECHA registration databases, EU customs trade data, and SEC filings of listed graphene producers. Bottom-up volume estimates triangulate against top-down market sizing by application segment.
Rate-of-change decomposition separates volume expansion from price trajectory movements across the projection horizon. The analytical framework models segmentation by product type, end-use industry, form, and application, with cross-dimensional analysis of regulatory qualification intensity. CAGRs derive from fitted growth curves calibrated to EMA nanomaterial safety guideline implementation schedules and EU Green Deal industrial decarbonization enforcement milestones. Industry-specific inputs include graphite feedstock price volatility indices and classification society certification timelines.
Caveats apply where ECHA nanoform guidance revisions or EU AI Act delegated acts could materially shift the outlook for wearable sensor and health monitoring applications. Forecasts reflect assumptions regarding REACH registration cost trajectories and battery manufacturer substitution timelines for carbon black. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Cathode Materials Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Lithium Tantalate Crystal Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Natural Single Crystal Diamond Market