
 Bioactive Glass Market | 2026-2036
Bioactive Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Glass Market Analysis
The shift from outsourced powder sourcing to in-house melt-quench production is hardening among top suppliers. Stryker leverages captive manufacturing to secure supply continuity for its orthopedic graft portfolio. Mo-Sci specializes in precision glass microspheres for controlled resorption profiles. Johnson & Johnson controls broad hospital purchasing channels that reinforce its position in spine and trauma applications.
Bioactive glass refers to silicate-based biomaterials containing calcium and phosphorus oxides that form hydroxyapatite upon implantation, with compositions typically ranging from 45S5 (46.1% SiO₂, 26.9% CaO, 24.4% Na₂O, 2.6% P₂O₅) to newer boron-containing variants engineered for faster ion release kinetics. These materials bond chemically with living bone and stimulate osteogenic cell differentiation, serving primarily as synthetic bone graft substitutes and dental defect fillers. Orthopedics occupies the largest value pool due to volume throughput in spinal fusion and trauma procedures, while tissue engineering represents the fastest-expanding application as researchers integrate bioactive glass scaffolds with stem cell therapies. Granule formulations dominate unit sales for their intraoperative handling properties, though coating applications on titanium implants command premium positioning.
The FDA's 510(k) and PMA pathways govern market entry for bone graft products in the United States, requiring biocompatibility data and clinical performance benchmarks that filter out undercapitalized entrants. ISO 10993 standards for biological evaluation of medical devices shape international testing protocols, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for permanent implant classifications. Stakeholders must monitor evolving reimbursement decisions for synthetic grafts versus autograft standards, as payer policies directly determine addressable procedure volumes across hospital systems.
Market Dynamics
Orthopedic surgeons in hospital settings are consolidating purchasing power around granule formulations with validated 510(k) clearance, compressing supplier margins while elevating clinical evidence requirements as the central competitive filter.
Growth Catalysts
- Spinal fusion reimbursement codes:Established CPT coding in the United States secures predictable payment pathways for synthetic graft procedures, sustaining hospital procurement volumes.
- ISO 10993 biocompatibility frameworks:Harmonized international testing standards accelerate regulatory dossier preparation for multi-market submissions, reducing time-to-clearance.
- Melt-quench production capabilities:In-house glass melting furnaces enable suppliers to control ion release kinetics and resorption profiles for patient-specific bone defect applications.
Market Restraints
- Autograft harvesting persistence:Iliac crest bone graft remains the clinical gold standard for spinal fusion, limiting synthetic graft penetration in high-reimbursement procedures.
- Raw material concentration:High-purity silica sand and phosphate precursors concentrate among limited specialty chemical suppliers, exposing formulation costs to input volatility.
- 510(k) clinical evidence burden:FDA substantial equivalence demonstrations require biocompatibility studies and performance benchmarking that filter undercapitalized entrants from commercialization.
Strategic Opportunities
- Stem cell scaffold integration:Bioactive glass architectures combined with mesenchymal stem cell therapies open regenerative medicine applications beyond traditional bone graft substitution.
- Titanium implant coating channels:Premium positioning for surface-modified orthopedic and dental hardware commands higher unit economics than bulk granule sales.
- EU MDR permanent implant classification:Stricter clinical evidence requirements for synthetic grafts create first-mover advantages for dossier-ready suppliers in European hospital systems.
Industry Challenges
- Biomaterials toxicology expertise:Shortage of specialists capable of designing ISO 10993-compliant biocompatibility study protocols delays regulatory submission timelines.
- Cleanroom manufacturing scale-up:Medical-grade glass processing requires validated aseptic environments and particle-controlled handling systems that demand substantial capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Glass Market |
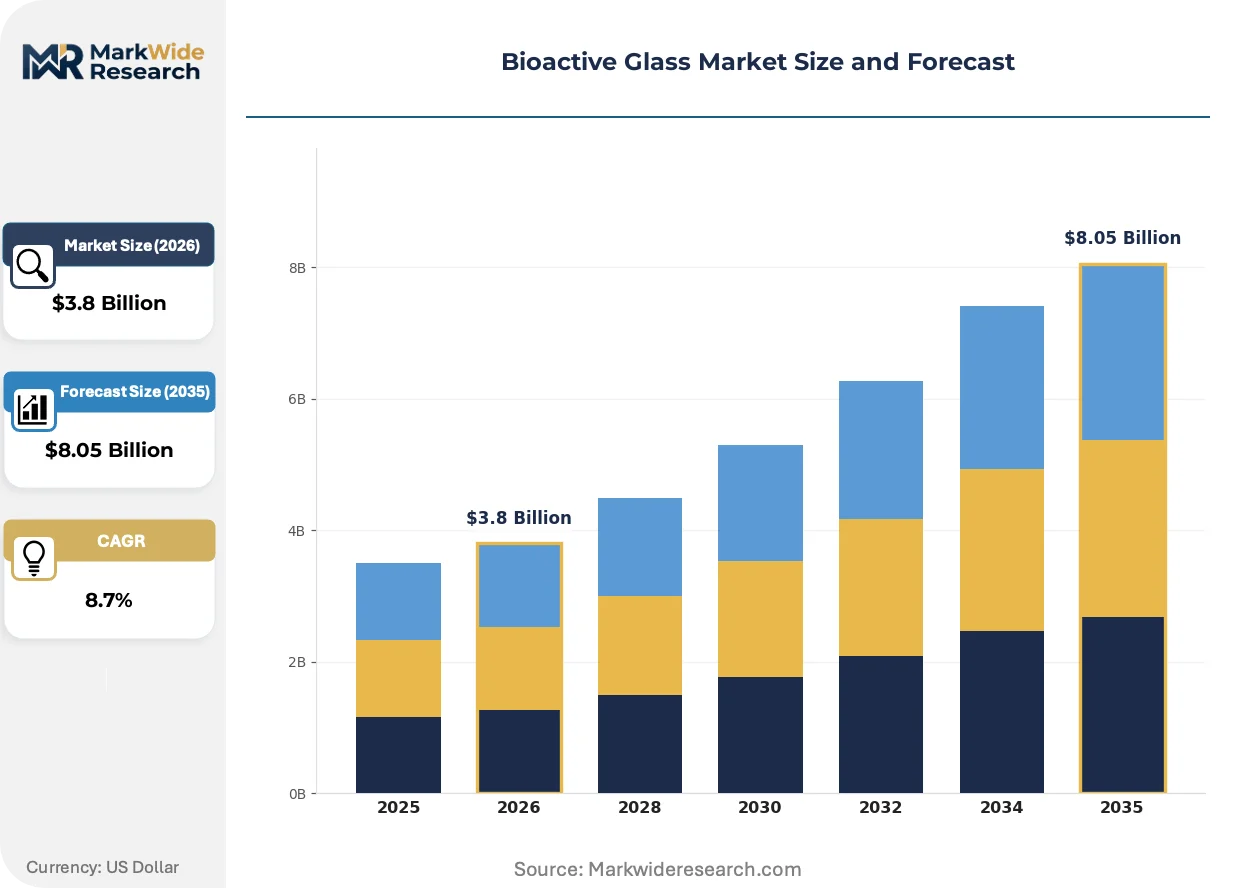
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powders, Discs, Sutures Application: Orthopedics, Dentistry, Wound Healing, Tissue Engineering End User: Hospitals, Clinics, Research Labs, Dental Practices Form: Aqueous, Solid, Gel, Coating |
| Companies Covered | Stryker, BonAlive Biomaterials, SCHOTT, NORAKER, Arthrex, Mo-Sci, Johnson & Johnson, Synergy Biomedical, NovaBone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Glass Market Emerging Trajectories
Boron-doped glass compositions and precision microsphere engineering are redefining performance benchmarks, while regulatory convergence around permanent implant classifications reshapes competitive entry barriers across major markets.
Next-generation boron-containing bioactive glasses are engineered for accelerated ion release kinetics that shorten osteoconduction timelines compared to traditional 45S5 formulations. Orthopedic trauma centers and dental implant specialists are adopting these materials for load-bearing applications where rapid bone bonding is clinically critical. This compositional evolution is modularizing supplier R&D roadmaps around tunable resorption rates rather than fixed degradation profiles.
The EU Medical Device Regulation's permanent implant classification for synthetic bone grafts imposes clinical evidence requirements that exceed prior CE-marking standards under the Medical Device Directive. Manufacturers must now generate prospective clinical data or equivalent scientific literature to support substantial equivalence claims for long-term implantation. Small and mid-cap suppliers without dedicated regulatory affairs infrastructure face particular pressure to outsource dossier preparation or exit the European market entirely.
Hospital value analysis committees are consolidating purchasing authority for bone graft substitutes away from individual surgeon preference cards toward system-level contracts with standardized formularies. Orthopedic service lines negotiate multi-year supply agreements that bundle granule, putty, and strip formulations under single-source arrangements. This procurement centralization is most advanced in United States integrated delivery networks and German hospital federations, where procurement officers now evaluate total episode cost rather than per-unit graft pricing.
Bioactive Glass Market Segmentation
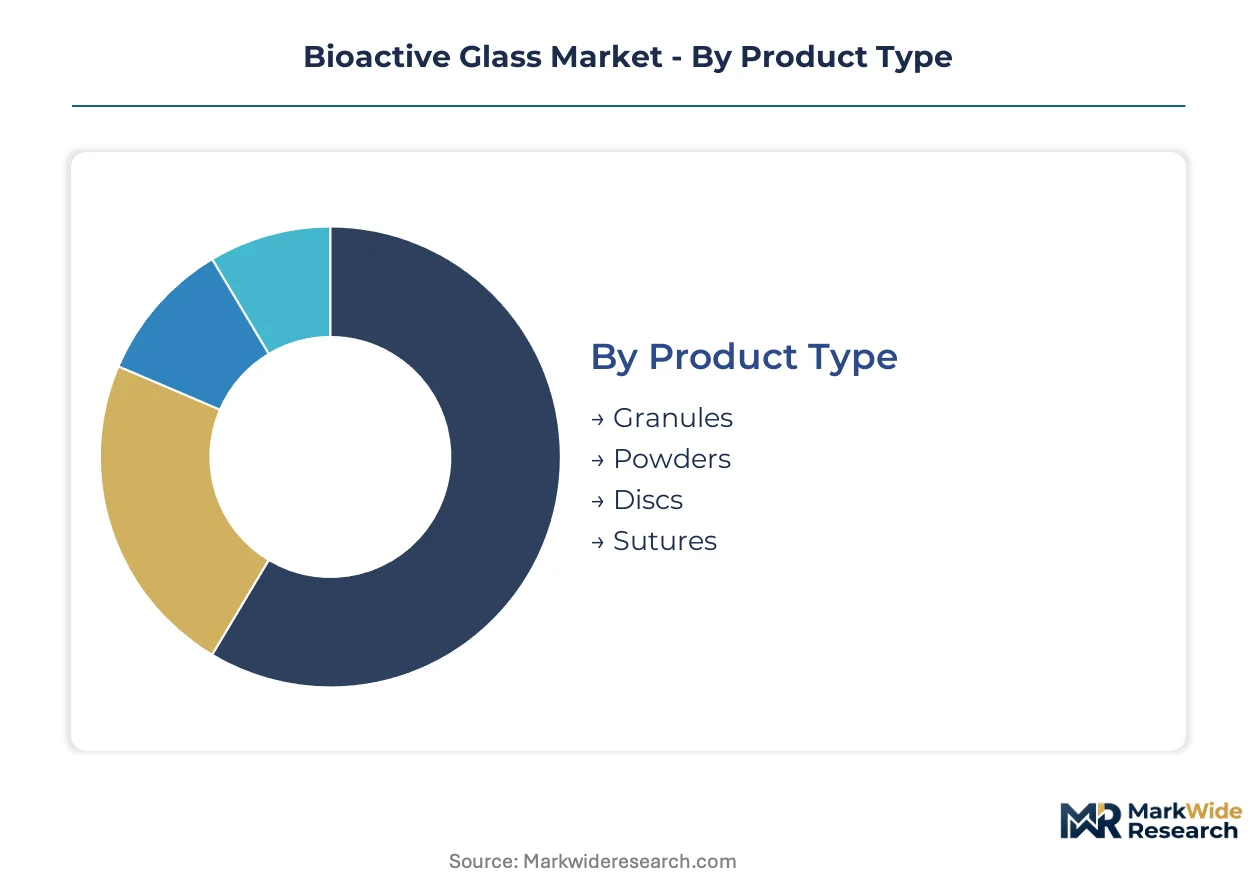
Bioactive glass suppliers configure production assets around form-factor specifications that determine surgical handling properties and regulatory classification pathways. Orthopedic procurement committees evaluate segment portfolios based on validated 510(k) clearance status and total episode cost rather than unit pricing alone.
Product Type:
Surgeon preference for intraoperative handling characteristics drives upgrade cycles from legacy powder formats toward precision-engineered granules and shaped implants.
- Granules:Irregular or spherical particles ranging from 90 to 710 micrometers enable defect-site packing with controlled porosity for vascular ingrowth. Hospital orthopedic service lines in the United States specify granule formulations for spinal fusion procedures where established CPT reimbursement codes secure predictable payment.
- Powders:Finely ground glass particles below 45 micrometers serve as raw material feedstock for putty compounding and custom scaffold fabrication. Research laboratories and specialized trauma centers source powders for patient-specific bone defect reconstruction where off-the-shelf geometries prove inadequate.
- Discs:Preformed cylindrical geometries suit craniomaxillofacial applications requiring load-bearing structural integrity.
- Sutures:Bioactive glass-coated or composite fiber configurations target soft tissue integration alongside bone contact.
Volume placements concentrate in granules; the faster expansion belongs to discs.
Application:
Procedure reimbursement levels and clinical evidence requirements create divergent margin profiles across surgical specialties.
- Orthopedics:Spinal fusion, trauma fixation, and joint reconstruction procedures consume bulk volumes of synthetic graft material. FDA 510(k) clearance pathways for bone graft substitutes shape product development timelines, with substantial equivalence demonstrations requiring biocompatibility data that filters undercapitalized entrants.
- Dentistry:Ridge augmentation, socket preservation, and implant site preparation drive demand for particulate and putty formulations. German and Swiss dental implant specialists specify boron-doped compositions for accelerated osteoconduction in load-bearing maxillofacial applications.
- Wound Healing:Bioactive glass dressings leverage ion release kinetics for antimicrobial and angiogenic effects in chronic ulcer management.
- Tissue Engineering:Three-dimensional scaffolds integrated with mesenchymal stem cell therapies represent regenerative medicine frontiers beyond traditional graft substitution.
Orthopedics commands the dominant revenue share; tissue engineering climbs the fastest.
End User:
Procurement centralization patterns differentiate volume contracting terms across institutional settings.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements bundling granule, putty, and strip formulations under standardized formularies. Value analysis committees in United States health systems now evaluate total episode cost rather than per-unit graft pricing.
- Clinics:Ambulatory surgical centers concentrate demand for pre-mixed putty configurations that minimize preparation time.
- Research Labs:Academic medical centers and contract research organizations source experimental compositions for investigational stem cell scaffold protocols.
- Dental Practices:Individual practitioners and group practices select particulate formulations based on implant manufacturer compatibility.
Hospitals absorb the majority of volume placements; research labs gain share fastest.
Form:
Manufacturing process selection determines ion release kinetics and shelf stability specifications.
- Aqueous:Suspension formulations enable injectable delivery through minimally invasive surgical approaches.
- Solid:Melt-quench derived bulk glass and sintered scaffolds provide structural support for load-bearing defects. Stryker and Mo-Sci maintain captive melting furnaces to control resorption profiles.
- Gel:Organic-bioactive glass composites improve cohesion for contained defect sites.
- Coating:Surface-modified titanium implants command premium positioning in orthopedic and dental hardware channels.
Solid forms dominate volume; coating applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement volumes concentrate in the United States, where aging demographics and established CPT reimbursement codes for spinal fusion procedures sustain market leadership. Germany and Switzerland anchor European demand through specialized dental implant applications. Japan and South Korea represent high-growth Asia-Pacific markets with advanced orthopedic infrastructure.
United States
Integrated delivery networks in Texas and California consolidate purchasing authority for bone graft substitutes under multi-year supply agreements. FDA 510(k) clearance pathways for synthetic graft materials shape product development timelines, with substantial equivalence demonstrations requiring biocompatibility data that filters undercapitalized entrants. The Greater Boston medical technology cluster hosts specialized biomaterials toxicology expertise serving regulatory submission preparation.
Germany
Dental implant specialists in Bavaria and Baden-Württemberg specify boron-doped bioactive glass compositions for accelerated osteoconduction in load-bearing maxillofacial procedures. The EU Medical Device Regulation's permanent implant classification imposes stricter clinical evidence requirements than prior CE-marking standards under the Medical Device Directive. Hospital federations in North Rhine-Westphalia evaluate total episode cost rather than per-unit graft pricing in procurement decisions.
Switzerland
Swissmedic maintains rigorous standards for permanent implant classifications that exceed baseline EU MDR requirements, creating regulatory differentiation for dossier-ready suppliers. The Basel pharmaceutical and medical technology corridor concentrates precision glass microsphere engineering capabilities for controlled resorption profiles. Zurich-based orthopedic research centers integrate bioactive glass scaffolds with investigational stem cell therapies.
Japan
PMDA regulatory frameworks for bone graft substitutes require harmonized biocompatibility data aligned with ISO 10993 international testing standards. The Kanto region around Tokyo hosts advanced orthopedic trauma centers adopting next-generation boron-containing glass formulations for rapid bone bonding applications. Japanese medical device manufacturers pursue strategic partnerships with European glass specialists to secure melt-quench production capabilities.
South Korea
MFDS approval pathways for synthetic bone graft materials accelerate multi-market submissions through recognition of international biocompatibility frameworks. The Seoul Capital Area concentrates hospital procurement volume for spinal fusion and trauma fixation procedures driving granule formulation demand. Daegu-Gyeongbuk medical technology clusters develop coating applications for surface-modified titanium orthopedic implants.
Bioactive Glass Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers invest in captive melt-quench production to secure supply continuity and control ion release kinetics. The vendor base stratifies across three tiers: diversified orthopedic conglomerates with broad hospital purchasing channels, specialized glass engineering firms with precision microsphere capabilities, and regional biomaterials suppliers serving niche dental applications. Strategic archetypes include backward-integrated manufacturers controlling raw material-to-finished-product pipelines, technology licensors monetizing proprietary glass compositions, and contract manufacturers serving private-label hospital formulary contracts. M&A activity and in-house furnace commissioning represent the dominant competitive moves reshaping supply-side positioning.
Among diversified orthopedic suppliers, Stryker and Johnson & Johnson occupy positions anchoring premium-tier hospital contracting through integrated delivery network relationships. Mo-Sci exemplifies the specialized glass engineering archetype, representing precision microsphere capabilities that command positioning in controlled resorption profile segments. These three companies illustrate the competitive tension between scale-driven procurement consolidation and technical specialization in formulation engineering.
| Leading Market Players |
|---|
| Stryker |
| BonAlive Biomaterials |
| SCHOTT |
| NORAKER |
| Arthrex |
| Mo-Sci |
| Johnson & Johnson |
| Synergy Biomedical |
| NovaBone |
| Others |
Supply Flow & Price Mechanics
Hospital value analysis committees in United States integrated delivery networks are consolidating purchasing authority for bone graft substitutes under multi-year supply agreements, forcing suppliers to absorb certification costs and scale melt-quench production capacity to maintain formulary inclusion. This procurement centralization compresses per-unit margins while elevating total episode cost accountability as the dominant pricing metric.
Pricing Analysis
Volume placements in granule formulations for spinal fusion procedures operate on thin margins, while coating applications on titanium implants and precision microsphere engineering for controlled resorption profiles capture premium positioning. Price differentiation rests on FDA 510(k) clearance status and ISO 10993 biocompatibility certification tier, with validated dossiers commanding substantial premiums over unregistered alternatives. Pricing pressure intensifies in standard granule tiers as German hospital federations and United States integrated delivery networks shift toward standardized formularies. Ambulatory surgical centers and clinics exhibit highest price sensitivity due to limited reimbursement flexibility, whereas academic medical centers prioritize clinical evidence over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate qualified backup suppliers for critical raw materials, particularly high-purity silica sand and phosphate precursors drawn from United States, Germany, and specialty chemical suppliers in Japan. Melt-quench production capabilities concentrate among Stryker's captive furnaces, Mo-Sci's precision microsphere operations, and Johnson & Johnson's orthopedic manufacturing network. Supply chain risk centers on single-source vulnerability for medical-grade glass processing equipment requiring validated aseptic environments. Distribution runs through orthopedic service line contracts at integrated delivery networks, with direct-to-hospital logistics displacing traditional distributor intermediaries in high-volume United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioactive glass market is becoming a vertical-integration race where control over melt-quench production furnaces and in-house biocompatibility testing infrastructure determines competitive survival. Suppliers without captive ion-release engineering capabilities face exclusion from premium hospital formulary tiers.
For Market Incumbents: Anticipate margin compression in standard granule segments by accelerating backward integration into high-purity silica sand sourcing and phosphate precursor supply agreements. Defensive consolidation through acquisition of specialized glass microsphere engineering firms in Switzerland and Germany will secure controlled resorption profile capabilities before EU MDR permanent implant classification deadlines filter undercapitalized competitors. For New Entrants and Emerging Players: Boron-doped compositions with accelerated ion release kinetics offer a technology-first wedge into dental implant specialist channels in Bavaria and Baden-Württemberg where rapid osteoconduction commands premium positioning. Target ambulatory surgical centers in the Seoul Capital Area with pre-mixed putty configurations that minimize preparation time, leveraging MFDS recognition of ISO 10993 frameworks for accelerated regulatory clearance. For Investors and Strategic Acquirers: The window for entry favors specialized glass engineering firms with precision microsphere capabilities and established biocompatibility dossiers. Long-term viability hinges on securing hospital system partnerships before procurement centralization completes in United States integrated delivery networks. Watch for FDA reimbursement code expansions covering synthetic grafts in trauma fixation as the inflection signal for addressable procedure volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Melt-Quench Furnace Commissioning | In-house glass melting secures ion release kinetics control and supply continuity for orthopedic graft portfolios. |
| EU MDR Permanent Implant Dossier Preparation | Prospective clinical data generation creates first-mover advantage in European hospital system contracting. |
| Stem Cell Scaffold Integration Partnership | Collaboration with academic medical centers opens regenerative medicine applications beyond traditional bone graft substitution. |
| Titanium Implant Coating Channel Development | Surface modification capabilities capture premium positioning in orthopedic and dental hardware markets. |
| Hospital System Direct Contracting | Multi-year supply agreements with integrated delivery networks lock out distributor-dependent competitors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at major suppliers. FDA 510(k) clearance databases, ISO 10993 biocompatibility registration records, EU MDR notified body submissions, and hospital procurement database extracts provided demand-side validation. Bottom-up volume modeling across granule, powder, disc, and coating form factors triangulated against top-down expenditure estimates from national health accounts.
Granularity-level modeling proceeded at the intersection of product type, application specialty, end-user institution class, and regional regulatory cluster. Orthopedics, dentistry, wound healing, and tissue engineering applications were projected across the analysis window with procedure-volume-linked demand elasticity. CAGRs derived from regression against aging demographic indices, spinal fusion reimbursement code stability, and synthetic graft penetration rates relative to autograft harvesting persistence.
Several conditions sit outside the modeled scope, including breakthrough stem cell therapy regulatory approvals, raw material export restrictions on high-purity silica, and major orthopedic conglomerate M&A activity. Forecasts reflect assumptions around CPT code stability for spinal fusion and EU MDR enforcement consistency. Deviation in FDA substantial equivalence demonstration requirements or payer synthetic graft reimbursement policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
Global High Performance Thermoplastics Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Global Core Materials Market
Advanced Materials
2D Materials Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Graphite Materials Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Cathode Materials Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market