
 Transparent Wood Market | 2026-2036
Transparent Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Wood Market Intelligence
The traditional separation between architectural specification and contractor procurement is collapsing as architects increasingly dictate the use of advanced materials like transparent wood. Stora Enso Oyj leverages its vast forestry and processing expertise to explore large-scale production pathways for this novel material. In contrast, InventWood Inc. specializes in developing unique material properties derived from its university research origins. Woodoo differentiates by focusing on augmented wood for applications in automotive and luxury goods, extending beyond simple transparency.
Transparent wood is a composite material produced by removing lignin from a wood veneer and infiltrating the remaining porous cellulose scaffold with a refractive index-matched polymer. This process yields a material with high optical transmittance and haze, combined with the mechanical strength and low thermal conductivity of wood. Within end-user segments, the construction industry's demand for innovative structural components and energy-saving solutions is driving initial commercialization. Chemical modification technology currently dominates production methods, with engineered wood formats representing the most viable product type for early adoption.
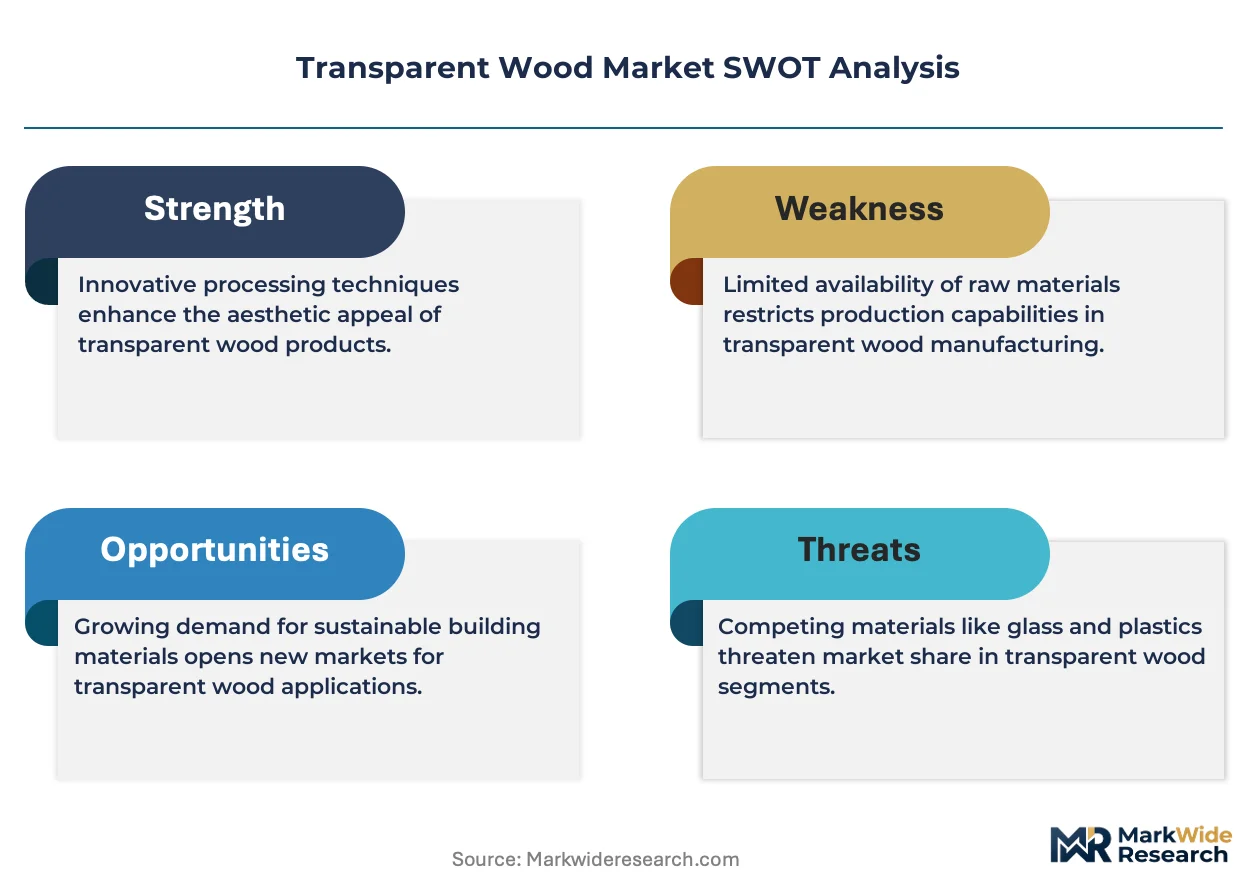
Building codes and standards, such as those governed by ISO technical committees and integrated into national frameworks like the EU's CE marking requirements, are critical for market entry. Environmental regulations, including the EU Green Deal and sustainability criteria in Japan, favor its bio-based and insulating properties over traditional glass and plastics. Scaling production to meet cost and volume targets for mainstream construction remains the central challenge for all stakeholders.
Market Dynamics
The central force shaping the transparent wood market is the direct regulatory pressure for decarbonization in the built environment. Mandates like the EU Green Deal are creating a non-negotiable demand pull for high-performance, bio-based building materials, positioning transparent wood as a potential alternative to incumbent glass and plastics.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and national sustainability criteria in countries like Japan create a strong incentive for adopting materials with superior thermal insulation and a lower carbon footprint, directly benefiting transparent wood's market entry.
- Construction Sector Demand:The architectural and construction industries require novel materials for energy-efficient building facades, smart windows, and unique structural elements, providing the primary end-use application for initial commercialization efforts.
- Process Technology Advancement:Progress in chemical modification techniques, specifically the delignification and polymer infiltration processes, is improving the optical and mechanical properties of the final composite, making it a more viable engineered product.
Market Restraints
- High Production Costs:The multi-step manufacturing process, involving expensive chemical inputs for lignin removal and specialized refractive index-matched polymers, results in a final material cost that is not competitive with traditional architectural glass.
- Limited Production Scale:Manufacturing remains concentrated in laboratory and small-scale pilot facilities, primarily in Northern Europe, which structurally constrains volume availability and prevents economies of scale needed for mainstream construction projects.
- Established Incumbent Materials:High-performance architectural glass, polycarbonates, and other advanced polymers are mature, standardized, and cost-effective substitutes that hold a dominant position in the building and automotive sectors, presenting a significant barrier to displacement.
Strategic Opportunities
- Automotive and Luxury Goods:Applications in automotive interiors, consumer electronics, and luxury product design offer a pathway to commercialization where high material cost is less of a barrier and unique aesthetics are highly valued.
- Building Code Integration:Proactive engagement with standards bodies like ISO and national building code commissions in North America could accelerate the creation of standards, unlocking the larger structural components market.
- Geographic Expansion in Asia:Targeting the Japanese and South Korean markets, where there is a strong tradition of wood in construction combined with a governmental push for sustainable technology, presents a key growth opportunity.
Industry Challenges
- Standardization and Certification:The absence of specific ISO standards and the long timeline to achieve national building code approvals or CE marking for structural use represent a critical operational hurdle for market access.
- Capital Investment for Scale-up:Transitioning from pilot-scale batches to industrial-volume production requires significant capital expenditure on specialized chemical reactors and polymer processing equipment, a major challenge for early-stage companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Wood Market |
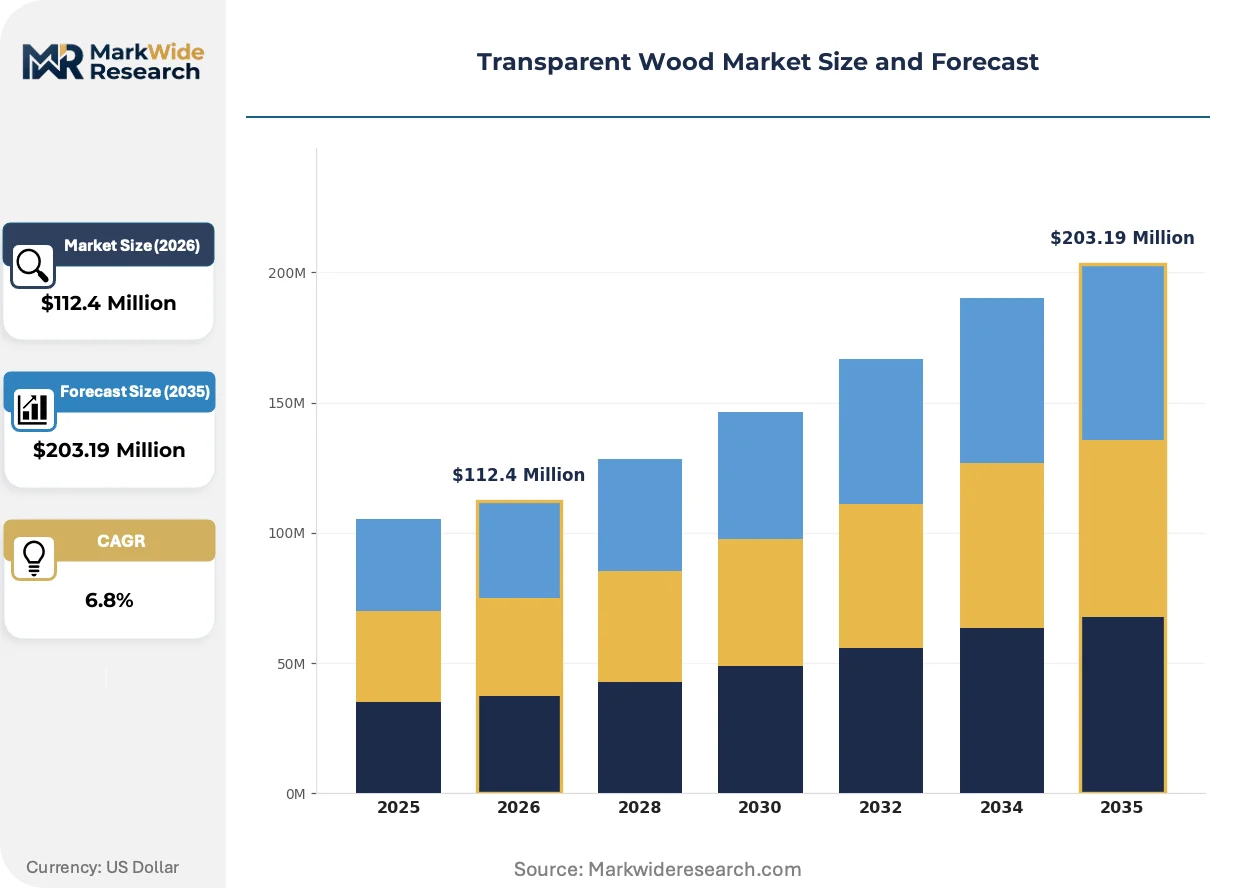
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $203.19 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineered Wood, Laminated Wood, Coated Wood, Composite Wood End User: Construction, Furniture, Automotive, Aerospace Application: Interior Design, Structural Components, Energy Solutions, Optical Applications Technology: Thermal Treatment, Chemical Modification, Bio-based Treatments, Laser Processing |
| Companies Covered | UPM-Kymmene Corporation, Transparent Wood Technologies, Stora Enso Oyj, KTH Royal Institute of Technology, VTT Technical Research Centre of Finland, Woodoo, Sumitomo Forestry Co., Ltd., Nanollose, InventWood Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Wood Market Strategic Shifts & Innovations
Material science innovation, driven by sustainability imperatives, is reshaping the path from laboratory concept to commercial reality. The focus is on optimizing production processes to balance optical performance with mechanical strength, targeting initial applications where material novelty commands a premium.
Polymer infiltration of a delignified wood scaffold is the core technology that yields a strong, translucent composite material. Architectural firms and university research teams are the primary adopters, specifying the material for high-profile pilot projects and academic studies. This dual-track development is bifurcating the material’s evolution into a high-cost aesthetic product for niche designs and a separate, long-term research path toward scalable structural components.
The EU Green Deal, particularly its Renovation Wave strategy, establishes aggressive targets for improving building energy efficiency across the Union. This regulatory framework creates a powerful incentive for materials with superior thermal insulation and lower embodied carbon compared to conventional glass and concrete. The construction sector in Northern Europe, especially in Sweden and Finland, is most affected and is responding by integrating transparent wood into demonstration projects for energy-saving facades.
A notable behavioral change involves architects directly specifying novel materials, circumventing traditional contractor-led procurement models. This dynamic disrupts the conventional, cost-centric value chain by prioritizing performance characteristics, sustainability credentials, and unique aesthetics. This trend is most apparent within high-end commercial and institutional building projects in Europe and North America, where design innovation is a key differentiator.
Transparent Wood Market Segmentation
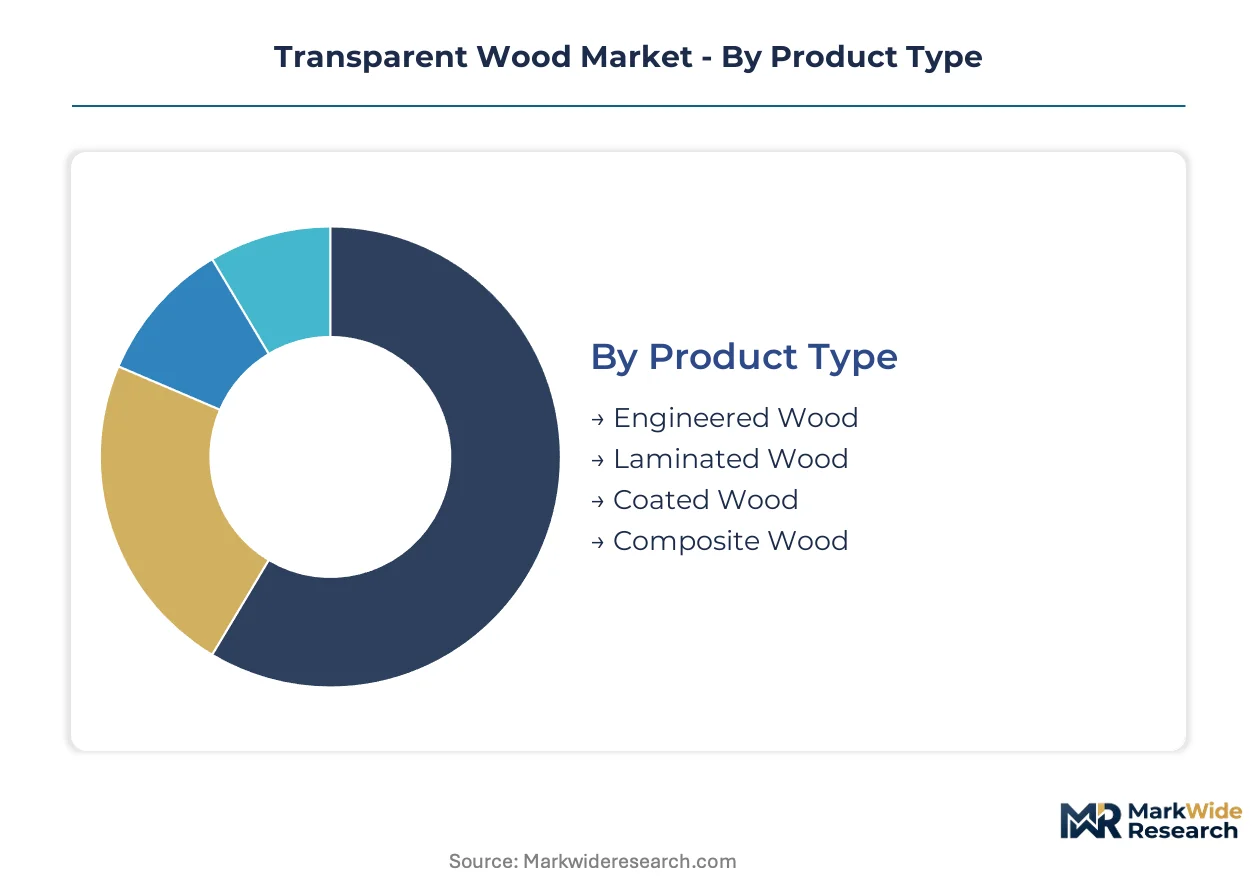
The transparent wood market is differentiated across several key dimensions, providing insight into the material's evolving commercial landscape and its varied adoption pathways. Understanding these segmentations reveals where value is currently captured and where future growth efforts are likely to concentrate.
Product Type:
The product type segmentation for transparent wood highlights the varying degrees of material substitution pressure from conventional alternatives like glass and plastics.
- Engineered Wood:This product type involves significant modification of wood structure to achieve specific properties, often including delignification and polymer infiltration for optical transparency. Demand is concentrating in Northern European construction for energy-efficient facades due to regulatory mandates like the EU Green Deal.
- Laminated Wood:This category includes transparent wood layers bonded with other materials, enhancing structural integrity or aesthetic appeal. These products find utility in specialized architectural elements where composite strength is required.
- Coated Wood:Transparent coatings applied to natural or modified wood surfaces offer enhanced durability and specific optical characteristics without full material transformation. Coated wood appeals to furniture and interior design applications for surface protection.
- Composite Wood:These materials integrate transparent wood with other polymer or natural fibers, creating hybrid products with tailored mechanical and optical performance. Initial demand comes from automotive interiors where unique material aesthetics are valued.
Engineered Wood retains volume leadership; Composite Wood holds the steepest expansion curve.
End User:
Transparent wood demand across end-user segments is largely defined by specific application requirements, ranging from aesthetic to structural performance needs.
- Construction:This segment utilizes transparent wood for energy-efficient building envelopes, smart windows, and innovative structural components. The construction industry in Europe drives initial commercialization efforts due to stringent decarbonization targets.
- Furniture:Transparent wood offers unique aesthetic and tactile properties for high-end furniture design, including tabletops and decorative panels. This sector values material novelty and premium design elements.
- Automotive:Transparent wood finds application in vehicle interiors for decorative trim, lighting elements, and potentially lightweight structural components. Luxury automotive brands are exploring its use for distinctive cabin aesthetics.
- Aerospace:This sector considers transparent wood for lightweight interior panels and non-structural components, seeking reduced weight and enhanced design flexibility. Material certification for aerospace applications remains a long-term challenge.
Construction accounts for substantial demand, while Automotive presents significant future potential.
Application:
The application segmentation reveals how different customer priorities, from energy efficiency to unique aesthetics, are driving transparent wood adoption.
- Interior Design:This application focuses on aesthetic appeal, using transparent wood for decorative panels, room dividers, and lighting fixtures. Architects frequently specify transparent wood for high-profile commercial and institutional projects.
- Structural Components:Transparent wood aims to replace traditional structural materials in specific load-bearing applications where light transmission is also desired. Development efforts in Northern Europe target this segment for novel building designs.
- Energy Solutions:Applications here leverage transparent wood's superior thermal insulation properties for energy-efficient windows, skylights, and building facades. The EU Green Deal provides a strong regulatory incentive for these solutions.
- Optical Applications:This segment explores transparent wood for advanced optical devices, sensors, or specialized lighting elements where high transparency and haze control are critical. University research teams are primary adopters for experimental studies.
Demand for Energy Solutions drives immediate commercialization, with Structural Components representing a critical long-term development.
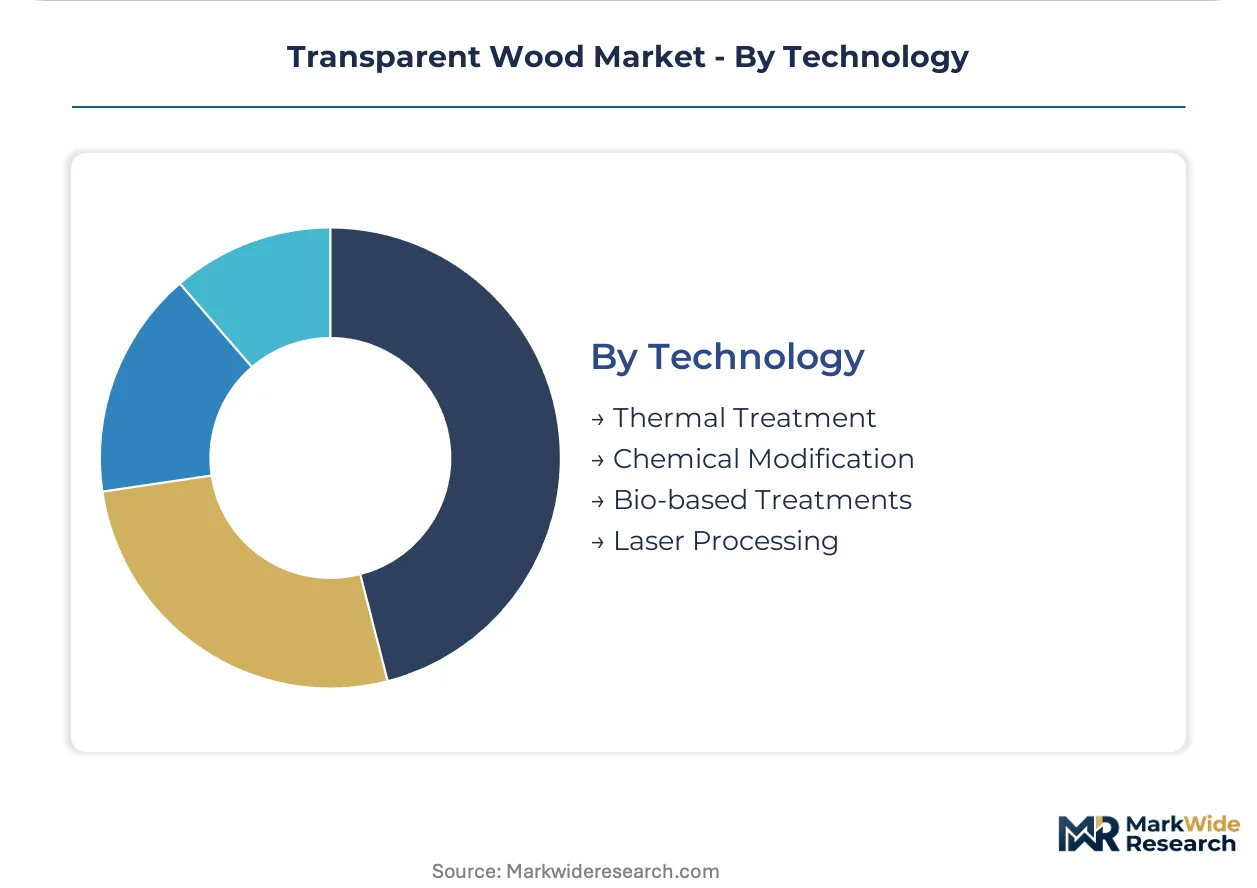
Technology:
Technology segmentation illustrates the current dominance of certain production methods and the emergence of novel approaches for transparent wood manufacturing.
- Thermal Treatment:This method uses heat to modify wood properties, potentially enhancing transparency or preparing it for further processing. Thermal treatments are often a preparatory step before chemical modification.
- Chemical Modification:This dominant technology involves the removal of lignin from wood veneers and subsequent infiltration with refractive index-matched polymers. This process yields a strong, translucent composite material with high optical transmittance.
- Bio-based Treatments:These emerging technologies utilize environmentally friendly chemicals or biological agents for lignin removal and polymer infiltration, aligning with sustainability goals. Research institutes in Finland are exploring these pathways.
- Laser Processing:Laser-based techniques are being investigated for precise material structuring and surface modification to control light transmission or create intricate patterns. This technology holds promise for high-value optical applications.
Chemical Modification currently leads production methods, while Bio-based Treatments are gaining traction for their sustainable attributes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transparent wood demand concentrates among specific buyer archetypes, particularly architects and construction firms seeking advanced materials. Early commercialization efforts and research are heavily focused within Northern Europe. This region actively pursues energy-saving solutions for building facades, driven by sustainability targets.
Sweden
Demand for structural components and energy-efficient facades drives Swedish transparent wood development. The EU Green Deal provides significant regulatory tailwinds for sustainable building materials. Research institutes like KTH Royal Institute of Technology in Stockholm are central to material science innovation and pilot projects. This concentration positions Sweden as a key development hub.
Finland
Finnish construction firms seek novel materials for energy-saving solutions. National sustainability criteria and the EU's Renovation Wave strategy support bio-based material adoption. VTT Technical Research Centre of Finland in Espoo actively explores bio-based treatments and production pathways. This fosters a strong R&D ecosystem.
Japan
Japanese construction values traditional wood use combined with advanced material innovation. Governmental pushes for sustainable technology align with transparent wood's bio-based properties. Companies like Sumitomo Forestry Co., Ltd. in Tokyo are exploring applications and market entry. This creates a receptive environment for new materials.
United States
Demand in the United States stems from high-performance architectural projects and smart window applications. Building codes and standards bodies in North America are crucial for market entry. University research hubs, particularly on the East and West Coasts, are advancing material science and prototyping. This supports diversified application development.
Germany
German construction emphasizes energy efficiency and durable building envelopes. The country's strong environmental regulations, aligned with the EU Green Deal, favor innovative bio-based solutions. Research centers and specialized material manufacturers in regions like Bavaria are contributing to industrial scaling efforts. This supports broader adoption across the EU.
Transparent Wood Market Key Industry Players
Player mix skews toward specialized material science firms and large integrated forestry companies. The market exhibits an early-stage, fragmented structure, with many players emerging from academic research. Strategic archetypes include R&D-focused startups, established forestry giants, and niche application developers. Companies are pursuing strategic partnerships and technology licensing to accelerate material development and market access.
Specialists in material innovation include InventWood Inc., which leverages university research origins for unique material properties. Finnish forestry giant Stora Enso Oyj represents integrated players exploring large-scale production pathways for transparent wood. Woodoo exemplifies companies targeting niche applications like automotive interiors and luxury goods with augmented wood, extending beyond simple transparency. These firms anchor distinct segments of the developing transparent wood ecosystem, from fundamental research to premium product integration, shaping its early commercial trajectory.
| Leading Market Players |
|---|
| UPM-Kymmene Corporation |
| Transparent Wood Technologies |
| Stora Enso Oyj |
| KTH Royal Institute of Technology |
| VTT Technical Research Centre of Finland |
| Woodoo |
| Sumitomo Forestry Co., Ltd. |
| Nanollose |
| InventWood Inc. |
| Others |
Cost & Logistics Intelligence
Project-based contracts for transparent wood currently lock in supply access and price visibility for early adopters, reflecting the material's customized application in high-profile construction and automotive pilot programs. These agreements mitigate risk for both producers and buyers in a nascent market.
Pricing Analysis
Cost-plus contracts, often indexed to polymer and specialized chemical input costs, currently define transparent wood pricing for early commercialization projects. Pricing stratifies across premium, standard, and economy tiers based on optical performance, mechanical strength, and specific project customization requirements. Pricing softness is anticipated as production scales and economies of scale emerge. The construction sector exhibits high price sensitivity, while luxury automotive and interior design applications value unique aesthetics over cost.
Supply Chain Analysis
The limited availability of specialized refractive index-matched polymers currently represents a chokepoint for scaling transparent wood production. Supply concentration centers in Northern Europe, particularly Sweden and Finland, for advanced research and pilot manufacturing, alongside Japan's expertise in wood processing. The reliance on unique chemical inputs and low production volumes creates a single-source vulnerability. Direct sales channels to architectural specifiers and high-end construction firms dominate early distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transparent wood market presents a defensive-moat story, primarily driven by regulatory entrenchment from the EU Green Deal and the high switching costs associated with material certification and building code integration. This creates a significant barrier for new market entrants.
For Market Incumbents:Consolidate R&D efforts to accelerate production scale-up and cost reduction, countering the pricing advantage of incumbent architectural glass. Secure long-term supply agreements for specialized polymers and delignification chemicals to mitigate raw material price volatility. Invest heavily in CE marking and ISO certification pathways for structural components to unlock mainstream construction adoption. Vertical integration into key chemical inputs offers a strategic lever.
For New Entrants and Emerging Players:Differentiate on unique aesthetic and performance properties, targeting niche applications where material novelty commands a premium, such as luxury automotive interiors or high-end consumer electronics. The interior design segment offers a penetrable entry point due to less stringent regulatory hurdles than structural components. A direct-to-designer go-to-market strategy, emphasizing custom solutions and unique visual appeal, can bypass traditional procurement models.
For Investors and Strategic Acquirers:Specialized material science firms with patented delignification and polymer infiltration technologies represent attractive acquisition targets for long-term growth. The market's viability remains strong over the coming decade, anchored by global decarbonization mandates and the demand for bio-based building materials. Watch for the successful completion of the first large-scale, certified structural transparent wood project as a key inflection indicator for broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-based Treatments | This initiative aligns production with EU Green Deal sustainability goals, enhancing market acceptance. |
| Accelerate CE Marking for Structural Use | Achieving CE marking unlocks the larger European structural components market for advanced wood materials. |
| Form Strategic R&D Partnerships | Partnerships with KTH Royal Institute of Technology accelerate material science innovation and scale-up efforts. |
| Secure Polymer Supply Chains | Securing long-term contracts for specialized polymers mitigates raw material price volatility for producers. |
| Target Automotive Interior Applications | Automotive applications offer a pathway to commercialization where aesthetic value outweighs initial material cost. |
Research Approach
A spread of perspectives from architectural specifiers, material scientists, construction project managers, and chemical suppliers converged on the working assumptions for the transparent wood market. This involved combining insights from primary interviews with rigorous secondary validation from ISO technical committee reports, EU Green Deal policy documents, and university research publications. Bottom-up data collection was triangulated with top-down market sizing for accuracy.
Product Type, End User, Application, Technology, and regional adoption patterns formed the core segmentation dimensions modeled across the analysis window. Compound Annual Growth Rates were derived through a combination of regression analysis on historical data and expert consensus projections over the projection horizon. Key forecast inputs included evolving regulatory timelines for building codes and ongoing advancements in polymer science.
The analysis sits within stated boundaries; outcomes outside significant shifts in raw material costs or unexpected delays in building code integration would require recalibration. Forecasts reflect assumptions concerning production scale-up and market acceptance. Practitioners should keep alternative scenarios live as material science innovations and regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Global Core Materials Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
2D Materials Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Wood Foam Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Global Thermal Interface Materials Market