
 Solar Encapsulation Materials Market | 2026-2036
Solar Encapsulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Encapsulation Materials Market Outlook
China is tilting global encapsulant supply through aggressive ethylene-vinyl acetate expansion and polyolefin capacity additions. Hangzhou First PV Material leverages integrated resin-to-sheet manufacturing to sustain cost leadership across Asia-Pacific. Dow Inc. anchors North American supply through ionomer and silicone product lines tailored to bifacial module architectures. DuPont differentiates via Tedlar backsheet and encapsulant combinations that command premium positioning in utility-scale tenders.
Solar encapsulation materials are polymer sheets, typically 0.4–0.8 mm thick, laminated between glass and cell layers to provide electrical insulation, moisture barrier protection, and mechanical adhesion across a 25-year service life. EVA dominates installed volume due to decades of process compatibility with standard lamination cycles, though polyolefin gains share in bifacial and TOPCon configurations requiring enhanced PID resistance and lower water vapor transmission rates. Photovoltaic modules represent the overwhelming application endpoint, while building integrated photovoltaics constitutes a margin-rich niche where aesthetic and thermal performance specifications command specialized silicone and thermoplastic formulations.
FDA oversight of polymer additives intersects with EPA chemical safety reviews to shape encapsulant formulation choices in the United States, while REACH and RoHS compliance gates European market access and restricts certain crosslinking chemistries. China's GB standards and MIIT industrial policy directives accelerate domestic substitution targets for imported encapsulant resins. Stakeholders must monitor evolving module efficiency roadmaps and corresponding encapsulant refractive index requirements as cell architectures shift toward heterojunction and tandem designs.
Market Dynamics
Module architecture bifurcation between monofacial and bifacial designs is fragmenting encapsulant specifications, forcing suppliers to maintain parallel resin formulations and qualification cycles.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated gases accelerate fluorine-free polyolefin adoption in European utility-scale tenders, creating compliant supply premiums.
- Bifacial module deployment:Double-glass configurations demand enhanced PID-resistant encapsulants with lower water vapor transmission, expanding addressable material value per watt.
- China MIIT industrial policy:Domestic substitution mandates for imported EVA resins localize supply chains and reduce foreign exchange exposure for module integrators.
Market Restraints
- Ethylene-vinyl acetate resin concentration:Three Asian petrochemical complexes control over half of solar-grade EVA supply, creating input vulnerability for non-integrated sheet producers.
- Crosslinking chemistry restrictions:REACH substance evaluations limit peroxide initiator options, forcing reformulation cycles that extend qualification timelines.
- Thermoplastic polyolefin processing:Lower lamination temperature requirements demand capital retooling incompatible with legacy EVA curing lines.
Strategic Opportunities
- Building-integrated photovoltaics:Aesthetic and thermal performance specifications in commercial facades command specialized silicone encapsulant premiums.
- Heterojunction cell compatibility:Low-temperature lamination requirements create white space for ionomer formulations with superior UV stability.
- US Inflation Reduction Act:Domestic content bonuses incentivize North American encapsulant sheet production co-located with module assembly.
Industry Challenges
- Polymer compounding expertise:Formulation chemistry skill gaps constrain rapid scaling of polyolefin capacity to match EVA process maturity.
- 25-year reliability certification:Accelerated aging test protocols require 3,000+ hour qualification cycles that delay new material commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Encapsulation Materials Market |
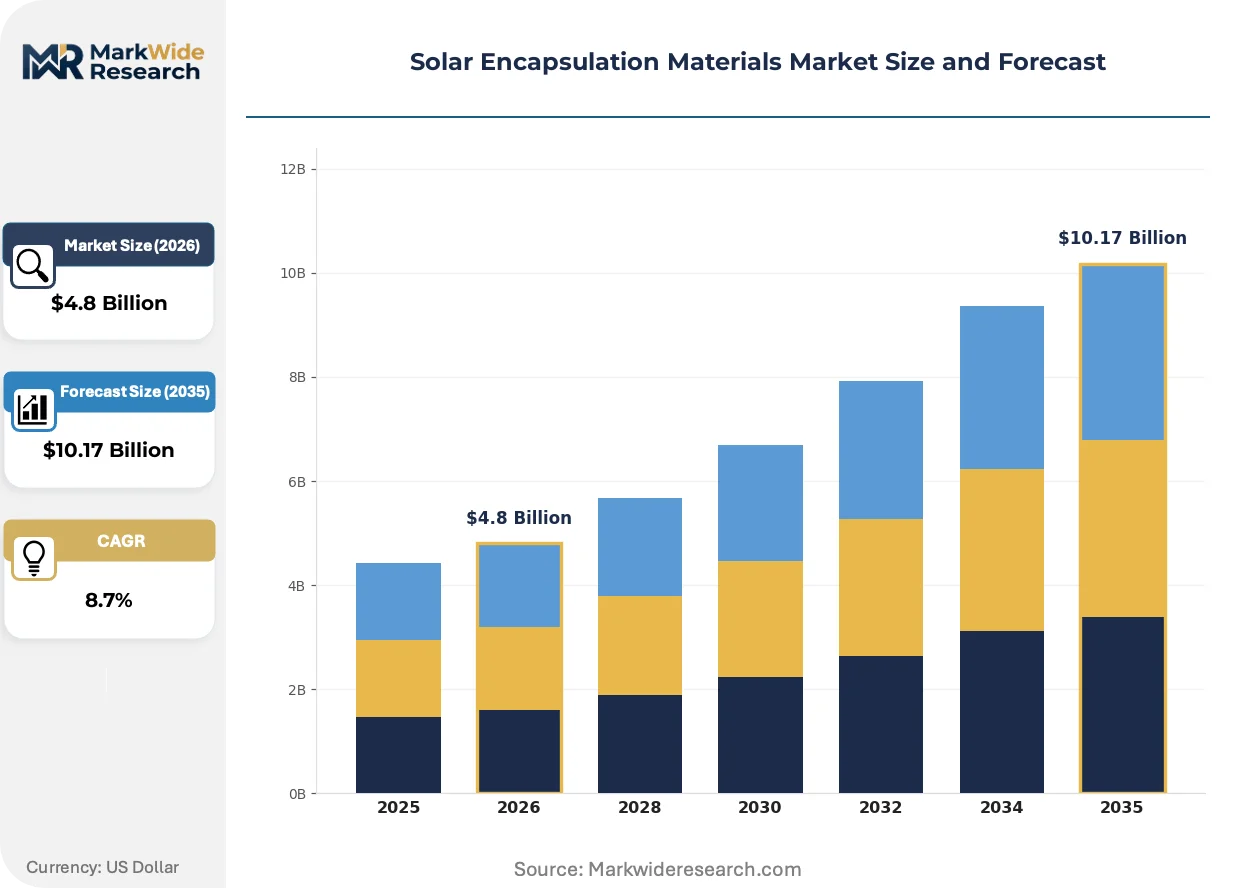
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: EVA, Polyolefin, Polyurethane, Silicone Application: Photovoltaic Modules, Concentrated Solar Power, Thin-Film Technology, Building Integrated Photovoltaics End User: Manufacturers, Distributors, Installers, Research Institutions Packaging Type: Bulk Packaging, Roll Packaging, Sheet Packaging, Custom Packaging |
| Companies Covered | Mitsui Chemicals Inc., Kuraray Co. Ltd., Minnesota Mining and Manufacturing Company, Hangzhou First PV Material Co. Ltd., STR Holding Inc., Dow Inc., 3M, Isovoltaic AG, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Encapsulation Materials Market Strategic Shifts
Encapsulant technology trajectories diverge along cell architecture lines, with material suppliers racing to match refractive index and thermal expansion requirements of emerging high-efficiency designs.
Polyolefin elastomer formulations are migrating from niche bifacial applications toward mainstream adoption in TOPCon and heterojunction modules. Tier-1 module producers in Asia-Pacific have accelerated qualification timelines from 18 to 9 months. This compression is forcing EVA incumbents to defend volume through price repositioning rather than performance differentiation.
The EU Green Deal's carbon border adjustment mechanism tightens embodied carbon accounting for imported encapsulant sheets. Module buyers now request polymer-grade life-cycle assessments upstream of lamination. European tender evaluations increasingly weight Scope 3 emissions alongside levelized cost of electricity.
Direct contracting between module makers and resin producers is displacing merchant sheet distribution in high-volume procurement. Integrated petrochemical-to-module conglomerates in China and South Korea bypass traditional encapsulant converters entirely. This channel consolidation concentrates margin capture at resin production nodes.
Solar Encapsulation Materials Market Segmentation
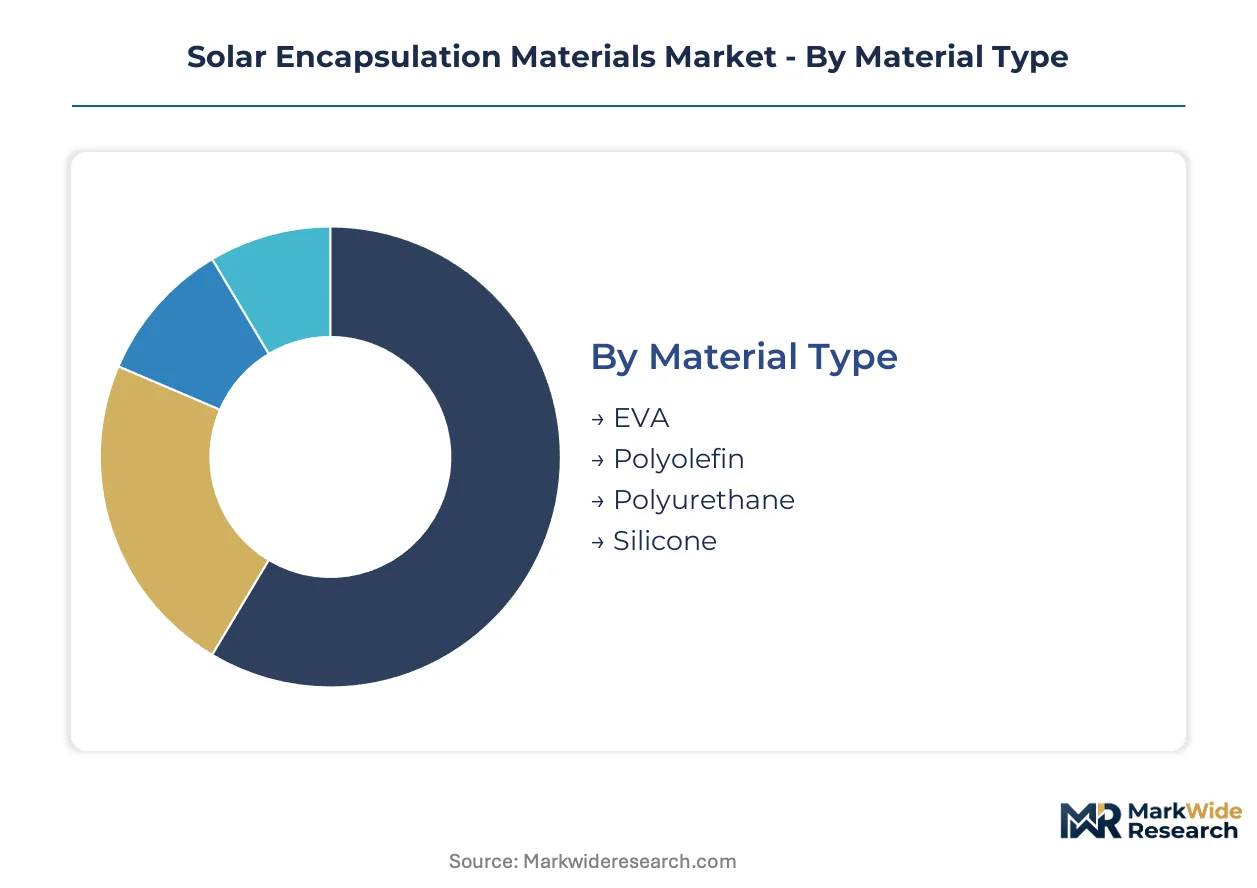
Encapsulant procurement patterns diverge sharply across material chemistries and module architectures, with specification requirements tightening as cell efficiency roadmaps advance. Segmentation clarity enables suppliers to align resin formulation investments against qualified demand pools rather than speculative capacity.
Material Type:
Cost tier stratification separates incumbent commodity formulations from premium alternatives commanding qualification premiums in next-generation modules.
- EVA:Ethylene-vinyl acetate copolymers with 28-33% vinyl acetate content deliver proven process compatibility across standard lamination cycles. Procurement concentrates among Chinese module integrators leveraging Hangzhou First PV Material's integrated resin-to-sheet supply. Peroxide crosslinking chemistry faces REACH substance scrutiny in European tenders.
- Polyolefin:Thermoplastic elastomer formulations enable lower-temperature lamination compatible with heterojunction cell temperature constraints. Demand is rotating up the share rankings in bifacial and TOPCon deployments requiring enhanced PID resistance and reduced water vapor transmission rates versus EVA baselines.
- Polyurethane:Castable systems serving niche concentrated solar power receiver applications where thermal cycling tolerance exceeds sheet encapsulant limits.
- Silicone:Two-part addition-cure chemistry dominates building-integrated photovoltaic facades where optical clarity and thermal stability specifications command formulation premiums.
EVA holds installed capacity. Polyolefin is climbing the fastest through qualification pipelines.
Application:
Volume distribution across application endpoints reflects module architecture bifurcation between utility-scale commoditization and specialized building integration.
- Photovoltaic Modules:Crystalline silicon laminates represent the overwhelming demand endpoint, with encapsulant specifications fragmenting between monofacial p-type and bifacial n-type configurations. Procurement scales through direct resin-to-module contracting that displaces merchant sheet distribution.
- Building Integrated Photovoltaics:Aesthetic performance requirements including color matching, thermal transmittance control, and structural glazing integration command specialized silicone and thermoplastic formulations at margin premiums. European Green Deal procurement increasingly weights embodied carbon in tender evaluations.
- Concentrated Solar Power:Receiver tube and dish-Stirling applications utilize high-temperature silicone and ceramic-composite encapsulants outside standard sheet formats.
- Thin-Film Technology:Cadmium telluride and CIGS modules employ distinct encapsulation architectures with glass-glass laminates or barrier film substitutes reducing polymer sheet intensity per watt.
Photovoltaic Modules anchor volume procurement. Building Integrated Photovoltaics is expanding most quickly as a margin capture opportunity.
End User:
Customer type determines specification authority and channel economics across the value chain.
- Manufacturers:Tier-1 module producers with in-house lamination lines drive formulation qualification and direct resin contracting. Procurement is consolidating among integrated petrochemical-to-module conglomerates in China and South Korea.
- Distributors:Merchant sheet stocking roles are compressing as direct manufacturer-resin relationships displace intermediate inventory positions.
- Installers:Rooftop and utility-scale EPCs specify encapsulant indirectly through module sourcing decisions rather than direct material procurement.
- Research Institutions:National laboratories and university programs pilot next-generation encapsulant formulations including ionomer and bio-based alternatives ahead of commercial qualification.
Manufacturers control specification authority. Research Institutions are rotating up the influence rankings through roadmap-setting partnerships.
Packaging Type:
Supply chain configuration determines format economics from resin production through module lamination.
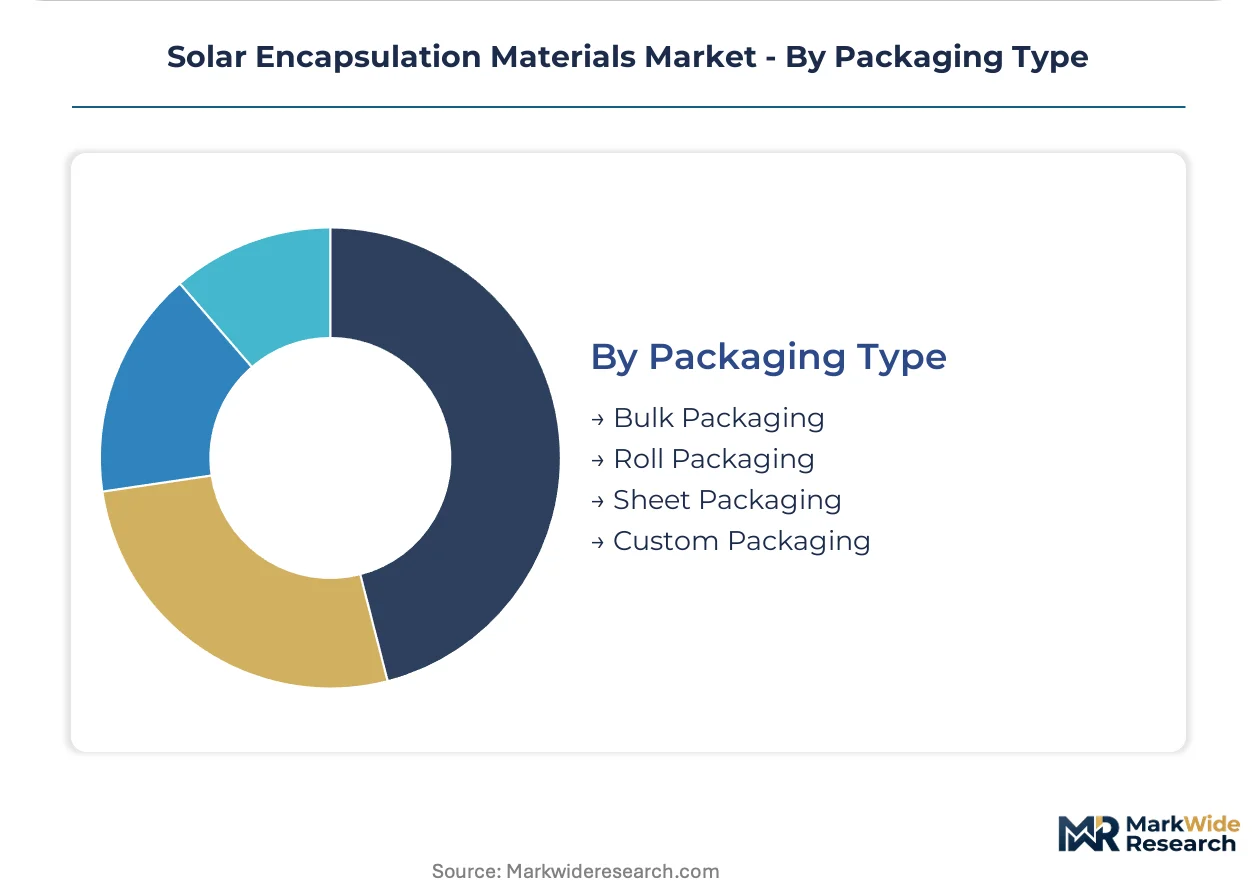
- Roll Packaging:Continuous wound sheets dominate high-volume module assembly lines, with width standardization at 1.1m and 1.3m matching common glass formats. Logistics optimization favors sea-container loading efficiency.
- Sheet Packaging:Cut-to-size formats serve specialty module producers and building-integrated photovoltaic fabricators requiring non-standard dimensions.
- Bulk Packaging:Pellet and liquid resin shipments feed integrated sheet extrusion operations at major module manufacturing campuses.
- Custom Packaging:Cleanroom and nitrogen-purged formats address heterojunction and tandem cell lamination where contamination sensitivity exceeds standard handling protocols.
Roll Packaging holds throughput dominance. Custom Packaging is gaining share fastest through next-generation cell qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT industrial policy directives anchor Chinese supply chain localization. The EU F-Gas Regulation and US Inflation Reduction Act reshape procurement patterns across three continents. Module assembly clusters concentrate where resin-to-sheet integration minimizes logistics exposure.
China
Utility-scale deployment drives encapsulant procurement at unprecedented scale. GB standards and MIIT substitution mandates accelerate domestic EVA resin capacity expansion. Hangzhou First PV Material anchors the Yangtze River Delta cluster through integrated manufacturing from petrochemical feedstock to finished sheet.
United States
Domestic content bonuses under the Inflation Reduction Act incentivize co-located encapsulant production. EPA chemical safety reviews intersect with FDA polymer additive oversight to constrain formulation choices. Southeast module assembly corridors attract sheet extrusion investment to capture IRA incentives.
Germany
REACH substance evaluations restrict peroxide crosslinking chemistries in European tenders. The EU Green Deal's carbon border adjustment mechanism tightens embodied carbon accounting for imported sheets. Bavaria's industrial corridor hosts qualification laboratories serving continental module producers.
South Korea
Bifacial module exports drive demand for PID-resistant polyolelin formulations. MFDS industrial policy supports petrochemical-to-module conglomerate integration. Busan-Ulsan chemical complexes supply resin to captive sheet operations serving Asia-Pacific module assembly.
India
PLI scheme production-linked incentives attract module manufacturing investment requiring qualified encapsulant supply. BIS standards and CEA grid connectivity regulations shape material specifications for domestic tenders. Gujarat's solar parks anchor procurement concentration for utility-scale deployment.
Solar Encapsulation Materials Market Competitive Environment
Integrated petrochemical conglomerates and specialized sheet converters split the market along capital intensity lines. Three distinct strategic archetypes occupy competitive positions: resin-to-sheet integrators, merchant extrusion specialists, and polymer science innovators. Capacity expansion and direct contracting with module makers represent the dominant competitive moves, displacing traditional distribution channels.
Within the integrated archetype, Hangzhou First PV Material Co. Ltd. exemplifies backward control over resin supply chains. Dow Inc. and DuPont occupy positions as polymer science innovators with formulation expertise spanning multiple chemistries. Kuraray Co. Ltd. represents the specialized converter tier with differentiated elastomer capabilities.
| Leading Market Players |
|---|
| Mitsui Chemicals Inc. |
| Kuraray Co. Ltd. |
| Minnesota Mining and Manufacturing Company |
| Hangzhou First PV Material Co. Ltd. |
| STR Holding Inc. |
| Dow Inc. |
| 3M |
| Isovoltaic AG |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor channels solar-grade EVA resin from petrochemical complexes to module assembly campuses, with logistics costs amplifying price spreads between integrated resin-to-sheet producers and merchant extrusion specialists. This corridor's container economics concentrate margin capture at upstream resin nodes while forcing non-integrated converters to absorb volatility in ethylene-vinyl acetate feedstock pricing.
Pricing Analysis
Asian-origin encapsulant sheets command premium positioning in European tenders due to EU F-Gas Regulation compliance costs and carbon border adjustment accounting. Three-tier pricing structure across premium polyolefin, standard EVA, and economy-grade formulations separates qualification-intensive bifacial applications from commodity monofacial procurement. Cost compression in standard EVA tiers is intensifying because Hangzhou First PV Material's integrated operations sustain lower unit economics than merchant converters. Utility-scale module integrators exhibit highest price sensitivity, while building-integrated photovoltaic fabricators prioritize optical clarity and thermal performance over unit cost.
Supply Chain Analysis
Ethylene and vinyl acetate monomer production anchors in China, South Korea, and Saudi Arabia, with solar-grade EVA resin capacity concentrating at three Asian petrochemical complexes. Sheet extrusion draws from peroxide crosslinking agents, antioxidant stabilizers, and silicone release liners as critical formulation inputs. Single-source vulnerability in solar-grade EVA resin supply creates exposure for non-integrated sheet producers when petrochemical turnarounds constrain feedstock availability. Distribution runs through direct resin-to-module contracting that displaces traditional merchant sheet stocking roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise represents the binding constraint as polyolelin qualification timelines compress and heterojunction cell architectures demand low-temperature lamination compatibility. The gap between EVA process maturity and emerging elastomer capabilities widens competitive moats for resin-to-sheet integrators.
For Market Incumbents: Entrench qualification advantages by accelerating ionomer and thermoplastic elastomer certification ahead of heterojunction cell commercialization. Add captive polyolelin capacity in Busan-Ulsan chemical corridors to match South Korean module export growth. Defend against Chinese resin-to-sheet conglomerates by securing long-term ethylene supply agreements with Middle Eastern feedstock suppliers.
For New Entrants and Emerging Players: Pursue white-space opportunities in building-integrated photovoltaic silicone formulations where aesthetic specifications command margin premiums unavailable in utility-scale commodity tiers. Target North American encapsulant sheet production co-located with Southeast module assembly corridors to capture Inflation Reduction Act domestic content bonuses. Lead with direct technical service capabilities that incumbent distributors cannot replicate.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized elastomer compounding assets and dormant solar qualification pipelines. Long-term viability hinges on backward integration into resin production or exclusive offtake relationships with petrochemical feedstock suppliers. Watch for bifacial module export acceleration from South Korea as the inflection signal for polyolelin demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captures margin upstream of sheet extrusion while securing supply against petrochemical turnaround disruptions. |
| Polyolelin Capacity Expansion | Matches qualification timelines for TOPCon and heterojunction cell architectures requiring PID-resistant encapsulants. |
| Direct Module Maker Contracting | Bypasses merchant distribution compression and locks volume through multi-year resin supply agreements. |
| Low-Temperature Lamination Qualification | Opens heterojunction compatibility where ionomer formulations command technical specification premiums. |
| Carbon Border Adjustment Compliance | Enables European tender participation where embodied carbon accounting weights procurement decisions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across module procurement directors, petrochemical plant managers, encapsulant formulation chemists, and utility-scale EPC contractors. Primary fieldwork combined structured interviews with secondary validation against customs trade data, MIIT industrial policy directives, SEC 10-K filings from listed material suppliers, and EU F-Gas Regulation implementation guidance. Bottom-up resin capacity modeling and top-down module deployment forecasts were triangulated to anchor volume projections.
Calibration against historical EVA resin pricing cycles and polyolelin qualification pipeline data refined elasticity assumptions across the projection horizon. Segmentation dimensions modeled include material chemistry tier, module architecture type, end-user procurement authority, and regional regulatory framework cluster. CAGRs were derived from installed capacity buildout trajectories and substitution elasticity between encapsulant formulations. Bifacial module deployment rates and heterojunction cell commercialization timelines served as key demand-side forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in ethylene feedstock pricing, freight rate volatility, or solar module tariff regimes would shift the trajectory. Forecasts reflect documented assumptions about qualification timeline compression and resin substitution mandates. Cross-checking against IEA photovoltaic deployment benchmarks and petrochemical capacity utilization disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Lithium Tantalate Crystal Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
US Graphene Market
Advanced Materials
2D Materials Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Global Aluminum Honeycomb Market