
 High-Purity Amorphous Boron Market | 2026-2036
High-Purity Amorphous Boron Market Size, Share, and Industry Trends Forecast 2026-2036
High-Purity Amorphous Boron Market Analytics
Silicon carbide is restructuring thermal management economics in high-temperature electronics, pushing boron suppliers toward purer amorphous grades for neutron capture and semiconductor doping applications. H.C. Starck GmbH leverages its German metallurgical heritage to sustain premium positioning in powder purification. Dandong Chemical Engineering Institute anchors Chinese supply through integrated boron ore processing in Liaoning. Noah Technologies Corporation differentiates via specialty chemical distribution networks spanning North American research institutions.
High-purity amorphous boron denotes elemental boron in a non-crystalline state, typically exceeding 95-99% purity with particle sizes below 10 microns, produced via reduction of boron halides or thermal decomposition of boranes for applications requiring controlled neutron absorption and precise dopant behavior. The powder segment leads volume shipments due to its dispersion advantages in pyrotechnic and semiconductor formulations, while neutron capture applications in defense and energy infrastructure represent the fastest-expanding margin pool as reactor shielding specifications tighten. Pellet and coated formats occupy narrower but higher-value niches where handling safety and controlled release properties command specification premiums.
EPA hazardous substance rules and OSHA workplace exposure limits shape U.S. manufacturing protocols for fine boron powders, while China's MEE enforces emission caps on boron refining that elevate capital requirements for new capacity. REACH registration obligations in Europe constrain importer flexibility and favor established suppliers with dossier completeness. Stakeholders must weigh regulatory compliance costs against end-user qualification timelines when evaluating capacity expansion or geographic diversification decisions.
Market Dynamics
Defense procurement programs in the United States are expanding boron-based neutron shielding requirements, while China's dual carbon goals tighten emissions standards for boron refining operations. These dual pressures are compressing supply timelines and elevating qualification barriers for new entrants.
Growth Catalysts
- Neutron capture applications:Reactor shielding specifications in defense and energy infrastructure are tightening, pulling demand for ultra-high purity grades. Military procurement cycles now embed boron specifications directly into long-term supply agreements.
- Semiconductor doping demand:Silicon carbide thermal management economics are pushing boron suppliers toward purer amorphous grades for precise dopant behavior in high-temperature electronics.
- REACH registration:European chemical registration obligations favor established suppliers with complete dossiers, consolidating market position for compliant producers.
Market Restraints
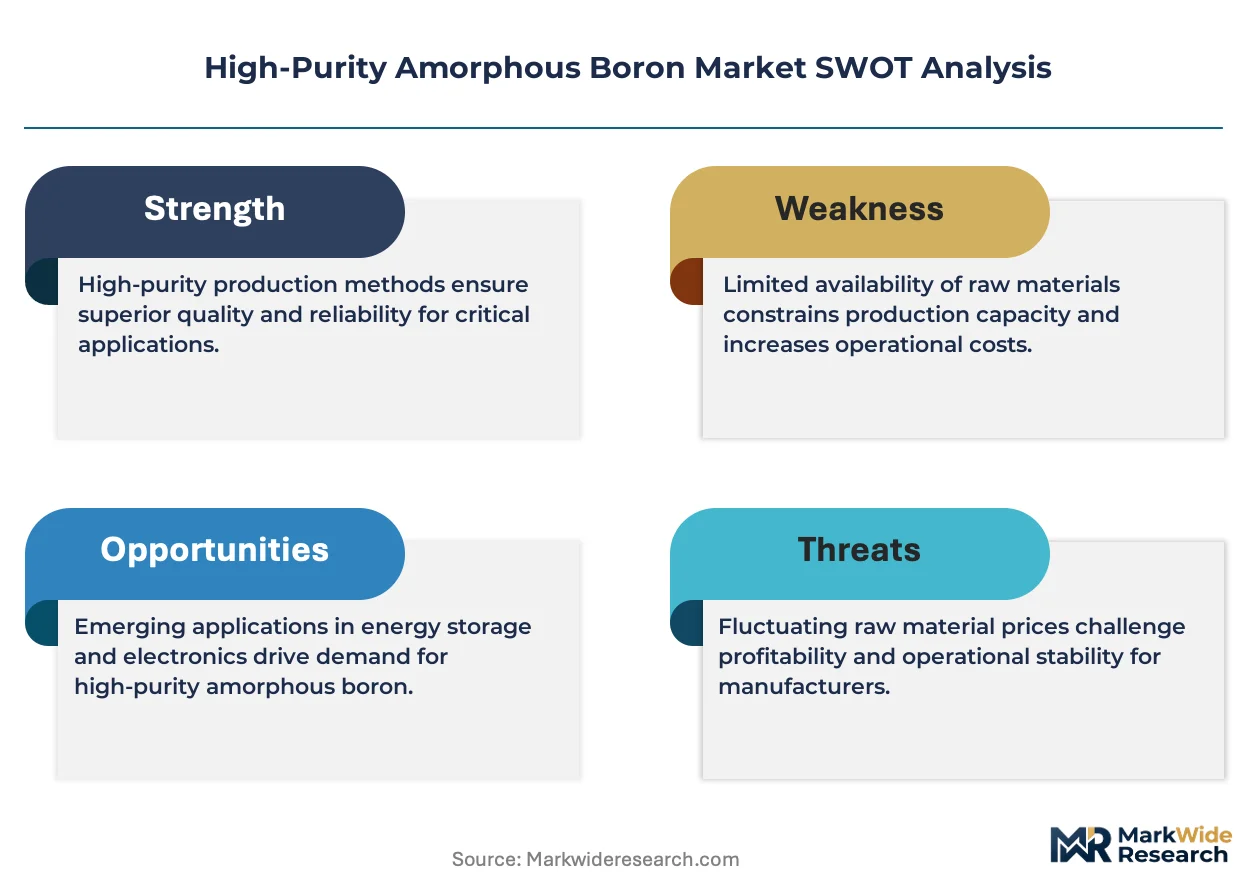
- Input cost volatility:Boron trichloride and diborane feedstock prices fluctuate with natural gas and chlorine markets, squeezing margin predictability for reduction-based production routes.
- Supply concentration risk:Liaoning Province's chemical processing corridor controls the majority of Chinese powder-grade output, creating single-point vulnerability for global supply continuity.
- Substitution threat:Cadmium-based neutron absorbers and rare-earth shielding composites compete in cost-sensitive reactor applications where boron purity premiums cannot be justified.
Strategic Opportunities
- Underpenetrated defense procurement:United Kingdom and French naval reactor programs are revising shielding specifications, opening qualification windows for certified suppliers.
- Emerging fusion energy applications:Tokamak first-wall and blanket shielding designs specify amorphous boron for tritium breeding and neutron multiplication control.
- Technology convergence:Additive manufacturing of boron-loaded polymer composites is automating complex shielding geometries, reducing machining waste and lead times.
Industry Challenges
- Specialized metallurgical talent scarcity:Halide reduction process expertise concentrates among retiring cohorts in German and Russian technical institutes, constraining knowledge transfer.
- Extended certification timelines:Defense and nuclear regulatory qualification protocols require multi-year stability testing, delaying revenue recognition for new production lines.
- IP licensing complexity:Boron isotope enrichment and purification patents held by national laboratories create fragmented technology access for commercial scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Purity Amorphous Boron Market |
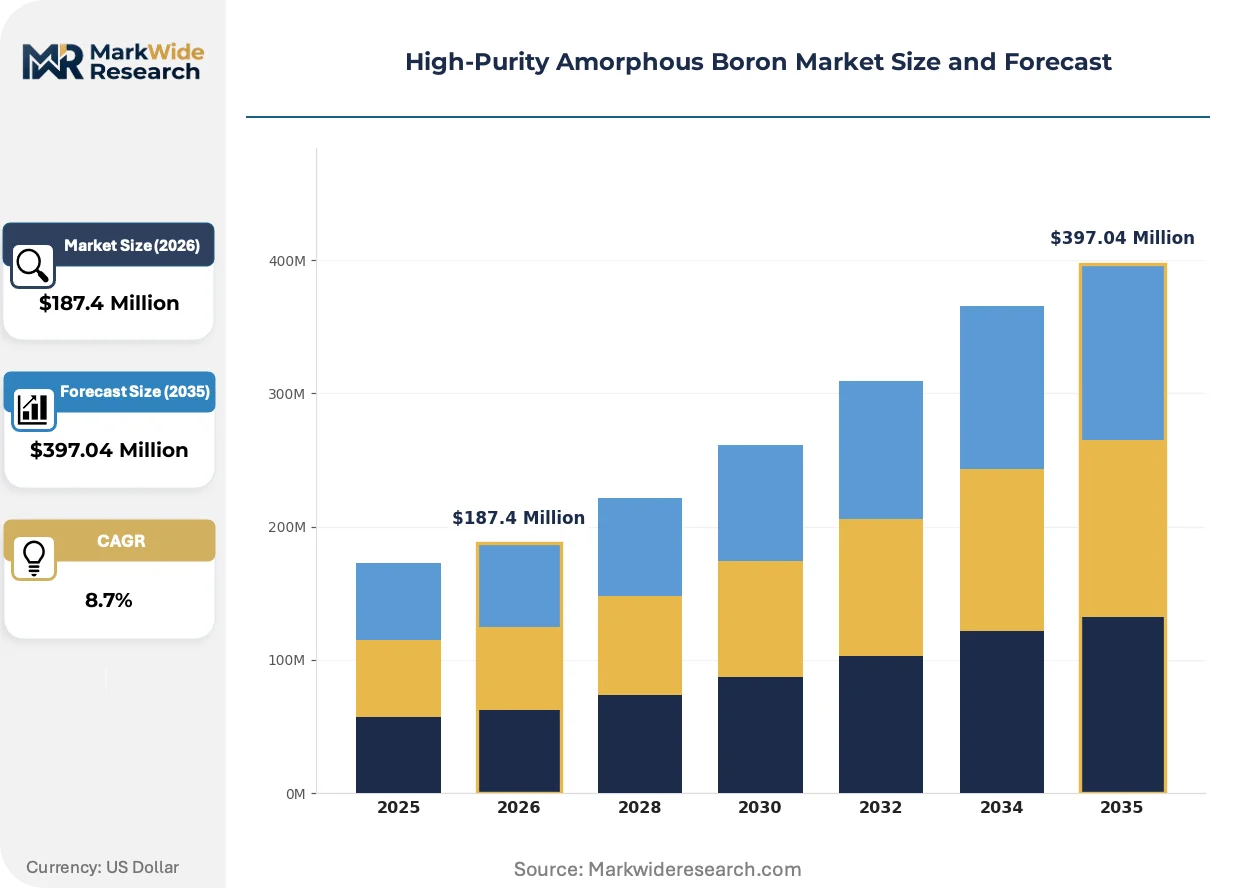
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Pellets, Coated Application: Semiconductors, Coatings, Glass Manufacturing, Neutron Capture End User: Electronics, Defense, Aerospace, Energy Form: Bulk, Tablet, Suspensions, Solutions |
| Companies Covered | Noah Technologies Corporation, Dandong Chemical Engineering Institute (DCEI), SB Boron, H.C. Starck GmbH, New Metals and Chemicals, Höganäs, Yingkou Liaobin Fine Chemicals, Baoding Zhongpuruituo Technology, SkySpring Nanomaterials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Purity Amorphous Boron Market Evolving Landscape
Silicon carbide power electronics are restructuring thermal management requirements across aerospace and automotive sectors, forcing boron suppliers to recalibrate purity thresholds and particle size distributions. This technical pivot is accelerating investment in automated process control and real-time quality verification systems.
Plasma-enhanced chemical vapor deposition is automating the production of sub-micron amorphous boron films for semiconductor applications. Memory and logic chip manufacturers in Taiwan and South Korea are adopting these deposition systems to achieve atomic-layer precision in dopant placement. The technology is compressing qualification cycles from years to months for advanced node production.
China's Ministry of Ecology and Environment emission caps on boron refining are forcing capacity consolidation among Liaoning Province producers. Smaller operators lacking flue gas treatment infrastructure face shutdown orders, while integrated processors with captive power and waste recovery systems secure operating permits. The policy is shifting export volume toward state-affiliated trading channels.
Direct procurement from specialized chemical distributors is displacing traditional broker networks for research-scale quantities. North American universities and national laboratories now contract through consolidated distribution platforms that bundle boron powders with handling protocols and safety documentation. This channel consolidation is most visible in California and Massachusetts research corridors.
High-Purity Amorphous Boron Market Segmentation
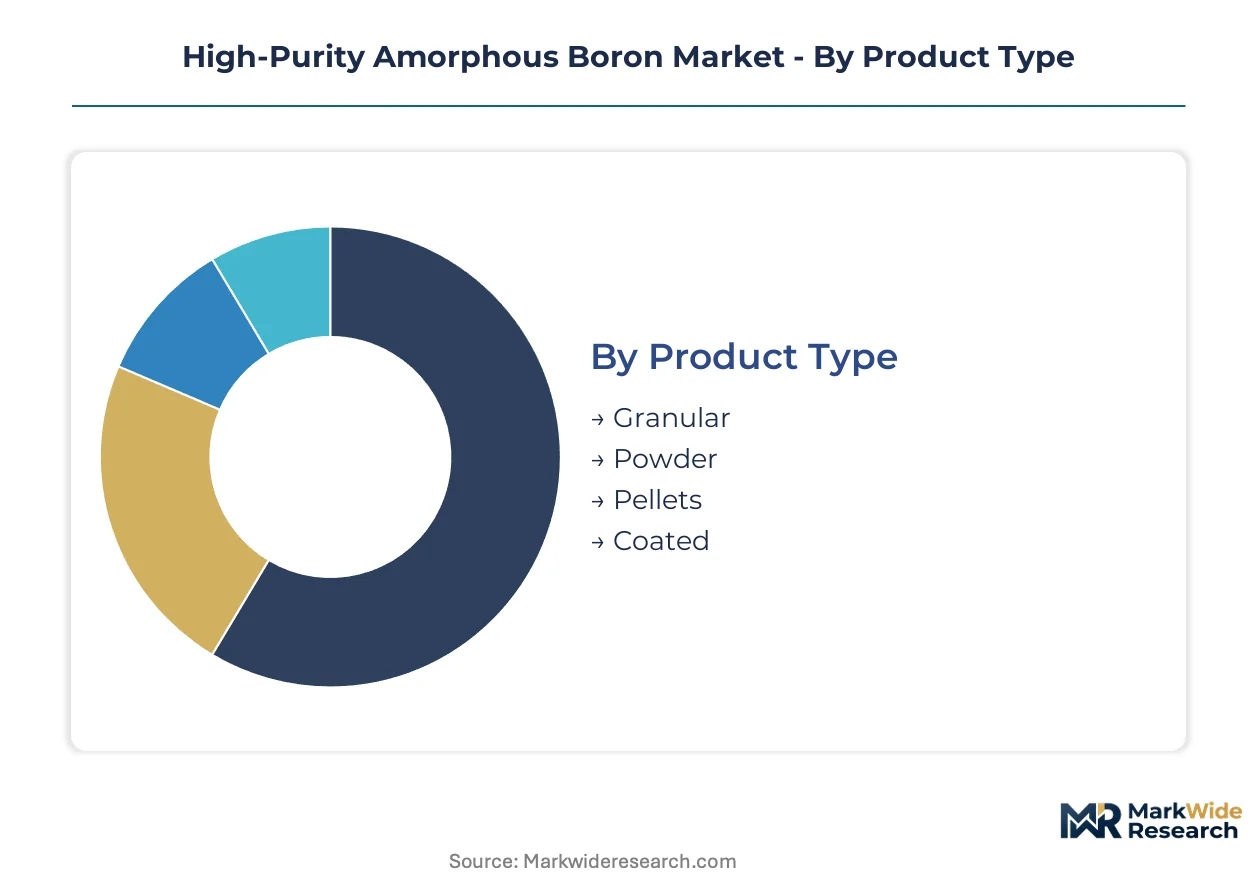
Segmentation in high-purity amorphous boron markets tracks how physical form, application chemistry, and end-user qualification requirements create divergent margin structures. Powder specifications dominate volume shipments while neutron capture applications command the steepest purity premiums.
Product Type:
Supply concentration in Liaoning Province's chemical processing corridor shapes which physical formats achieve scale economics versus specialty positioning.
- Powder:Sub-10 micron particle distributions enable uniform dispersion in pyrotechnic formulations and semiconductor doping baths. Defense procurement programs in the United States specify powder grades for neutron shielding composites, though OSHA workplace exposure limits elevate handling costs for fine fractions.
- Granular:Coarser agglomerates between 100-500 microns reduce dust generation during transport and metering. Glass manufacturers in Germany's industrial heartland prefer granular feedstock for controlled boron oxide release in furnace operations.
- Pellets:Pressed cylindrical forms with controlled density suit automated feeding systems in nuclear shielding fabrication.
- Coated:Surface-passivated particles with polymer or oxide layers prevent atmospheric degradation during extended storage.
Powder absorbs the bulk of installed capacity; coated formats are expanding most quickly as handling safety specifications tighten.
Application:
Application chemistry determines whether boron functions as a bulk additive or a precision dopant, with radically different purity thresholds and pricing outcomes.
- Neutron Capture:Ultra-high purity grades exceeding 99% boron content with controlled isotopic composition enable precise neutron absorption cross-sections in reactor shielding. Military procurement cycles now embed these specifications directly into multi-year supply agreements, compressing qualification windows for certified suppliers.
- Semiconductors:Atomic-layer doping of silicon carbide power electronics demands sub-micron amorphous boron with parts-per-billion metallic impurity limits. Taiwan and South Korean foundries are driving adoption of plasma-enhanced chemical vapor deposition systems for this application.
- Glass Manufacturing:Boron oxide incorporation reduces thermal expansion coefficients in borosilicate glassware for laboratory and consumer applications.
- Coatings:Abrasion-resistant boron-rich surface treatments protect turbine blades and cutting tools in high-temperature service environments.
Neutron capture applications absorb the bulk of installed capacity; semiconductor doping is climbing the fastest as silicon carbide thermal management economics restructure electronics supply chains.
End User:
End-user qualification protocols create tiered market access, with defense and nuclear sectors imposing multi-year stability testing that delays revenue recognition.
- Defense:Naval reactor programs in the United Kingdom and France are revising shielding specifications, opening qualification windows for certified suppliers. EPA hazardous substance rules and extended military procurement cycles embed boron suppliers into decade-long relationships.
- Energy:Fusion energy tokamak designs specify amorphous boron for tritium breeding and neutron multiplication control in first-wall and blanket shielding applications.
- Electronics:Memory and logic chip manufacturers require atomic-layer precision in dopant placement, compressing qualification cycles through automated process control.
- Aerospace:Thermal protection systems and lightweight structural composites utilize boron-loaded polymers for high-temperature performance.
Defense procurement absorbs the bulk of installed capacity; energy applications are gaining share fastest as fusion reactor construction accelerates.
Form:
Physical presentation determines logistics economics and handling safety compliance, with bulk shipments dominating industrial scale and precision formats serving research markets.
- Bulk:Loose powder or granular shipments in sealed drums serve high-volume glass and coating manufacturers with established material handling infrastructure.
- Tablet:Compressed units with standardized mass enable precise batching in small-scale nuclear shielding fabrication and research reactor modifications.
- Suspensions:Boron particles dispersed in organic carriers facilitate spray deposition and dip-coating processes for complex geometries.
- Solutions:Soluble boron compounds in aqueous or solvent systems support wet chemical processing and precursor synthesis for advanced ceramics.
Bulk shipments absorb the bulk of installed capacity; tablet formats are expanding most quickly as additive manufacturing of boron-loaded composites automates complex shielding geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement programs and semiconductor supply chain reconfigurations are concentrating high-purity amorphous boron demand across five national markets. Each geography exhibits distinct regulatory pressures and industrial clustering patterns that shape competitive access.
United States
Naval reactor shielding specifications and fusion energy research programs drive procurement volumes. EPA hazardous substance rules and OSHA workplace exposure limits govern domestic manufacturing protocols for fine boron powders. The Department of Energy's national laboratory network in New Mexico and Tennessee anchors qualification testing infrastructure for defense-grade material.
China
Liaoning Province's chemical processing corridor controls the majority of global powder-grade output, with Dandong and Yingkou municipalities hosting integrated boron ore processing. The Ministry of Ecology and Environment enforces emission caps on boron refining that elevate capital requirements for new capacity. Dual carbon goals are forcing consolidation among smaller operators lacking flue gas treatment systems.
Germany
Metallurgical heritage and REACH registration completeness sustain premium positioning in European supply chains. ECHA registration obligations constrain importer flexibility and favor established suppliers with dossier completeness. The industrial heartland around Hesse and North Rhine-Westphalia maintains specialized halide reduction expertise concentrated among technical institutes.
Japan
Silicon carbide power electronics manufacturers in the Nagoya and Osaka industrial zones are pulling demand for sub-micron amorphous boron with parts-per-billion metallic impurity limits. METI industrial standards shape qualification protocols for semiconductor dopant applications. Kyushu-based materials processors are investing in plasma-enhanced chemical vapor deposition systems for atomic-layer precision.
South Korea
Memory and logic chip foundries in the Seoul Capital Area and Busan-Ulsan corridor are compressing qualification cycles through automated process control adoption. MFDS chemical safety regulations govern precursor handling in advanced node production facilities. Domestic trading companies are securing long-term offtake agreements to hedge against Liaoning supply concentration risk.
High-Purity Amorphous Boron Market Competitive Landscape
Capacity expansion dominates the current landscape as producers respond to defense procurement timelines and semiconductor qualification windows. The vendor base stratifies across three tiers: integrated ore-to-powder processors with captive refining assets, specialty chemical distributors with research-scale handling protocols, and metallurgical heritage firms with halide reduction expertise. Strategic archetypes include Liaoning-based volume producers leveraging integrated supply chains, German premium-grade specialists sustaining REACH-compliant positioning, and North American distributors bundling safety documentation with research quantities. Geographic expansion and technology licensing represent the two dominant competitive moves, with producers seeking to decouple from single-region supply concentration.
Among German metallurgical specialists, H.C. Starck GmbH occupies a position exemplifying premium-tier REACH-registered supply. Liaoning-based integrated processors Dandong Chemical Engineering Institute and Yingkou Liaobin Fine Chemicals represent the volume-driven archetype with captive ore processing and state-affiliated trading channel access. Noah Technologies Corporation exemplifies the research-scale distribution model, anchoring North American institutional procurement through consolidated platforms spanning California and Massachusetts research corridors.
| Leading Market Players |
|---|
| Noah Technologies Corporation |
| Dandong Chemical Engineering Institute (DCEI) |
| SB Boron |
| H.C. Starck GmbH |
| New Metals and Chemicals |
| Höganäs |
| Yingkou Liaobin Fine Chemicals |
| Baoding Zhongpuruituo Technology |
| SkySpring Nanomaterials |
| Others |
Value Network & Pricing Analysis
Plasma-enhanced chemical vapor deposition systems are compressing semiconductor qualification cycles from years to months while simultaneously elevating purity thresholds and concentrating supply among processors with atomic-layer precision capabilities. This technical pivot is reshaping cost economics across powder-grade and sub-micron film segments, with Liaoning Province's integrated ore-to-powder operators capturing volume economics and German metallurgical specialists commanding specification premiums.
Pricing Analysis
Volume shipments of powder-grade material absorb the bulk of installed capacity at compressed margins, while neutron capture applications for defense procurement command the steepest purity premiums. Three-tier pricing structure across defense-certified, semiconductor-grade, and industrial-standard levels separates qualification-intensive reactor shielding from research-scale distribution. Price differentiation hinges on isotopic composition control and metallic impurity limits measured in parts-per-billion. Margins are tightening in industrial glass and coating feedstock as Liaoning's state-affiliated trading channels expand export volume. Defense procurement officers show the least price sensitivity due to embedded multi-year supply agreements, while research institutions purchasing through North American distribution platforms negotiate aggressively on handling protocol bundles.
Supply Chain Analysis
Domestic-content mandates in United States naval reactor programs and United Kingdom shielding specifications are reshaping sourcing patterns toward qualified indigenous processors. Supply concentrates in China's Liaoning Province, Germany's Hesse industrial corridor, and United States Department of Energy laboratory networks. The chain rests on boron trichloride and diborane feedstock availability, halide reduction expertise concentrated among German and Russian technical institutes, and plasma-enhanced deposition equipment from Japanese and South Korean manufacturers. Single-source vulnerability runs through Liaoning's chemical processing corridor, where emission caps are forcing consolidation among smaller operators. Distribution runs through state-affiliated trading channels for bulk industrial shipments and specialized chemical distributors for research-scale quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide thermal management economics are displacing legacy silicon-based power electronics, forcing boron suppliers to recalibrate around atomic-layer doping specifications and compressing qualification timelines for new production entrants.
For Market Incumbents: Hedge against Liaoning supply concentration risk by securing alternative ore processing partnerships in Turkey or Argentina's emerging borate districts. Invest in plasma-enhanced chemical vapor deposition capabilities to capture semiconductor doping demand from Taiwan and South Korean foundries. Backward integration into captive boron isotope enrichment addresses defense procurement specifications tightening around neutron absorption cross-section control. For New Entrants and Emerging Players: The price-point gap between REACH-registered German premium grades and Liaoning volume exports creates entry space for mid-tier processors with halide reduction expertise and ECHA dossier completeness. Target United Kingdom and French naval reactor programs revising shielding specifications, where qualification windows remain open for certified suppliers. Lead with additive manufacturing partnerships for boron-loaded polymer composites, automating complex shielding geometries that reduce machining waste and accelerate design iteration cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in defense contractor vertical integration plays and semiconductor materials platform roll-ups. Long-term viability favors processors with captive ore assets, flue gas treatment infrastructure compliant with China's MEE emission caps, and established relationships with national laboratory qualification networks. Watch for inflection signals in fusion energy tokamak construction timelines, where first-wall and blanket shielding specifications for tritium breeding could replicate defense procurement volume scales.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Alternative Geographies | Turkish and Argentine bor ore processing reduces single-point vulnerability to Liaoning emission enforcement actions. |
| Backward Integration into Isotope Enrichment | In-house boron-10 separation capability secures defense procurement tiers requiring precise neutron absorption cross-sections. |
| Plasma-Enhanced CVD System Deployment | Taiwan and South Korean foundry qualification demands atomic-layer precision for silicon carbide dopant placement. |
| Long-term Defense Supply Agreements | United States Naval Reactors and United Kingdom submarine programs embed decade-long material specifications. |
| Joint Venture with Additive Manufacturing Platforms | Automated boron-loaded polymer deposition reduces shielding fabrication lead times and machining waste. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with halide reduction process engineers, defense procurement officers at national laboratories, semiconductor materials managers at Taiwan and South Korean foundries, and specialty chemical distribution executives in California and Massachusetts research corridors combined with secondary validation. Secondary sources included EPA hazardous substance rulemakings, ECHA REACH registration databases, China MEE emission cap enforcement records, and Department of Energy national laboratory procurement disclosures. Bottom-up capacity assessments across Liaoning Province processors and top-down demand modeling from defense and semiconductor end-use segments were triangulated to reconcile volume estimates.
Data-stream reconciliation across production capacity surveys, import-export customs classifications, and end-user procurement disclosures shaped the analytical framework. Segmentation dimensions modeled include physical form, application chemistry, end-user qualification tier, and regional regulatory cluster. CAGRs were derived from regression analysis of historical shipment volumes and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated silicon carbide power electronics adoption curves and fusion energy tokamak construction pipeline assessments.
Underlying measurement precision varies by segment; defense procurement and semiconductor doping applications carry tighter precision than industrial glass and coating feedstock due to disclosed contract values and foundry capex tracking. Forecasts reflect assumptions around qualification timeline stability, emission cap enforcement consistency, and plasma-enhanced deposition technology diffusion rates. Substitution risk from cadmium-based neutron absorbers and rare-earth shielding composites represents a specific revision trigger for boron demand elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Artificial Marble Products Market