
 Vaccine Technology Market | 2026-2036
Vaccine Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Technology Market Intelligence
Demand from biotechnology firms focused on therapeutic vaccines for oncology is reorganizing the competitive landscape, shifting focus from purely prophylactic applications. Pfizer leverages its extensive manufacturing scale for both traditional and novel vaccines. Moderna specializes in mRNA-based platforms, driving innovation in rapid-response development. GSK sustains a strong position through its advanced adjuvant technologies, which enhance immune responses for a variety of vaccine candidates.
Vaccine technology encompasses the scientific methods and platforms used to develop and produce immunobiological agents that stimulate a protective immune response. This includes processes like recombinant DNA engineering to express specific antigens and the formulation of lipid nanoparticles for nucleic acid delivery. While infectious diseases remain the largest indication area, oncology applications represent the fastest-growing segment. Among vaccine types, mRNA and viral vector platforms are gaining share from traditional inactivated vaccines due to their rapid development cycles and platform adaptability.
Regulatory bodies such as the US FDA, the European Medicines Agency (EMA), and China's NMPA establish stringent protocols for clinical trials and good manufacturing practices. These approval pathways directly influence development timelines and market access for new vaccine technologies across major economic blocs. Stakeholders must now navigate the evolving standards for platform-based approvals versus single-product authorizations.
Market Dynamics
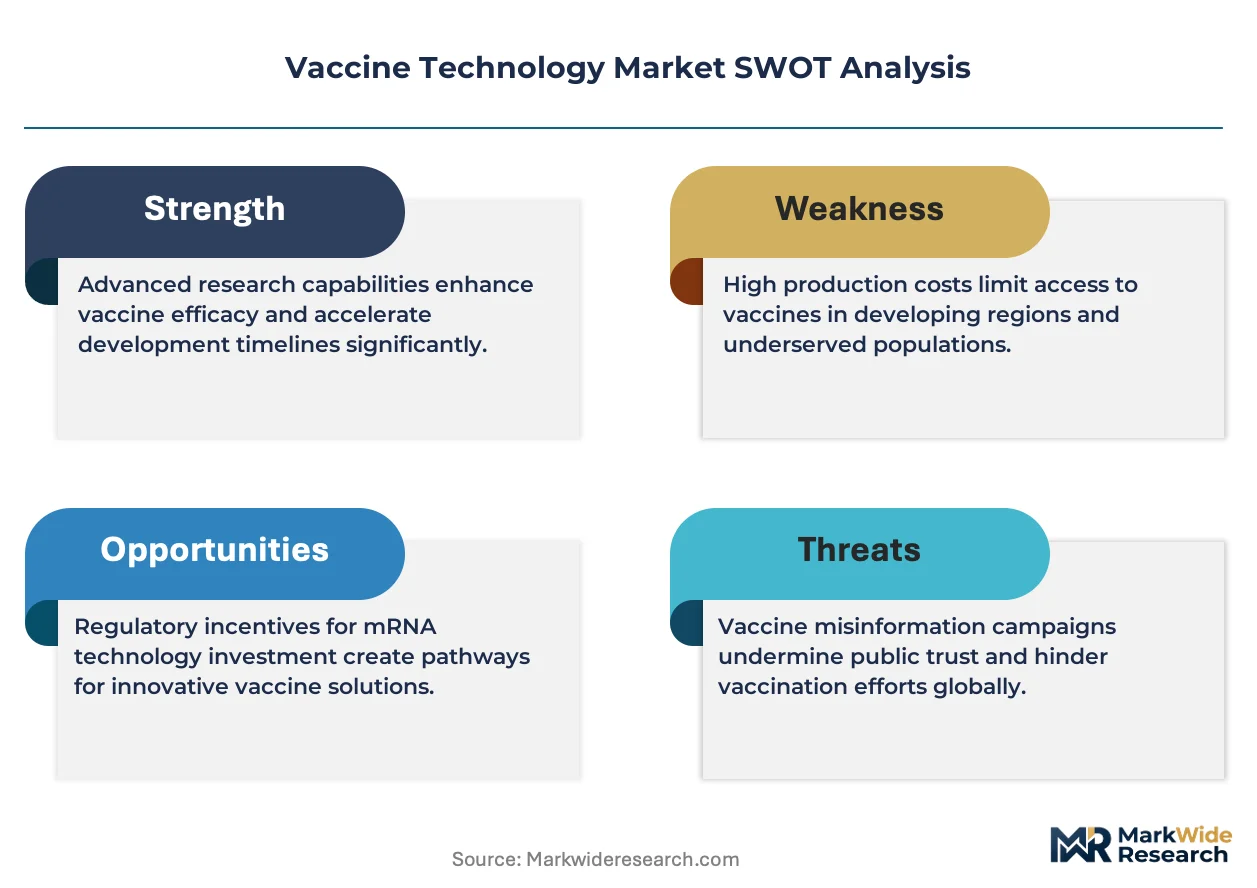
The vaccine technology field is defined by the strategic pivot from infectious disease prophylaxis to therapeutic applications, particularly in oncology. This shift is driven by the adaptability of novel platforms like mRNA and viral vectors, which allow for rapid development cycles against new targets like cancer neoantigens.
Growth Catalysts
- Novel Platform Adoption:The application of mRNA and lipid nanoparticle delivery systems in oncology and for emerging infectious diseases accelerates development timelines and attracts significant investment into the biopharmaceutical sector.
- Government Funding and Policy:Increased public investment and the creation of expedited regulatory pathways by agencies like the US FDA and EMA for pandemic preparedness and high-unmet-need diseases stimulate R&D.
- Therapeutic Vaccine Demand:Rising demand from biotechnology firms in China and the US for therapeutic vaccines to treat chronic diseases and cancers is creating a new, high-value market segment.
Market Restraints
- High Development Costs:The substantial capital investment required for GMP-compliant manufacturing facilities and extensive clinical trials for novel vaccine platforms creates a high barrier to entry for smaller companies.
- Cold-Chain Logistics:Stringent temperature requirements for storing and transporting mRNA-based vaccines pose significant logistical and cost hurdles, particularly in regions with underdeveloped infrastructure.
- Complex Manufacturing Processes:The technical complexity and scarcity of raw materials for viral vector and nucleic acid vaccine production can lead to manufacturing bottlenecks and supply chain vulnerabilities.
Strategic Opportunities
- Personalized Oncology Vaccines:The development of patient-specific cancer vaccines based on neoantigen identification offers a significant opportunity in precision medicine, commanding premium pricing and addressing unmet clinical needs.
- Adjuvant Technology Innovation:Creating next-generation adjuvants that can safely boost the immunogenicity of subunit or recombinant protein vaccines opens avenues for improved efficacy in challenging populations, such as the elderly.
- Expansion in Emerging Markets:Building domestic manufacturing capabilities in markets like Brazil and India, supported by government initiatives like the PLI scheme, provides access to large, underpenetrated populations.
Industry Challenges
- Specialized Talent Scarcity:A shortage of scientists and technicians with expertise in process development, bio-analytics, and GMP manufacturing for nucleic acid and viral vector platforms constrains industry growth.
- Intellectual Property Disputes:The dense and overlapping patent landscape surrounding core technologies like lipid nanoparticles and mRNA modifications creates a risk of costly litigation and licensing disputes.
- Regulatory Pathway Uncertainty:Navigating evolving global regulatory standards, such as the requirements from China's NMPA versus the EMA for platform-based approvals, complicates global development strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Technology Market |
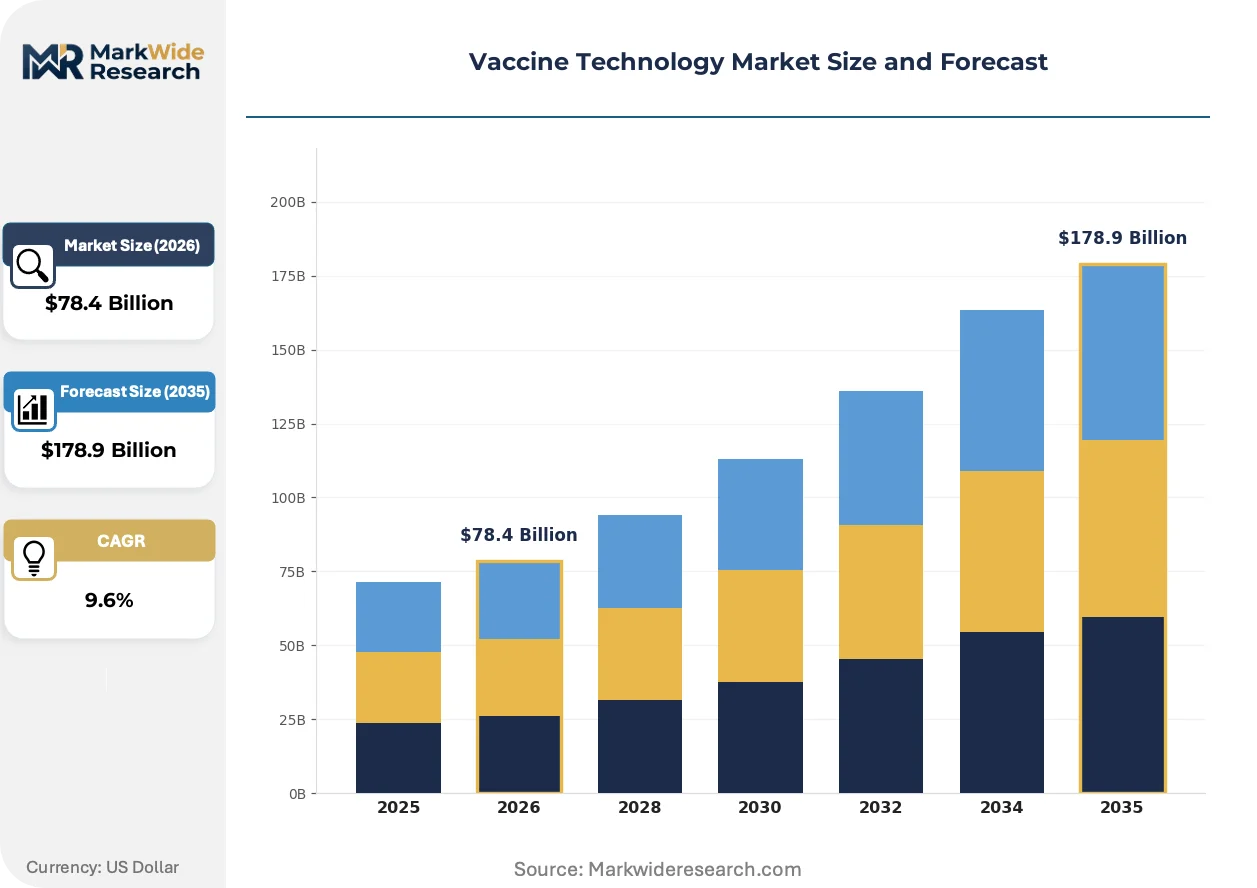
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: mRNA, Viral Vector, Protein Subunit, Inactivated, Live Attenuated, Toxoid Technology Platform: Recombinant DNA, Nanoparticle, Lipid Nanoparticle, Adjuvant, Conjugate, Peptide Indication Area: Infectious Diseases, Oncology, Autoimmune Disorders, Allergies, Rare Diseases, Neurological Conditions End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Public Health Agencies, Vaccine Distributors, Clinical Laboratories |
| Companies Covered | Pfizer Inc, Merck & Co., Inc., GSK plc, Sanofi, Moderna, Inc., AstraZeneca, Serum Institute of India Pvt Ltd, CSL, Emergent BioSolutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Technology Market Strategic Shifts & Innovations
Platform-based development is reshaping the industry's core value proposition, moving it from a product-centric model to a capability-centric one. This transition prioritizes speed and adaptability, enabling rapid responses to both public health crises and complex therapeutic challenges like cancer.
Self-amplifying RNA (saRNA) technology enables antigen expression at lower doses by allowing the mRNA strand to replicate within the cell. Biotechnology firms focused on next-generation infectious disease and oncology candidates are the primary adopters. The technology's potential for a lower cost-per-dose is fragmenting the development landscape away from conventional mRNA approaches toward more efficient and scalable solutions.
The European Medicines Agency (EMA) is formalizing its framework for platform technology master files, a system mirrored by initiatives at the US FDA. This regulatory evolution permits developers to submit foundational data on a core platform, such as a specific LNP formulation, for reuse across multiple vaccine products. This shift significantly benefits companies with established platform technologies by accelerating clinical trial initiation for subsequent candidates derived from the same validated base.
A shift toward strategic stockpiling and rapid-response contracts is altering government procurement models for pandemic preparedness. This change is displacing traditional, fixed-volume tenders with more flexible agreements that secure access to manufacturing capacity and platform technologies. This trend is most visible in North America and Europe, where public health agencies are building frameworks to ensure rapid vaccine availability for future threats.
Vaccine Technology Market Segmentation
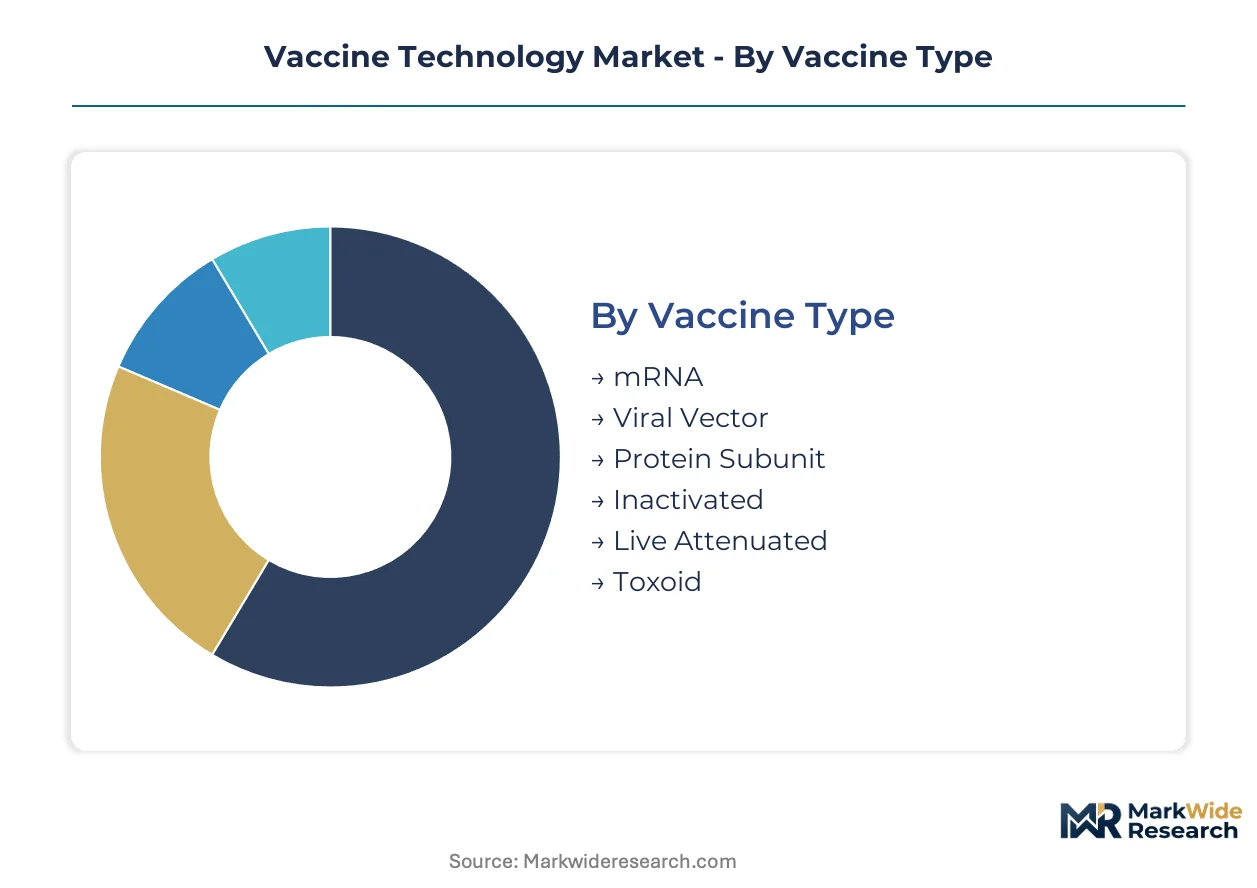
The vaccine technology market segments across diverse dimensions, reflecting the scientific complexity and varied applications of immunobiological agents. Understanding these segments is crucial for stakeholders to identify growth opportunities and navigate the evolving competitive landscape. This segmentation highlights the interplay between technological innovation, regulatory pathways, and end-user demands in shaping market dynamics.
Vaccine Type:
Regulatory bodies globally differentiate vaccine types based on their manufacturing processes and safety profiles, influencing approval pathways and market access for new candidates.
- mRNA:These vaccines deliver genetic instructions for producing antigens directly within host cells, enabling rapid development and high adaptability for novel targets. Demand for mRNA platforms is concentrating in high-income markets like the US and Europe due to their advanced manufacturing capabilities and pandemic preparedness strategies.
- Viral Vector:Viral vector vaccines utilize modified viruses to deliver genetic material encoding antigens, offering robust immune responses and platform versatility. China and India are investing in these platforms for both infectious disease and oncology applications, leveraging domestic biopharmaceutical capabilities.
- Protein Subunit:These vaccines contain purified components of a pathogen, offering high safety profiles and ease of formulation.
- Inactivated:Inactivated vaccines consist of whole pathogens rendered non-infectious, providing broad immune stimulation.
- Live Attenuated:Live attenuated vaccines use weakened forms of pathogens, eliciting strong, long-lasting immune responses.
- Toxoid:Toxoid vaccines target bacterial toxins, stimulating immunity against the toxic effects of specific pathogens.
Inactivated vaccines handle the majority of throughput; mRNA is the fastest mover on share.
Technology Platform:
Technology platforms are increasingly defined by their application focus, ranging from broad-spectrum antigen delivery to highly targeted therapeutic approaches.
- Lipid Nanoparticle:These advanced delivery systems encapsulate nucleic acids, protecting them from degradation and facilitating efficient cellular uptake for mRNA and gene therapies. Demand for LNP technology is concentrating in oncology research, particularly for personalized neoantigen vaccines, due to their precision delivery capabilities.
- Adjuvant:Adjuvants are substances added to vaccines to enhance the immune response, crucial for subunit vaccines and challenging antigens. Innovation in adjuvant technology is attracting investment in elderly populations, where improved immunogenicity is a critical need.
- Recombinant DNA:This platform involves engineering DNA sequences to produce specific antigens, allowing for precise vaccine design.
- Nanoparticle:Nanoparticle platforms utilize nanoscale particles for antigen presentation, improving stability and immunogenicity.
- Conjugate:Conjugate vaccines chemically link antigens to carrier proteins, enhancing immune responses against bacterial polysaccharides.
- Peptide:Peptide vaccines use short amino acid sequences to mimic pathogen epitopes, offering highly specific immune targeting.
Lipid nanoparticle platforms are climbing the fastest, while recombinant DNA platforms maintain broad utility.
Indication Area:
The maturity of indication areas varies significantly, with established infectious disease markets contrasting with nascent but rapidly expanding therapeutic segments.
- Infectious Diseases:This segment addresses a wide range of pathogens, forming the traditional and largest market for prophylactic vaccines globally. Demand for infectious disease vaccines remains consistently high in all regions, driven by routine immunization programs and emerging outbreaks.
- Oncology:Oncology applications focus on therapeutic vaccines for various cancers, representing the fastest-growing and high-value segment. Investment in oncology vaccines is concentrating in the US and Europe, where precision medicine approaches are well-established.
- Autoimmune Disorders:This area explores vaccines to modulate immune responses for conditions like rheumatoid arthritis or multiple sclerosis.
- Allergies:Allergy vaccines aim to desensitize individuals to specific allergens, offering long-term relief.
- Rare Diseases:Vaccines for rare diseases target specific genetic or infectious conditions with limited treatment options.
- Neurological Conditions:This emerging area investigates vaccines for neurodegenerative diseases like Alzheimer's or Parkinson's.
Infectious diseases represent the largest volume, but oncology applications show the steepest expansion trajectory.
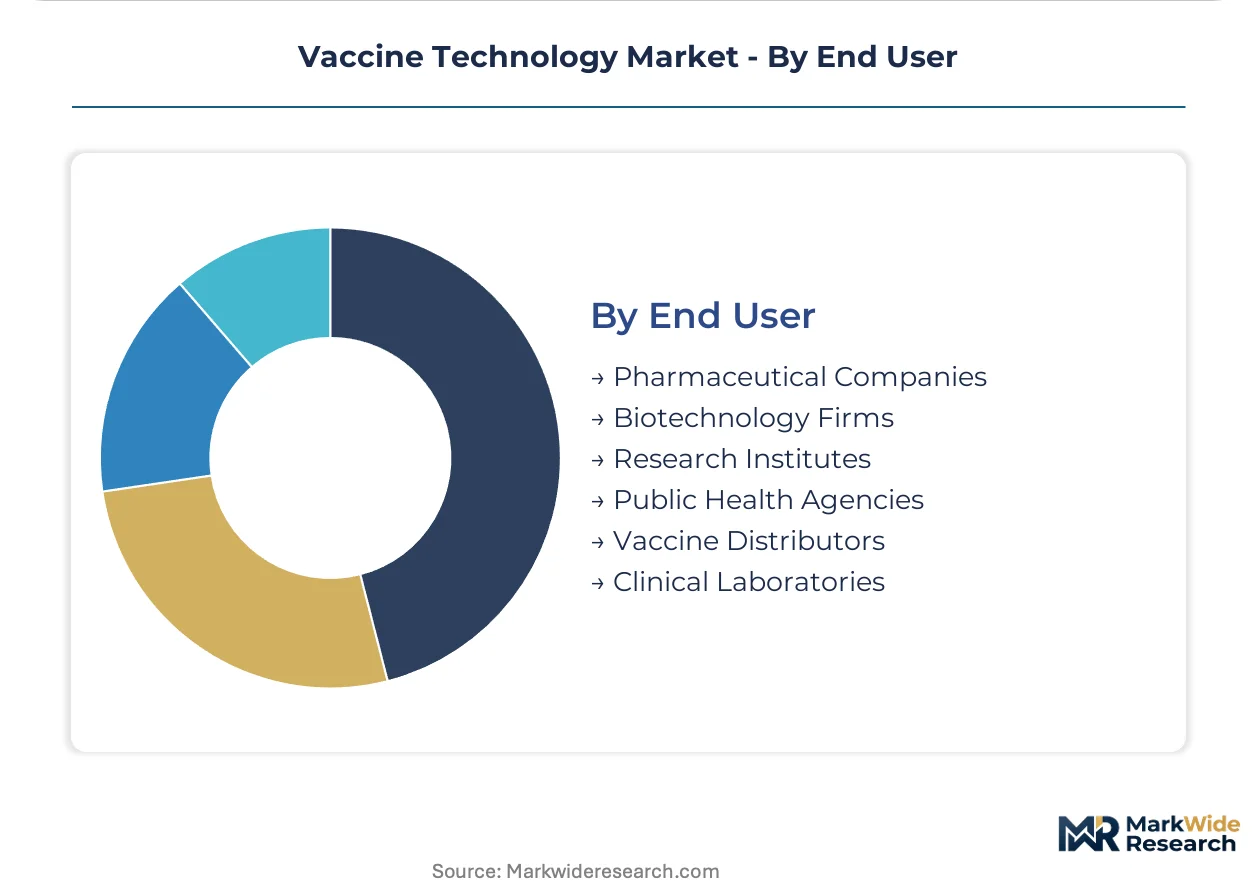
End User:
Different end-user segments exhibit distinct procurement patterns and technological demands, shaping product development priorities and distribution strategies.
- Biotechnology Firms:These entities are at the forefront of novel vaccine platform development, specializing in rapid prototyping and innovative therapeutic applications. Biotechnology firms in the US and China are driving demand for advanced mRNA and viral vector technologies, focusing on high-unmet-need areas like cancer.
- Public Health Agencies:Government agencies are responsible for large-scale procurement and distribution of vaccines for national immunization programs and pandemic preparedness. Public health agencies in Europe and North America are prioritizing rapid-response contracts and strategic stockpiling for future health crises.
- Pharmaceutical Companies:Large pharmaceutical companies leverage extensive manufacturing capabilities and global distribution networks for established vaccine products.
- Research Institutes:Academic and non-profit research institutes conduct fundamental and translational research, contributing to early-stage vaccine discovery.
- Vaccine Distributors:These companies manage the logistics and supply chain for vaccine products, ensuring timely delivery to healthcare providers.
- Clinical Laboratories:Clinical laboratories play a critical role in vaccine efficacy testing, diagnostic support, and surveillance.
Pharmaceutical companies represent the largest procurement volume, while biotechnology firms are gaining share fastest in novel platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global vaccine technology market relies on extensive biopharmaceutical research and manufacturing networks across diverse geographies. These regional hubs drive innovation and ensure efficient production and distribution of novel vaccine candidates. Different national priorities and regulatory landscapes shape local market dynamics.
United States
Demand for personalized oncology vaccines and advanced mRNA platforms drives significant investment in the United States. The US FDA's expedited regulatory pathways accelerate development timelines for high-unmet-need diseases. The Greater Boston area fosters significant biotechnology innovation, concentrating research and development efforts.
China
China's market demand focuses on expanding domestic biopharmaceutical capabilities and viral vector platforms for both infectious diseases and oncology. The NMPA's evolving standards for platform-based approvals influence market access for new technologies. The Yangtze River Delta region is a key hub for vaccine manufacturing and research activities.
Germany
German demand centers on advanced adjuvant technologies and therapeutic vaccine research and development. The European Medicines Agency (EMA) formalizes its framework for platform technology master files, benefiting established innovators. Bavaria supports numerous specialized vaccine research institutes, driving early-stage discovery.
India
India's market expansion is fueled by government initiatives promoting domestic manufacturing and access to large, underpenetrated populations. The PLI scheme stimulates local vaccine production and technology transfer. Pune's biopharmaceutical sector is a key vaccine development center, attracting significant investment.
Japan
Japanese demand emphasizes addressing the needs of elderly populations and high-unmet-need diseases through innovative vaccine solutions. The PMDA's focus on rapid development cycles supports new platform technologies. The Kansai region hosts advanced vaccine research facilities, fostering collaborations with academic institutions.
Vaccine Technology Market Key Industry Players
Concentration sits with established pharmaceutical giants leveraging extensive manufacturing capabilities. The market structure exhibits a tiered consolidation, with a few large players holding significant share alongside numerous specialized biotechnology firms. Strategic archetypes include diversified pharmaceutical conglomerates and agile mRNA technology innovators. Dominant competitive moves involve strategic partnerships for technology access and continuous portfolio diversification into novel therapeutic areas.
Within the diversified pharmaceutical conglomerate archetype, US-based Pfizer Inc. leverages its global manufacturing scale across various vaccine types, maintaining a broad market presence in both traditional and novel applications. US-based Moderna, Inc. exemplifies the agile mRNA technology innovator, focusing on rapid-response development and platform adaptability for emerging health challenges and personalized medicine, rapidly bringing new candidates to trials. UK-based GSK plc occupies a strong position through its advanced adjuvant technologies, which significantly enhance immune responses for a diverse range of vaccine candidates and therapeutic applications, particularly in challenging populations. These players collectively drive innovation and competitive dynamics across the vaccine technology landscape.
| Leading Market Players |
|---|
| Pfizer Inc |
| Merck & Co., Inc. |
| GSK plc |
| Sanofi |
| Moderna, Inc. |
| AstraZeneca |
| Serum Institute of India Pvt Ltd |
| CSL |
| Emergent BioSolutions, Inc. |
| Others |
Cost & Logistics Intelligence
Extensive manufacturing scale in vaccine production drives supply concentration, establishing lower price floors for high-volume traditional vaccines. This scale also influences the cost-effectiveness of novel platform technologies.
Pricing Analysis
Volume-discount tiering structures dominate vaccine pricing, where larger procurement volumes from public health agencies secure more favorable per-dose costs. Price differentiation stems from the technological complexity of novel platforms like mRNA and the certification level of manufacturing facilities. Pricing softness in traditional vaccine segments reflects intense competition and established production capacities. Public health agencies are highly price-sensitive for routine immunization, while biotechnology firms developing personalized oncology vaccines prioritize efficacy and speed over unit cost.
Supply Chain Analysis
Strategic stockpiling for pandemic preparedness contrasts with just-in-time inventory for routine vaccine components, reflecting varied demand predictability. Global supply concentrates in manufacturing hubs across India, China, and the United States, drawing heavily from specialized lipid nanoparticle and viral vector raw materials. Single-source vulnerability for advanced adjuvants poses a critical supply chain risk. Distribution runs through a network of pharmaceutical companies and specialized vaccine distributors, reaching public health programs and private healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vaccine technology market increasingly demands a substitution defense, as novel mRNA and viral vector platforms challenge traditional inactivated vaccine dominance. Incumbents must navigate this shift toward more adaptable and rapidly developed therapeutic solutions.
For Market Incumbents: Secure intellectual property rights for next-generation adjuvant technologies to enhance existing vaccine portfolios and improve immunogenicity for challenging antigens. Diversify manufacturing capabilities to include viral vector and mRNA platforms, mitigating reliance on traditional production methods against the threat of rapid-response innovators. Invest in specialized talent development for nucleic acid and LNP platforms to address talent scarcity. This proactive approach defends market share against agile biotechnology firms.
For New Entrants and Emerging Players: Lead with personalized oncology vaccine development, leveraging neoantigen identification to address high-unmet clinical needs in precision medicine. Target niche therapeutic areas in autoimmune disorders or rare diseases where established players have limited focus, offering a clear market entry point. Focus on rapid prototyping and platform adaptability, utilizing advanced mRNA or saRNA technologies. This strategy allows for premium pricing and avoids direct competition in large-volume prophylactic markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms with validated platform technologies and established regulatory approvals for multiple vaccine candidates. The long-term viability of this market hinges on continued innovation in therapeutic vaccines for oncology and chronic conditions, offering sustained growth over a five-to-ten-year horizon. Target acquisition archetypes include specialized biotechnology firms with advanced LNP delivery systems or novel adjuvant intellectual property. Watch for formalized platform technology master file approvals by the EMA or US FDA as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel mRNA oncology candidates, securing first-mover advantage against cancer neoantigens. |
| Manufacturing Scale-Up | Ensures rapid global distribution of viral vector vaccines, meeting public health agency demand for pandemic preparedness. |
| Licensing Agreement | Expands market access for adjuvant technologies, enhancing immune responses in elderly populations. |
| Pipeline Diversification | Spreads risk across infectious diseases and therapeutic oncology, balancing traditional and high-growth segments for pharmaceutical companies. |
| Regulatory Approval Pathway | Streamlines market access for platform-based technologies, benefiting biotechnology firms with validated LNP systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, academic publications, and industry reports, ensuring data veracity. Interviews with drug development executives, regulatory affairs leads, and hospital procurement managers provided qualitative insights into market dynamics. This primary intelligence was then triangulated with extensive secondary data sources like ClinicalTrials.gov and NMPA submissions. The analysis employed both bottom-up and top-down approaches to validate market sizing and growth projections.
Segmentation dimensions modeled include vaccine type, technology platform, indication area, and end-user, alongside regional regulatory frameworks. The analytical framework projects market growth across the modeling period, incorporating historical trends and future demand drivers. Compound annual growth rates were derived through a weighted average of segment-specific forecasts. Key forecast inputs included clinical trial success rates for novel oncology vaccines and government funding commitments for pandemic preparedness.
Forecasts assume regulatory continuity in US FDA, EMA, and NMPA regimes; material policy shifts would require re-modeling. The analysis accounts for inherent uncertainties in clinical trial outcomes and the pace of technological adoption for novel platforms. Revision becomes warranted when major public health crises or significant funding reallocations cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Global RNA Analysis Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Drug Discovery Enzymes Market