
 Particle-Enhanced Turbidimetric Immunoassays Market | 2026-2036
Particle-Enhanced Turbidimetric Immunoassays Market Size, Share, and Industry Trends Forecast 2026-2036
Particle-Enhanced Turbidimetric Immunoassays Market Analytics
Automation integration in clinical chemistry workflows is narrowing the performance gap between high-throughput analyzers and point-of-care systems. Thermo Fisher Scientific leverages its instrument-reagent bundling strategy to anchor laboratory contracts across North American health systems. bioMérieux sustains competitive positioning through specialized assay development for sepsis biomarkers and inflammatory markers. Roche Diagnostics dominates the installed base of modular chemistry platforms that accommodate turbidimetric immunoassay modules.
Particle-enhanced turbidimetric immunoassays employ latex or gold nanoparticle conjugates that amplify light-scattering signals when antigen-antibody complexes form in solution, enabling quantitative protein detection at nanogram-per-milliliter sensitivity ranges with standard spectrophotometric endpoints. The technique serves primary industrial purpose in clinical diagnostics for C-reactive protein, D-dimer, and immunoglobulin quantification where rapid turnaround and cost efficiency outweigh mass spectrometry alternatives. Assay kits and reagents capture the majority of recurring revenue as consumable pull-through tied to instrument placements. Clinical diagnostics applications lead volume demand while veterinary testing represents a faster-growing adjacency as reference laboratories expand companion animal panels. Hospitals and diagnostic centers concentrate procurement power through centralized tender processes that favor multi-year reagent supply agreements.
FDA 510(k) clearance pathways and Clinical Laboratory Improvement Amendments shape product development timelines and analytical validation requirements for manufacturers seeking US market access. EMA In Vitro Diagnostic Regulation transition imposes new conformity assessment burdens on European market entrants, favoring established players with notified body relationships and quality management infrastructure. ISO 15189 accreditation standards for medical laboratories drive standardization of assay performance verification protocols across jurisdictions. Stakeholders must monitor evolving harmonization between FDA and EMA post-market surveillance expectations as dual-territory registration strategies become cost-critical for mid-scale assay developers.
Market Dynamics
Clinical laboratories are consolidating procurement through multi-year reagent supply agreements that lock in instrument placements, reshaping competitive dynamics toward bundled contracts over standalone assay sales.
Growth Catalysts
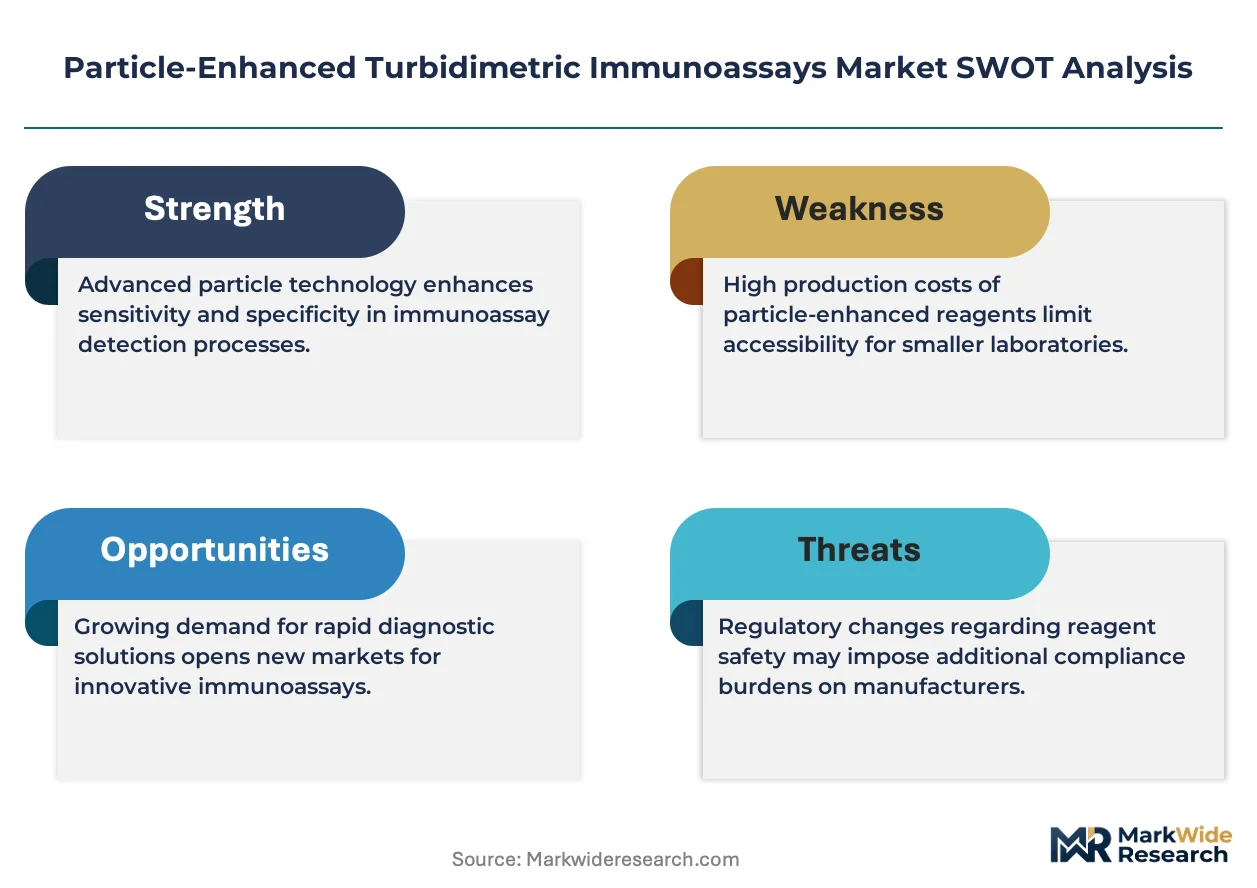
- IVDR Transition in Europe:The EMA's In Vitro Diagnostic Regulation imposes stricter conformity assessments that favor established manufacturers with notified body relationships, accelerating market concentration among quality-certified suppliers.
- Sepsis Biomarker Protocols:Hospital emergency departments are expanding D-dimer and procalcitonin testing volumes as rapid turnaround requirements displace slower immunofluorescence alternatives in triage workflows.
- Latex Nanoparticle Engineering:Advances in uniform particle synthesis are improving assay precision coefficients, enabling diagnostic platforms to meet ISO 15189 accreditation standards for high-sensitivity C-reactive protein quantification.
Market Restraints
- Gold Nanoparticle Supply Concentration:Precursor chemical production clusters in East Asian refining centers, exposing reagent manufacturers to input cost volatility and geopolitical supply disruptions.
- Mass Spectrometry Substitution:Clinical proteomics platforms are capturing reference laboratory protein quantification volumes where ultra-low detection limits outweigh turbidimetry's cost advantages.
- FDA 510(k) Pathway Friction:Evolving analytical validation requirements for novel biomarker claims extend product development timelines and inflate regulatory compliance expenditures for mid-scale developers.
Strategic Opportunities
- Companion Animal Reference Laboratories:Veterinary diagnostic chains in Germany and Japan are expanding immunoglobulin and acute-phase protein panels, creating faster-growing adjacent demand than human clinical markets.
- Point-of-Care Convergence:Integration of turbidimetric modules with cartridge-based analyzers is opening physician office and urgent care settings previously served by centralized hospital laboratories.
- EMA Green Deal Alignment:Sustainable manufacturing incentives under the EU Green Deal are rewarding reagent producers with reduced packaging waste and solvent-free conjugation processes.
Industry Challenges
- Metrology Talent Scarcity:Assay developers face recruitment bottlenecks for analytical chemists experienced in nanoparticle characterization and light-scattering signal optimization.
- Legacy Platform Integration:Modular chemistry analyzer retrofits require firmware adaptations that strain technical support resources and delay customer go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Particle-Enhanced Turbidimetric Immunoassays Market |
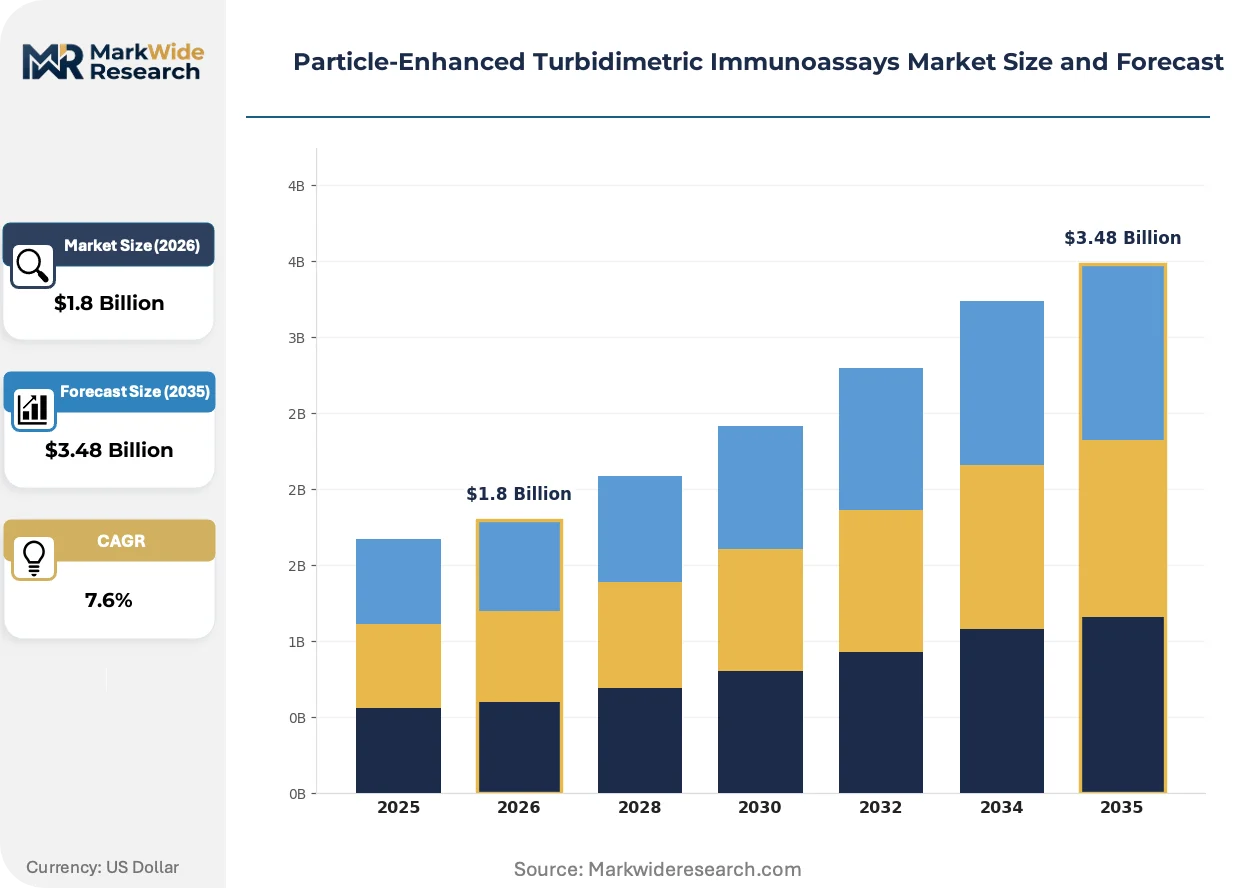
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assay Kits, Reagents, Instruments, Software Application: Clinical Diagnostics, Research, Quality Control, Veterinary Testing Technology: Microplate Readers, Flow Cytometry, Lateral Flow, Enzyme-Linked Immunosorbent End User: Hospitals, Laboratories, Research Institutes, Diagnostic Centers |
| Companies Covered | Thermo Fisher Scientific, bioMérieux, Roche Diagnostics, Gentian Diagnostics, DiaSorin, Abbott Laboratories, Danaher Corporation, QIAGEN, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Particle-Enhanced Turbidimetric Immunoassays Market Evolving Landscape
Automation architectures and detection chemistries are converging to compress assay turnaround times while expanding test menus on shared instrument footprints.
Gold nanoparticle conjugates are migrating from research-grade applications to routine clinical diagnostics. Reference laboratories in Japan are adopting these materials for high-sensitivity cardiac marker panels. The technology is migrating from specialty immunoassay formats toward mainstream chemistry analyzer modules, compressing the performance gap between dedicated immunochemistry systems and general-purpose platforms.
EMA's In Vitro Diagnostic Regulation is restructuring European market access requirements. Manufacturers must now maintain quality management systems under notified body supervision for all class C and D devices. Mid-scale assay developers are responding by prioritizing FDA 510(k) clearance first, deferring European commercialization until regulatory infrastructure matures.
Diagnostic procurement through centralized hospital tenders is displacing fragmented purchasing by individual departments. Health systems in the United States are consolidating reagent contracts under three-to-five-year supply agreements that bundle instrument placement, maintenance, and consumable replenishment. This pattern concentrates most visibly in integrated delivery networks managing multiple acute-care facilities under single procurement governance.
Particle-Enhanced Turbidimetric Immunoassays Market Segmentation
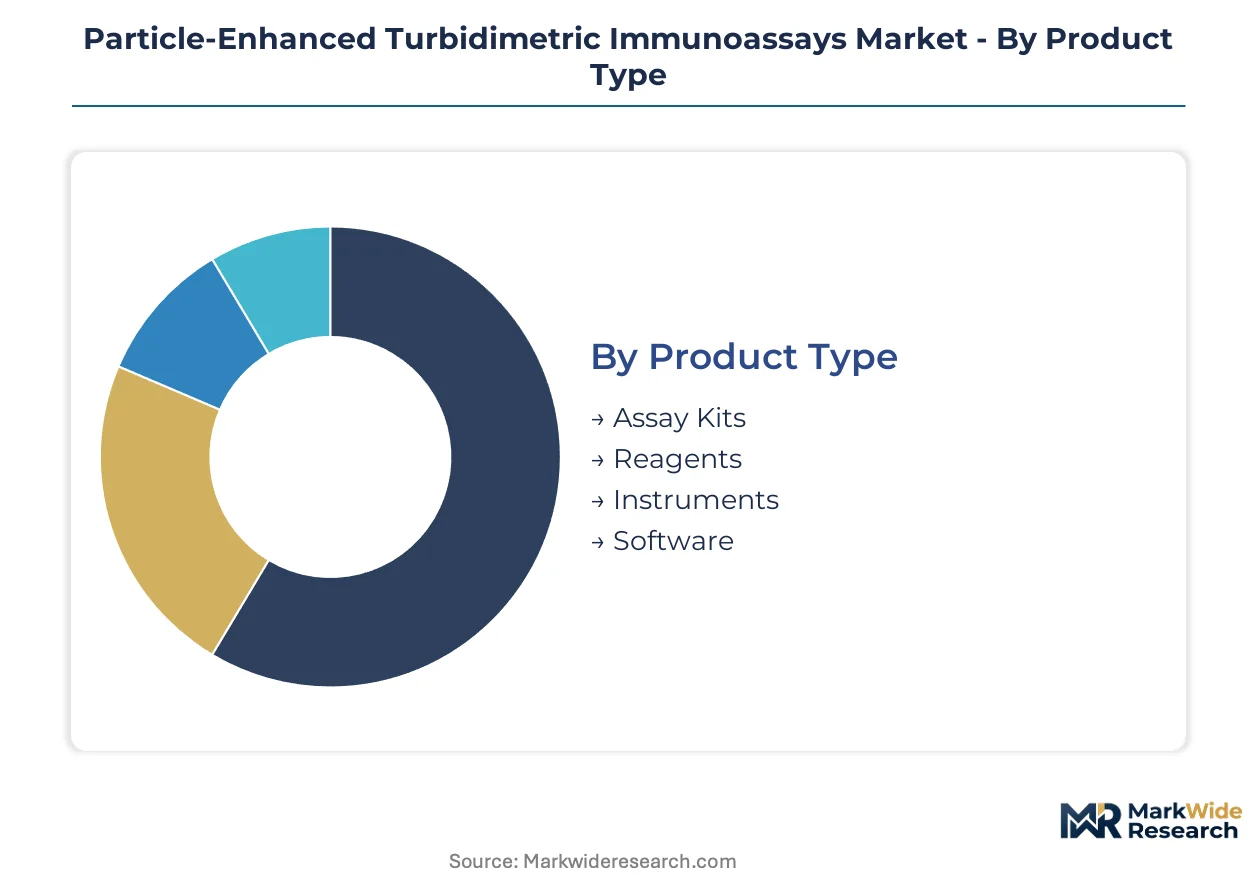
Segmentation in particle-enhanced turbidimetric immunoassays reveals distinct procurement patterns across product tiers and use environments. Assay chemistry formats, detection platforms, and institutional settings each impose unique performance specifications and commercial terms.
Product Type:
Clinical laboratories deploy consumables and capital equipment across workflows ranging from high-throughput screening to specialized biomarker quantification.
- Assay Kits:Pre-configured reagent sets with standardized calibrators and controls enable C-reactive protein, D-dimer, and immunoglobulin quantification on modular chemistry platforms. Hospital laboratories in the United States prioritize FDA 510(k)-cleared kits with lot-to-lot consistency guarantees for accreditation compliance.
- Reagents:Bulk latex and gold nanoparticle conjugates, antibody preparations, and buffer systems constitute recurring consumable pull-through. German reference laboratories negotiate multi-year reagent supply agreements that lock in pricing and secure preferential allocation during supply disruptions.
- Instruments:Spectrophotometric analyzers with dedicated turbidimetric modules integrate into automated clinical chemistry workflows. Japanese diagnostic centers favor compact footprint designs that accommodate limited laboratory real estate.
- Software:Assay data management, calibration tracking, and quality control analytics interface with laboratory information systems. Research institutes require LIMS-compatible platforms with customizable reporting protocols.
Established volume favors Assay Kits; emerging adoption favors Software.
Application:
Functional requirements diverge sharply between regulated patient diagnostics and exploratory research environments.
- Clinical Diagnostics:Quantitative protein detection for cardiac markers, inflammatory indicators, and coagulation factors in hospital emergency departments demands rapid turnaround under CLIA and ISO 15189 standards. Sepsis biomarker protocols in the United States are displacing slower immunofluorescence methods.
- Veterinary Testing:Companion animal reference laboratories in Germany and Japan are expanding acute-phase protein panels and immunoglobulin profiles. This segment is expanding most quickly as pet insurance penetration drives diagnostic spending.
- Research:Investigational biomarker discovery and assay development employ flexible, non-regulated reagent formats. Academic medical centers prioritize open-platform compatibility over regulatory pre-clearance.
- Quality Control:Biopharmaceutical manufacturing and blood bank operations validate product consistency and safety. Industrial laboratories require traceable reference materials and documented analytical precision.
Revenue concentration sits with Clinical Diagnostics; steepest expansion trajectory belongs to Veterinary Testing.
Technology:
Detection modality selection balances sensitivity requirements, throughput needs, and capital constraints across laboratory tiers.
- Microplate Readers:Standard spectrophotometric endpoints with kinetic measurement capabilities serve routine clinical chemistry installations. Mid-scale hospital laboratories in Japan favor these systems for cost-efficient C-reactive protein quantification.
- Lateral Flow:Cartridge-based point-of-care formats compress turnaround times for physician office and urgent care deployment. Urgent care networks in the United States are adopting these systems for D-dimer triage.
- Flow Cytometry:Multi-parameter particle analysis enables complex multiplexed assays in specialized reference settings. Research institutes employ these platforms for investigational biomarker panels.
- Enzyme-Linked Immunosorbent:Established colorimetric detection chemistry persists in resource-constrained settings and legacy installations. Public health laboratories maintain these workflows for cost-sensitive screening programs.
Installed base dominance favors Microplate Readers; point-of-care convergence favors Lateral Flow.
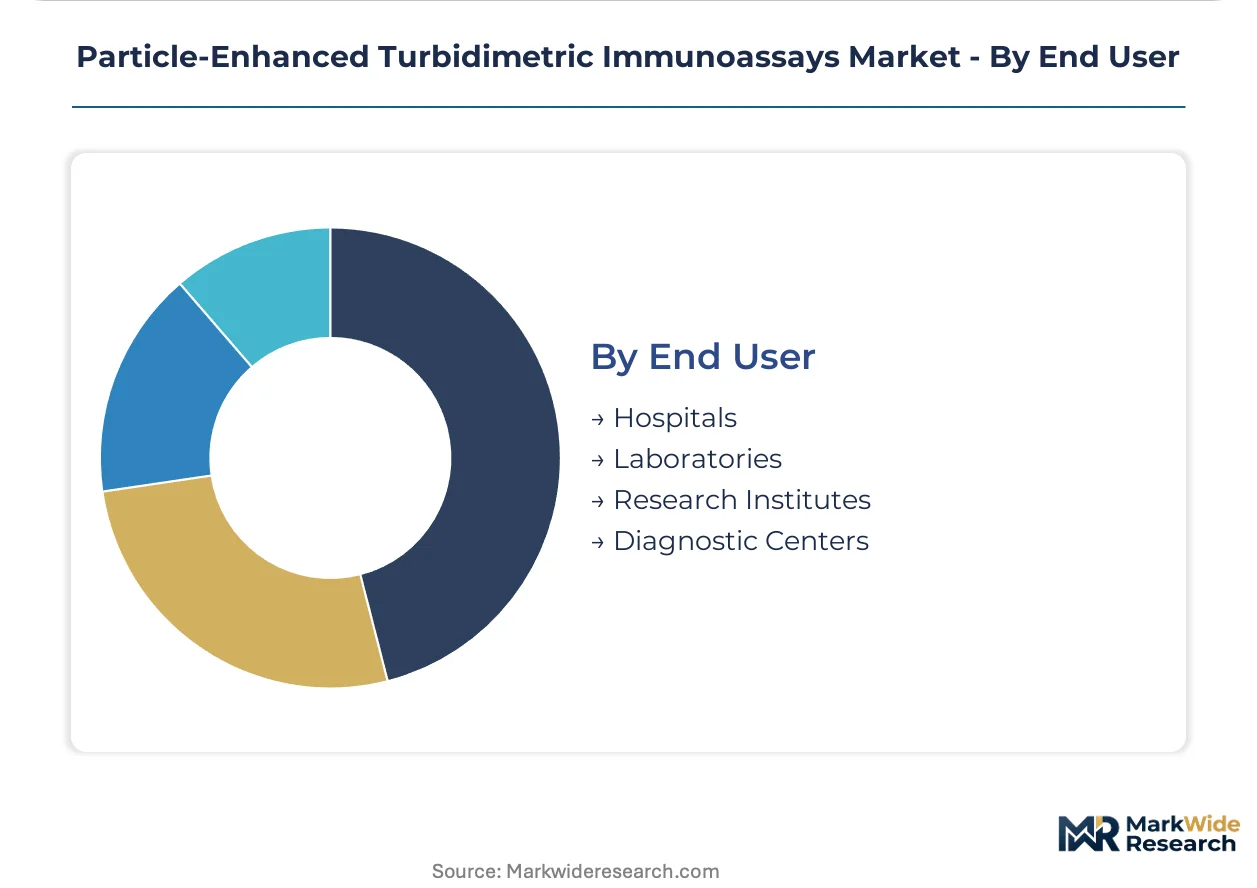
End User:
Procurement governance and technical specifications vary substantially across institutional categories.
- Hospitals:Integrated delivery networks consolidate reagent contracts under centralized tender processes that bundle instrument placement, maintenance, and consumable replenishment. US health systems managing multiple acute-care facilities favor three-to-five-year supply agreements.
- Laboratories:Independent reference laboratories and hospital-affiliated clinical labs concentrate specialized testing volumes. German laboratory chains prioritize EMA IVDR-compliant assay portfolios for European market access.
- Diagnostic Centers:Outpatient-focused facilities emphasize rapid turnaround and patient throughput over test menu breadth. Japanese diagnostic centers seek compact analyzer footprints for urban real estate constraints.
- Research Institutes:Academic and government laboratories prioritize analytical flexibility and publication-grade precision over regulatory pre-clearance. Investigational use exemptions allow novel biomarker assay development.
Procurement scale favors Hospitals; margin expansion favors Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in the United States, Germany, and Japan concentrate purchasing power through multi-year reagent contracts that lock in instrument placements and consumable volumes. These three markets anchor demand for particle-enhanced turbidimetric immunoassays as reference laboratory hubs with stringent accreditation requirements.
United States
Integrated delivery networks managing multiple acute-care facilities consolidate tenders under three-to-five-year supply agreements. FDA 510(k) clearance pathways shape product development timelines for assay developers seeking market access. Boston and San Diego host dense clusters of clinical chemistry innovators developing sepsis biomarker protocols for emergency department deployment.
Germany
Reference laboratory chains prioritize EMA IVDR-compliant assay portfolios as the In Vitro Diagnostic Regulation imposes stricter conformity assessments. The EU Green Deal rewards reagent producers with sustainable manufacturing processes including reduced packaging waste. Munich and Hamburg concentrate veterinary diagnostic expansion as companion animal panels drive faster-growing adjacent demand.
Japan
Diagnostic centers seek compact analyzer footprints to accommodate limited urban laboratory real estate. METI standards and PMDA oversight govern analytical validation requirements for novel biomarker claims. Tokyo and Osaka anchor adoption of gold nanoparticle conjugates for high-sensitivity cardiac marker panels in reference laboratory settings.
United Kingdom
NHS procurement frameworks centralize reagent purchasing for hospital trusts across England, Scotland, and Wales. MHRA regulations align with evolving FDA post-market surveillance expectations for dual-territory registration strategies. The Cambridge-Oxford corridor sustains research institute demand for flexible, non-regulated reagent formats in biomarker discovery.
China
Public hospital laboratories expand automated clinical chemistry workflows as healthcare infrastructure investment accelerates. NMPA regulatory pathways require analytical validation documentation that extends product development timelines for domestic and foreign manufacturers. Shanghai and Beijing concentrate procurement scale for high-throughput screening platforms in tier-one medical centers.
Particle-Enhanced Turbidimetric Immunoassays Market Competitive Landscape
Channel-controlling players compete with product-specialist players through divergent route-to-market strategies. The vendor base organizes around three tiers: diversified life science conglomerates with instrument-reagent bundling capabilities, mid-scale assay developers with specialized biomarker portfolios, and regional reagent suppliers serving cost-sensitive installations. Consolidation pressures favor established manufacturers with notified body relationships under EMA IVDR transition. Dominant competitive moves include multi-year supply agreement negotiations and firmware adaptations for legacy platform integration.
Among diversified diagnostics conglomerates, Thermo Fisher Scientific, bioMérieux, and Roche Diagnostics exemplify contrasting strategic archetypes. Thermo Fisher Scientific represents the instrument-reagent bundling model through laboratory contract anchoring across North American health systems. bioMérieux occupies a position as specialized assay developer for sepsis biomarkers and inflammatory markers. Roche Diagnostics anchors the installed base concentration for modular chemistry platforms accommodating turbidimetric immunoassay modules. These three entities collectively illustrate how scale, specialization, and platform dominance create distinct competitive positions without direct overlap in core value propositions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| bioMérieux |
| Roche Diagnostics |
| Gentian Diagnostics |
| DiaSorin |
| Abbott Laboratories |
| Danaher Corporation |
| QIAGEN |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
Gold nanoparticle supply concentration in East Asian refining centers determines both pricing tier spreads and supply chain shape, exposing reagent manufacturers to input cost volatility that compresses margins in economy-grade assay segments while amplifying premium-tier pricing power for certified suppliers with secured precursor allocations.
Pricing Analysis
Cost-plus contracts with latex nanoparticle indexation dominate procurement between German reference laboratories and reagent suppliers, locking in multi-year pricing stability. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared kits with lot-to-lot guarantees from bulk reagent volumes and unvalidated research-grade materials. Price differentiation rests on certification grade and volume scale, with ISO 15189-accredited hospitals showing lowest sensitivity and urgent care networks facing acute margin pressure from cartridge-based point-of-care alternatives.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese diagnostic equipment distributors ease working capital burdens for mid-scale assay developers competing against conglomerate bundling strategies. Raw material dependencies draw from Chinese gold salt refineries, Japanese latex polymer producers, and Indian antibody preparation facilities. Single-source vulnerability concentrates in high-purity nanoparticle precursor synthesis. Distribution runs through instrument-reagent bundling contracts that anchor hospital system procurement under three-to-five-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as veterinary diagnostic chains and point-of-care urgent care networks create demand-side niches underserved by incumbent bundling strategies focused on centralized hospital laboratories.
For Market Incumbents: Entrench competitive positioning through backward integration into nanoparticle precursor synthesis, securing captive supply of high-purity gold salts against East Asian supply disruptions. Deepen firmware adaptation capabilities for legacy chemistry analyzer retrofits, converting installed base concentration into switching-cost barriers against modular competitors. Mass spectrometry substitution in reference laboratories and IVDR compliance burdens on mid-scale developers constitute immediate threats requiring certification investment and platform standardization. For New Entrants and Emerging Players: Companion animal reference laboratories in Germany and Japan represent the most penetrable white-space target, with pet insurance expansion driving diagnostic spending faster than saturated human clinical markets. Point-of-care urgent care networks in the United States offer secondary entry through cartridge-based D-dimer triage systems displacing slower immunofluorescence workflows. Go-to-market execution should prioritize EMA Green Deal alignment for sustainable manufacturing credentials that unlock European tender preferences. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized assay developers with notified body relationships and quality-certified manufacturing infrastructure. Long-term viability over the projection horizon hinges on regulatory navigation capabilities rather than pure scale. Acquisition targets should demonstrate IVDR technical documentation maturity and FDA 510(k) clearance track records. The signal to watch is mid-scale developer distress from extended regulatory timelines prompting portfolio divestitures.| Strategic Initiative | Industry Significance |
|---|---|
| EMA IVDR Technical Documentation Investment | Notified body relationships accelerate European market access for Class C and D devices. |
| Gold Nanoparticle Precursor Backward Integration | Captive supply secures cost stability against East Asian refining center volatility. |
| Veterinary Diagnostic Panel Expansion | Companion animal reference laboratories in Germany and Japan drive faster-growing adjacent demand. |
| Point-of-Care Cartridge Platform Development | Urgent care network adoption opens settings previously served by centralized hospital laboratories. |
| Legacy Analyzer Firmware Adaptation Program | Technical support resources accelerate customer go-live dates and strengthen switching costs. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, hospital procurement officers, reagent manufacturing executives, and regulatory affairs specialists anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation databases, ISO 15189 accreditation registries, and hospital GPO contract disclosures. Bottom-up assay volume modeling and top-down market sizing triangulated across product type, application, technology, and end user segmentation dimensions.
Scenario-bracketing framed analytical outputs across the analysis window, with sensitivity testing around regulatory timeline delays and nanoparticle supply disruption events. Segmentation modeling incorporated assay kit versus reagent versus instrument revenue splits, clinical diagnostics versus veterinary testing growth trajectories, and microplate reader versus lateral flow technology adoption patterns. CAGRs derived from installed base expansion rates, consumable pull-through coefficients, and pricing trajectory assumptions for premium-certified versus economy-grade product tiers.
Macroeconomic conditions sit as an overlay; deviation in healthcare infrastructure investment cycles, diagnostic reimbursement rates, or precious metal commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and supply chain resilience. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Neoantigen Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Biochips Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Global Biological Stains Market