
 Drug Discovery Enzymes Market | 2026-2036
Drug Discovery Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Discovery Enzymes Market Foresight
A shortage of protein biochemists with specialized enzyme engineering expertise is unwinding capacity expansion timelines across the sector. Thermo Fisher Scientific leverages its vertical integration across reagent manufacturing and analytical instrumentation to dominate supply chain reliability. Merck KGaA anchors its position through deep catalog breadth in recombinant enzymes for drug target validation. Promega Corporation differentiates via proprietary luciferase reporter systems integrated into kinase and protease screening panels.
Drug discovery enzymes comprise biocatalysts—primarily recombinant proteins, native extracts, and synthetic variants—engineered for substrate specificity, thermal stability, and kinetic precision in pharmaceutical research workflows. These enzymes catalyze molecular transformations essential for target identification, lead compound optimization, and quantitative assay development in therapeutic pipelines. Recombinant enzymes command the largest revenue share due to batch consistency and customizable expression systems, while CRISPR-associated nucleases represent the fastest-expanding technology segment as gene-editing modalities proliferate in target validation. High-throughput screening applications sustain mature demand volumes, though assay development is capturing expanding margin pools as multiplexed formats grow more complex.
FDA quality standards for diagnostic-grade enzymes and EPA guidelines for biocatalyst manufacturing waste streams shape product certification requirements and facility siting decisions in the United States. ISO 13485 and GMP-adjacent quality frameworks govern supplier qualification for pharmaceutical end users, raising barriers for uncertified entrants. Stakeholders must monitor evolving EMA guidance on cell-free enzyme production systems, as European regulatory alignment will determine cross-border market access for next-generation biocatalyst suppliers.
Market Dynamics
CRISPR-associated nucleases are compressing timelines for target validation workflows, forcing suppliers to retool expression systems toward gene-editing-grade specificity. Contract research organizations now demand batch-certified enzymes with documented kinetic precision, tightening qualification standards across the value chain.
Growth Catalysts
- FDA Accelerated Approval Pathways:Biologics developers require validated assay-grade enzymes for IND-enabling studies, expanding procurement volumes among Boston and San Diego R&D clusters.
- High-Throughput Screening Automation:Robotics integration in lead optimization workflows demands thermostable biocatalysts with minimal batch-to-batch variation.
- Cell-Free Enzyme Production:EMA guidance on synthetic biology manufacturing systems is opening regulatory pathways for next-generation recombinant expression platforms.
Market Restraints
- Specialized Talent Scarcity:Protein biochemists with directed evolution expertise command premium compensation, stretching R&D budgets at mid-scale suppliers.
- Supply Concentration Risk:Three vendors control approximately 70% of GMP-adjacent recombinant enzyme capacity, creating vulnerability to single-site disruptions.
- ISO 13485 Certification Burden:Diagnostic-grade enzyme qualification requires 18-24 month validation timelines, freezing out uncertified entrants from pharmaceutical procurement pools.
Strategic Opportunities
- Multiplexed Assay Formats:Kinase and protease screening panels integrating luciferase reporters enable premium pricing for integrated reagent-instrument bundles.
- Biocatalyst Manufacturing Waste Recovery:EPA guidelines for enzymatic process waste streams incentivize closed-loop production facility investments with tax-advantaged depreciation schedules.
- Gene-Editing Modalities:CRISPR-Cas12 and base editor variants require engineered nucleases with modified PAM specificity, opening white space beyond wild-type Cas9 supply.
Industry Challenges
- Expression System Scale-Up:Translating bench-scale kinetic performance to bioreactor volumes demands proprietary strain engineering capabilities held by few contract manufacturers.
- Cross-Border Regulatory Alignment:Divergent EMA and FDA positions on cell-free production documentation create dual-track submission burdens for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Discovery Enzymes Market |
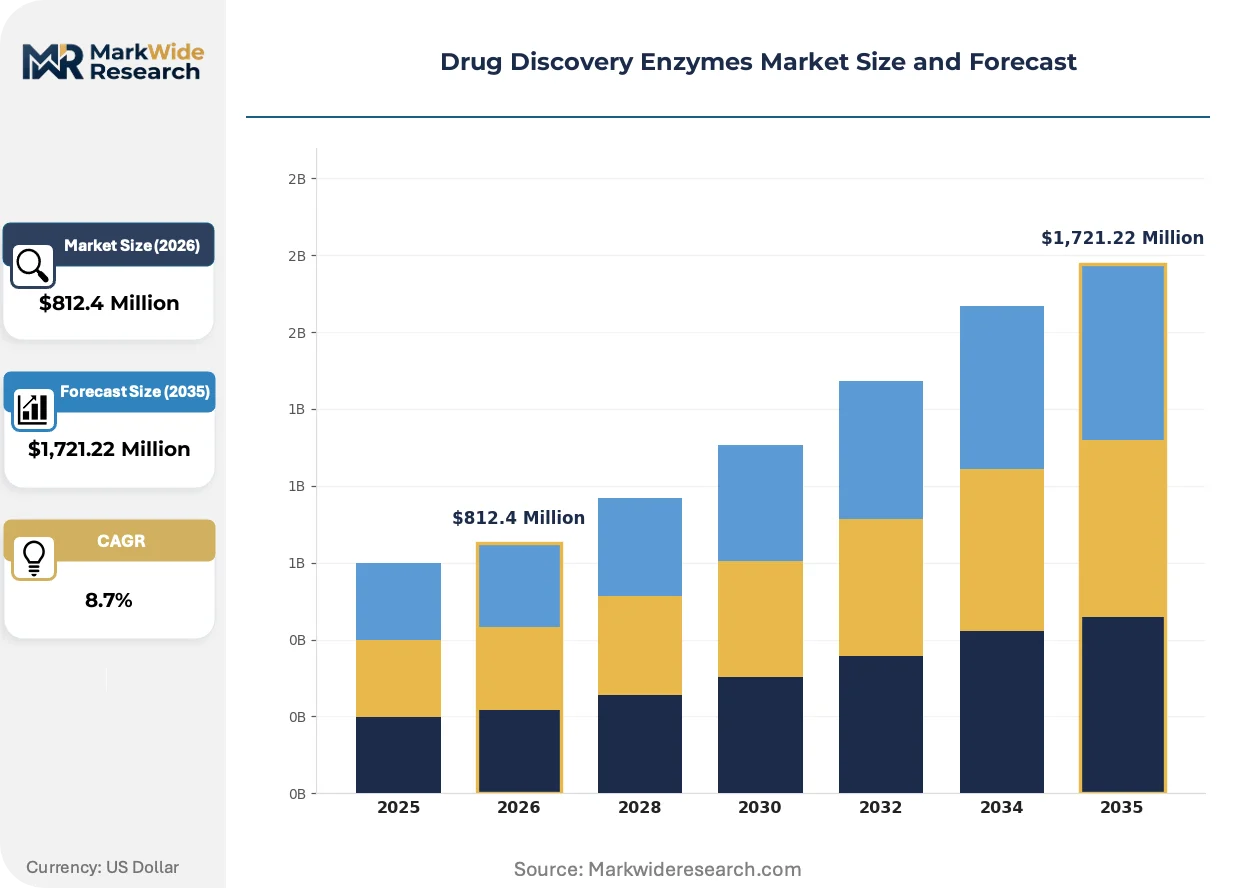
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,721.22 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Enzymes, Synthetic Enzymes, Native Enzymes, Diagnostic Enzymes Application: Target Identification, Lead Optimization, Assay Development, Screening End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutions, Contract Research Organizations Technology: High-Throughput Screening, CRISPR, Mass Spectrometry, Gene Editing |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Sigma-Aldrich Co. LLC, Agilent Technologies, F. Hoffmann-La Roche, Enzo Life Sciences, Inc., Promega Corporation, Takara Bio Inc., New England Biolabs, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Discovery Enzymes Market Shifts & Advancements
Synthetic biology toolkits are compressing enzyme engineering cycles from months to weeks, reshaping how suppliers build competitive moats. The convergence of computational protein design with automated screening is redistributing value capture across the supply chain.
Engineered CRISPR nucleases with expanded targeting range are supplanting first-generation Cas9 variants in high-value therapeutic editing applications. Gene therapy developers at contract research organizations have adopted these variants within 18 months of commercial release. The shift is compressing addressable market windows for legacy wild-type enzyme inventories while rewarding suppliers with rapid variant-to-product pipelines.
EMA guidance on cell-free enzyme production systems is tightening documentation requirements for synthetic biology manufacturing. Suppliers must now demonstrate absence of host-cell DNA below 10 parts per billion to qualify for pharmaceutical-grade certification. European contract manufacturers are responding by segregating cell-free production lines from traditional fermentation assets, raising facility capital intensity.
Assay development teams now unbundle reagent procurement from instrument service contracts, reversing decade-old bundled pricing structures. Multiplexed screening formats demand enzyme lots with matched kinetic profiles across 96- and 384-well configurations. This specification compression is most visible among San Diego biopharma clusters, where high-throughput screening centers negotiate lot-matched batch contracts directly with specialty enzyme suppliers.
Drug Discovery Enzymes Market Segmentation
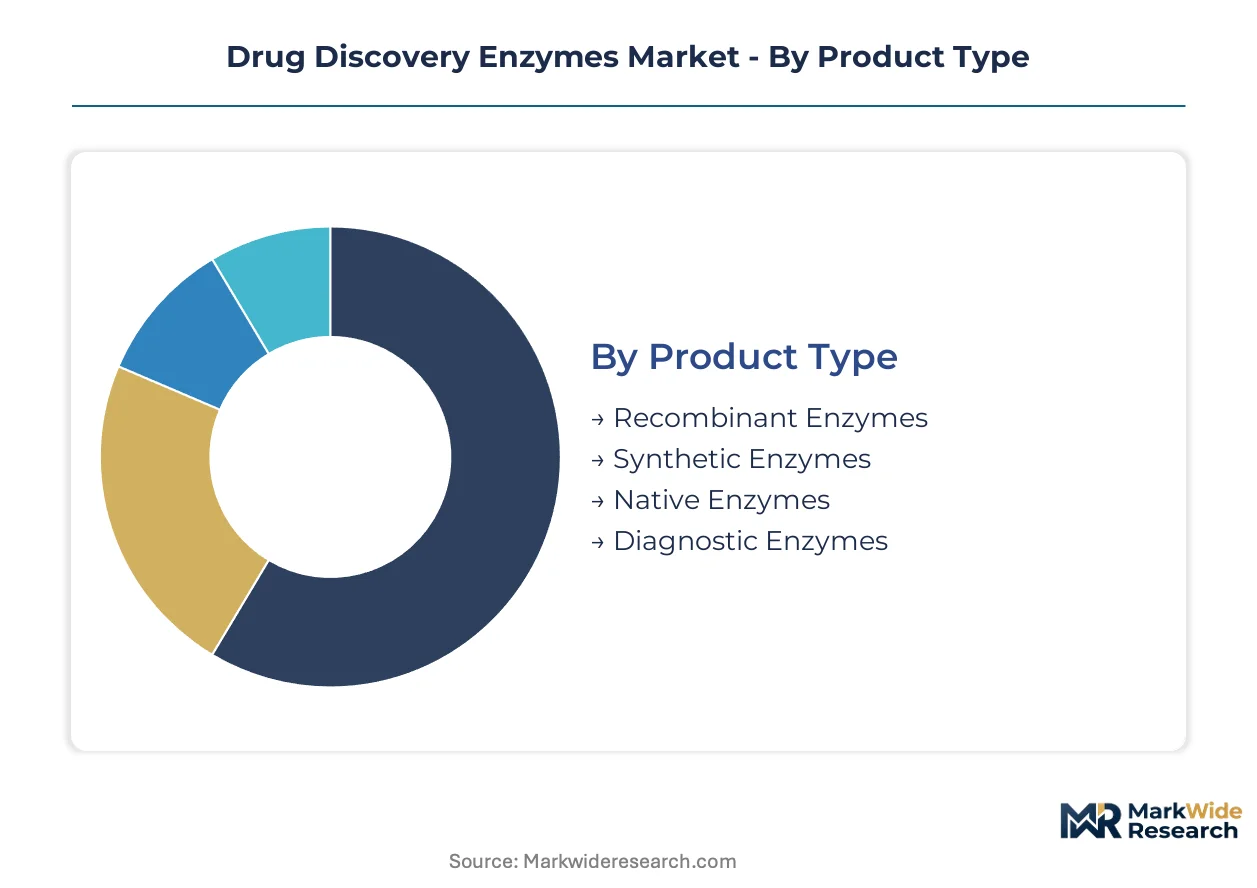
Enzyme procurement decisions in drug discovery pivot on certification grade, kinetic precision requirements, and workflow automation compatibility. Segmentation reveals how regulatory stringency and application complexity redistribute margin pools across supplier tiers.
Product Type:
FDA diagnostic-grade standards and ISO 13485 certification burdens stratify supply reliability across enzyme categories, concentrating pharmaceutical procurement among validated manufacturing tiers.
- Recombinant Enzymes:Batch-consistent proteins expressed in bacterial, yeast, or mammalian systems with customizable post-translational modifications. Pharmaceutical companies in Boston and San Diego R&D clusters demand documented absence of host-cell DNA below regulatory thresholds for IND-enabling studies.
- Synthetic Enzymes:Chemically synthesized biocatalysts with non-natural amino acid incorporation enabling expanded substrate scope. Academic research institutions leverage these variants for mechanistic studies where recombinant expression fails, though manufacturing scale remains constrained.
- Native Enzymes:Isolated from natural sources without genetic modification; cost-competitive for basic screening applications.
- Diagnostic Enzymes:Assay-grade formulations meeting FDA quality standards for companion diagnostic development.
Recombinant Enzymes handle the majority of throughput; Synthetic Enzymes are gaining share fastest on gene-edging modality expansion.
Application:
Workflow automation intensity and multiplexing complexity determine enzyme specification tiers, with high-value applications commanding kinetic-matched batch contracts.
- Target Identification:CRISPR-associated nucleases and reporter systems for gene knockout validation. Contract research organizations compress timelines using engineered Cas12 variants with expanded PAM specificity.
- Lead Optimization:Thermostable kinases and proteases integrated into robotics-enabled high-throughput screening workflows. San Diego biopharma clusters negotiate lot-matched batch contracts for 384-well format consistency.
- Assay Development:Multiplexed formats demanding enzyme lots with matched kinetic profiles across plate configurations.
- Screening:Standardized biocatalyst panels for primary library evaluation.
Lead Optimization absorbs the largest procurement volumes; Target Identification climbs fastest on gene-editing therapeutic pipelines.
End User:
Capital intensity and regulatory exposure differentiate procurement patterns, with commercial-stage developers imposing stringent supplier qualification protocols.
- Pharmaceutical Companies:Integrated R&D organizations with captive assay development capabilities. Boston-based developers require GMP-adjacent documentation for IND-submission enzyme lots.
- Biotechnology Firms:Venture-funded developers outsourcing target validation to contract research organizations. These entities prioritize rapid variant-to-product pipelines over legacy catalog breadth.
- Academic Research Institutions:Price-sensitive procurement with tolerance for native enzyme variability.
- Contract Research Organizations:High-throughput screening service providers aggregating demand across client portfolios.
Contract Research Organizations aggregate the broadest enzyme portfolios; Biotechnology Firms are expanding procurement fastest on biologics pipeline growth.
Technology:
Instrumentation integration requirements and data reproducibility standards shape enzyme specification, with mass spectrometry and gene-editing modalities imposing distinct kinetic precision demands.
- High-Throughput Screening:Robotics-compatible thermostable biocatalysts with minimal batch-to-batch variation. EMA guidance on cell-free production systems is opening regulatory pathways for next-generation expression platforms serving this segment.
- CRISPR:Engineered nucleases with modified PAM specificity for therapeutic gene editing. Base editor variants require suppliers with rapid variant-to-product pipelines beyond wild-type Cas9 supply.
- Mass Spectrometry:Enzyme formulations compatible with quantitative proteomics workflows.
- Gene Editing:Broad category encompassing zinc-finger and TALEN platforms alongside CRISPR systems.
High-Throughput Screening sustains mature demand volumes; CRISPR shows the steepest expansion trajectory on therapeutic editing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drug discovery enzyme consumption patterns diverge sharply by geography. The United States concentrates procurement in validated assay-grade enzymes for IND-enabling studies, while European and Asian markets prioritize cell-free production systems and cost-engineered recombinant variants respectively.
United States
FDA accelerated approval pathways for biologics drive validated enzyme procurement volumes. EPA guidelines for biocatalyst manufacturing waste streams shape facility siting decisions in pharmaceutical corridors. Boston and San Diego R&D clusters negotiate lot-matched batch contracts directly with specialty suppliers for high-throughput screening workflows.
Germany
EMA guidance on cell-free enzyme production systems positions German contract manufacturers as regulatory pathway pioneers. REACH compliance requirements for synthetic biology inputs elevate documentation standards for recombinant expression platforms. The Rhine-Main biotech corridor segregates cell-free production lines from traditional fermentation assets to meet pharmaceutical-grade certification thresholds.
China
NMPA alignment with international GMP-adjacent frameworks expands domestic recombinant enzyme capacity for export markets. MIIT industrial biotechnology initiatives accelerate cell-free production system investments. Yangtze River Delta biopharma clusters integrate synthetic biology toolkits to compress enzyme engineering cycles for therapeutic editing applications.
Japan
METI precision medicine programs sustain demand for diagnostic-grade enzymes in companion diagnostic development. PMDA quality standards for biologics assay components tighten supplier qualification protocols. Kanto region pharmaceutical developers prioritize thermostable biocatalysts with documented kinetic precision for robotics-enabled lead optimization.
United Kingdom
MHRA post-Brexit regulatory autonomy creates dual-track submission burdens for suppliers serving both UK and EU markets. National industrial biotechnology strategies incentivize closed-loop production facility investments. London-Oxford-Cambridge golden triangle research institutions leverage synthetic enzyme variants for mechanistic studies where recombinant expression fails.
Drug Discovery Enzymes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in drug discovery enzyme supply. Thermo Fisher Scientific leverages backward integration across reagent manufacturing and analytical instrumentation to dominate supply chain reliability. Merck KGaA anchors position through catalog breadth in recombinant enzymes. Promega Corporation differentiates via proprietary reporter systems integrated into screening panels. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with ISO 13485 certification serving as the critical gating factor for pharmaceutical procurement access.
Within the integrated life science tools tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify archetypes of supply chain control and catalog depth respectively. Promega Corporation occupies a specialist position anchored in detection chemistry integration. Takara Bio Inc. represents the Asia-Pacific manufacturing scale vector, while New England Biolabs, Inc. exemplifies the research-grade enzyme purity archetype. Agilent Technologies and F. Hoffmann-La Roche sit within the analytical instrumentation-enzyme bundle segment, though their strategic emphasis diverges toward platform integration rather than standalone biocatalyst supply.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Sigma-Aldrich Co. LLC |
| Agilent Technologies |
| F. Hoffmann-La Roche |
| Enzo Life Sciences, Inc. |
| Promega Corporation |
| Takara Bio Inc. |
| New England Biolabs, Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Boston biopharma clusters and specialty enzyme suppliers lock in supply access while anchoring price visibility across multi-year IND-enabling study timelines. These contracts bundle ISO 13485-certified recombinant enzyme lots with kinetic documentation, insulating procurement teams from spot-market volatility in GMP-adjacent manufacturing tiers.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical procurement, with pricing stratifying across diagnostic-grade, assay-grade, and research-grade certification tiers. Price differentiation hinges on batch-to-batch kinetic precision documentation and FDA submission-ready quality frameworks. Cost compression in research-grade native enzymes is intensifying as academic institutions consolidate purchasing through cooperative agreements. Biotechnology firms exhibit highest price sensitivity, while commercial-stage developers absorb premiums for validated IND-enabling lots.
Supply Chain Analysis
Inbound logistics costs from German cell-free production facilities to United States R&D clusters hinge on cold-chain container availability through Rotterdam-Charleston trade lanes. Manufacturing concentrates in Germany, the United States, and China, with raw material dependencies on recombinant expression plasmids, specialized fermentation media, and chromatography resins. Single-source vulnerability runs through the three vendors controlling GMP-adjacent recombinant enzyme capacity. Distribution runs through direct supplier relationships with contract research organizations and pharmaceutical procurement teams, bypassing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene-editing modality proliferation is compressing target validation timelines and reshaping competitive positioning across enzyme supply tiers. FDA accelerated approval pathways for biologics intensify demand for validated assay-grade enzymes, creating structural advantages for certified manufacturers.
For Market Incumbents: Shield catalog positions by accelerating variant-to-product pipelines for engineered CRISPR nucleases beyond wild-type Cas9 supply. Invest in segregated cell-free production lines to meet EMA pharmaceutical-grade certification thresholds. Capacity expansion in the Rhine-Main biotech corridor addresses cross-border regulatory alignment risks while capturing European contract manufacturing demand. For New Entrants and Emerging Players: Lead with synthetic enzyme variants incorporating non-natural amino acids for mechanistic studies where recombinant expression fails. Target academic research institutions as the most penetrable segment, where price sensitivity tolerates native enzyme variability. Pursue direct lot-matched batch contracts with San Diego high-throughput screening centers as a go-to-market anchor. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale suppliers with proprietary strain engineering capabilities and ISO 13485 certification in progress. Long-term viability favors entities with rapid variant-to-product pipelines serving gene-editing therapeutic applications. Watch EMA guidance finalization on cell-free production documentation as the inflection signal determining cross-border market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks pharmaceutical procurement pools currently frozen to uncertified entrants. |
| Cell-Free Production Scale-Up | Positions suppliers ahead of EMA synthetic biology manufacturing documentation requirements. |
| Strategic Partnership with CROs | Secures lot-matched batch contracts for robotics-enabled high-throughput screening workflows. |
| Acquisition of Specialist Enzyme Engineering Firm | Addresses protein biochemist talent scarcity compressing capacity expansion timelines. |
| Backward Integration into Expression Plasmid Supply | Reduces raw material dependency risk in recombinant enzyme manufacturing. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, contract research organization procurement managers, and protein biochemistry R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA biologics guidance documents, EMA synthetic biology manufacturing consultations, ClinicalTrials.gov enzyme-dependent study registrations, and SEC 10-K filings from integrated life science tools providers. Bottom-up enzyme procurement volume estimates triangulated against top-down market sizing from certification-grade production capacity.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including enzyme product type, application workflow, end-user capital intensity, and regional regulatory cluster. CAGRs were derived from enrollment trajectories in gene-editing therapeutic pipelines and automation penetration rates in high-throughput screening centers. Forecast inputs incorporated CRISPR-associated nuclease variant commercialization timelines and ISO 13485 certification completion rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA accelerated approval pathway utilization or EMA cell-free production guidance finalization would require recalibration. Forecasts reflect assumptions regarding protein biochemist labor market elasticity and recombinant expression platform yield improvements. Recalibration cycles align with material shifts in gene-editing therapeutic pipeline advancement and synthetic biology manufacturing regulatory harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
BOD Incubator Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
E2 Antibody Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
PD L1 Biomarker Testing Market