

Enzymatic DNA Synthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Enzymatic DNA Synthesis Market Insights
Platform licensing revenue is reshaping competitive economics in enzymatic DNA synthesis. Twist Bioscience leverages silicon-based DNA writing architecture to sustain high-throughput production economics. DNA Script anchors European market presence through benchtop enzymatic instruments. Molecular Assemblies specializes in polymerase-driven synthesis protocols that differentiate its technical approach.
Enzymatic DNA synthesis employs engineered terminal transferases and DNA polymerases to assemble nucleotide sequences without organic chemistry cycles, achieving error rates below one per thousand bases in optimized systems. The process serves gene assembly, oligonucleotide production, and synthetic biology construction pipelines. DNA polymerases command the largest product type position due to their catalytic versatility across reaction conditions. Automated deployment platforms represent the fastest-expanding segment as biotech firms integrate synthesis into continuous workflows. Pharmaceutical developers concentrate end-user spending on validated oligonucleotide supply chains.
FDA oversight of synthetic nucleic acids as gene therapy starting materials shapes vendor qualification requirements in the United States. EPA chemical manufacturing exemptions for biologically produced oligonucleotides influence process economics versus phosphoramidite chemistry. ISO 13485 quality management expectations extend from diagnostic applications into research-grade supply agreements. Stakeholders must monitor how EMA's evolving ATMP guidance treats enzymatically synthesized genetic material versus chemically derived equivalents.
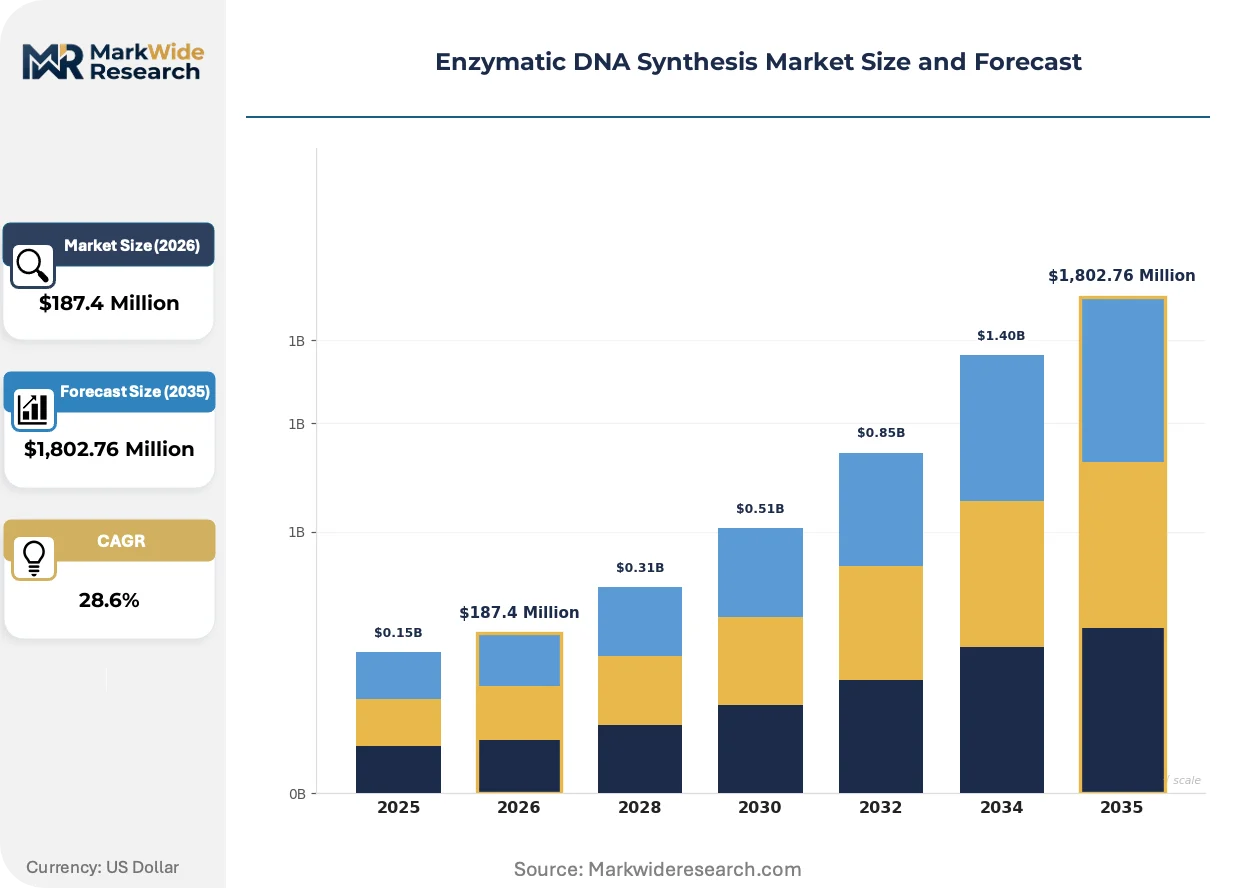
Market Dynamics
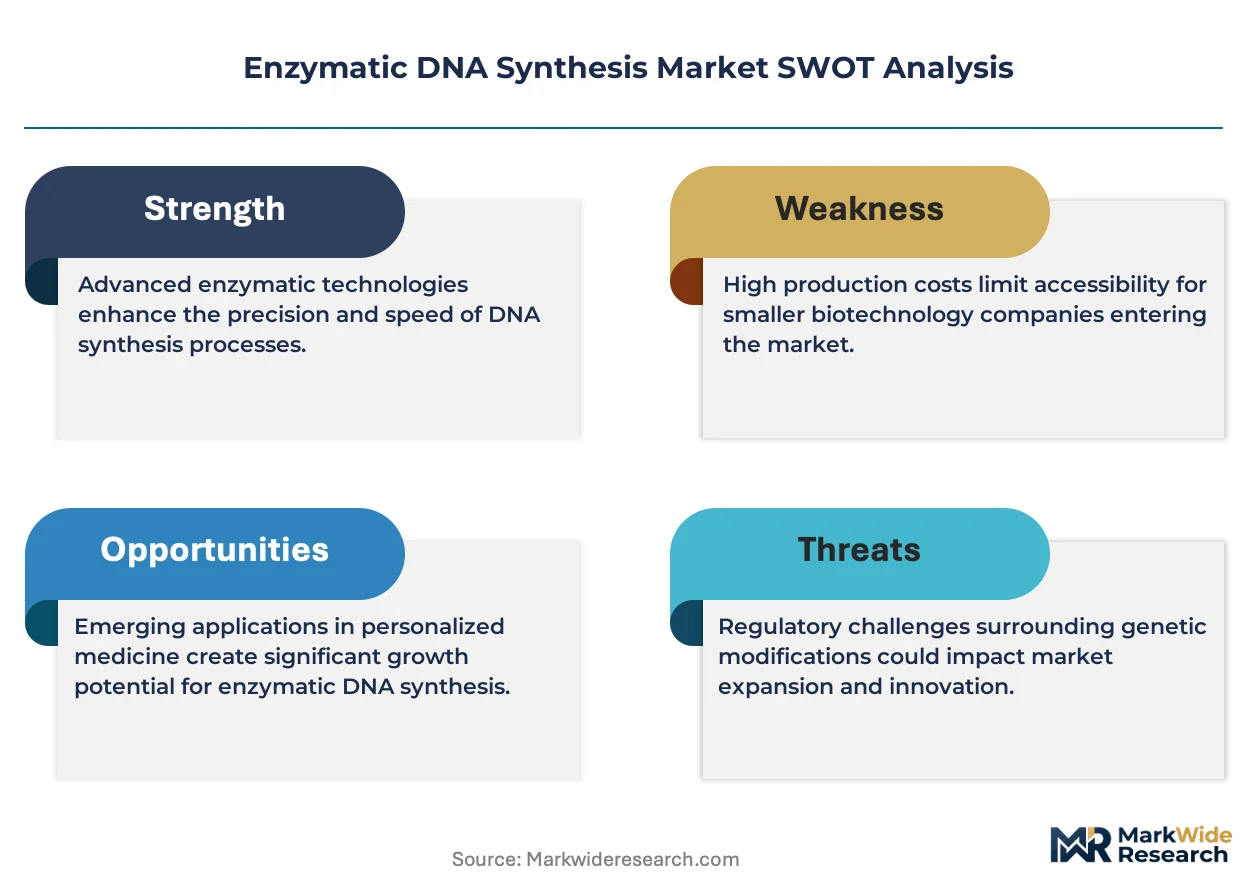
Platform licensing revenue is compressing traditional instrument sales cycles as enzymatic DNA synthesis vendors pivot from capital equipment to recurring consumable streams. This shift rewards integrated workflow providers and marginalizes pure-play hardware suppliers.
Growth Catalysts
- Gene therapy manufacturing scale-up:FDA's evolving guidance on synthetic nucleic acids as starting materials is forcing pharmaceutical developers to qualify enzymatic supply chains for ATMP production.
- REACH chemical manufacturing exemptions:EPA parallel frameworks for biologically produced oligonucleotides reduce hazardous waste disposal costs versus phosphoramidite chemistry cycles.
- Boston-Switzerland demand clustering:Synthetic biology startups concentrated in Massachusetts and Basel are driving benchtop instrument procurement ahead of centralized service bureau adoption.
Market Restraints
- Terminal transferase supply concentration:Engineered enzyme production relies on a limited supplier base in Denmark and California, creating input vulnerability.
- Phosphoramidite chemistry cost floor:Mature chemical synthesis infrastructure maintains price pressure on enzymatic alternatives below 200-base lengths.
- ISO 13485 diagnostic-grade certification:Quality management system requirements extend into research supply agreements, extending vendor qualification timelines.
Strategic Opportunities
- India's biologics manufacturing expansion:CDSCO's streamlined biosimilar pathways create entry points for enzymatic oligonucleotide suppliers serving contract research organizations.
- Continuous bioprocessing integration:Convergence of enzymatic synthesis with automated liquid handling platforms enables real-time gene assembly within cell therapy workflows.
- EU Green Deal chemical substitution mandates:REACH authorization pressures on acetonitrile-intensive phosphoramidite processes favor aqueous enzymatic alternatives.
Industry Challenges
- Polymerase engineering talent scarcity:Protein design expertise for error-rate optimization remains concentrated at academic institutions in Cambridge and Zurich.
- Legacy LIMS integration friction:Biopharma quality systems built around chemical synthesis batch records require reconfiguration for enzymatic reaction monitoring parameters.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzymatic DNA Synthesis Market Trends and Innovations
Synthetic biology workflows are demanding synthesis architectures that bridge research-scale flexibility with manufacturing-grade reproducibility. Vendors are responding with platform designs that collapse the traditional handoff between discovery and production.
Silicon-based DNA writing substrates are hybridizing with enzymatic polymerase extension to achieve density gains impossible in either pure approach. Pharmaceutical developers are adopting these hybrid platforms for antibody discovery campaigns requiring variant libraries beyond 10,000 sequences. The convergence is compressing the economic threshold where enzymatic synthesis displaces chemical methods for gene-length constructs.
EMA's evolving ATMP guidance is creating divergent qualification pathways for enzymatically versus chemically synthesized genetic material. Swissmedic has issued early clarity favoring enzymatic provenance in cell therapy starting materials. Gene therapy CDMOs are restructuring supplier qualification protocols to capture this regulatory arbitrage ahead of formal harmonization.
Service bureau procurement is fragmenting as mid-size biotechs acquire benchtop enzymatic instruments to protect intellectual property. The shift bypasses traditional centralized synthesis providers in favor of captive production capacity. This pattern is most visible in Boston's Kendall Square cluster, where venture-backed startups prioritize speed-to-data over per-base cost optimization.
Enzymatic DNA Synthesis Market Segmentation
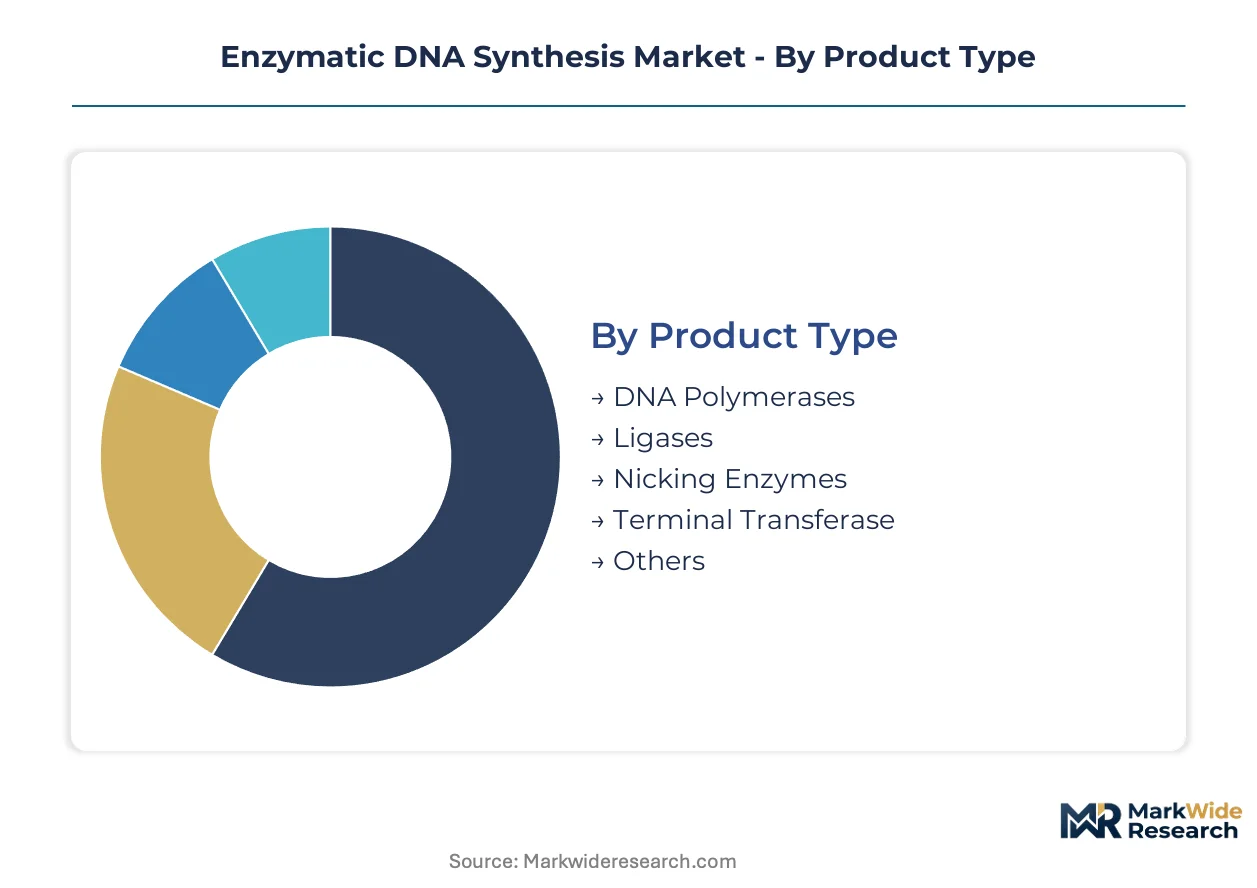
Enzymatic DNA synthesis segments diverge sharply in procurement velocity, with consumable enzymes turning monthly while automated platforms cycle across multi-year capital budgets. Understanding these cadence differences illuminates where vendor revenue concentrates versus where expansion investments flow.
Product Type:
Cycle times range from quarterly polymerase replenishment to multi-year terminal transferase development contracts, compressing margin capture into distinct temporal windows.
- DNA Polymerases:Engineered variants with proofreading domains dominate catalytic versatility across reaction conditions. Pharmaceutical developers in Basel and Boston concentrate procurement on high-fidelity polymerases for gene therapy starting materials, driven by FDA's evolving nucleic acid guidance.
- Terminal Transferase:Modified enzymes enable template-independent nucleotide addition at 3' termini without organic chemistry cycles. Supply concentrates among engineered strain producers in Denmark and California, creating input vulnerability as gene assembly scales.
- Ligases:DNA joining enzymes seal nicks in phosphodiester backbones during assembly workflows.
- Nicking Enzymes:Site-specific single-strand cleavage tools enable isothermal amplification protocols.
- Others:Auxiliary enzymes including exonucleases and methyltransferases complete synthesis toolkit coverage.
DNA Polymerases anchors the volume base while Terminal Transferase gains share at the steepest rate.
Application:
Cost tiers separate commodity oligonucleotide production from premium gene therapy starting material qualification, with synthetic biology occupying the mid-tier expansion zone.
- Oligonucleotide Synthesis:Short sequence production for primers and probes represents the highest-throughput application segment. Diagnostic laboratories in Massachusetts and Switzerland drive demand for ISO 13485-compliant enzymatic supply chains, constrained by phosphoramidite chemistry cost floors below 200-base lengths.
- Gene Assembly:Multi-kilobase construct construction serves antibody discovery and cell therapy workflows. Biotech firms in Kendall Square prioritize speed-to-data over per-base cost optimization, accelerating benchtop instrument adoption.
- Synthetic Biology:Standardized biological part construction bridges research flexibility with manufacturing reproducibility.
- Gene Editing:CRISPR guide RNA and donor template production enables precision genome engineering.
- Molecular Diagnostics:Isothermal amplification and detection probe synthesis supports point-of-care testing expansion.
Oligonucleotide Synthesis captures the largest revenue pool while Gene Assembly climbs the fastest.
End User:
Customer type determines procurement modality, with pharmaceutical developers demanding validated supply chains and research institutes prioritizing protocol flexibility.
- Pharmaceutical Developers:Gene therapy manufacturers require enzymatic synthesis documentation for ATMP starting material qualification. Swissmedic's early clarity on enzymatic provenance advantages drives CDMO supplier restructuring in Basel.
- Biotech Firms:Venture-backed startups in Boston's Kendall Square cluster acquire captive benchtop capacity to protect intellectual property, bypassing centralized service bureaus.
- Research Institutes:Academic laboratories in Cambridge and Zurich concentrate protein engineering expertise for error-rate optimization.
- Diagnostic Laboratories:Clinical testing facilities pursue ISO 13485 certification extension into research-grade supply agreements.
Pharmaceutical Developers dominate absolute spending while Biotech Firms expand most quickly.
Deployment:
Volume concentration favors automated platforms as biopharma quality systems reconfigure from chemical synthesis batch records toward enzymatic reaction monitoring parameters.
- Automated Platforms:Integrated liquid handling systems enable real-time gene assembly within cell therapy workflows. Continuous bioprocessing convergence rewards vendors pivoting from capital equipment to recurring consumable streams.
- In-house Synthesis:Captive production capacity protects sequence intellectual property and accelerates iteration cycles.
- Outsourced Services:Centralized synthesis providers face fragmentation as mid-size biotechs internalize capacity.
- Manual Protocols:Bench-scale enzymatic reactions persist in protocol development and troubleshooting workflows.
Automated Platforms represent the fastest-expanding trajectory while In-house Synthesis captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineered enzyme production clusters in Denmark and California constrain input availability for gene assembly scaling. FDA guidance on synthetic nucleic acids as gene therapy starting materials reshapes vendor qualification timelines in the United States. EMA's evolving ATMP guidance creates divergent pathways across European markets.
United States
Gene therapy manufacturing scale-up and synthetic biology startup formation drive instrument procurement in Massachusetts and California. FDA oversight of synthetic nucleic acids as starting materials forces pharmaceutical developers to qualify enzymatic supply chains for ATMP production. Boston's Kendall Square cluster hosts venture-backed startups acquiring captive benchtop capacity to protect intellectual property.
Switzerland
Pharmaceutical research concentration and cell therapy CDMO expansion anchor demand in Basel and Zurich. Swissmedic has issued early regulatory clarity favoring enzymatic provenance in cell therapy starting materials. The Basel pharmaceutical research belt drives supplier qualification protocol restructuring among gene therapy contract manufacturers.
United Kingdom
Antibody discovery campaigns and variant library construction sustain demand for high-throughput synthesis platforms. REACH authorization pressures on acetonitrile-intensive chemical processes favor aqueous enzymatic alternatives. Cambridge concentrates protein engineering expertise for polymerase error-rate optimization across academic and commercial laboratories.
Denmark
Engineered terminal transferase supply and biologics manufacturing infrastructure position the country as critical enzyme source. EPA parallel frameworks for biologically produced oligonucleotides reduce hazardous waste disposal costs versus phosphoramidite chemistry. Copenhagen-area suppliers face input vulnerability concentration as gene assembly scales globally.
India
Biologics manufacturing expansion and contract research organization growth create entry points for enzymatic oligonucleotide suppliers. CDSCO streamlined biosimilar pathways accelerate regulatory navigation for novel synthesis platforms. Maharashtra and Karnataka host emerging demand clusters as domestic biotech capacity matures.
Enzymatic DNA Synthesis Market Competitive Landscape
Silicon-based substrate specialists and benchtop instrument providers split the market across divergent deployment modalities. The vendor landscape organizes around three strategic archetypes: integrated workflow platforms, pure-play enzyme suppliers, and hybrid hardware-consumable bundlers. Consolidation pressure favors recurring revenue models over capital equipment cycles. Competitive moves center on platform licensing expansion and geographic footprint extension into Asian manufacturing hubs.
Among integrated platform developers, Twist Bioscience and DNA Script occupy positions at opposite ends of the deployment spectrum. Twist Bioscience represents the silicon-based DNA writing architecture archetype, while DNA Script anchors the European benchtop instrument segment. Molecular Assemblies exemplifies the polymerase-driven synthesis protocol specialization within the enzyme-centric tier.
| Leading Market Players |
|---|
| Telesis Bio |
| Twist Bioscience |
| GenScript Biotech |
| Evonetix |
| Ansa Biotechnologies |
| Camena Bioscience |
| Molecular Assemblies |
| DNA Script |
| Touchlight |
| Others |
Pricing and Supply Chain Analysis
Engineered terminal transferase production concentrates in Denmark and California, tethering margin capture to enzyme supplier qualification tiers and creating pricing power stratification between validated pharmaceutical-grade and research-grade supply chains.
Pricing Analysis
Consumable reagent subscriptions and extended service contracts now drive lifetime value beyond initial instrument placement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-qualified gene therapy starting material grades from ISO 13485 diagnostic tiers and uncertified research supply. Pricing pressure stems from phosphoramidite chemistry cost floors below 200-base lengths. Biotech startups in Boston's Kendall Square cluster exhibit lowest price sensitivity, prioritizing speed-to-data over per-base optimization.
Supply Chain Analysis
Upstream nucleotide feedstock and engineered enzyme strain development anchor supply in Denmark, California, and Switzerland. Critical inputs include modified terminal transferases, high-fidelity DNA polymerases, and nucleotide triphosphate reagents. Single-source vulnerability concentrates around Copenhagen-area enzyme suppliers as gene assembly scales. Distribution runs through qualified CDMO networks and direct benchtop instrument channels to pharmaceutical developers and biotech firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform licensing revenue is reshaping vendor economics, with recurring consumable streams expanding faster than capital equipment sales and creating durable service-attach opportunities across qualified supply chains.
For Market Incumbents: Entrench position through backward integration into engineered enzyme production and captive nucleotide supply. Secure terminal transferase strain development capacity in Denmark or California to offset input concentration risk. Invest in FDA pre-submission pathways for gene therapy starting material qualification ahead of formal guidance harmonization. For New Entrants and Emerging Players: Establish a beachhead in India's contract research organization segment, where CDSCO streamlined biosimilar pathways reduce regulatory friction. Target mid-size biotechs in Boston and Basel seeking captive benchtop capacity to bypass centralized service bureaus. Lead with aqueous enzymatic platforms that capture EU Green Deal chemical substitution mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed enzymatic instrument developers facing Series C-D financing thresholds. Long-term viability hinges on recurring revenue ratio and consumable attachment rates. Watch for FDA draft guidance on synthetic nucleic acid starting materials as inflection signal for qualification-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Licensing Expansion | Recurring consumable revenue displaces capital equipment cycles at Twist Bioscience and DNA Script. |
| Regulatory Pre-Qualification Investment | Early FDA engagement on gene therapy starting materials creates vendor selection advantage for ATMP CDMOs. |
| Enzyme Supply Backward Integration | Captive terminal transferase production in Denmark or California reduces input vulnerability as gene assembly scales. |
| Geographic Footprint Extension | Benchtop instrument deployment in India's Maharashtra and Karnataka clusters captures CRO biologics expansion. |
| Continuous Bioprocessing Integration | Automated liquid handling convergence enables real-time gene assembly within cell therapy manufacturing workflows. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with synthetic biology executives, gene therapy manufacturing heads, regulatory affairs leads at CDMOs, and diagnostic laboratory procurement managers; and secondary validation against FDA guidance documents, EMA ATMP submissions, Swissmedic position papers, ISO 13485 certification databases, and REACH authorization records. Bottom-up segment sizing triangulated with top-down market reconstruction.
Forecast inputs spanned polymerase product type trajectories, automated platform deployment velocity, gene therapy manufacturing scale-up timing, and regional regulatory pathway divergence across the analysis window. Segmentation modeling incorporated enzyme class, application tier, end-user procurement modality, and deployment architecture. CAGRs derived from fitted growth curves against qualification timeline assumptions and consumable attachment rate projections.
Stress conditions across FDA guidance finalization timing, terminal transferase supplier concentration events, and phosphoramidite chemistry cost compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against EMA ATMP guidance evolution and CDSCO biosimilar pathway updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.